
 Global 5G in Automotives Market | 2026-2036
Global 5G in Automotives Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G in Automotives Market Analysis
Modular service bundling is recalibrating how fleet operators and OEMs purchase 5G automotive connectivity. Qualcomm Technologies Inc. leverages its integrated modem-RF platforms to anchor premium tier supply contracts with German and Japanese automakers. Robert Bosch GmbH competes through embedded telematics control units that sustain long-term software update revenue streams. Vodafone Group Plc differentiates by operating multi-national 5G edge nodes positioned for low-latency vehicle-to-everything applications.
5G in automotives denotes the deployment of fifth-generation cellular networks to enable ultra-reliable low-latency communication between vehicles, infrastructure, and cloud platforms, typically operating at sub-10 millisecond latency for safety-critical functions. The technology serves autonomous driving coordination, real-time traffic optimization, and predictive maintenance across commercial and passenger vehicle fleets. Network slicing for autonomous driving commands the dominant share of infrastructure investment as mobile operators provision dedicated bandwidth with guaranteed quality of service. Edge computing for vehicle-to-everything communication represents the fastest-expanding technology segment, with latency requirements below 5 milliseconds driving co-location of compute at roadside units and base stations. Fleet management applications sit at a relatively mature adoption phase among long-haul logistics operators, though margin pools are shifting toward predictive analytics layered atop connectivity subscriptions.
The FCC governs spectrum allocation for cellular vehicle-to-everything in the United States, with recent rulemakings reserving 5.9 GHz band segments for intelligent transportation systems. The EU AI Act and CE marking requirements under the EU Green Deal impose conformity obligations on automated driving systems that rely on 5G backhaul, effectively conditioning market access on cybersecurity and functional safety certifications. China's MIIT enforces GB standards for connected vehicle data security that constrain cross-border data flows and mandate domestic edge infrastructure deployment. Stakeholders must monitor evolving spectrum harmonization negotiations between regulators, as divergent national frameworks for 5G automotive deployment risk fragmenting supplier certification pathways and raising compliance costs for global platform rollouts.
Market Dynamics
Network slicing mandates from telecom regulators are compressing deployment timelines for dedicated automotive 5G corridors, forcing OEMs to pre-integrate modem-RF platforms before full infrastructure maturity.
Growth Catalysts
- Cellular vehicle-to-everything mandates:The FCC's 5.9 GHz band reservation for intelligent transportation systems compels US automakers to embed V2X-capable hardware across 2026 model year fleets.
- Edge computing latency requirements:Sub-5 millisecond response thresholds for autonomous emergency braking are driving co-location of compute at roadside units and base stations.
- Germany:The country's automotive OEMs co-develop dedicated network slices with Deutsche Telekom, creating reference architectures that accelerate supplier certification across the EU.
Market Restraints
- Semiconductor supply concentration:Advanced modem-RF platforms depend on TSMC's 4nm capacity, creating single-source vulnerability for automotive-grade silicon.
- Cross-border data friction:China's MIIT GB standards constrain vehicle data flows outside domestic edge infrastructure, fragmenting global platform architectures.
- Millimeter-wave propagation limitations:28 GHz and 39 GHz bands suffer rapid attenuation in urban canyon environments, requiring dense small cell deployment.
Strategic Opportunities
- Predictive maintenance analytics:Long-haul logistics operators in the United States are layering AI-driven failure prediction atop connectivity subscriptions, expanding margin pools beyond raw data transmission.
- EU AI Act compliance services:Conformity assessment for automated driving systems creates adjacent revenue streams for cybersecurity certification providers.
- Japan:METI's connected vehicle infrastructure investments position the country for V2X corridor standardization that could export to ASEAN markets.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for 5G modem software stacks extends development cycles by 18-24 months.
- Legacy CAN bus integration:Ethernet-TSN gateways must bridge deterministic legacy networks with stochastic 5G backhaul, complicating vehicle E/E architecture redesign.
- Radio frequency engineering talent scarcity:Automotive OEMs compete with consumer electronics for mmWave antenna design expertise, inflating compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G in Automotives Market |
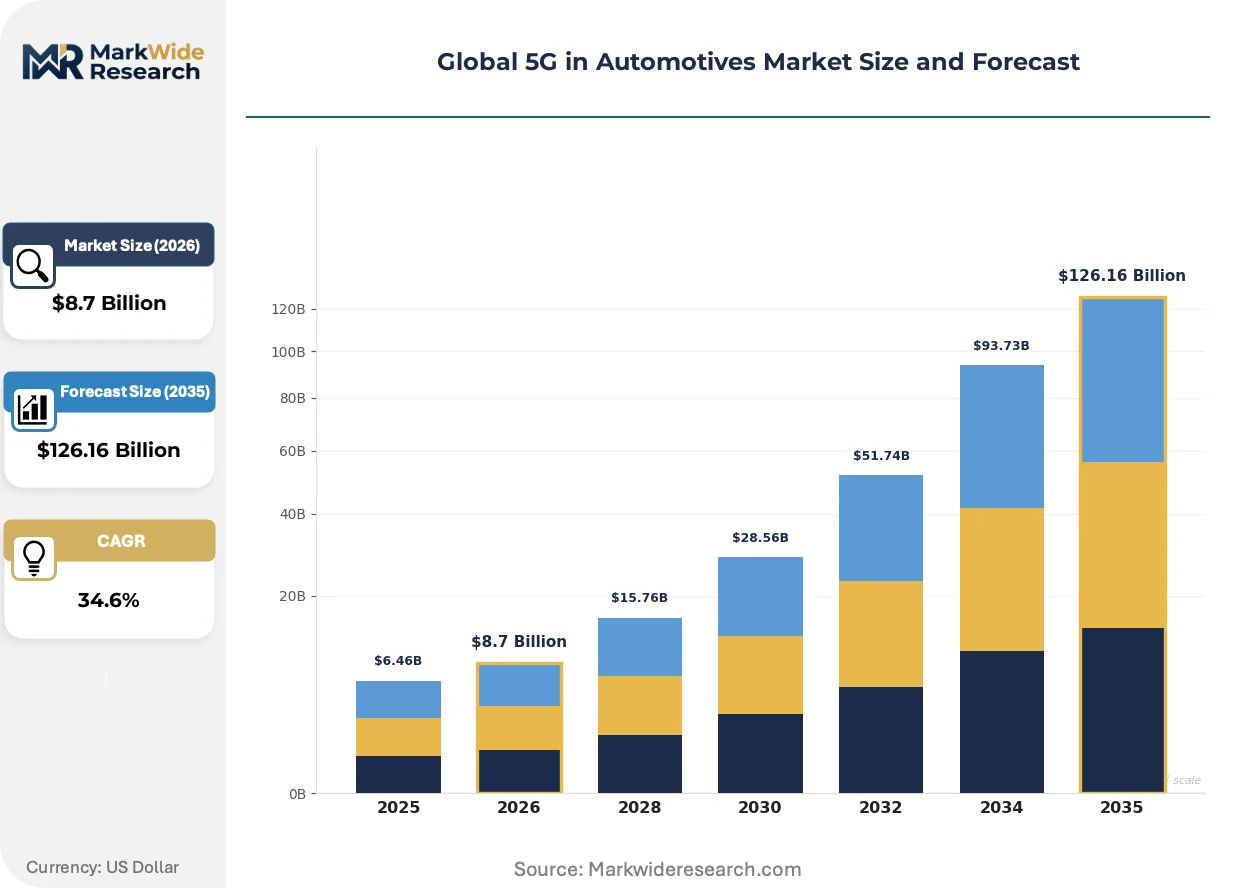
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $126.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Autonomous Driving, Vehicle-to-Everything, Fleet Management, Telematics Technology: Network Slicing, Edge Computing, Cloud Connectivity, Software-Defined Networking Feature: Real-Time Data Processing, Enhanced Safety Features, Over-the-Air Updates, In-Car Entertainment End User: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Providers |
| Companies Covered | Qualcomm Technologies Inc., BMW Group, Audi Group, Robert Bosch GmbH, Vodafone Group Plc, Deutsche Telekom AG, Telefonaktiebolaget LM Ericsson, Verizon Communications Inc., Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G in Automotives Market Emerging Trajectories
Software-defined modems are decoupling hardware refresh cycles from protocol evolution, allowing automakers to upgrade 5G capabilities through over-the-air updates rather than physical replacement.
Multi-mode modem-RF platforms are integrating LTE, 5G NR, and satellite NTN connectivity into single-chip solutions. German and Japanese automakers are qualifying these devices for 15-year vehicle lifecycles. This integration is compressing supplier tier consolidation as tier-2 RF component vendors lose socket access to integrated platform providers.
The EU AI Act's risk-based classification for automated driving systems is mandating formal verification of 5G-dependent decision algorithms. Automotive suppliers must now document training data provenance and model drift monitoring. German TÜV certification bodies are expanding capacity to handle this workload, creating regional bottlenecks.
Fleet operators are unbundling connectivity from telematics platforms, negotiating direct relationships with mobile network operators. Long-haul logistics buyers in the United States now procure network slices separately from vehicle OEMs. This disintermediation is eroding embedded connectivity margins and forcing automakers to pivot toward data analytics monetization.
Global 5G in Automotives Market Segmentation
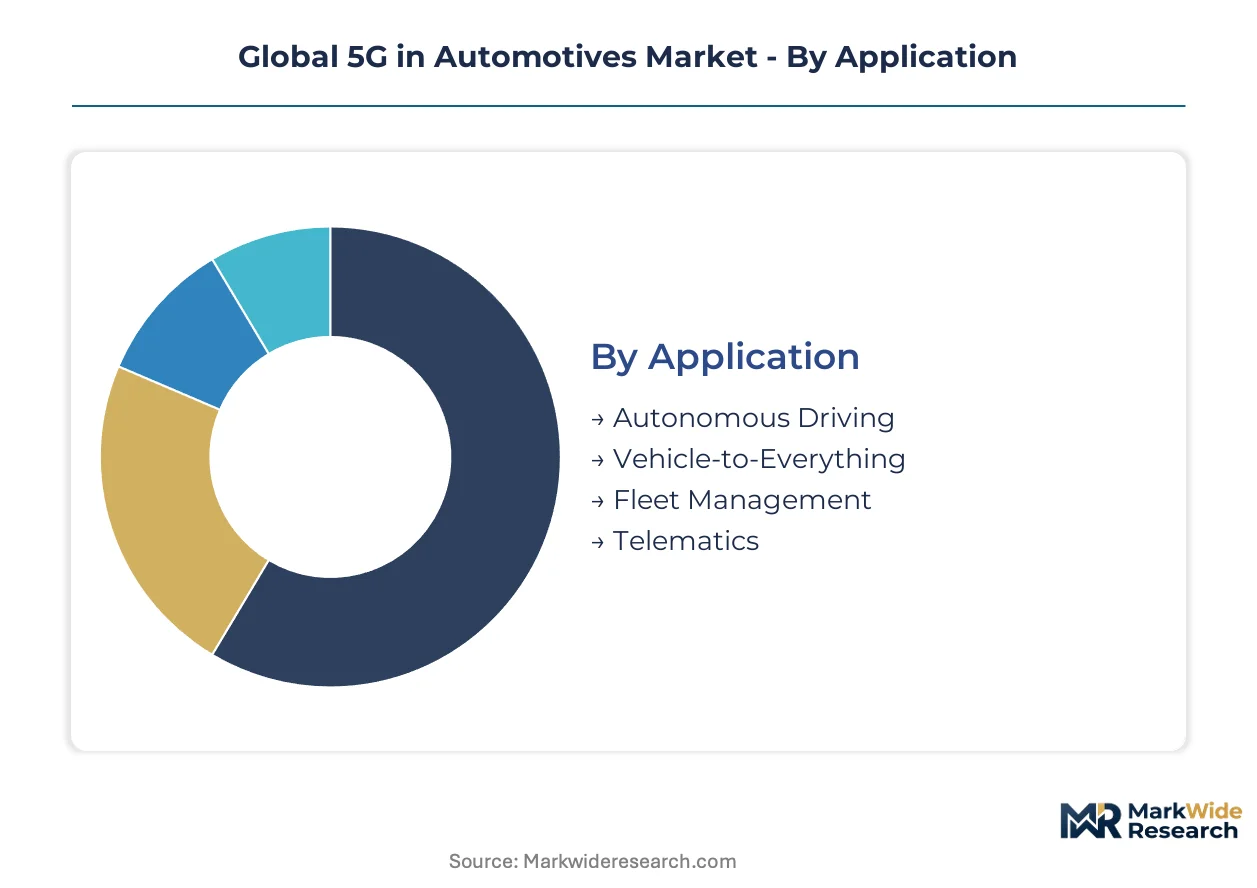
5G automotive deployments fragment across four distinct axes: application use case, underlying network architecture, vehicle-facing functionality, and procurement channel. Each axis carries different margin profiles, certification requirements, and infrastructure dependencies that reshape supplier positioning.
Application:
Network latency specifications and safety integrity levels vary sharply by application type, determining modem-RF platform selection and edge node placement.
- Autonomous Driving:Sub-10 millisecond latency requirements for sensor fusion and path planning demand dedicated network slices with guaranteed quality of service. German OEMs co-develop these slices with Deutsche Telekom for highway corridor deployment.
- Vehicle-to-Everything:Direct PC5 interface communication between vehicles and roadside units operates independently of cellular base stations. FCC 5.9 GHz band reservations in the United States mandate V2X-capable hardware across new vehicle fleets.
- Fleet Management:Long-haul logistics operators in North America layer predictive analytics atop connectivity subscriptions, shifting margin pools beyond raw data transmission.
- Telematics:Embedded control units sustain software update revenue streams through 15-year vehicle lifecycle support commitments.
Autonomous Driving leads on scale; Vehicle-to-Everything leads on momentum.
Technology:
Cost tiers separate infrastructure-heavy deployments from software-centric implementations, with capital intensity determining operator adoption sequencing.
- Network Slicing:Mobile operators provision dedicated bandwidth with guaranteed quality of service for safety-critical functions. China's MIIT enforces domestic edge infrastructure deployment that constrains cross-border data flows.
- Edge Computing:Sub-5 millisecond response thresholds for autonomous emergency braking drive compute co-location at roadside units and base stations. This segment is expanding most quickly across German and Japanese deployment corridors.
- Cloud Connectivity:Centralized data lakes enable fleet-wide predictive maintenance model training with latency tolerance above 50 milliseconds.
- Software-Defined Networking:Protocol decoupling from hardware refresh cycles allows capability upgrades through over-the-air updates rather than physical modem replacement.
Network Slicing dominates current infrastructure investment; Edge Computing shows the steepest expansion trajectory.
Feature:
Customer willingness to pay stratifies across safety-critical functions versus convenience services, with regulatory mandates overriding pure market dynamics for certain capabilities.
- Real-Time Data Processing:Sensor fusion pipelines require deterministic compute allocation at vehicle edge nodes. EU AI Act conformity obligations impose formal verification requirements on training data provenance.
- Enhanced Safety Features:ISO 26262 ASIL-D qualification for 5G modem software stacks extends development cycles by 18-24 months, concentrating supply among qualified platform providers.
- Over-the-Air Updates:Software-defined modems decouple capability evolution from hardware replacement, compressing supplier tier consolidation as integrated platforms displace discrete RF components.
- In-Car Entertainment:High-bandwidth infotainment streams tolerate higher latency thresholds, utilizing best-effort network slices rather than guaranteed quality of service.
Real-Time Data Processing commands premium pricing; Over-the-Air Updates is gaining share fastest among fleet procurement criteria.
End User:
Procurement authority is shifting from integrated OEM bundles toward direct fleet operator negotiations with mobile network operators, fragmenting traditional supply relationships.
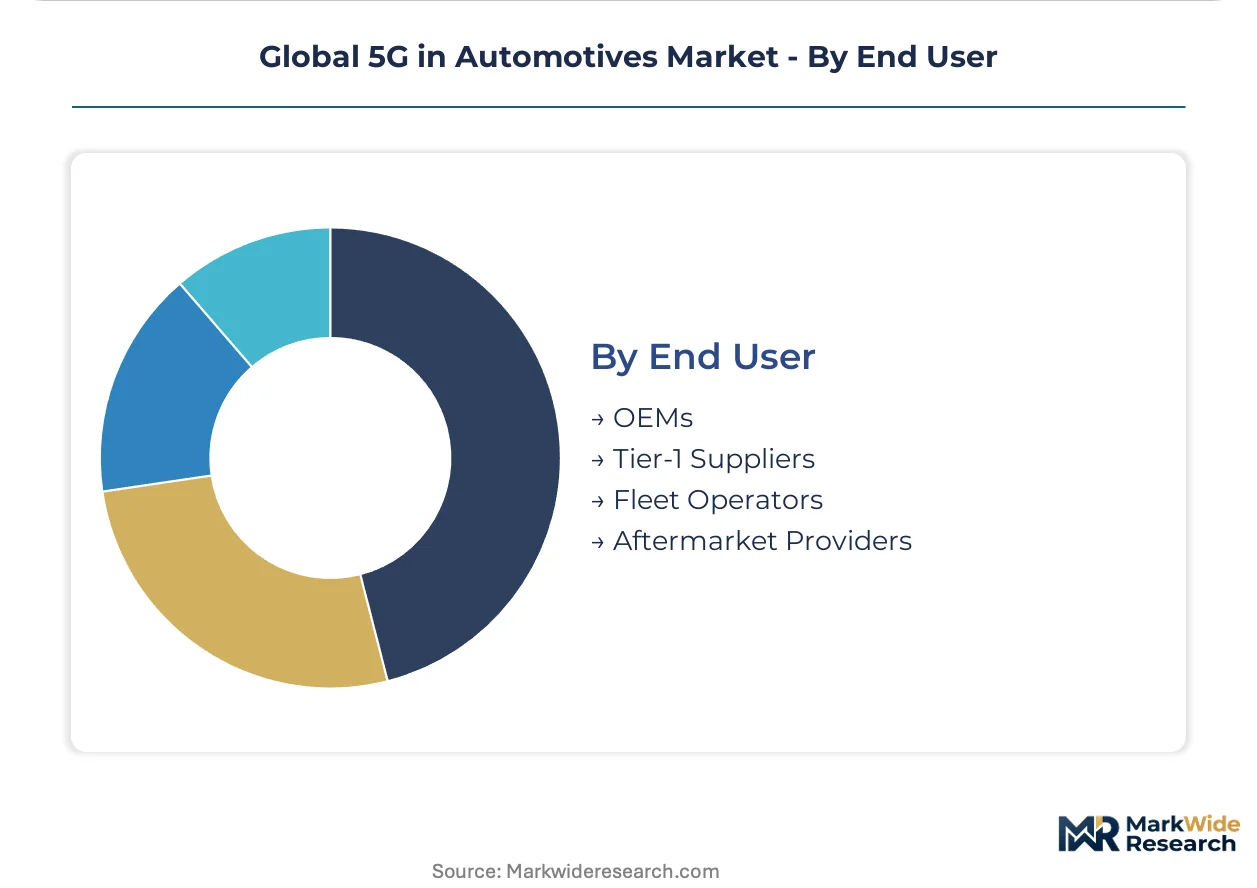
- OEMs:German and Japanese automakers pre-integrate modem-RF platforms before full infrastructure maturity, absorbing regulatory compliance risk across 15-year vehicle lifecycles.
- Tier-1 Suppliers:Robert Bosch GmbH competes through embedded telematics control units that bridge deterministic legacy CAN bus networks with stochastic 5G backhaul.
- Fleet Operators:Long-haul logistics buyers in the United States now procure network slices separately from vehicle OEMs, eroding embedded connectivity margins.
- Aftermarket Providers:Retrofit telematics installations serve commercial vehicle segments with extended legacy fleet depreciation timelines.
OEMs retain volume concentration; Fleet Operators show the most rapid procurement pattern disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive 5G connectivity originated in Germany's precision manufacturing corridor, where BMW and Deutsche Telekom pioneered cellular vehicle-to-everything trials during the 2016 Berlin motor show. This industrial heritage established technical protocols that now propagate through supplier ecosystems across three continents.
United States
Fleet operators in Michigan and California accelerate connected truck deployments as the FCC's 5.9 GHz band reservation mandates V2X-capable hardware. The Detroit-Warren-Dearborn automotive cluster hosts modem-RF platform integration facilities serving domestic OEMs.
Germany
Deutsche Telekom co-develops dedicated network slices with Bavarian automakers for autonomous highway corridors. The EU AI Act imposes conformity obligations on automated driving systems, forcing TÜV certification bodies to expand formal verification capacity.
China
MIIT enforces GB standards for connected vehicle data security that constrain cross-border flows and mandate domestic edge infrastructure. The Yangtze River Delta hosts concentrated deployment of roadside units for low-latency vehicle-to-everything communication.
Japan
METI's connected vehicle infrastructure investments position Nagoya-based suppliers for V2X corridor standardization. Toyota Motor Corporation anchors development of multi-mode modem platforms qualifying for 15-year vehicle lifecycles.
South Korea
The Seoul Capital Area concentrates 5G base station density for autonomous driving testbeds. Domestic semiconductor fabricators supply automotive-grade silicon for integrated modem-RF platforms serving regional OEMs.
Global 5G in Automotives Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and software update revenue durability. The vendor base stratifies into three tiers: integrated modem-RF platform providers, embedded telematics specialists, and mobile network operators provisioning edge infrastructure. Two competitive moves dominate: strategic partnerships between automakers and telecom providers for network slice development, and vertical integration of RF component design into single-chip solutions.
Within the integrated platform tier, Qualcomm Technologies Inc. and Telefonaktiebolaget LM Ericsson exemplify semiconductor-telecom convergence. Robert Bosch GmbH occupies a position among embedded systems specialists bridging legacy vehicle architectures. Vodafone Group Plc and Verizon Communications Inc. represent mobile operators capturing fleet procurement relationships directly.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| BMW Group |
| Audi Group |
| Robert Bosch GmbH |
| Vodafone Group Plc |
| Deutsche Telekom AG |
| Telefonaktiebolaget LM Ericsson |
| Verizon Communications Inc. |
| Toyota Motor Corporation |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's carbon border adjustment mechanism gates qualified supply for automotive-grade 5G modem-RF platforms, restricting premium-tier pricing access to suppliers with verified low-carbon foundry relationships. German OEMs now condition procurement contracts on semiconductor carbon intensity disclosures, compressing margin pools for unqualified tier-2 RF component vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies 5G automotive connectivity procurement. Premium tiers command certification-grade premiums for ISO 26262 ASIL-D qualified modem software stacks, while standard tiers serve fleet management applications with relaxed latency specifications. Price differentiation hinges on functional safety certification level and guaranteed quality-of-service bandwidth allocation. Cost compression in economy tiers is intensifying because Chinese MIIT domestic edge infrastructure mandates fragment global platform architectures. Long-haul logistics operators in the United States show highest price sensitivity, negotiating direct network slice procurement separate from vehicle OEM bundles.
Supply Chain Analysis
ISO 26262 ASIL-D qualification timelines of 18-24 months gate supplier access to safety-critical automotive 5G sockets. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with TSMC's 4nm capacity serving as the chokepoint for advanced modem-RF platforms. Raw material dependencies span gallium nitride substrates for mmWave power amplifiers, high-purity silicon wafers, and automotive-grade epoxy molding compounds. Single-source vulnerability in TSMC's automotive-grade capacity creates supply chain risk. Distribution runs through tier-1 embedded systems specialists bridging deterministic legacy CAN bus networks with stochastic 5G backhaul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G automotive connectivity market functions as a geographic-arbitrage play where regulatory compliance cost differentials between the EU AI Act's formal verification requirements and China's MIIT data localization mandates reshape supplier margin structures.
For Market Incumbents: Anchor modem-RF platform roadmaps to 15-year vehicle lifecycle commitments, absorbing regulatory compliance risk across multiple certification regimes. Deepen backward integration into automotive-grade silicon supply through captive foundry allocations or joint development agreements with TSMC. Defend against fleet operator disintermediation by layering predictive analytics capabilities atop connectivity subscriptions, shifting revenue durability beyond raw data transmission. For New Entrants and Emerging Players: Mobile network operators seeking automotive vertical expansion represent the most accessible channel partnership archetype for unbundled edge computing solutions. Target aftermarket retrofit telematics installations serving commercial vehicle segments with extended legacy fleet depreciation timelines. Penetrate ASEAN markets through technology transfer partnerships with Japanese METI-funded V2X corridor standardization initiatives. Pursue white-label software-defined modem development for tier-2 automotive suppliers losing socket access to integrated platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-2 RF component vendors facing socket displacement from multi-mode modem-RF integration. Long-term viability over the projection horizon favors cybersecurity certification providers positioned for EU AI Act conformity assessment expansion. Monitor TÜV certification body capacity constraints as an inflection indicator for compliance service pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Network Slice Development Partnership | Deutsche Telekom's co-development with Bavarian automakers creates reference architectures accelerating EU supplier certification. |
| Software-Defined Modem Platform Launch | Qualcomm's integrated modem-RF solutions compress tier-2 vendor socket access through over-the-air upgrade capability. |
| Edge Computing Infrastructure Expansion | Vodafone's multi-national 5G edge nodes capture low-latency V2X application demand from autonomous driving corridors. |
| Functional Safety Certification Investment | Robert Bosch GmbH's ASIL-D qualified telematics control units sustain 15-year software update revenue streams. |
| Predictive Analytics Capability Buildout | Fleet operators in the United States layer AI-driven failure prediction atop connectivity subscriptions, expanding margin pools. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement leads, mobile network operator automotive vertical heads, and fleet operations managers at long-haul logistics providers. Secondary validation drew from FCC rulemaking dockets, EU AI Act implementation guidance, MIIT GB standard publications, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing and top-down macroeconomic anchoring provided cross-verification.
Comparable-period anchoring tied projection assumptions to historical deployment trajectories across the analysis window. The analytical framework modeled segmentation across application use case, network architecture technology, vehicle-facing functionality, and procurement channel end user, with additional dimensioning by regional regulatory cluster and OEM tier. CAGRs derived from fitted growth curves applied to infrastructure investment pipelines and fleet penetration assumptions. Forecast inputs incorporated cellular V2X mandate compliance timelines and semiconductor fab capacity allocation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum harmonization negotiations between regulators and millimeter-wave propagation technology maturation. Forecasts reflect documented assumptions on infrastructure deployment sequencing and fleet replacement cycles. A model refresh is warranted upon material change in FCC or EU spectrum allocation rulemakings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Global in Dash Navigation System Market