
 Telematics Market | 2026-2036
Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Telematics Market Outlook
ISO 26262 functional safety certification is bifurcating the competitive landscape between qualified automotive-grade suppliers and consumer-electronics entrants. Geotab Inc. leverages its open-platform architecture to sustain integration partnerships across fleet ecosystems. Verizon Connect anchors its position through deep channel control in North American commercial insurance verticals. Continental AG dominates embedded OEM programs with manufacturing scale that spans powertrain and connectivity modules.
Telematics denotes the integrated hardware-software systems that transmit vehicle location, diagnostics, and operational data via cellular or satellite networks to centralized management platforms, typically incorporating GPS receivers, OBD-II interfaces, and cloud gateways operating at sub-100-millisecond latency for real-time fleet coordination. Insurance telematics and fleet management represent the most structurally differentiated application segments, with the former capturing recurring data-monetization revenue pools and the latter driving volume through SaaS subscription models. GPS tracking technology leads deployment incidence, while satellite communication extends addressable coverage into remote logistics corridors where cellular density remains thin.
FCC spectrum allocations shape device certification timelines and transmission protocols for cellular-enabled units entering the United States, while the EU Green Deal and GDPR impose parallel carbon-reporting and data-governance obligations on European deployments. The FMCSA ELD mandate in the United States created baseline hardware demand that now ripples into adjacent driver-behavior analytics and predictive maintenance modules. Stakeholders must weigh embedded versus aftermarket deployment economics as OEMs tighten data-access policies and fleet operators seek platform portability across vehicle lifecycles.
Market Dynamics
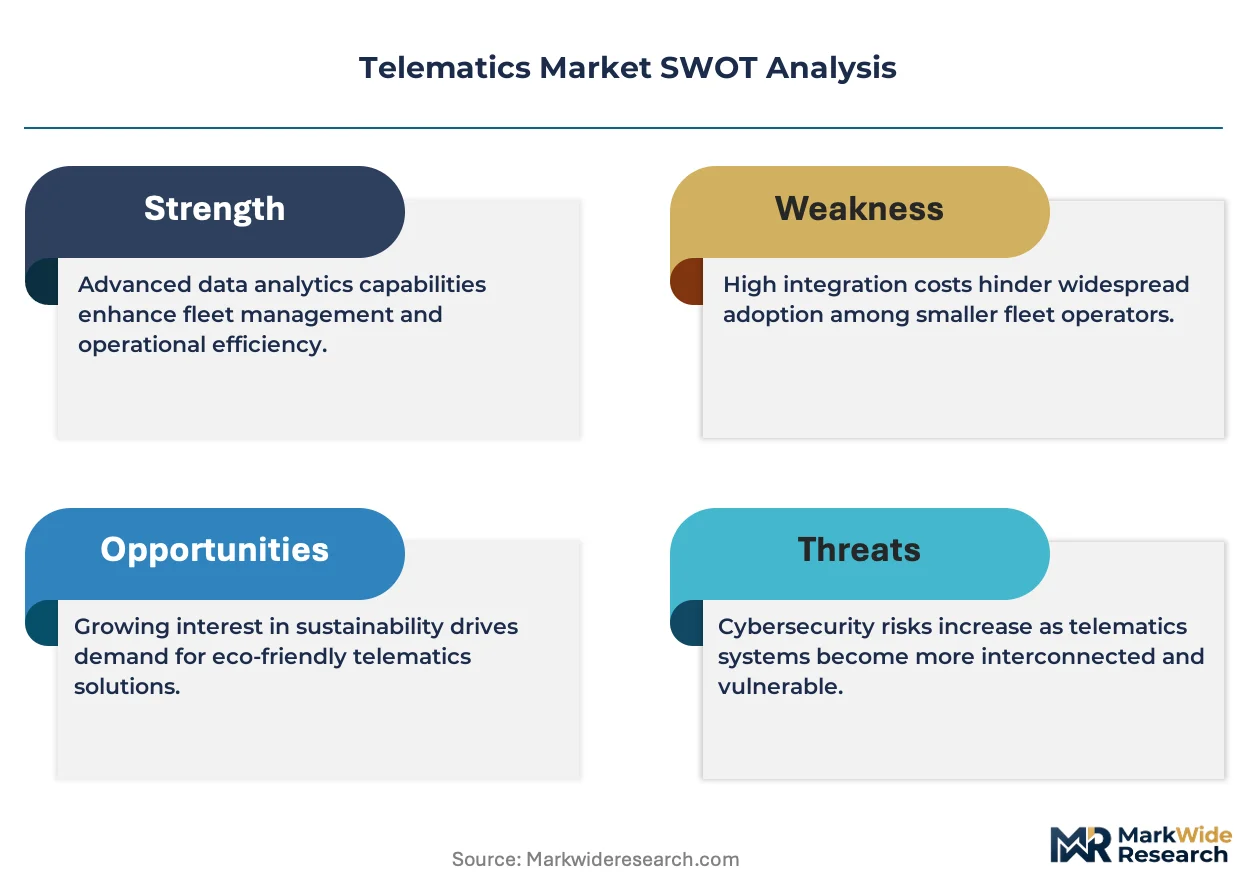
Fleet operators face a structural squeeze between OEM data-access restrictions and the portability demands of multi-brand vehicle portfolios, forcing platform architecture choices that lock in competitive position for entire replacement cycles.
Growth Catalysts
- FMCSA ELD Mandate:Federal Motor Carrier Safety Administration enforcement created baseline hardware penetration that now expands into adjacent driver-behavior analytics and predictive maintenance modules across United States long-haul fleets.
- Cellular Module Cost Curves:4G LTE and 5G chipset economies are compressing device bill-of-materials sufficiently to enable telematics bundling into mid-duty vehicle segments previously excluded on unit economics.
- Insurance Premium Incentives:Commercial auto underwriters in the United States are deploying usage-based pricing algorithms that reward fleet telematics adoption with measurable premium reductions.
Market Restraints
- Semiconductor Supply Concentration:Cellular modem and GPS receiver fabrication concentrates in Taiwan and South Korea, exposing device manufacturers to geographic supply disruption with limited near-term alternative sourcing.
- OEM Data Sovereignty:Vehicle manufacturers are tightening embedded system access policies, restricting third-party telematics platform interoperability and fragmenting fleet data aggregation across proprietary OEM clouds.
- Satellite Connectivity Cost Structure:Remote logistics corridor coverage requires Iridium or Starlink terminal integration at 3-5x cellular-equivalent hardware cost, constraining addressable market expansion in thin-density routes.
Strategic Opportunities
- Electric Vehicle Transition:Battery electric commercial vehicles require telematics architectures that integrate state-of-charge monitoring, route optimization, and charging infrastructure coordination, opening white space for platform specialization.
- GDPR-Compliant Data Monetization:European Union General Data Protection Regulation frameworks are creating certified data-pool structures that enable fleet operators to monetize aggregated driving behavior for insurance and infrastructure planning verticals.
- AI-Enabled Predictive Maintenance:Machine learning inference at the edge is converging with OBD-II diagnostic streams to enable component-failure prediction with sufficient lead time for scheduled maintenance windows.
Industry Challenges
- ISO 26262 Certification Timelines:Functional safety qualification for automotive-grade telematics hardware extends development cycles by 18-24 months, compressing product refresh cadence against software-defined vehicle evolution.
- Legacy Fleet Integration:Aftermarket telematics deployment across pre-2017 vehicle populations requires adapter harness engineering for non-standardized OBD-II implementations, fragmenting installation protocols and elevating field service costs.
- Cybersecurity Skill Scarcity:Over-the-air update architectures and edge computing modules demand embedded security engineering capabilities that outpace current workforce pipeline output in North American and European labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telematics Market |
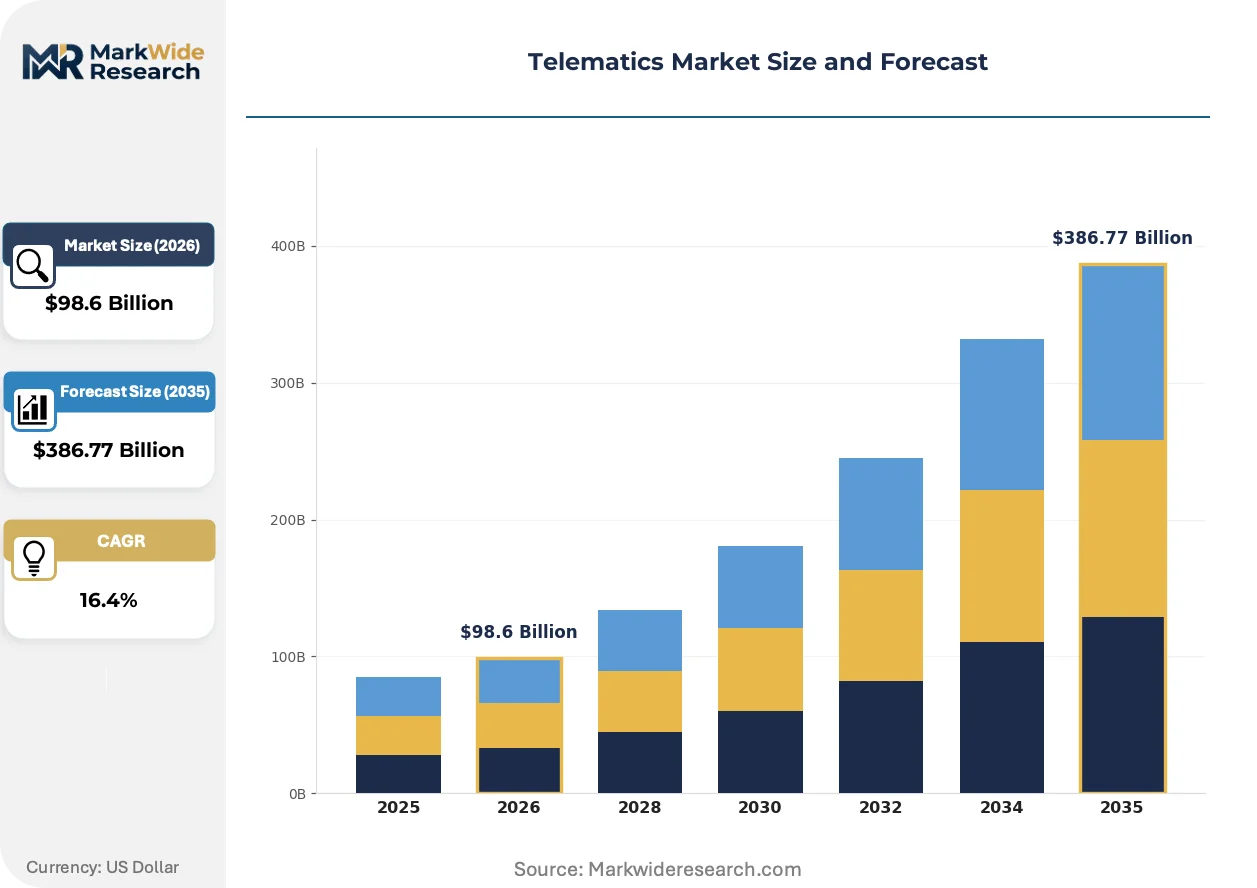
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $386.77 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Tracking, Cellular Communication, Satellite Communication, Bluetooth Application: Fleet Management, Vehicle Diagnostics, Driver Behavior Monitoring, Insurance Telematics End User: Automotive OEMs, Fleet Operators, Insurance Companies, Logistics Providers Deployment: On-Premise, Cloud-Based, Hybrid, Embedded |
| Companies Covered | Geotab Inc., Mix Telematics, Verizon Connect, Samsara, AT&T Inc., Trimble Inc., Continental AG, LG Electronics, HARMAN International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telematics Market Strategic Shifts
Telematics platform architecture is pivoting from monolithic hardware-software bundles toward modular, API-first ecosystems that enable fleet operators to swap analytics providers without device replacement.
Edge computing silicon is decomposing the traditional cloud-dependent telematics stack by enabling real-time inference for driver coaching and collision avoidance directly on vehicle-mounted units. Heavy-duty fleet operators in the United States are adopting these modules fastest, driven by insurance carrier discounts for immediate event response. This localization is compressing latency-dependent application economics and reducing cellular data transmission costs for high-frequency sensor streams.
European Union CSRD carbon-reporting obligations are mandating granular fuel consumption and emissions telemetry from commercial vehicle fleets above defined size thresholds. The regulation forces telematics platforms to integrate fuel-flow sensors and idle-time algorithms as standard features rather than premium add-ons. Logistics operators with cross-border European routes are prioritizing platforms with pre-certified CSRD reporting modules to avoid audit preparation overhead.
Fleet procurement departments are consolidating vendor relationships around full-stack platform providers capable of spanning light-duty through heavy-duty asset classes under unified data contracts. This concentration is displacing point-solution GPS tracking vendors who lack predictive maintenance or compliance module depth. The pattern is most pronounced in United States regional LTL carriers seeking to standardize technology spend across acquired fleet populations.
Telematics Market Segmentation
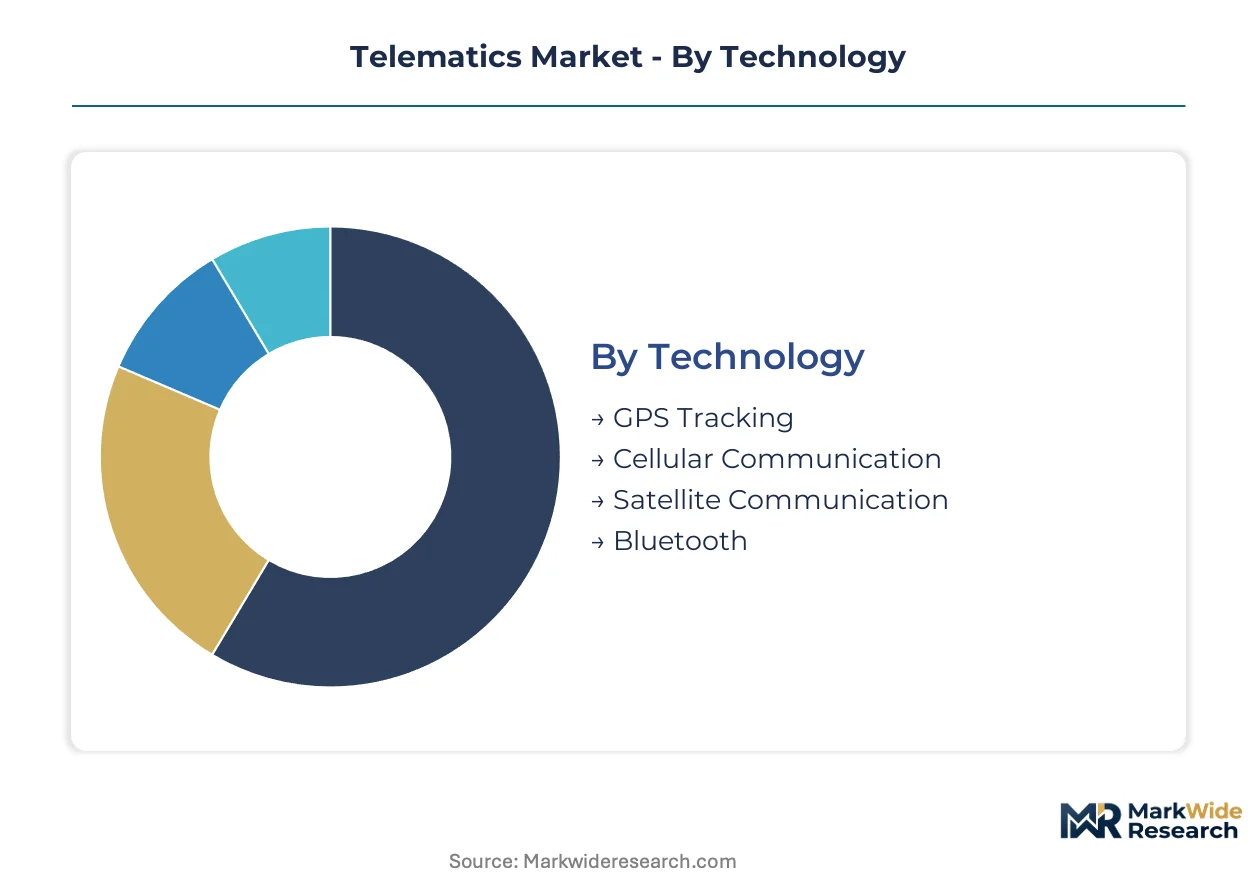
Telematics market segmentation reveals distinct procurement patterns across hardware-software bundles and service delivery models. Channel economics vary sharply between embedded OEM programs and aftermarket fleet installations, with each pathway demanding specialized certification and integration protocols.
Technology:
Channel mix varies significantly by transmission protocol, with cellular-enabled units dominating volume through carrier-integrated distribution while satellite terminals flow through specialized logistics hardware vendors.
- GPS Tracking:Satellite-based positioning modules deliver sub-5-meter accuracy for real-time vehicle location through constellations including GPS, GLONASS, and Galileo. Fleet operators in the United States prioritize multi-constellation receivers for coverage redundancy across interstate corridors where urban canyon effects degrade single-system performance.
- Cellular Communication:4G LTE and 5G modem chipsets enable sub-100-millisecond data transmission to cloud platforms, with FCC certification requirements shaping device approval timelines for United States market entry. Logistics providers with high-frequency reporting needs select cellular-first architectures for cost-effective data streaming.
- Satellite Communication:Iridium and emerging LEO networks extend coverage into remote mining and agricultural zones beyond cellular reach.
- Bluetooth:Short-range protocols enable driver smartphone pairing for last-mile delivery coordination and cabin-based sensor integration.
GPS Tracking dominates installed base. Cellular Communication is where expansion concentrates.
Application:
Application segmentation aligns with revenue model differentiation, with fleet management driving SaaS subscription economics and insurance telematics capturing data-monetization premiums.
- Fleet Management:Unified platforms integrate route optimization, fuel monitoring, and compliance reporting through centralized dashboards. Regional LTL carriers in the United States consolidate procurement around full-stack providers capable of spanning acquired fleet populations under single data contracts.
- Insurance Telematics:Usage-based pricing algorithms translate driving behavior into risk-scored premium adjustments, with commercial auto underwriters in the United States deploying telematics adoption as a measurable discount mechanism.
- Vehicle Diagnostics:OBD-II stream parsing enables predictive maintenance scheduling based on component degradation patterns.
- Driver Behavior Monitoring:Accelerometer and gyroscope fusion detects harsh braking, acceleration events, and fatigue indicators for coaching interventions.
Fleet Management commands the largest revenue pool. Insurance Telematics is climbing the fastest as underwriters harden pricing algorithms.
End User:
End user economics bifurcate between OEM-embedded programs with multi-year production commitments and aftermarket deployments requiring platform portability across mixed-brand fleets.
- Fleet Operators:Multi-brand vehicle portfolios demand platform architectures that maintain data continuity across replacement cycles, forcing interoperability investments that lock in vendor relationships. Long-haul freight operators face structural tension between OEM data-access restrictions and operational flexibility requirements.
- Automotive OEMs:Embedded telematics integration at factory floor enables proprietary cloud ecosystems with restricted third-party access, tightening data sovereignty around vehicle lifecycle information. Powertrain and connectivity module suppliers compete for program awards based on manufacturing scale and ISO 26262 certification status.
- Insurance Companies:Risk-scoring algorithm development depends on normalized driving behavior datasets across pooled fleet contributions.
- Logistics Providers:Cross-border route operators prioritize platforms with pre-certified emissions reporting modules for European CSRD compliance.
Fleet Operators represent the deepest demand concentration. Automotive OEMs are gaining share fastest through embedded program expansion.
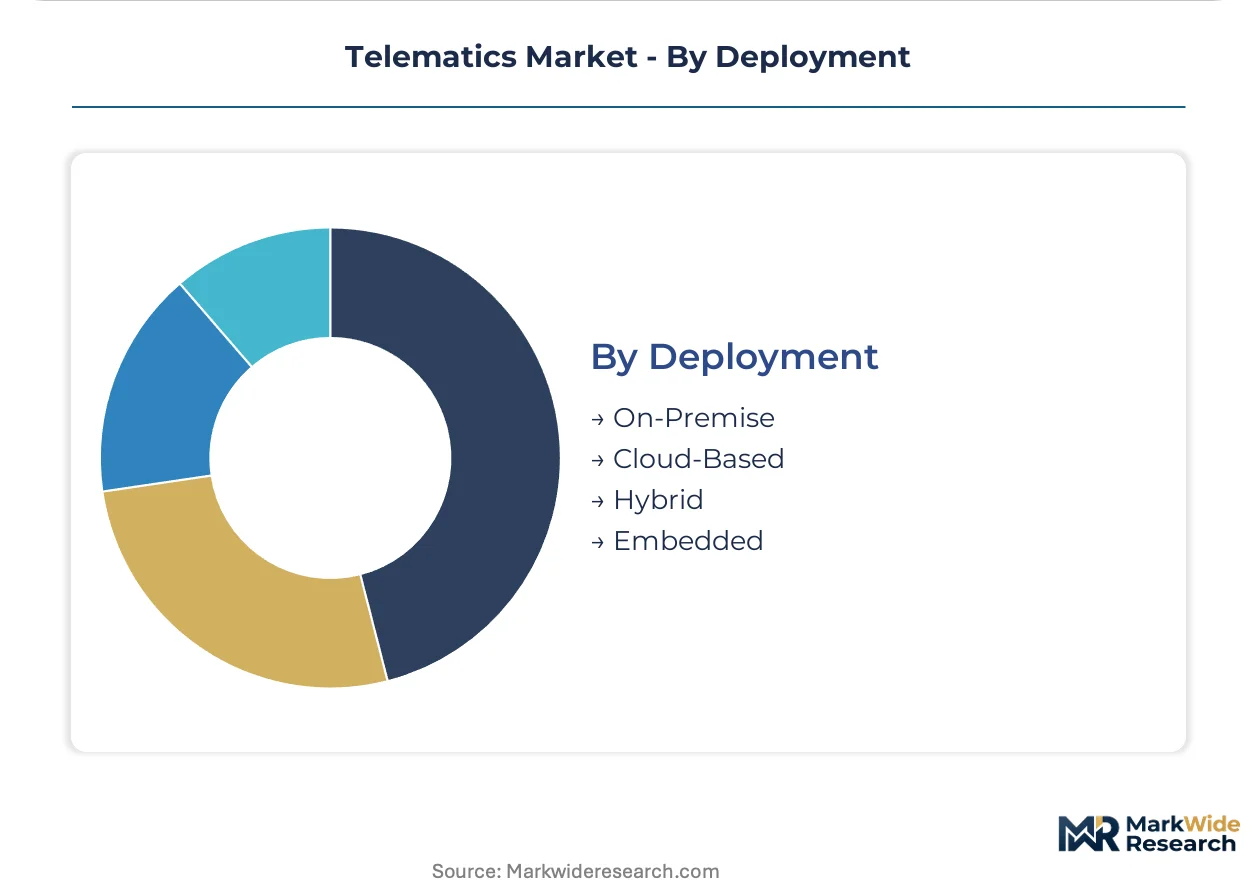
Deployment:
Deployment architecture selection hinges on latency requirements, data sovereignty preferences, and integration complexity with legacy fleet management systems.
- Cloud-Based:Centralized data processing enables scalable analytics infrastructure without on-site server maintenance, with subscription economics aligning operational expenditure to fleet size fluctuations. Mid-duty fleet segments previously excluded by hardware unit economics now access telematics through cellular module cost compression.
- Embedded:Factory-integrated systems eliminate aftermarket installation labor and warranty fragmentation, though OEM data-access policies constrain third-party platform interoperability. European Union GDPR frameworks impose parallel governance obligations on data residency and cross-border transfer protocols.
- On-Premise:Air-gapped installations serve defense and critical infrastructure operators with classified operational security requirements.
- Hybrid:Edge-cloud partitioning optimizes latency-sensitive applications while maintaining centralized historical analytics.
Cloud-Based architectures lead new installations. Embedded deployment is expanding most quickly as OEMs tighten data ecosystem control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FMCSA ELD mandates and insurance premium incentives in the United States are accelerating connected vehicle platform deployment across commercial freight corridors. Cellular module cost compression and satellite coverage expansion are extending addressable markets into mid-duty segments and remote logistics routes.
United States
Long-haul freight density and ELD compliance requirements drive concentrated telematics adoption among fleet operators. FCC spectrum allocations shape device certification timelines for cellular-enabled units entering commercial markets. Chicago and Dallas-Fort Worth anchor major fleet management platform deployments serving regional LTL carriers.
Germany
Automotive OEM embedded programs and powertrain connectivity integration sustain manufacturing-scale demand for telematics hardware. EU Green Deal carbon-reporting obligations and GDPR data-governance frameworks impose parallel compliance requirements on commercial vehicle fleets. Stuttgart and Munich host Continental AG and other automotive-grade suppliers dominating embedded OEM programs.
China
Domestic logistics platform expansion and commercial vehicle electrification create white space for battery state-of-charge monitoring architectures. MIIT connectivity standards and GB certification protocols govern device approval for cellular-enabled telematics systems. Shanghai and Shenzhen cluster telematics module manufacturing serving both domestic fleet operators and export markets.
United Kingdom
Insurance telematics adoption accelerates as commercial auto underwriters deploy usage-based pricing algorithms with measurable premium discounts. CSRD-aligned carbon-reporting requirements from cross-border European operations extend compliance obligations to UK-based logistics operators. London and Birmingham concentrate fleet management platform procurement for last-mile delivery networks.
Japan
Precision logistics and just-in-time manufacturing supply chains demand sub-100-millisecond latency for real-time fleet coordination. METI industrial standards and JIS certification protocols shape telematics hardware qualification for automotive-grade deployment. Tokyo and Nagoya anchor embedded telematics integration programs serving domestic OEM production networks.
Telematics Market Competitive Environment
Player mix skews toward integrated platform providers with open-architecture capabilities and embedded OEM specialists with manufacturing scale. Market structure concentrates around full-stack fleet management vendors capable of spanning light-duty through heavy-duty asset classes under unified data contracts. Two strategic archetypes dominate: cellular-first SaaS platform operators and automotive-grade hardware suppliers with ISO 26262 certification status. Competitive moves center on API-first ecosystem expansion and channel control deepening in commercial insurance verticals.
Within the open-platform tier, Geotab Inc. and Samsara exemplify architectures enabling fleet operators to swap analytics providers without device replacement. Continental AG anchors the embedded OEM specialist archetype through manufacturing scale spanning powertrain and connectivity modules. Verizon Connect occupies a position emphasizing channel control in North American commercial insurance verticals.
| Leading Market Players |
|---|
| Geotab Inc. |
| Mix Telematics |
| Verizon Connect |
| Samsara |
| AT&T Inc. |
| Trimble Inc. |
| Continental AG |
| LG Electronics |
| HARMAN International |
| Others |
Value Chain & Pricing Dynamics
Long-term SaaS subscription contracts lock in both supply access and price visibility for fleet operators navigating multi-year vehicle replacement cycles, insulating platform providers from spot-market volatility while compressing upfront hardware margins through bundled cellular connectivity commitments.
Pricing Analysis
Certification level creates the primary spread between automotive-grade and consumer-electronics telematics tiers, with ISO 26262-qualified hardware commanding premium positioning against uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects bundling depth from basic GPS tracking through full predictive maintenance suites. Cost compression in mid-duty cellular modules is intensifying because 5G chipset economies enable feature-rich configurations at legacy 4G price points. Regional LTL carriers exhibit highest price sensitivity due to thin operating margins, while long-haul freight operators prioritize reliability over unit cost.
Supply Chain Analysis
Taiwan Strait fabrication concentration exposes cellular modem and GPS receiver supply to geopolitical disruption with limited near-term alternative sourcing. Taiwan, South Korea, and China anchor semiconductor wafer production for telematics chipsets, while Mexico and Germany feed automotive-grade assembly operations. Raw material dependencies center on rare-earth magnets for GPS antennas, lithium-ion cells for backup power, and copper for vehicle harness integration. Single-source vulnerability in 5G baseband silicon creates procurement risk for North American device manufacturers. Distribution runs through carrier-integrated channels for cellular-enabled units and specialized logistics hardware vendors for satellite terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telematics market is accelerating through a regulatory inflection as FMCSA ELD mandates and EU CSRD carbon-reporting obligations force baseline hardware deployment that ripples into adjacent analytics modules.
For Market Incumbents: Compound platform stickiness through API-first ecosystem expansion that locks fleet operators into data-continuity relationships across vehicle replacement cycles. Deepen channel control in commercial insurance verticals where usage-based pricing algorithms reward telematics adoption with measurable premium reductions. Invest in ISO 26262 certification maintenance to defend automotive-grade positioning against consumer-electronics entrants. For New Entrants and Emerging Players: Anchor in electric vehicle fleet white space where battery state-of-charge monitoring and charging infrastructure coordination architectures remain underdeveloped. Target mid-duty commercial segments previously excluded by hardware unit economics now accessible through cellular module cost compression. Pursue GDPR-compliant data monetization partnerships with European logistics operators seeking certified data-pool structures for insurance and infrastructure planning verticals. For Investors and Strategic Acquirers: Open-platform SaaS providers with embedded insurance carrier relationships represent the highest-conviction acquisition archetype for portfolio exposure to recurring revenue pools. Long-term viability hinges on sustained R&D allocation toward edge computing inference capabilities that reduce cloud dependency and cellular data transmission costs. Watch for inflection in OEM data-access policy tightening as the signal for aftermarket platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable fleet operators to swap analytics providers without device replacement. |
| Strategic Partnership | Insurance carrier collaborations unlock usage-based pricing algorithms with measurable premium discount mechanisms. |
| Acquisition of Specialist Firm | Edge computing module specialists compress latency-dependent application economics for real-time driver coaching. |
| Geographic Expansion | European CSRD pre-certification opens carbon-reporting compliance revenue from cross-border logistics operators. |
| Product Launch | Battery electric vehicle telematics suites capture state-of-charge monitoring and charging coordination white space. |
Study Parameters
A standing panel of fleet operations directors, commercial insurance underwriters, OEM platform engineers, and aftermarket distribution managers provided ongoing calibration against primary fieldwork conducted across North American and European logistics corridors. Secondary validation drew from FMCSA regulatory filings, FCC equipment authorization databases, EU Green Deal implementation guidance, vehicle production registries, and carrier-integrated channel shipment records. Bottom-up unit economics modeling triangulated against top-down market sizing from connected vehicle platform deployment tracking.
Consistency checks validated volume and value outputs against external benchmarks including cellular module shipment data, insurance telematics policy attachment rates, and fleet management SaaS subscription disclosures. The analytical framework segmented across technology transmission protocols, application revenue models, end-user procurement archetypes, and deployment architecture choices throughout the forecast period. CAGRs were derived from logistic diffusion curves fitted to regulatory mandate compliance timelines and cellular cost compression trajectories. Industry-specific inputs included ELD mandate enforcement velocity and CSRD carbon-reporting threshold implementation schedules.
Decision-makers should treat outputs as directional under sustained 5G infrastructure buildout and stable semiconductor supply assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as OEM data-access policy evolution and satellite connectivity cost trajectories reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
C-V2X OBU Market