
 GCC Commercial Telematics Market | 2026-2036
GCC Commercial Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Commercial Telematics Market Intelligence
The divergence between premium fleet management platforms and basic vehicle tracking is repositioning competitive dynamics across the GCC. Trimble Inc. leverages its precision agriculture heritage to anchor high-value construction and mining telematics contracts in Saudi Arabia. Verizon Connect sustains channel dominance through integrated video telematics and compliance tools tailored to regional fleet operators. Geotab Inc. differentiates via open-platform architecture that allows Gulf-based logistics firms to customize analytics without proprietary hardware lock-in.
Commercial telematics encompasses GPS-enabled hardware, cellular communication modules, and cloud-based software that collects, transmits, and analyzes vehicle operational data to optimize fleet performance, ensure driver safety, and enforce regulatory compliance. IoT-enabled sensor arrays now supplement traditional GPS positioning with real-time engine diagnostics, cargo condition monitoring, and predictive maintenance algorithms. Fleet Management occupies the largest value pool as integrated dispatch and route optimization platforms command recurring software subscription revenue across GCC logistics networks. Driver Behavior analytics represent the fastest-expanding segment as insurers and transport regulators in the Gulf tie premium calculations and operator licensing to telematics-verified safety scores.
Saudi Arabia's Public Transport Authority and the UAE's Federal Transport Authority are mandating electronic logging devices and hours-of-service tracking for commercial vehicles, directly accelerating hardware replacement cycles. TRAI-equivalent spectrum regulators across GCC states are allocating dedicated IoT bandwidth that reduces cellular connectivity costs for fleet operators. Stakeholders must monitor how forthcoming unified GCC vehicle standards harmonize data formats and compliance thresholds across national borders.
Market Dynamics
The GCC Commercial Telematics Market is being restructured by mandatory electronic logging and emissions monitoring requirements from Saudi Arabia's Public Transport Authority and the UAE's Federal Transport Authority, which are forcing fleet operators to replace legacy GPS-only hardware with integrated cellular-IoT platforms across long-haul logistics corridors.
Growth Catalysts
- Electronic Logging Mandates:Saudi Arabia's Public Transport Authority and the UAE's Federal Transport Authority now require hours-of-service tracking for commercial vehicles, triggering hardware replacement cycles across fleet operators.
- IoT Spectrum Allocation:TRAI-equivalent regulators across GCC states have dedicated bandwidth for fleet connectivity, reducing cellular data costs and enabling real-time sensor arrays for cargo monitoring.
- Construction and Mining Fleets:Heavy equipment operators in Saudi Arabia's Neom and Red Sea Project zones are deploying precision telematics for asset tracking and predictive maintenance in remote worksites.
Market Restraints
- Hardware Cost Structure:Cellular communication modules and multi-sensor IoT arrays carry 40-60% higher upfront costs than legacy GPS-only units, compressing margins for small fleet operators with under fifty vehicles.
- Supply Concentration Risk:Cloud infrastructure for GCC telematics platforms relies heavily on hyperscale data centers concentrated in Dubai and Riyadh, creating single-point-of-failure exposure during regional connectivity disruptions.
- Technical Limitation:Real-time video telematics generates data volumes that exceed available cellular bandwidth across remote desert corridors linking Jeddah to Riyadh, forcing latency compromises in driver behavior analytics.
Strategic Opportunities
- Kuwait and Oman Penetration:Fleet telematics adoption in Kuwait and Oman lags Saudi Arabia and the UAE by approximately three to four years, presenting first-mover advantages for platform providers establishing local partnerships.
- Insurance-Telematics Convergence:Gulf-based insurers are piloting usage-based premium models tied to telematics-verified safety scores, creating new revenue streams for data analytics providers.
- AI-Video Fusion:Machine vision algorithms integrated with dashcam footage are expanding into automated incident reconstruction and driver coaching, differentiating premium platform tiers.
Industry Challenges
- Embedded Systems Engineering Talent:The shortage of firmware developers experienced in low-power IoT sensor design limits local product customization for GCC climate conditions and Arabic-language interfaces.
- Legacy Fleet Integration:Older commercial vehicles lacking OBD-II ports require expensive aftermarket hardware retrofits, complicating rollout timelines for mixed-age fleets.
- Cross-Border Data Harmonization:Divergent national standards for telematics data formats between Saudi Arabia, the UAE, and other GCC states create compliance complexity for regional logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Commercial Telematics Market |
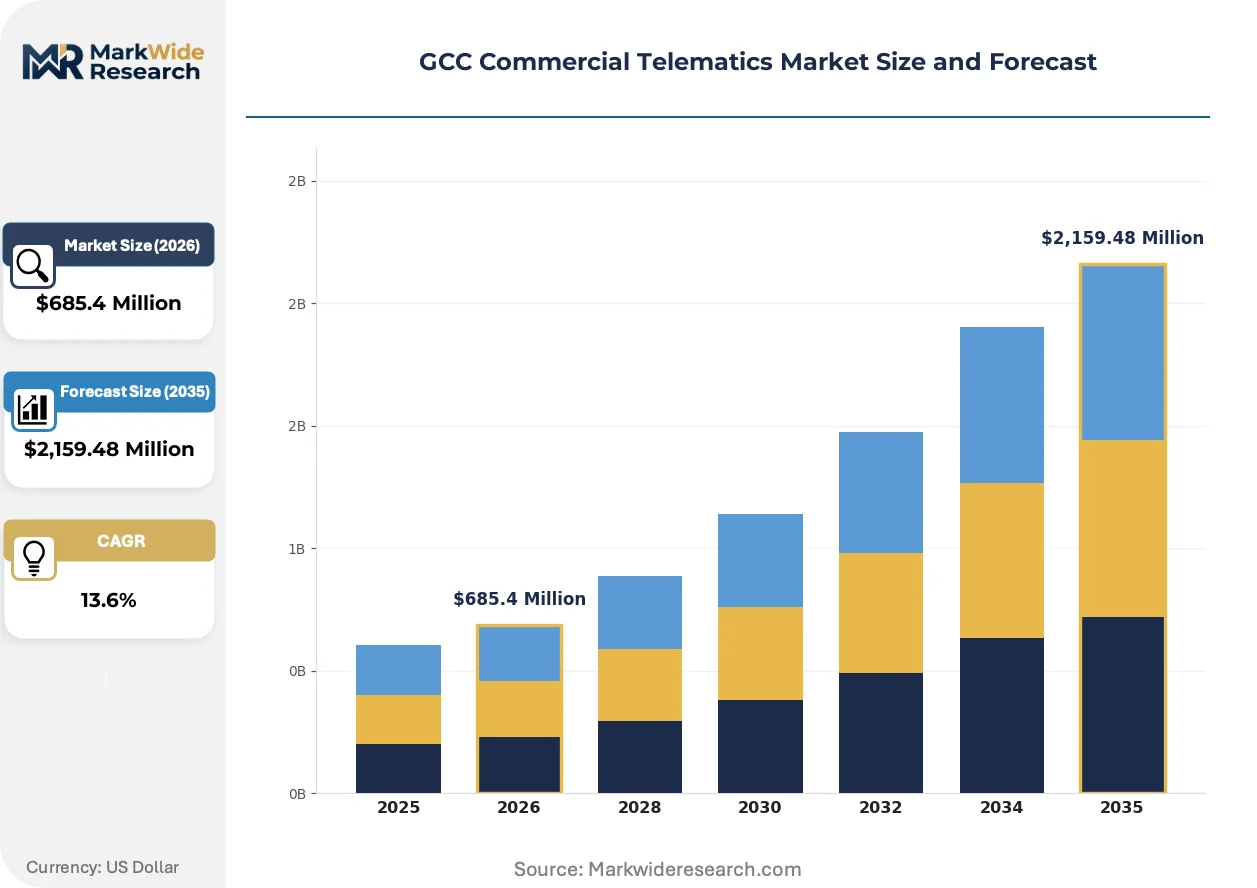
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,159.48 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Driver Behavior, Vehicle Tracking, Asset Monitoring Technology: GPS, RFID, IoT, Cellular End User: Logistics, Transportation, Construction, Waste Management Service Type: Data Analysis, Software Integration, Consulting, Maintenance |
| Companies Covered | Trimble Inc., Powerfleet Inc., Verizon Connect, MiX Telematics, Continental AG, Geotab Inc., Omnitracs, CalAmp Wireless Networks Corporation, Samsara Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Commercial Telematics Market Strategic Shifts & Innovations
Cellular-based connectivity architectures are displacing satellite-dependent systems across GCC commercial fleets, while artificial intelligence and edge computing capabilities migrate from cloud servers into vehicle-mounted hardware units.
Edge AI processors embedded directly into vehicle telematics units are expanding into real-time driver fatigue detection and predictive engine diagnostics without cloud dependency. Saudi-based long-haul operators running Dubai-Riyadh-Jeddah corridors are deploying these units to maintain functionality during cellular dead zones. This capability expansion is compressing the differentiation window between basic tracking and premium fleet management tiers.
SFDA and MOHAP alignment with EU-type data protection frameworks is expanding into commercial vehicle telematics, requiring explicit driver consent for biometric monitoring and location tracking. Fleet operators must now maintain auditable consent records alongside operational data. The driver behavior analytics segment is responding by re-architecting data pipelines to separate personally identifiable information from aggregated safety scoring.
Subscription-based platform pricing is displacing perpetual license models as Gulf logistics firms prioritize operational expenditure flexibility over capital-intensive hardware ownership. Third-party logistics providers and mid-sized freight operators are driving this transition, demanding month-to-month contracts with embedded hardware upgrades. This shift is most visible in Dubai's free zone logistics clusters, where fleet operators rotate equipment across multiple contract vehicles.
GCC Commercial Telematics Market Segmentation
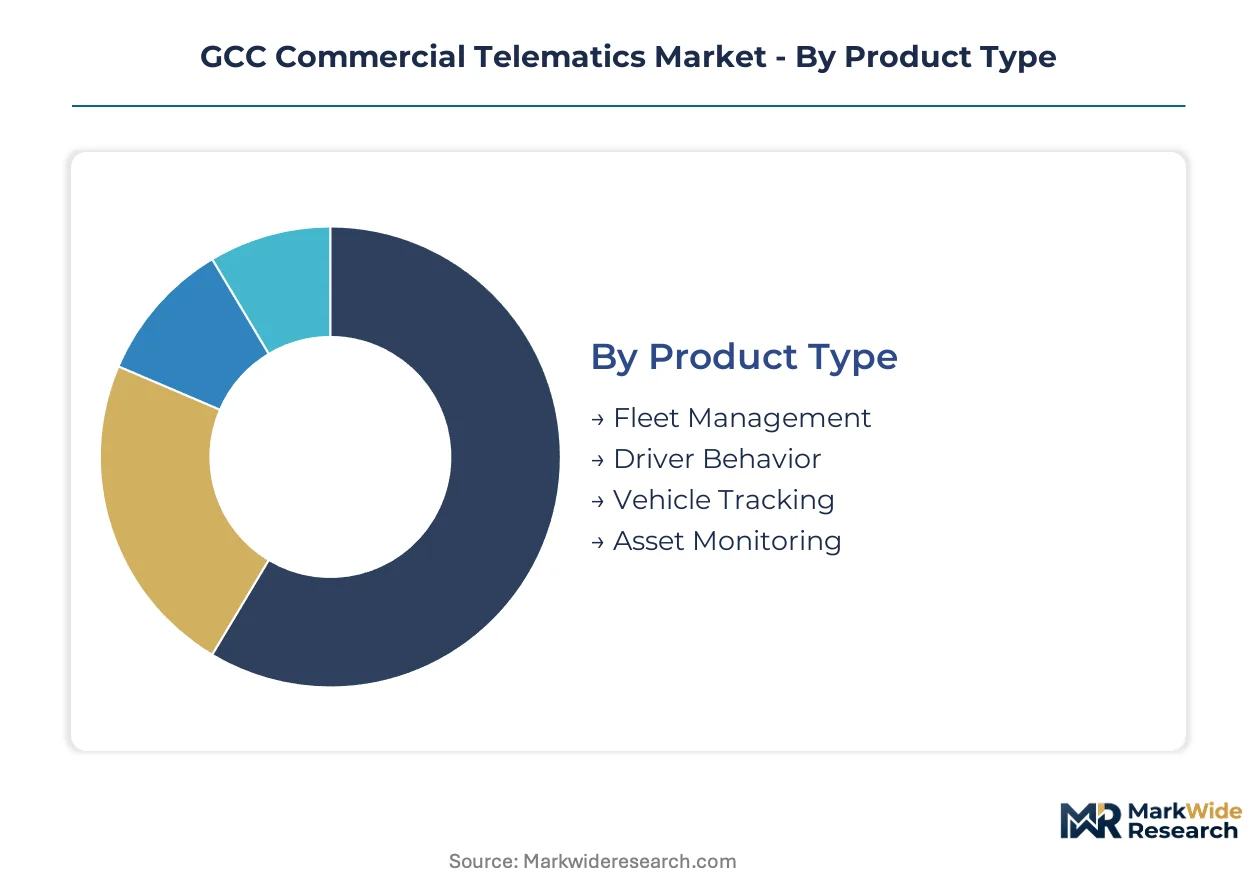
Segmentation in the GCC Commercial Telematics Market reveals how integration depth varies sharply across product tiers. Fleet operators in Saudi Arabia and the UAE select standalone modules for basic compliance while embedding multi-sensor platforms for predictive analytics in long-haul corridors.
Product Type:
Integration depth separates standalone tracking units from embedded enterprise platforms that fuse multiple data streams into unified command centers.
- Fleet Management:Integrated dispatch, route optimization, and compliance dashboards anchor recurring software subscriptions across Dubai's logistics free zones and Riyadh's freight networks. Saudi Arabia's Public Transport Authority mandates for hours-of-service tracking accelerate hardware refresh cycles among operators running Jeddah-Riyadh-Dubai corridors.
- Driver Behavior:Telematics-verified safety scoring systems tie insurance premium calculations to real-time acceleration, braking, and cornering analytics. Gulf-based insurers pilot usage-based models in the UAE, creating data monetization channels for platform providers.
- Vehicle Tracking:GPS-only legacy units face replacement pressure as cellular-IoT mandates take effect.
- Asset Monitoring:Cargo condition sensors and predictive maintenance algorithms target construction fleets in Neom and Red Sea Project zones.
Fleet Management leads volumes today; Driver Behavior is gaining share fastest.
Technology:
Cost tier alignment determines which connectivity stacks dominate budget-conscious versus premium deployments across GCC fleet operators.
- IoT:Multi-sensor arrays combining engine diagnostics, cargo monitoring, and edge AI processing command 40-60% hardware premiums over legacy units. Construction and mining operators in Saudi Arabia's remote worksites deploy these for predictive maintenance without cloud dependency during cellular dead zones.
- Cellular:Dedicated IoT spectrum allocation by TRAI-equivalent regulators across GCC states reduces data costs and enables real-time sensor transmission. Logistics providers in Dubai's free zones rotate cellular-enabled hardware across contract vehicles under month-to-month subscription models.
- GPS:Standalone positioning remains embedded as a baseline capability in all hardware tiers.
- RFID:Short-range identification supplements yard management and cargo handoff verification in port-centric logistics clusters.
Cellular anchors the largest installed base; IoT is expanding most quickly.
End User:
Application intensity varies by sector, with long-haul operators demanding continuous connectivity versus intermittent-use construction fleets.
- Logistics:Third-party freight operators across Dubai, Jeddah, and Riyadh corridors drive subscription pricing adoption, prioritizing operational expenditure flexibility. Integrated dispatch platforms with embedded compliance tools capture recurring revenue from mid-sized regional operators.
- Transportation:Passenger and goods transport fleets face the steepest regulatory pressure for electronic logging and emissions monitoring under Saudi and UAE federal mandates.
- Construction:Heavy equipment operators in Saudi Arabia's giga-projects deploy precision telematics for asset tracking in remote worksites with limited cellular coverage.
- Waste Management:Municipal and private collection fleets utilize route optimization and bin-level sensors for operational efficiency in urban Saudi and UAE centers.
Logistics dominates current deployment value; Construction is climbing the fastest.
Service Type:
Customer type segmentation separates self-managed fleets from operators outsourcing telematics complexity to managed service providers.
- Software Integration:API-first platforms allowing customization without proprietary hardware lock-in attract Gulf-based logistics firms seeking analytics flexibility. Open-architecture providers enable third-party data fusion with existing enterprise resource planning systems.
- Data Analysis:Aggregated safety scoring and predictive maintenance insights create standalone revenue streams for analytics specialists serving insurers and fleet operators.
- Consulting:Implementation and compliance advisory supports mixed-age fleets requiring aftermarket hardware retrofits for vehicles lacking OBD-II ports.
- Maintenance:Hardware refresh and firmware update services ensure continued regulatory compliance as GCC states harmonize cross-border data standards.
Software Integration leads service revenue; Data Analysis is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telematics engineering talent concentrates in Dubai and Riyadh, where platform providers have built regional headquarters to serve cross-border logistics operators. These hubs anchor software development and customer success teams supporting fleet deployments across the Arabian Peninsula.
Saudi Arabia
Construction fleets in Neom and the Red Sea Project zones deploy precision telematics for asset tracking in remote worksites. The Public Transport Authority mandates electronic logging devices and hours-of-service tracking for all commercial vehicles. Riyadh's logistics corridors connecting Jeddah and Dammam see the highest density of cellular-IoT hardware installations.
United Arab Emirates
Dubai's free zone logistics clusters drive subscription-based platform adoption among third-party freight operators. The Federal Transport Authority requires emissions monitoring and electronic logging for commercial fleets operating across the seven emirates. Abu Dhabi's industrial zones host managed service providers offering integrated telematics with ERP system connectivity.
Kuwait
Fleet telematics adoption lags Saudi Arabia and the UAE by approximately three to four years, creating first-mover opportunities for platform providers. The country's national transport regulator is evaluating electronic logging mandates similar to neighboring Gulf states. Kuwait City's port-centric logistics operators pilot basic vehicle tracking ahead of anticipated compliance deadlines.
Oman
Long-haul operators running the Muscat-Dubai corridor face intermittent cellular coverage challenges in desert stretches. Oman's telecommunications regulator has allocated dedicated IoT spectrum to reduce connectivity costs for commercial fleets. Sohar's industrial port zone attracts construction equipment telematics deployments serving mining and infrastructure projects.
Qatar
Post-event infrastructure development drives demand for construction fleet telematics with predictive maintenance capabilities. The country's national transport authority coordinates with GCC counterparts on harmonized vehicle data standards. Doha's logistics free zones host regional headquarters for telematics providers serving the broader Gulf market.
GCC Commercial Telematics Market Key Industry Players
Top-tier vendors anchor premium fleet management platforms, while mid-tier specialists compete on sector-specific customization and price-sensitive hardware bundles. The vendor base spans integrated multinational platforms, regional system integrators, and hardware-focused equipment suppliers. Two strategic archetypes dominate: open-architecture software providers enabling third-party analytics integration, and vertically integrated hardware-software stacks targeting compliance-heavy transportation segments. Competitive moves center on strategic partnerships with Gulf logistics operators and portfolio diversification into adjacent insurance-telematics convergence.
Within the precision telematics tier, Trimble Inc. and Geotab Inc. exemplify contrasting platform philosophies for Gulf-based fleet operators. Trimble anchors high-value construction and mining contracts through integrated asset tracking, while Geotab occupies a position emphasizing open-platform customization without proprietary hardware lock-in. Verizon Connect represents the compliance-integrated archetype, with video telematics and regulatory tooling tailored to regional operator requirements. These three vendors illustrate how competitive positioning splits between sector specialization, architectural openness, and regulatory workflow depth.
| Leading Market Players |
|---|
| Trimble Inc. |
| Powerfleet Inc. |
| Verizon Connect |
| MiX Telematics |
| Continental AG |
| Geotab Inc. |
| Omnitracs |
| CalAmp Wireless Networks Corporation |
| Samsara Inc. |
| Others |
Cost & Logistics Intelligence
Mandatory electronic logging mandates from Saudi Arabia's Public Transport Authority and the UAE's Federal Transport Authority are forcing fleet operators toward integrated cellular-IoT hardware bundles, compressing procurement flexibility and compressing margins for suppliers unable to absorb upfront cost differentials.
Pricing Analysis
The bundled-versus-unbundled service split separates hardware-only transactions from recurring software subscriptions across GCC fleet management platforms. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by integration depth, after-sales support tiers, and customization scope for Arabic-language interfaces. Pricing pressure stems from small fleet operators with under fifty vehicles resisting hardware premiums for multi-sensor IoT arrays. Large logistics providers in Dubai's free zones exhibit lowest price sensitivity due to operational expenditure flexibility demands.
Supply Chain Analysis
Firmware engineering talent shortages in Dubai and Riyadh constrain local customization capacity for GCC climate-specific hardware adaptations. Hardware manufacturing concentrates in China, Taiwan, and South Korea, with cellular communication modules and edge AI processors drawing from semiconductor foundries in these geographies. Supply chain risk centers on single-source vulnerability for low-power IoT sensor components during regional connectivity disruptions. Distribution runs through hyperscale data centers concentrated in Dubai and Riyadh, with managed service providers handling downstream integration for mixed-age fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC Commercial Telematics Market functions as a regulatory compounder, with electronic logging and emissions monitoring mandates from Saudi and UAE transport authorities generating replacement-driven demand cycles across fleet operator procurement.
For Market Incumbents: Hedge against margin compression in basic tracking tiers by deepening software integration capabilities and securing managed service contracts with large logistics operators in Dubai's free zones. Prioritize certification investment for unified GCC vehicle standards to preempt compliance fragmentation risks. Channel control through local partnerships in Kuwait and Oman defends position against emerging regional system integrators. For New Entrants and Emerging Players: Edge AI processors embedded for real-time driver fatigue detection offer a technology-first wedge into premium fleet management tiers where latency requirements exceed cloud-dependent alternatives. Kuwait and Oman present the most penetrable geographies, with fleet telematics adoption lagging Saudi Arabia and the UAE by three to four years. A direct-to-fleet sales model targeting mid-sized construction operators in Saudi Arabia's giga-projects bypasses incumbent channel dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with open-architecture software providers enabling third-party analytics integration without proprietary hardware lock-in, given Gulf logistics firms' prioritization of customization flexibility. Long-term viability favors platforms with recurring subscription revenue anchored to regulatory compliance mandates rather than hardware-dependent transactional models. Watch for harmonized GCC vehicle standards as the inflection signal accelerating cross-border operator consolidation and platform standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open-architecture APIs enable ERP connectivity for Dubai-based third-party logistics providers. |
| Geographic Expansion | First-mover partnerships in Kuwait and Oman capture pre-mandate fleet operator relationships. |
| Strategic Partnership | Insurance-telematics convergence pilots with UAE-based underwriters create data monetization channels. |
| Product Launch | Edge AI-enabled driver coaching differentiates premium tiers in Saudi long-haul corridors. |
| Acquisition of Specialist Firm | Firmware development capabilities address embedded systems engineering scarcity in GCC markets. |
Research Approach
Bottom-up fleet operator modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with fleet managers, transport authority compliance officers, telematics platform engineers, and insurance underwriting specialists combined with secondary validation from Saudi Public Transport Authority regulatory filings, UAE Federal Transport Authority mandate documentation, customs import records for cellular-IoT hardware, and hyperscaler data center capacity disclosures. Triangulation across these sources ensures segment-level granularity without single-source dependency.
The input-output matrix framing maps installed base expansion, hardware refresh cycles, and software subscription attach rates against regulatory mandate timelines and cellular spectrum allocation decisions. Segmentation dimensions modeled include product type, connectivity technology, end-user sector, and service delivery model, with CAGRs derived from slope consistency checks across hardware unit economics and recurring revenue trajectories. Forecast inputs incorporate fleet operator consolidation patterns and cross-border logistics corridor development in the Arabian Peninsula.
The model holds under sustained regulatory enforcement of electronic logging mandates and stable IoT spectrum allocation; deviation in mandate delay or spectrum reallocation would shift hardware replacement timelines. Forecasts reflect documented assumptions regarding compliance adoption curves and cellular coverage expansion in remote desert corridors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Global Automotive Navigation System Market