
 Roadside Assistance Software Market | 2026-2036
Roadside Assistance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Roadside Assistance Software Market Insights
The EU Green Deal is recalibrating roadside assistance requirements as electric vehicle adoption mandates expand charging-network coverage obligations. Samsara leverages its IoT sensor platform to anchor fleet breakdown prediction across North American logistics corridors. TowBook sustains dominance in dispatch automation through deep workflow specialization for independent tow operators.
Roadside assistance software encompasses digital platforms that coordinate vehicle recovery, repair dispatch, and emergency services through real-time GPS tracking, API-connected job routing, and cloud-based fleet visibility. These systems process location telemetry, service history, and traffic data to minimize response latency for stranded motorists. Mobile app solutions command the largest deployment share as drivers expect smartphone-native incident reporting, while GPS tracking segments capture expanding margin pools through insurance telematics partnerships. API integration architectures are displacing standalone deployments as automotive manufacturers embed roadside assistance into connected vehicle operating systems.
The US NHTSA mandates emergency response data standards that shape software interoperability requirements for crash-alert systems. The EU's GDPR and AI Act impose algorithmic transparency obligations on automated dispatch routing and driver data processing. Stakeholders must monitor how evolving vehicle-to-everything communication standards redefine the boundary between OEM-controlled assistance and third-party service networks.
Market Dynamics
Connected vehicle telemetry is compressing incident-to-dispatch windows as OEMs embed predictive failure algorithms directly into operating systems. This shift is redefining competitive advantage around data latency rather than fleet scale.
Growth Catalysts
- EU Green Deal charging mandates:Member states must deploy interoperable charging infrastructure, creating dispatch complexity that software platforms resolve through real-time availability mapping.
- Insurance telematics integration:Underwriters now require granular incident data for usage-based policies, pulling roadside platforms into core claim workflows.
- German automotive OEM ecosystem:Predictive breakdown alerts from connected car fleets are generating proprietary service demand that third-party software must interface with.
Market Restraints
- API standard fragmentation:Vehicle manufacturers deploy proprietary data protocols, forcing software vendors to maintain multiple integration layers that inflate development overhead.
- GPRS network dependency:Rural coverage gaps in mountainous regions of Austria and Switzerland create dispatch blind spots that satellite fallback cannot economically address.
- Lithium battery thermal runaway protocols:EV recovery requires specialized equipment certification that extends technician training cycles and limits supplier pools.
Strategic Opportunities
- Polish logistics corridor expansion:Cross-border freight volume through Baltic-Black Sea routes lacks integrated breakdown coverage, creating first-mover terrain for dispatch platforms.
- Vehicle-to-everything protocol convergence:5G-V2X standardization enables direct vehicle-infrastructure communication, allowing software to preempt driver-initiated service calls.
- France mobility-as-a-service mandates:Urban congestion pricing schemes are accelerating fleet electrification, requiring roadside networks that handle mixed-powertrain incidents.
Industry Challenges
- Technician certification velocity:High-voltage EV safety credentials require renewal cycles that outpace training program capacity in Iberian markets.
- Legacy dispatch system interoperability:Independent tow operators in Italy and Greece operate on decades-old radio networks that resist cloud-based routing integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roadside Assistance Software Market |
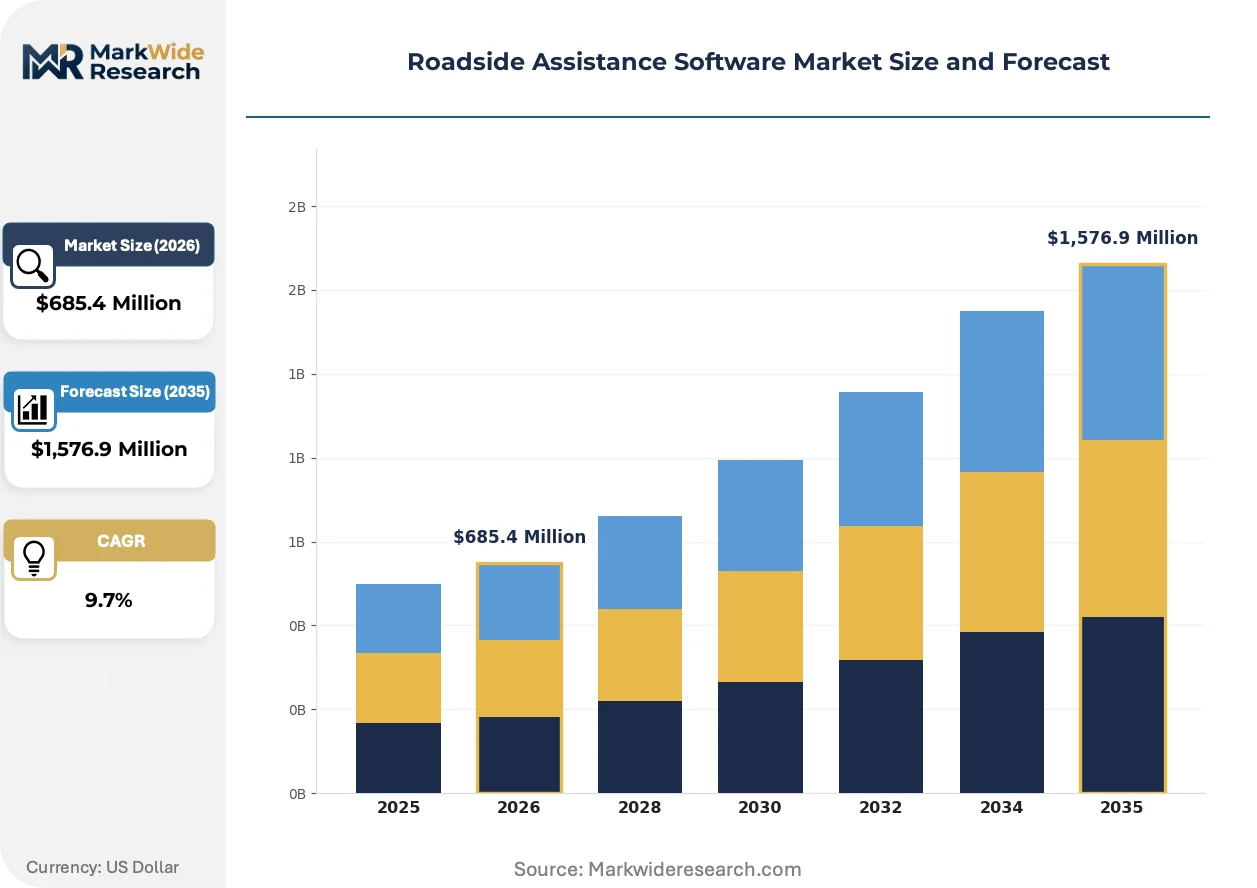
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Mobile App, Web Portal, GPS Tracking, Fleet Management Service Model: Subscription, Pay-Per-Use, On-Demand, Annual Plan End User: Emergency Services, Insurance Companies, Automotive Manufacturers, Tow Truck Operators Integration Level: API Integration, Standalone, Cloud Integration, Mobile Integration |
| Companies Covered | OnDispatch, TowBook, TowManager, ServiceTitan, Jobber, Housecall Pro, Samsara, Fleetio, Geotab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roadside Assistance Software Market Trends and Innovations
Artificial intelligence is rewriting dispatch optimization as neural networks process multi-source telemetry to predict failure before symptom manifestation. This capability is shifting competitive differentiation toward predictive accuracy rather than reactive response density.
Edge computing architectures are electrifying roadside assistance by embedding inference engines directly within connected vehicle gateways. Fleet operators in the Netherlands and Belgium are deploying these systems to process sensor data locally, eliminating cloud round-trip latency for critical safety alerts. This architecture is compressing the window between anomaly detection and service dispatch from minutes to milliseconds.
The EU AI Act's risk classification framework is imposing algorithmic transparency obligations on automated dispatch routing decisions. Software vendors must now document training data provenance and decision logic for high-risk automated systems that direct emergency response. German and French regulators are conducting the first compliance audits, forcing platforms to reengineer black-box recommendation engines into auditable decision trees.
Subscription-based service bundling is displacing per-incident pricing as fleet managers consolidate vendor relationships. Logistics operators across the Rhine-Alpine corridor now procure roadside coverage through annual contracts tied to vehicle telematics platforms, collapsing the traditional insurance-intermediary channel. This shift is most visible in Scandinavian markets where fleet digitization maturity exceeds continental averages.
Roadside Assistance Software Market Segmentation
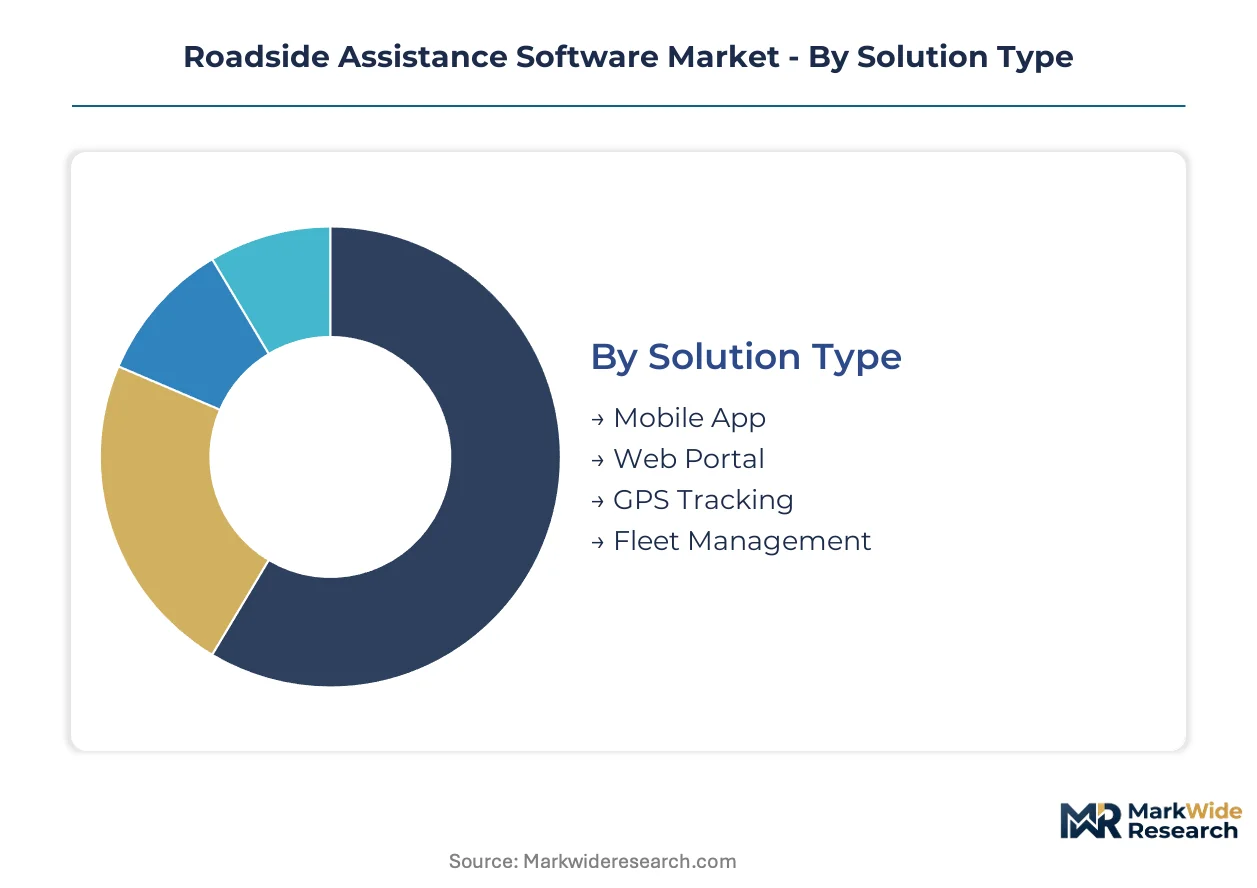
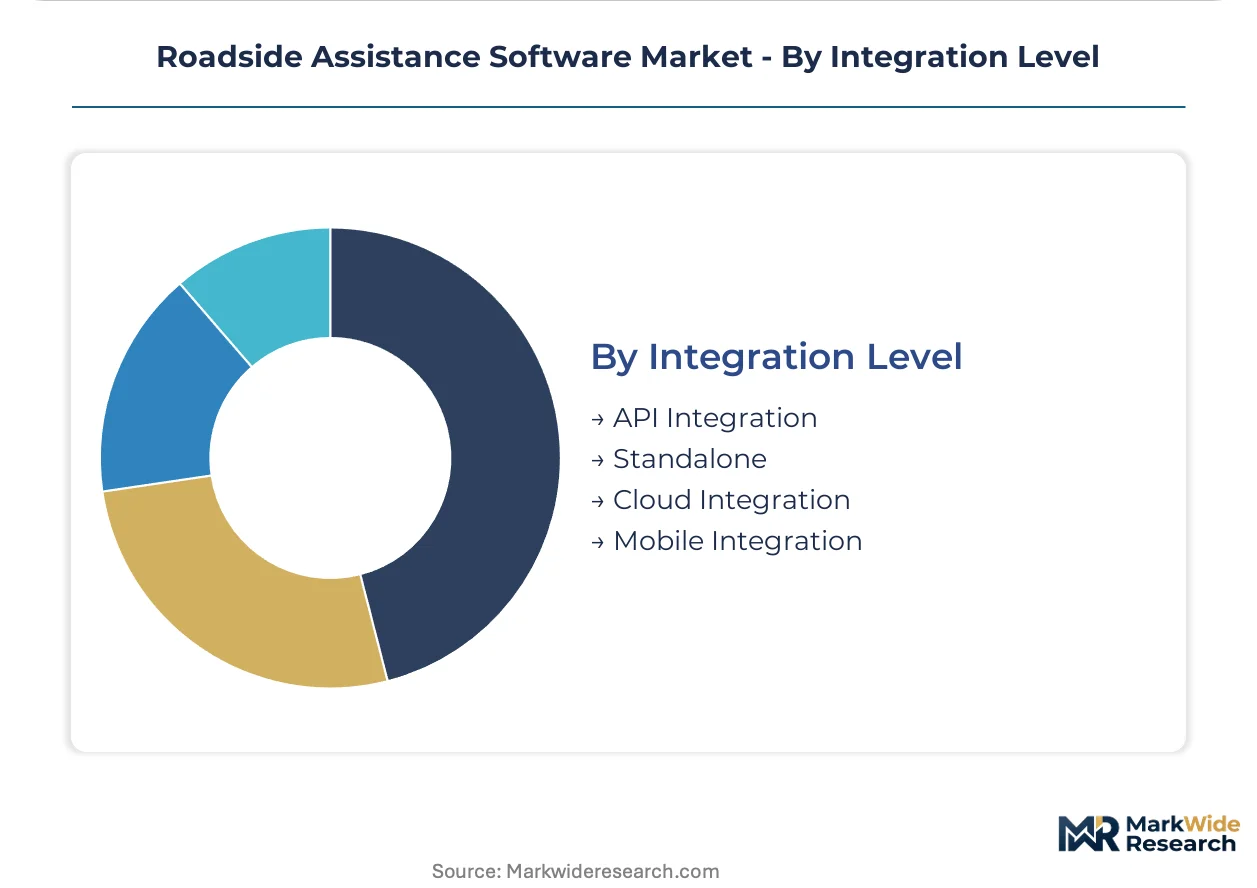
Segmentation in roadside assistance software reveals how deployment architecture and commercial relationships determine margin capture. Solution type and integration level expose the technical fault lines between incumbent dispatch systems and emerging predictive platforms.
Solution Type:
Volume deployment concentrates in driver-facing mobile interfaces, while premium functionality migrates toward embedded fleet infrastructure and predictive telemetry systems.
- Mobile App:Native smartphone applications process incident reporting through GPS-enabled distress signaling and real-time technician tracking. Demand clusters in Germany where automotive OEMs mandate white-label driver interfaces for connected car subscriptions. Fleet operators in the Netherlands prioritize these solutions for last-mile delivery visibility.
- GPS Tracking:Continuous location telemetry enables proactive dispatch routing through traffic-aware algorithms and geofenced service territories. Insurance telematics partnerships in France and Belgium are pulling these capabilities into usage-based policy workflows, creating recurring data revenue streams.
- Web Portal:Browser-based dashboards serve fleet managers requiring multi-vehicle oversight without mobile dependency.
- Fleet Management:Integrated platforms combine breakdown response with preventive maintenance scheduling and fuel monitoring.
Mature deployment sits with Web Portal systems serving legacy fleet operators. Newer deployment is concentrated in GPS Tracking as insurers embed location intelligence into core underwriting workflows.
Service Model:
Commercial structure separates recurring revenue platforms from transactional dispatch networks, with contract duration directly correlating to data integration depth.
- Subscription:Fixed monthly fees bundle unlimited service calls with predictive maintenance alerts and priority dispatch queuing. Rhine-Alpine logistics corridors favor these arrangements as fleet digitization maturity enables telematics-linked annual contracts.
- Annual Plan:Prepaid yearly commitments lock in service rates while granting access to premium technician networks and guaranteed response windows. Scandinavian fleet operators lead adoption here, consolidating vendor relationships beyond traditional insurance intermediaries.
- Pay-Per-Use:Per-incident billing persists among independent operators and occasional-use commercial fleets.
- On-Demand:Instant activation without prior registration targets consumer roadside assistance through marketplace aggregators.
Subscription models dominate enterprise fleet procurement. On-Demand activation is expanding most quickly among urban mobility platforms and car-sharing services requiring flexible coverage without asset ownership.
End User:
Customer type determines whether software deployment emphasizes crash-alert automation, claim cycle compression, or technician workflow optimization.
- Insurance Companies:Digital dispatch platforms reduce claim cycle times through automated first notice of loss and direct repair network assignment. EU Green Deal mandates for EV infrastructure coverage are forcing underwriters to recalibrate risk models around charging-network dispatch complexity.
- Automotive Manufacturers:Embedded roadside assistance within connected car operating systems creates proprietary service ecosystems. German OEMs lead integration of predictive breakdown alerts, generating demand that third-party software must interface with through standardized APIs.
- Emergency Services:Public safety agencies require interoperability with crash-alert systems meeting NHTSA data standards.
- Tow Truck Operators:Independent dispatchers prioritize job routing efficiency and payment processing over predictive capabilities.
Insurance company deployment represents the deepest integration with telematics data streams. Tow truck operator adoption concentrates in workflow automation without predictive layer investment.
Integration Level:
Technical architecture choices expose the tension between OEM-controlled vehicle data and open third-party service networks.
- API Integration:Standardized data interfaces enable real-time exchange between vehicle telemetry, dispatch platforms, and insurance claim systems. EU AI Act algorithmic transparency obligations now require documented decision logic for automated routing engines in Germany and France.
- Cloud Integration:Centralized data processing supports multi-tenant scalability and cross-border service coordination for Baltic-Black Sea freight corridors lacking integrated breakdown coverage.
- Standalone:Self-contained deployments persist where proprietary OEM protocols resist external connectivity.
- Mobile Integration:Smartphone-centric architectures prioritize driver-initiated reporting over predictive vehicle signaling.
Cloud Integration anchors new platform development for cross-border logistics. Standalone systems retain share among independent operators in Italy and Greece operating legacy radio networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European roadside assistance software development as German automotive OEMs embed predictive breakdown alerts into connected car operating systems.
Germany
Bavaria and Baden-Württemberg concentrate predictive maintenance platform development as BMW and Mercedes-Benz integrate roadside assistance into vehicle OS. The KBA enforces type-approval standards for connected vehicle data protocols. Munich-based fleet operators now procure telematics-linked annual contracts that collapse traditional insurance intermediaries.
United States
Silicon Valley and Detroit corridors drive AI-powered dispatch optimization through neural networks processing multi-source telemetry. The NHTSA mandates emergency response data standards that shape software interoperability for crash-alert systems. Arizona and Texas host edge computing deployments that compress incident-to-dispatch windows from minutes to milliseconds.
France
Île-de-France logistics operators accelerate subscription-based service bundling as fleet managers consolidate vendor relationships. Urban congestion pricing schemes in Paris mandate mobility-as-a-service integration, requiring roadside networks that handle mixed-powertrain incidents. The CNIL enforces GDPR algorithmic transparency obligations on automated dispatch routing decisions.
Netherlands
Randstad corridor fleet operators deploy edge computing architectures embedding inference engines directly within connected vehicle gateways. Belgian and Dutch regulators conduct the first EU AI Act compliance audits, forcing platforms to reengineer black-box recommendation engines into auditable decision trees. Rotterdam-Antwerp freight lanes lack integrated breakdown coverage, creating first-mover terrain for dispatch platforms.
Poland
Cross-border freight volume through Baltic-Black Sea routes generates demand for cloud-based coordination platforms. The Polish logistics corridor expansion lacks legacy dispatch infrastructure, enabling direct deployment of API-connected job routing without radio network migration costs. Gdańsk and Warsaw clusters attract software vendors targeting first-mover advantage in emerging European freight corridors.
Roadside Assistance Software Market Competitive Landscape
The competitive structure tilts toward fleet telematics specialists with deep insurance integration capabilities. Three archetypes dominate: IoT sensor platform operators anchoring predictive breakdown detection, dispatch automation specialists serving independent tow operators, and connected vehicle system integrators interfacing with OEM proprietary protocols. Strategic moves concentrate on API standardization partnerships and edge computing deployments that eliminate cloud round-trip latency.
Among North American platform operators, Samsara and Geotab occupy positions as telematics-native entrants, while TowBook exemplifies the workflow specialization archetype for independent tow operators. ServiceTitan and Housecall Pro represent field service management platforms extending into roadside assistance through broader contractor software ecosystems. These groupings illustrate how data latency capabilities now outweigh fleet scale as the primary competitive differentiator.
| Leading Market Players |
|---|
| OnDispatch |
| TowBook |
| TowManager |
| ServiceTitan |
| Jobber |
| Housecall Pro |
| Samsara |
| Fleetio |
| Geotab |
| Others |
Pricing and Supply Chain Analysis
Fleet operators in the Rhine-Alpine corridor anchor procurement concentration, locking in multi-year telematics-linked contracts that collapse traditional insurance-intermediary channels and compress pricing variability into standardized SaaS tiers.
Pricing Analysis
Outcome-based pricing tied to guaranteed response windows commands premium positioning in German automotive OEM ecosystems. Three-tier pricing structure across enterprise fleet, mid-market logistics, and independent operator levels differentiates by API integration depth and predictive maintenance bundling. Cost compression in the independent tow segment intensifies as legacy radio-network operators resist cloud migration. Insurance companies exhibit lowest price sensitivity due to claim cycle reduction value, while Mediterranean independent operators face acute margin pressure.
Supply Chain Analysis
High-voltage EV safety certification requirements gate technician network participation, extending training program cycles and limiting supplier pools. Software development concentrates in Germany, the Netherlands, and the United States, drawing from cloud infrastructure providers, IoT sensor manufacturers, and automotive Tier 1 system integrators. Single-source vulnerability sits with proprietary OEM data protocols that resist standardization. Distribution runs through direct enterprise sales for fleet accounts and marketplace aggregators for consumer on-demand activation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into edge computing hardware and OEM data protocol licensing defines competitive positioning as latency capabilities displace fleet scale as the primary value driver.
For Market Incumbents: Hedge API standard fragmentation risk by deepening certification partnerships with German KBA and French CNIL regulators while acquiring niche dispatch automation specialists in Iberian and Italian markets. Channel control through embedded fleet management bundling protects against telematics-native platform erosion. For New Entrants and Emerging Players: Begin with Polish Baltic-Black Sea freight corridors where cross-border breakdown coverage gaps eliminate legacy infrastructure displacement costs. Target cloud-native dispatch platforms for logistics operators lacking integrated service networks. Go-to-market leverage centers on API-first architectures that bypass radio-network migration entirely. For Investors and Strategic Acquirers: The window for entry favors telematics-native platforms with deep insurance integration capabilities over standalone dispatch software. Long-term viability hinges on predictive algorithm accuracy and edge computing deployment scale. Watch for EU AI Act compliance audit outcomes in Germany and France as inflection signals for platform reengineering requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | Embedding inference engines within vehicle gateways eliminates cloud round-trip latency for critical safety alerts. |
| API Standardization Partnership | Collaboration with German OEMs on connected car data protocols reduces proprietary integration overhead. |
| High-Voltage Certification Program | EU Green Deal EV mandates require specialized technician training that extends competitive moats. |
| Insurance Telematics Integration | Direct embedding into usage-based policy workflows creates recurring data revenue streams. |
| Cross-Border Logistics Platform | Cloud-based coordination for Baltic-Black Sea routes captures first-mover advantage in emerging corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fleet operations directors, insurance claims executives, automotive platform engineers, and tow network dispatch managers. KBA type-approval documentation, EU AI Act implementation guidance, NHTSA emergency response standards, and connected vehicle production databases supplied validation layers. Bottom-up deployment counts triangulated against top-down software spending estimates.
Granularity-level modeling segmented by solution architecture, service contract structure, end-user vertical, and integration complexity across deployment scenarios. CAGRs derived from trend extrapolation of telematics penetration rates and predictive maintenance adoption curves, cross-referenced against EU Green Deal infrastructure investment timelines. Forecast inputs incorporated OEM connected car shipment projections and insurance telematics partnership expansion trajectories.
Underlying measurement precision varies by segment; mobile app and GPS tracking deployments carry tighter precision than emerging edge computing architectures. Forecasts reflect documented assumptions around V2X protocol standardization velocity and EV charging network buildout schedules. A model refresh is warranted upon material change in EU AI Act enforcement patterns or 5G-V2X commercial deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Automotive Wi-Fi Router Market