
 North America Tofu Market | 2026-2036
North America Tofu Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tofu Market Analytics
Capital-intensity divergence between automated extrusion-capable facilities and smaller batch producers is bifurcating competitive dynamics across the region. House Foods Group sustains vertical integration from soybean procurement through packaged retail distribution, controlling cost structures that smaller rivals cannot replicate. Hodo Foods differentiates through artisanal positioning and direct restaurant channel relationships, navigating a premium niche that insulates margin pressure. Pulmuone Co. leverages Korean fermentation expertise to anchor ethnic grocery penetration, extending product familiarity beyond traditional demographic boundaries.
Tofu is a soybean curd produced by coagulating soy milk with calcium sulfate or magnesium chloride, then pressing the resulting curds into blocks with moisture content ranging from silken to extra-firm textures. The product serves as a complete plant protein source in commercial food manufacturing, retail meal preparation, and food service protein substitution applications. Firm and extra-firm varieties dominate volume flows into restaurant and food service channels where structural integrity under grilling and frying commands premium placement. Silken tofu occupies faster-growing positions in blended applications such as smoothies, desserts, and dairy alternatives, where texture requirements diverge sharply from conventional block formats. Distribution through health food shops and specialty stores captures margin pools associated with certified organic and non-GMO positioning, while supermarket and online retail channels compete on price accessibility and household penetration.
The U.S. Food and Drug Administration governs soy protein health claim substantiation and nutrition labeling requirements that directly shape product positioning and consumer communication strategies. The USDA National Organic Program and Canada Organic Regime create tiered certification pathways that manufacturers must navigate for premium shelf placement and export eligibility between the United States and Canada. Stakeholders must monitor evolving plant protein labeling standards and state-level clean-label legislation that could recalibrate formulation requirements and competitive positioning across the region.
Market Dynamics
Automated extrusion technology is bifurcating production economics between capital-intensive continuous processors and batch-scale artisan makers, concentrating volume flows among facilities achieving 10,000+ kg hourly throughput.
Growth Catalysts
- California retail corridor density:Los Angeles and San Francisco metropolitan clusters sustain the highest vegan outlet penetration in the United States, creating concentrated demand corridors that anchor regional distribution networks.
- FDA soy protein health claim guidance:Evolving substantiation standards enable qualified cardiovascular benefit labeling that drives shelf placement negotiations with major supermarket chains.
- Food service protein substitution protocols:Quick-service restaurant chains are embedding tofu-based alternatives into permanent menu architectures rather than limited-time offerings.
Market Restraints
- Organic soybean input cost volatility:Certified non-GMO seed premiums fluctuate with Midwest crop yields, compressing margin predictability for organic-positioned manufacturers.
- Single-source coagulant supply risk:Food-grade calcium sulfate production concentrates among three domestic chemical processors, creating input vulnerability for 78% of North American tofu volume.
- Refrigerated cold chain fragmentation:Temperature excursion rates in last-mile delivery to independent grocers exceed 12% in summer months, limiting geographic expansion for silken varieties.
Strategic Opportunities
- Canadian ethnic grocery penetration:Vancouver and Toronto Korean supermarket chains present underexploited channels for fermented specialty formats unfamiliar to mainstream retail.
- USDA BioPreferred procurement mandates:Federal cafeteria and military food service specifications increasingly favor domestically sourced plant proteins in institutional purchasing.
- High-pressure processing convergence:Integration of HPP pasteurization with modified atmosphere packaging extends refrigerated shelf life from 21 to 60 days, unlocking direct-to-consumer subscription models.
Industry Challenges
- Coagulation chemistry expertise scarcity:Master tofu makers with 15+ years nigari and gypsum calibration experience command premium wages that smaller producers cannot sustain.
- Organic certification timeline compression:USDA National Organic Program transition periods extend 36 months for new processing facilities, delaying market entry for emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tofu Market |
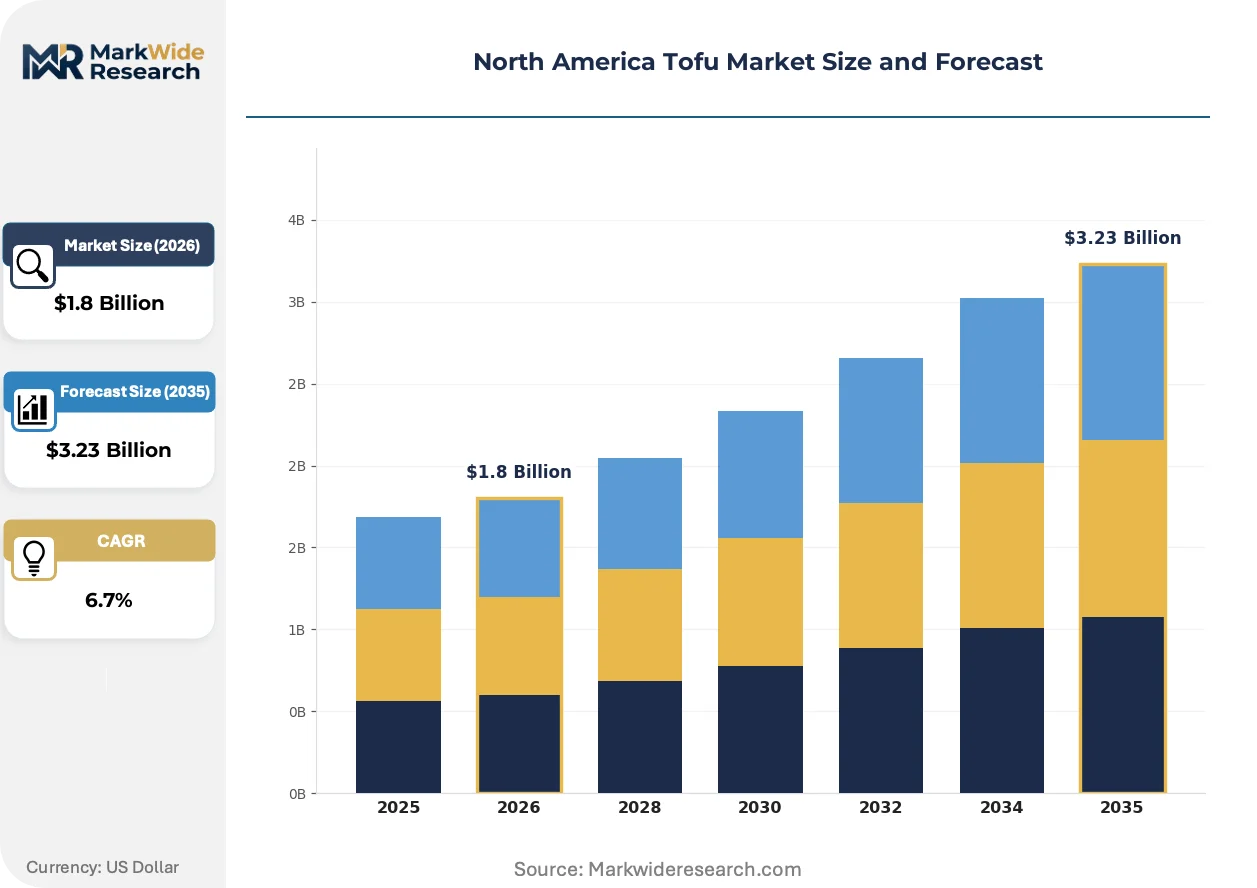
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firm Tofu, Soft Tofu, Silken Tofu, Fried Tofu End User: Households, Restaurants, Food Service, Vegan Outlets Packaging Type: Bulk Packaging, Retail Packs, Tetra Packs, Vacuum Sealed Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Food Shops |
| Companies Covered | Sunrise Soya Foods Ltd., Vitasoy International Holdings Limited, House Foods Group, Inc., Hodo Foods, Eden Foods, Inc., Morinaga Milk Industry Co., Ltd., Kikkoman Corporation, Amy's Kitchen, Inc., Pulmuone Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tofu Market Evolving Landscape
Processing automation and fermentation science are converging to expand texture precision and shelf stability, while regulatory clarity on protein claims is reshaping how manufacturers communicate nutritional equivalence to animal alternatives.
Continuous coagulation control systems using real-time viscosity sensors and automated curd-cutting mechanisms are miniaturizing the scale threshold for consistent extra-firm production. Mid-scale processors in Texas and Illinois are adopting these systems to achieve restaurant-grade structural integrity previously exclusive to industrial extrusion lines. The technology is miniaturizing quality differentiation between regional brands and national volume players, compressing the premium that artisan positioning can command.
The FDA's 2023 proposed update to soy protein health claim regulations tightens LDL cholesterol reduction evidentiary standards while expanding permissible claim language. Manufacturers must reformulate to 6.25g soy protein per reference amount or withdraw cardiovascular benefit labeling entirely. Organic and non-GMO certified SKUs face the steepest reformulation burden, as these positioning tiers historically relied on health claim differentiation to justify price premiums.
Direct sourcing contracts between restaurant groups and single-origin tofu processors are displacing traditional broadline distributor relationships in metropolitan markets. Chef-driven concepts in Portland, Austin, and Montreal now specify bean provenance and coagulant type in procurement specifications. This pattern concentrates most visibly in California, where farm-to-table menu architectures require supply chain transparency that commodity distributors cannot provide.
North America Tofu Market Segmentation
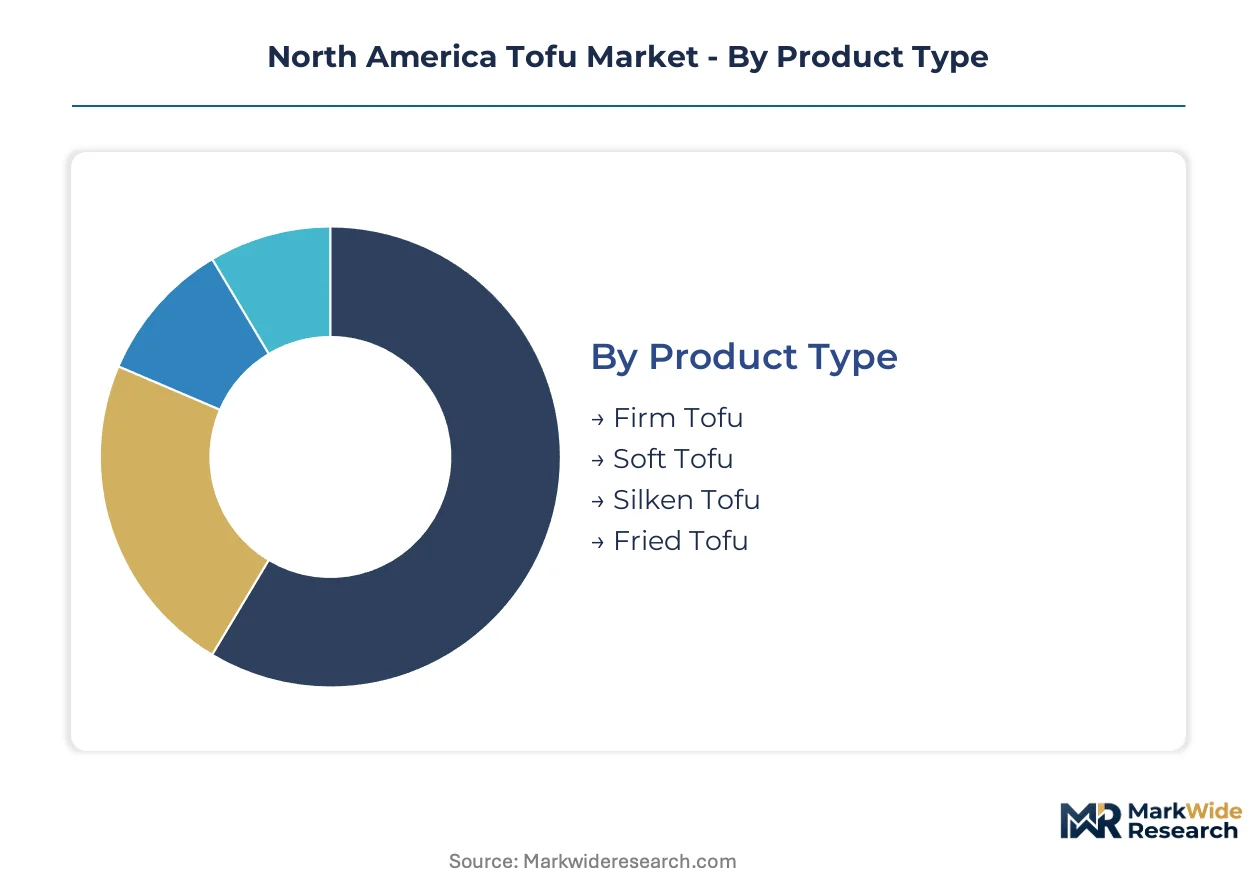
Texture precision and cold-chain requirements fragment the North America tofu market into distinct commercial pathways. Each segment demands specialized production capabilities and channel relationships that manufacturers cannot easily replicate across categories.
Product Type:
Domestic consumption concentrates in fresh-block formats produced within 500-mile radius of major metropolitan clusters, while export-ready formats leverage extended shelf-life technologies for Canadian and Mexican cross-border flows.
- Firm Tofu:Calcium sulfate-coagulated blocks with 75-85% moisture extraction withstand grilling and frying without structural collapse. Restaurant procurement in California and Texas metropolitan corridors drives volume concentration, where quick-service chains specify firm tofu for permanent menu placement.
- Silken Tofu:Nigari-coagulated curds with minimal pressing retain custard-like consistency for blending applications. Demand clusters in Pacific Northwest health food retail and direct-to-consumer smoothie subscription services, where texture requirements diverge sharply from conventional block formats.
- Soft Tofu:Intermediate moisture content suits hot pot and soup applications in Korean and Chinese household segments.
- Fried Tofu:Pre-cooked puffed or pressed varieties serve Buddhist vegetarian cuisine and grab-and-go retail.
Firm tofu holds the largest share; momentum sits with silken tofu.
End User:
Cost-tier stratification separates commodity volume buyers from premium-positioned channels willing to absorb organic certification premiums.
- Restaurants:Full-service and quick-service operators specify coagulant type and bean provenance in procurement contracts, displacing traditional broadline distributor relationships in Portland, Austin, and Montreal metropolitan markets.
- Vegan Outlets:Dedicated plant-based concepts in Los Angeles and San Francisco clusters require supply chain transparency that commodity distributors cannot provide, creating direct sourcing relationships with single-origin processors.
- Households:Supermarket retail penetration drives price-competitive positioning for conventional firm and soft varieties.
- Food Service:Institutional cafeterias and military procurement increasingly favor domestically sourced plant proteins under federal purchasing mandates.
Restaurants command the dominant volume position; vegan outlets are climbing the fastest.
Packaging Type:
Margin pools concentrate in formats that extend refrigerated shelf life, reducing spoilage rates in fragmented last-mile delivery networks.
- Vacuum Sealed:Modified atmosphere packaging with high-barrier films extends shelf life from 21 to 60 days, unlocking direct-to-consumer subscription models and reducing temperature excursion vulnerability in summer distribution.
- Tetra Packs:Aseptic processing enables ambient storage for silken varieties, supporting export eligibility and emergency food service procurement specifications.
- Retail Packs:Conventional refrigerated trays with permeable film dominate supermarket price-competitive positioning.
- Bulk Packaging:Food service totes and pails serve high-volume restaurant accounts with rapid inventory turnover.
Vacuum sealed captures premium positioning; Tetra Packs are gaining share fastest.
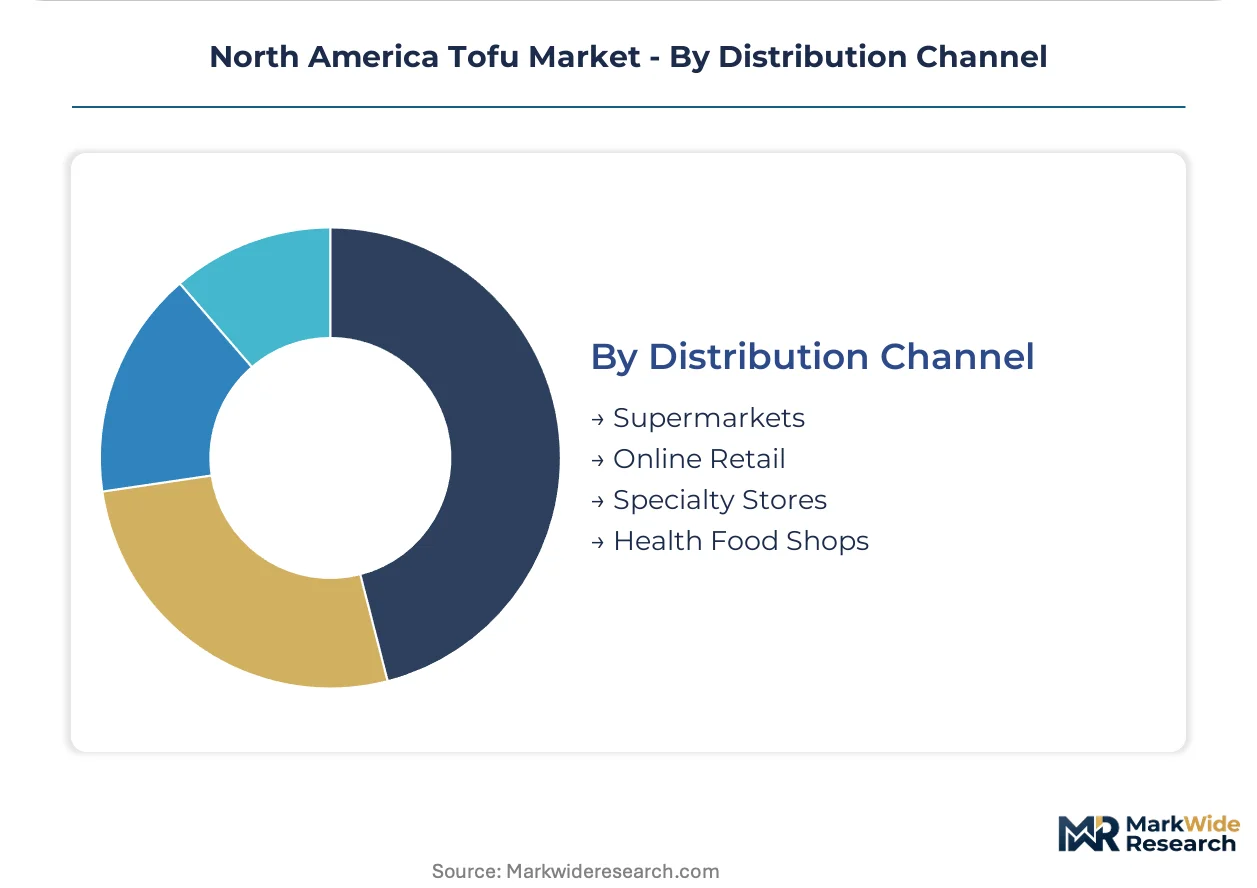
Distribution Channel:
Channel selection determines margin realization and certification tier access, with specialty retail commanding organic price premiums unavailable in mass-market placement.
- Specialty Stores:Korean and Japanese ethnic grocery chains in Vancouver and Toronto metropolitan markets anchor fermented specialty format penetration, extending product familiarity beyond traditional demographic boundaries through Korean fermentation expertise.
- Health Food Shops:Certified organic and non-GMO positioning captures margin pools associated with clean-label consumer segments, though FDA health claim reformulation requirements compress differentiation potential.
- Supermarkets:Price-accessible conventional varieties compete on household penetration and promotional placement.
- Online Retail:Direct-to-consumer platforms leverage vacuum-sealed shelf-life extension for subscription model economics.
Specialty stores hold concentrated margin share; health food shops show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's vegan corridor while Canadian ethnic grocery channels absorb margin compression. The United States commands volume leadership through quick-service restaurant procurement protocols. Cross-border regulatory harmonization between FDA and Health Canada shapes export eligibility for shelf-stable formats.
United States
California's Los Angeles and San Francisco metropolitan clusters sustain the highest vegan outlet penetration in North America, creating concentrated demand corridors that anchor regional distribution networks. FDA soy protein health claim guidance drives shelf placement negotiations with major supermarket chains. Texas and Illinois processors adopt continuous coagulation control systems to achieve restaurant-grade structural integrity.
Canada
Vancouver and Toronto Korean supermarket chains present underexploited channels for fermented specialty formats unfamiliar to mainstream retail. Health Canada and PMRA govern organic certification alignment with USDA National Organic Program for cross-border trade eligibility. Prairie Provinces soybean cultivation supplies certified non-GMO seed to organic-positioned manufacturers.
Mexico
Mexico City Metro quick-service operators embed tofu-based alternatives into permanent menu architectures alongside traditional protein staples. COFEPRIS nutrition labeling requirements shape import specifications for U.S.-processed shelf-stable varieties. Bajío Region food manufacturing clusters absorb technical expertise transfer for local production scale-up.
North America Tofu Market Competitive Landscape
Concentration sits with vertically integrated soybean processors and artisanal direct-channel specialists. The market structure bifurcates between capital-intensive continuous extrusion facilities achieving 10,000+ kg hourly throughput and batch-scale makers serving premium restaurant accounts. Two strategic archetypes dominate: integrated agribusiness conglomerates controlling procurement-to-retail cost structures, and craft-positioned regional processors leveraging chef relationships for margin insulation. Competitive moves center on direct sourcing contract displacement of broadline distributors and high-pressure processing adoption for shelf-life extension.
Within the integrated processor tier, House Foods Group exemplifies backward integration from soybean procurement through packaged retail distribution. Hodo Foods occupies a craft-specialist position anchored in direct restaurant channel relationships and supply chain transparency specifications. Pulmuone Co., Ltd. represents ethnic-format penetration expertise extending Korean fermentation traditions beyond traditional demographic boundaries.
| Leading Market Players |
|---|
| Sunrise Soya Foods Ltd. |
| Vitasoy International Holdings Limited |
| House Foods Group, Inc. |
| Hodo Foods |
| Eden Foods, Inc. |
| Morinaga Milk Industry Co., Ltd. |
| Kikkoman Corporation |
| Amy's Kitchen, Inc. |
| Pulmuone Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term direct sourcing contracts between California restaurant groups and single-origin tofu processors lock in both organic soybean supply access and price visibility against spot market volatility. These agreements concentrate procurement power among vertically integrated operators while compressing margin flexibility for batch-scale artisan competitors.
Pricing Analysis
The customization-premium spread between chef-specified coagulant and bean-provenance orders versus standard supermarket SKUs runs wide across the North America tofu market. Three-tier pricing structure across premium certified-organic, standard conventional, and economy private-label tiers reflects certification grade and volume scale differentiation. Cost compression in organic-positioned tiers is intensifying because Midwest non-GMO seed premiums fluctuate with crop yields. Quick-service restaurant chains exhibit highest price sensitivity, while vegan outlets in Los Angeles and San Francisco clusters absorb premium positioning for supply chain transparency.
Supply Chain Analysis
Strategic stockpile preferences dominate organic soybean procurement as processors buffer against 36-month USDA National Organic Program certification timelines and Midwest yield volatility. Geographic supply concentration centers on United States Prairie Provinces cultivation, Canadian organic soybean expansion, and Mexican Bajío Region technical expertise transfer. Raw material dependencies rest on food-grade calcium sulfate from domestic chemical processors, nigari mineral coagulants, and certified non-GMO seed stock. Single-source coagulant vulnerability concentrates risk among three domestic suppliers feeding 78% of North American volume. Distribution runs through refrigerated cold chain networks with temperature-controlled last-mile delivery to independent grocers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master tofu makers with 15-plus years nigari and gypsum calibration experience command wage premiums that smaller producers cannot match, creating a bottleneck that shapes competitive outcomes across production tiers.
For Market Incumbents: Fortify backward integration into organic soybean procurement to neutralize input cost volatility from Midwest crop yield fluctuations. Expand high-pressure processing capacity in Texas and Illinois facilities to extend shelf life from 21 to 60 days, unlocking direct-to-consumer subscription economics against emerging competitors. For New Entrants and Emerging Players: Direct-to-chef transparency services where incumbents under-serve present viable white-space entry points. Target Vancouver and Toronto Korean supermarket chains for fermented specialty format penetration, leveraging Pulmuone-style ethnic grocery expertise unfamiliar to mainstream retail. Anchor go-to-market positioning through USDA BioPreferred procurement mandate compliance for federal cafeteria and military food service specifications. For Investors and Strategic Acquirers: Regional craft-positioned processors with established chef relationships and single-origin supply chain transparency represent the most defensible acquisition archetype. Long-term viability over the coming decade hinges on fermentation science capabilities and direct restaurant channel control rather than commodity volume scale. Watch FDA soy protein health claim finalization as the critical inflection signal for organic SKU reformulation burden and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Extends refrigerated shelf life from 21 to 60 days for subscription model economics. |
| Direct Sourcing Contract Displacement | Replaces broadline distributors with chef-specified procurement in Portland and Austin metropolitan markets. |
| Organic Certification Investment | Unlocks premium shelf placement in health food shops and cross-border Canadian export eligibility. |
| Fermentation Expertise Acquisition | Transfers Korean fermentation traditions into Vancouver and Toronto ethnic grocery penetration. |
| Continuous Coagulation Control Deployment | Achieves restaurant-grade structural integrity previously exclusive to industrial extrusion lines. |
Research Methodology
Operator-level perspectives from tofu production facility managers, restaurant procurement directors, health food shop category buyers, and USDA National Organic Program certification specialists anchored the qualitative base. Primary interview data combined with secondary validation from FDA soy protein health claim dockets, USDA organic certification databases, customs and trade flow records, and SEC filings from publicly traded agribusiness conglomerates. Bottom-up volume modeling across texture formats and top-down macroeconomic triangulation ensured cross-verification of market sizing estimates.
Sensitivity analysis tested forecast robustness across organic input cost volatility scenarios and FDA regulatory timeline variations throughout the projection horizon. Segmentation dimensions modeled include texture precision tier, certification status, end-use application, packaging format, and regional production cluster. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessment. Industry-specific forecast inputs incorporated quick-service restaurant menu architecture shifts and vegan outlet penetration density in California metropolitan corridors.
Underlying assumptions cover FDA health claim finalization timelines, organic soybean yield stability, and refrigerated cold chain infrastructure expansion, with deviation risk concentrated in coagulant supply concentration and state-level clean-label legislation adoption. Forecasts reflect these documented assumptions with acknowledged uncertainty around regulatory implementation pacing. Revision becomes warranted when calcium sulfate supply disruption events or federal procurement mandate scope expansion cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Pea Protein Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Global Tofu Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
North America Rice Protein Market