
 Vegan Flour Market | 2026-2036
Vegan Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Flour Market Analytics
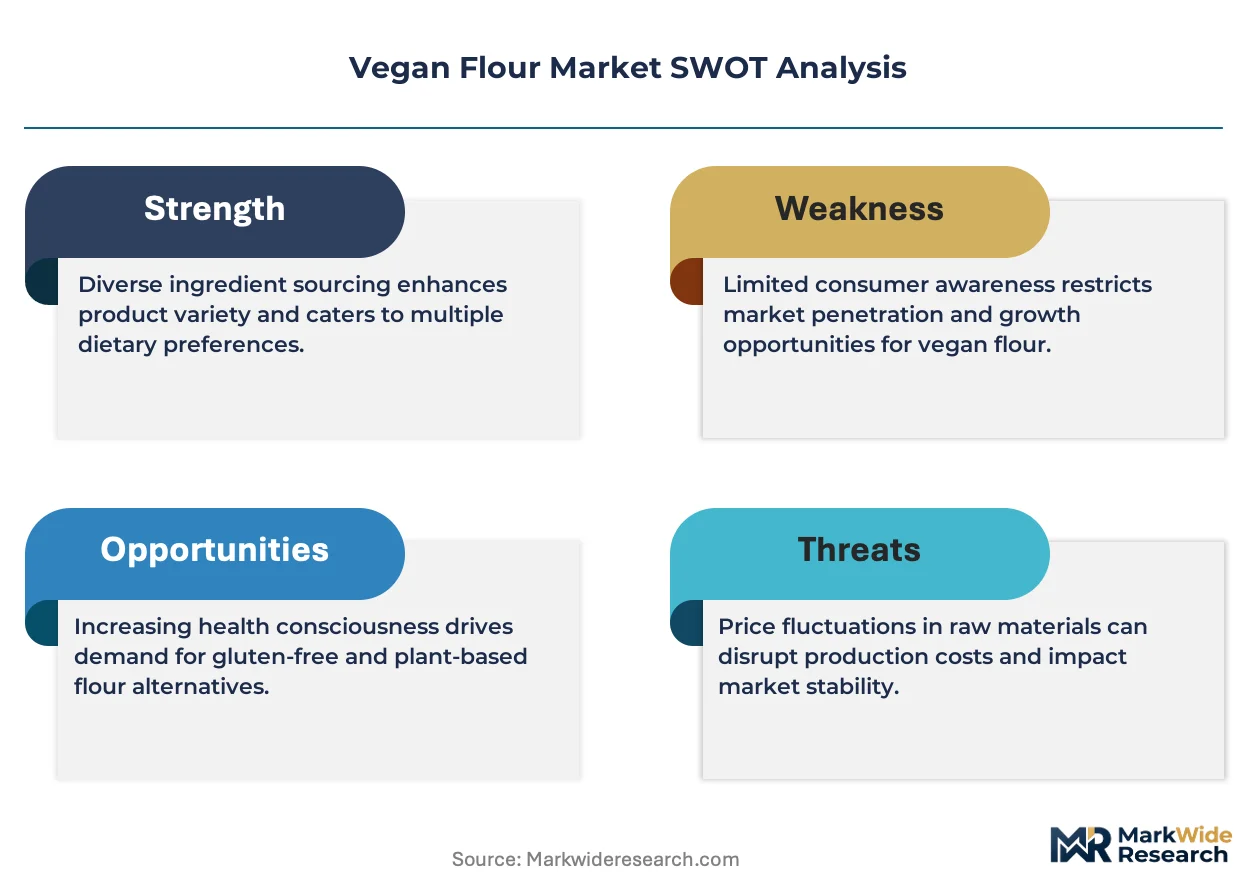
Organic certification and gluten-free specification tiers is reorganizing supplier hierarchies in the vegan flour market. Cargill, Incorporated leverages its North American grain handling infrastructure to secure consistent organic oat supply chains. Bob's Red Mill Natural Foods differentiates through stone-milled heritage processes that command premium shelf positioning. King Arthur Flour Company anchors retail distribution through direct-to-baker partnerships and controlled-channel specialty placement.
Vegan flour denotes milled products derived exclusively from plant sources—almonds, coconuts, chickpeas, oats—processed without animal-derived additives or cross-contamination, typically achieving protein contents of 6-22% and fiber levels of 10-40% depending on source material. These flours serve commercial baking, home cooking, and nutritional fortification applications where allergen management and clean-label positioning drive formulation decisions. Almond flour occupies the premium margin pool due to California supply concentration and high input costs, while chickpea flour represents the fastest-growing structural segment as Mediterranean and South Asian culinary applications expand into Western industrial baking. Oat flour sustains volume leadership through its functional compatibility with existing bakery equipment and neutral flavor profile that reduces reformulation barriers for conventional manufacturers.
FDA allergen labeling requirements and USDA organic certification standards shape product claims and facility segregation protocols in the United States, while EU REACH and EFSA novel food assessments govern ingredient introductions and cross-border trade within Europe. The EU Green Deal's Farm to Fork strategy tightens carbon footprint disclosures for imported nut and legume supplies, redirecting procurement toward regional sourcing clusters. Stakeholders must monitor evolving protein content thresholds in nutrition labeling rules and assess whether backward integration into regional pulse processing or continued reliance on established distributor networks offers superior margin protection.
Market Dynamics
EU Green Deal carbon footprint disclosure mandates are forcing supply chain reconfiguration across the vegan flour sector, redirecting procurement toward regional pulse and nut processing clusters that can document farm-to-mill emissions.
Growth Catalysts
- FDA Allergen Labeling Requirements:Strict facility segregation protocols for nut-derived flours create competitive moats for certified producers serving school and institutional baking contracts.
- France:Artisanal bakers and industrial producers are simultaneously reformulating traditional wheat-based recipes with chickpea and fava bean alternatives to meet clean-label consumer expectations.
- Stone-milling heritage processes:Premium positioning through low-temperature milling preserves heat-sensitive proteins and lipids, commanding shelf space in specialty retail channels.
Market Restraints
- California almond supply concentration:Drought-induced water allocation restrictions and pollination cost volatility compress margins for almond flour producers regardless of end-use segment.
- Cross-contamination protocols:Dedicated gluten-free and allergen-free facility requirements impose capital intensity that excludes smaller regional millers from institutional contract pools.
- Legume flour flavor masking:Beany off-notes in chickpea and lentil flours require enzyme treatment or blending systems that add processing steps and equipment costs.
Strategic Opportunities
- Germany:Plant-based bakery chains are scaling direct procurement relationships with specialty millers to secure traceable organic oat and fava bean supply ahead of EU supply chain disclosure deadlines.
- Pulse protein fortification:Bakery and prepared foods manufacturers are integrating 15-25% chickpea flour to achieve front-of-pack protein claims without isolates or concentrates.
- Direct-to-baker distribution:Bypassing traditional ingredient distributors through miller-owned digital platforms reduces lead times and enables custom granulation specifications for artisanal producers.
Industry Challenges
- Organic certification timeline:Three-year land conversion requirements and annual audit costs delay entry for conventional grain millers pivoting into vegan flour categories.
- Laboratory analytical capacity:Protein content verification, mycotoxin screening, and allergen detection for diverse plant sources strain third-party testing infrastructure in regional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Flour Market |
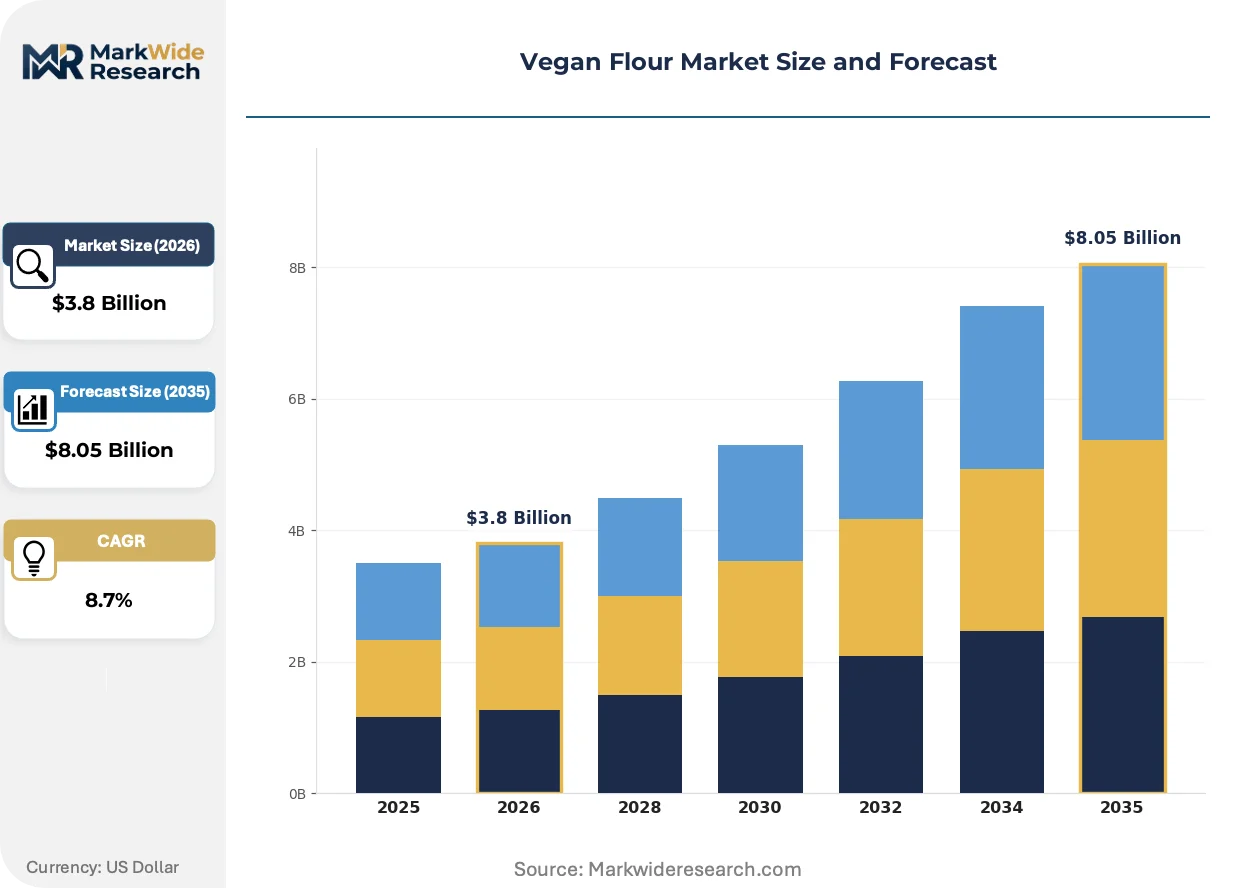
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Flour, Coconut Flour, Chickpea Flour, Oat Flour End User: Bakers, Restaurants, Health Food Stores, Home Cooks Application: Baking, Cooking, Gluten-Free Products, Nutritional Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Ingredion Incorporated, Conagra Brands, Inc, Ardent Mills LLC, Bob's Red Mill Natural Foods, Associated British Foods plc, Puratos Group, King Arthur Flour Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Flour Market Evolving Landscape
Processing technology and procurement models are simultaneously evolving to address protein functionality gaps and supply chain transparency demands that legacy commodity flour systems cannot satisfy.
Extrusion-assisted milling is decomposing the traditional trade-off between fine particle size and protein integrity in pulse flours. Industrial bakeries in the Netherlands and Belgium are adopting twin-screw pre-conditioning systems that gelatinize starch while preserving native protein structures. This technology is decomposing the premium pricing power of imported specialty flours by enabling regional processors to match functional performance.
EU REACH and EFSA novel food assessments are tightening ingredient introduction pathways for emerging protein sources like mung bean and lupin flours. Manufacturers must compile comprehensive toxicology dossiers and consumption exposure data before achieving market authorization. Smaller ingredient innovators are responding through collaborative pre-submission programs that pool safety study costs across multiple applicants.
Buyer concentration among plant-based bakery chains is compressing supplier negotiation leverage and accelerating specification standardization. German and French retail bakery networks are consolidating procurement through central buying cooperatives that demand uniform protein content ranges and lot-level traceability documentation. This concentration is most visible in the artisanal segment, where former independent bakers now operate under franchise systems with mandated ingredient sourcing protocols.
Vegan Flour Market Segmentation
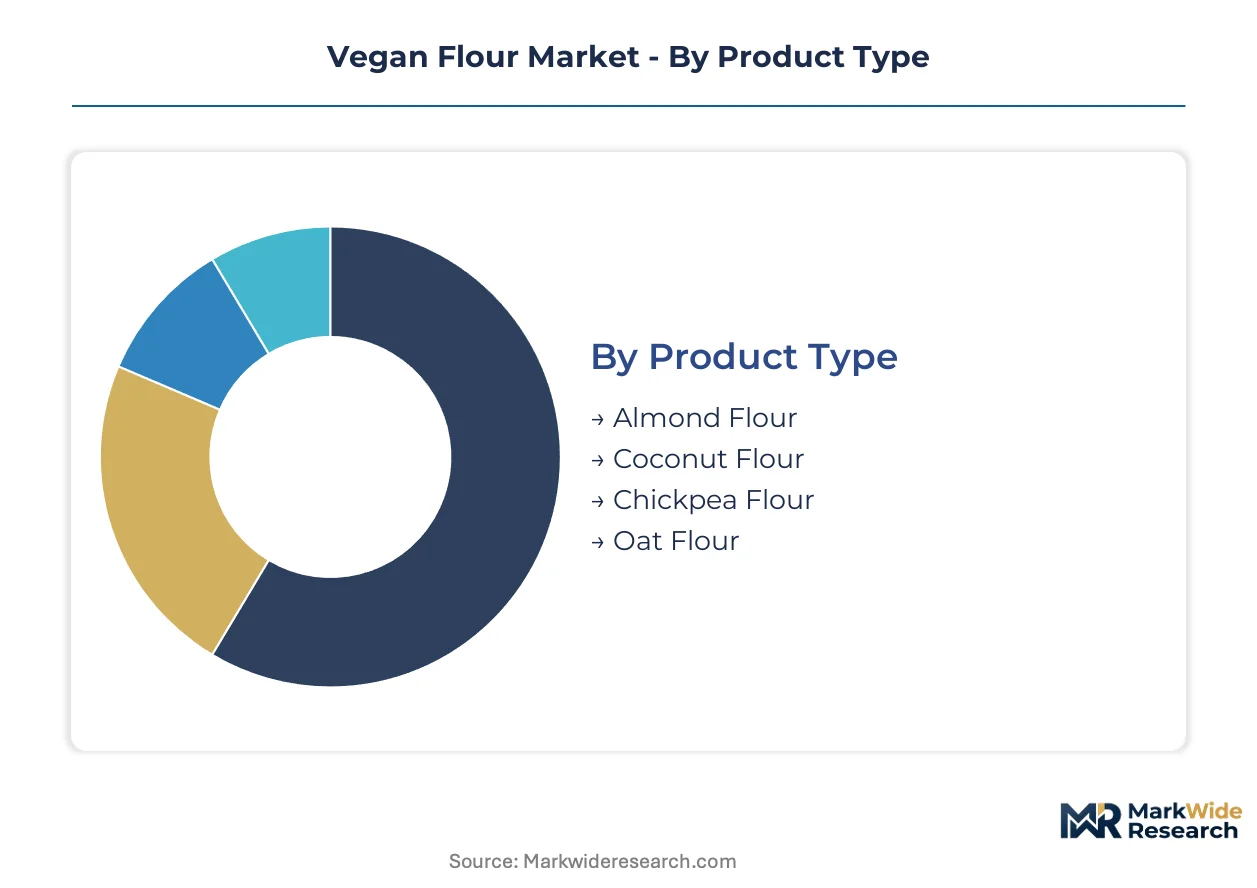
Margin distribution across vegan flour segments follows raw material scarcity and processing intensity rather than volume throughput. Premium protein positioning and clean-label certification tiers create divergent profitability profiles that reshape supplier investment priorities across each dimension.
Product Type:
Margin pools concentrate in nut-derived categories where California water stress and pollination cost volatility sustain premium pricing power, while pulse-based alternatives capture volume through functional reformulation demand.
- Almond Flour:Finely ground blanched almonds yield 21-25% protein content with minimal starch interference in low-carbohydrate baking formulations. Artisanal bakeries in France command premium positioning for macaron and frangipane applications where fat content and particle uniformity determine finished product quality.
- Chickpea Flour:Matured from Mediterranean and South Asian culinary traditions, this segment delivers 18-22% protein with inherent emulsification properties that reduce egg replacement requirements in vegan formulations. Industrial bakeries in Germany are scaling procurement for protein-fortified bread and pasta applications under tightening EU Green Deal disclosure mandates.
- Coconut Flour:High-fiber byproduct of coconut milk extraction processes, requiring significant liquid absorption adjustments in standard recipes.
- Oat Flour:Neutral flavor profile and existing bakery equipment compatibility sustain volume leadership in conventional manufacturer reformulations.
Almond flour holds installed capacity concentration in California processing clusters. Chickpea flour is rotating up the share rankings through Mediterranean culinary application expansion.
End User:
Procurement sophistication varies sharply across this dimension, with institutional buyers demanding lot-level traceability while household purchasers prioritize shelf accessibility and recipe compatibility.
- Bakers:Commercial and artisanal operations specify custom granulation ranges and protein content tolerances that necessitate direct miller relationships. French industrial producers are consolidating procurement through central buying cooperatives that mandate uniform specification documentation.
- Restaurants:Menu development teams source specialty flours for dietary accommodation and narrative differentiation in plant-forward concepts.
- Health Food Stores:Curated assortment strategies emphasize organic certification tiers and allergen-free facility claims that command 40-60% shelf price premiums.
- Home Cooks:Recipe-driven purchasing concentrates in coconut and almond varieties through supermarket baking aisles and digital recipe platform affiliate channels.
Bakers command specification authority through volume commitments. Home cooks are rotating up the share rankings through subscription commerce and direct-to-consumer miller platforms.
Application:
Functional performance requirements determine ingredient selection intensity, with structural applications demanding protein network formation that legume flours satisfy more cost-effectively than nut alternatives.
- Baking:Bread, pastry, and confectionery applications require precise hydration management and gluten-mimetic structure development. Dutch industrial bakeries are adopting extrusion-assisted milling systems that enable regional pulse flour processing to match imported specialty functional performance.
- Gluten-Free Products:Dedicated facility protocols and cross-contamination prevention systems create competitive moats for certified producers serving celiac and wheat-sensitive consumer segments.
- Cooking:Sauce thickening and coating applications leverage starch gelatinization properties without structural protein requirements.
- Nutritional Supplements:Protein fortification and meal replacement formulations prioritize amino acid completeness and digestibility metrics over sensory characteristics.
Baking holds installed capacity across European industrial processing infrastructure. Gluten-free products are rotating up the share rankings through school and institutional contract expansion.
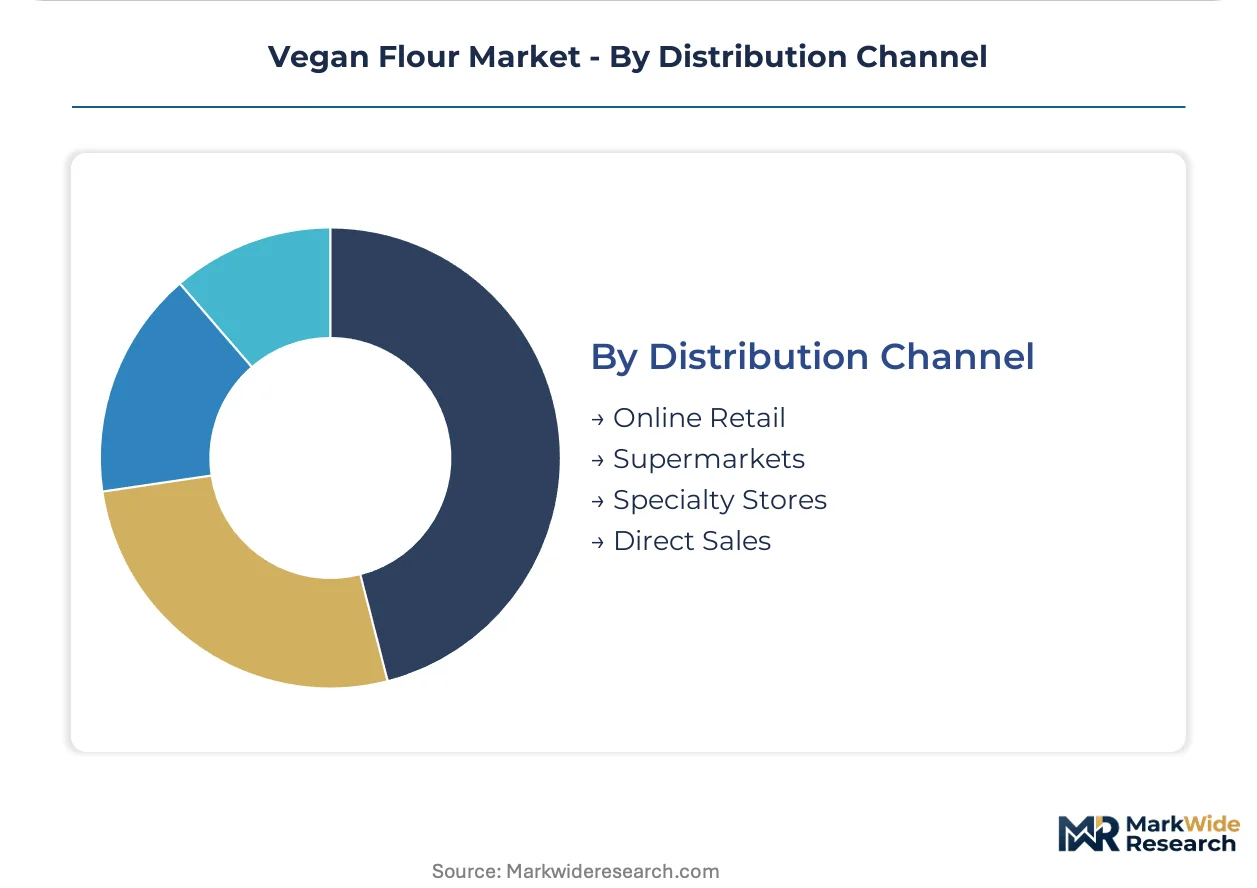
Distribution Channel:
Channel selection determines margin retention and specification control, with direct relationships enabling custom production runs that mass retail distribution cannot accommodate.
- Direct Sales:Miller-owned digital platforms and bakery cooperative procurement systems bypass traditional ingredient distributors to reduce lead times and enable granulation customization. German plant-based bakery chains are scaling these relationships ahead of EU supply chain disclosure deadlines.
- Specialty Stores:Curated assortment and staff expertise support premium positioning for heritage-processed and single-origin flour varieties.
- Online Retail:Subscription models and recipe-bundle merchandising concentrate in home cook segments with pantry stocking convenience priorities.
- Supermarkets:Mass retail placement requires packaging standardization and promotional fund participation that compresses net margins for specialty producers.
Direct sales holds installed capacity among established specialty millers. Online retail is rotating up the share rankings through platform algorithm optimization and influencer recipe integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian organic oat processors are expanding export capacity to serve German plant-based bakery chains facing EU Green Deal disclosure deadlines. This trade corridor illustrates how North American grain infrastructure connects with European sustainability mandates.
United States
California almond millers supply premium flour to French macaron producers despite drought-induced water allocation restrictions. FDA allergen labeling requirements enforce strict facility segregation protocols that certified producers leverage for school and institutional contracts. Sacramento Valley processing clusters concentrate blanched almond flour capacity serving export markets.
Germany
Plant-based bakery chains in Berlin and Hamburg are scaling direct procurement relationships with specialty millers for traceable organic oat and fava bean supply. EU Green Deal Farm to Fork strategy mandates tighten carbon footprint disclosures for imported ingredients. North Rhine-Westphalia industrial zones host extrusion-assisted milling system adoption for regional pulse processing.
France
Artisanal bakers in Paris and Lyon simultaneously reformulate traditional wheat-based recipes with chickpea and fava bean alternatives to meet clean-label consumer expectations. ANSM and DGCCRF enforce strict organic certification verification for health food retail placement. Île-de-France concentrates industrial procurement consolidation through central buying cooperatives mandating uniform protein specifications.
Netherlands
Industrial bakeries in Amsterdam and Rotterdam adopt twin-screw pre-conditioning systems that gelatinize starch while preserving native protein structures in pulse flours. EFSA novel food assessments govern ingredient introductions for emerging protein sources like mung bean. Dutch food technology clusters enable regional processors to match imported specialty flour functional performance.
United Kingdom
Health food retailers in London and Manchester emphasize organic certification tiers and allergen-free facility claims commanding premium shelf positioning. FSA allergen guidance shapes facility segregation protocols for nut-derived flour production. Midlands processing regions concentrate oat flour milling capacity serving conventional manufacturer reformulation demand.
Vegan Flour Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and milling technology dimensions. The supplier base organizes around three structural positions: diversified agricultural conglomerates with North American grain handling infrastructure, heritage stone-milling specialists commanding premium retail placement, and regional pulse processors scaling extrusion-assisted systems. Competitive moves concentrate on backward integration into regional organic supply chains and direct-to-baker digital platform development.
Within the diversified agricultural tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven supply chain control. Among heritage-process specialists, Bob's Red Mill Natural Foods and King Arthur Flour Company occupy positions defined by low-temperature milling preservation and controlled-channel specialty placement. These named entities anchor archetype boundaries without exhausting the competitor set.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Conagra Brands, Inc |
| Ardent Mills LLC |
| Bob's Red Mill Natural Foods |
| Associated British Foods plc |
| Puratos Group |
| King Arthur Flour Company |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety day lead times for organic-certified pulse shipments from Mediterranean processors to German plant-based bakeries compress margin buffers and reinforce California almond millers' premium pricing power. This inventory dynamic concentrates negotiation leverage with buyers who can document farm-level carbon footprints under tightening EU Green Deal mandates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across organic certification tiers, stone-milling heritage premiums, and volume scale discounts. Price differentiation centers on EU organic seal verification and gluten-free facility segregation protocols that command 40-60% shelf premiums in health food retail. Cost compression in almond flour runs through California water allocation restrictions and pollination cost volatility. Artisanal bakers exhibit lowest price sensitivity due to recipe-driven specification requirements, while conventional industrial manufacturers face highest pressure to reduce per-unit ingredient costs.
Supply Chain Analysis
Ninety-day organic conversion audit timelines strain inventory planning for millers pivoting from conventional grain processing. Geographic supply concentration centers on California almond processing clusters, Canadian Prairie organic oat infrastructure, and Mediterranean pulse milling zones in Turkey and Spain. Raw material dependencies rest on blanched almond supply, heritage oat varietals, and fava bean cultivation expansion. Single-source vulnerability in California water-stressed production regions threatens margin stability. Distribution feeds from miller-owned digital platforms and central buying cooperatives that bypass traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-baker procurement platforms are collapsing traditional distributor intermediation and creating winner-take-most dynamics for millers who achieve interoperability with bakery ERP systems and EU traceability disclosure protocols.
For Market Incumbents: Secure backward integration into regional organic pulse processing in North Rhine-Westphalia and Prairie Canada to defend against extrusion-assisted milling technology diffusion that erodes specialty flour premiums. Lock in three-year organic supply contracts with German plant-based bakery chains before EU Green Deal disclosure deadlines consolidate buyer leverage. For New Entrants and Emerging Players: EU organic certification fast-track programs for heritage grain varietals open white-space penetration in French artisanal segments where ANSM verification commands retail placement. Target direct-to-baker digital platforms with custom granulation specifications as the most penetrable channel, using subscription commerce integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural conglomerates seeking to divest non-core specialty milling assets amid commodity grain margin pressure. Long-term viability hinges on certification moat durability and regional sourcing cluster control. Watch EFSA novel food authorization timelines for mung bean and lupin flours as inflection signals for pulse protein expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Organic Supply | Captures margin from Canadian Prairie oat processors and Mediterranean pulse cooperatives. |
| Direct-to-Baker Digital Platform Launch | Bypasses traditional distributors for German plant-based bakery chain procurement. |
| EU Organic Certification Investment | Unlocks ANSM-enforced retail placement in French health food channels. |
| Extrusion-Assisted Milling Technology Adoption | Enables Dutch and Belgian regional processors to match imported specialty flour performance. |
| Heritage Stone-Milling Process Preservation | Commands premium shelf positioning through low-temperature protein and lipid preservation. |
Research Methodology
A spread of perspectives from specialty miller procurement directors, plant-based bakery chain supply chain managers, EU regulatory affairs consultants, and organic certification auditors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA allergen guidance documents, EFSA novel food submission databases, EU Green Deal Farm to Fork strategy disclosures, and organic certification body audit protocols. Bottom-up volume modeling triangulated against top-down value estimates.
Segmentation dimensions modeled include product type tiers, end-user procurement sophistication levels, application functional requirements, and distribution channel control structures across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated EU REACH compliance timelines and extrusion-assisted milling capacity buildout rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or California water policy stability would require recalibration. Forecasts reflect documented assumptions about organic conversion timelines and novel food authorization pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Veggie Meals Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Germany Soy Protein Market
Plant Based Food
Plant Based Pasta Market