
 Extruded Soy Products Market | 2026-2036
Extruded Soy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded Soy Products Market Foresight
REACH is repositioning the European extrusion sector toward cleaner solvent-recovery systems and tighter supply-chain documentation. Cargill, Incorporated leverages its North American crush capacity to anchor downstream extrusion economics. Archer Daniels Midland Company dominates integrated soy protein isolate production through in-house oilseed processing. Bunge Limited controls South American origination flows that feed Asian extrusion demand.
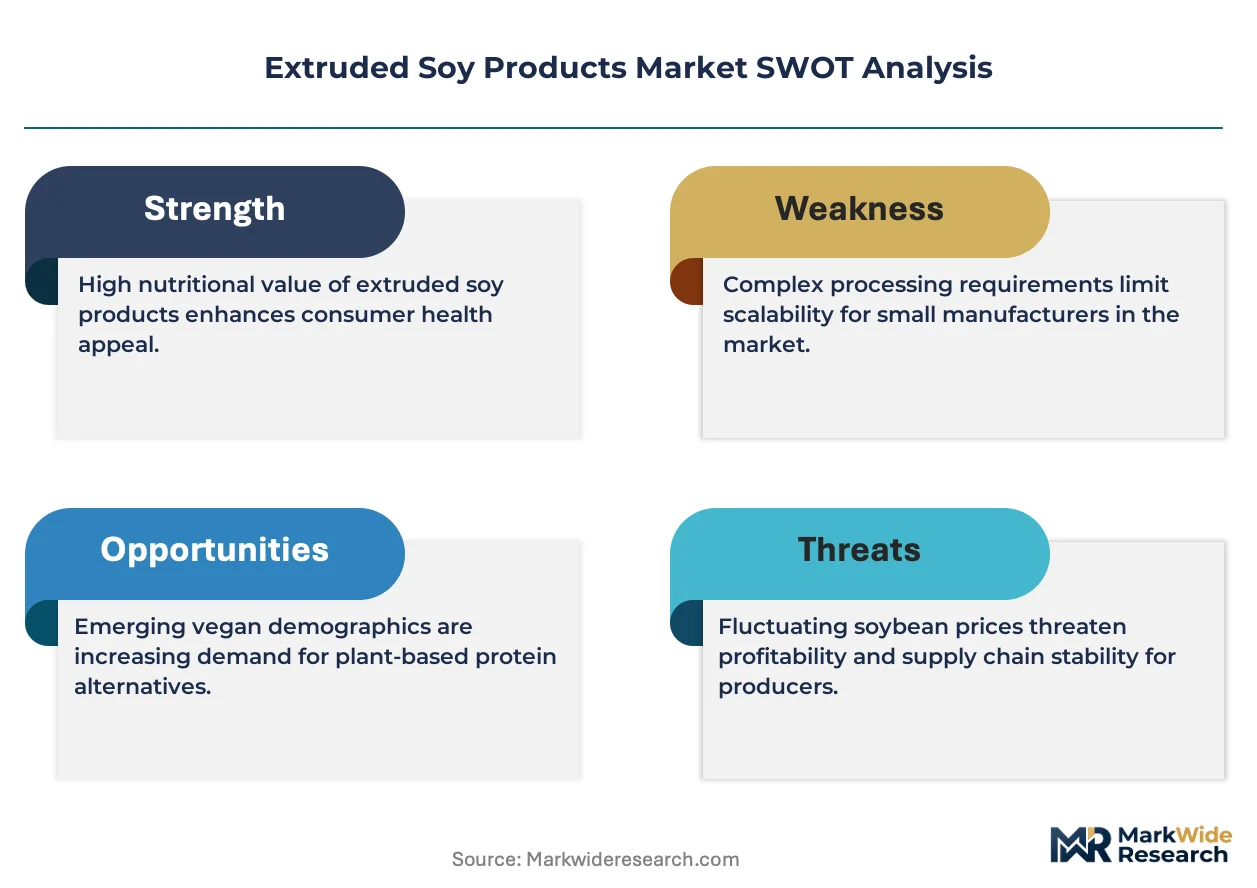
Extruded soy products are thermoplasticized soybean materials formed under high temperature, pressure, and shear through single or twin-screw extruders, yielding texturized structures with protein contents ranging from 50% to 90% depending on starting substrate. These products function primarily as functional protein matrices in meat analogues, nutritional bars, and aquafeed formulations where water absorption and fibrous texture are critical performance parameters. Soy protein isolate commands the highest margin pool due to its functional purity in premium meat alternatives, while soy nuggets represent the fastest-expanding category as Asian snack manufacturers scale production. The food industry end-use segment leads absolute volume, though sports nutrition channels are capturing disproportionate value growth through direct-to-consumer protein positioning.
FDA protein-labeling standards shape how extruded soy products qualify for nutrient-content claims in the United States, while EFSA novel-food assessments govern entry of next-generation textured formats into European commerce. China's SAMR enforces GB standards for plant-protein labeling that directly affect import eligibility and domestic formulation requirements. Stakeholders must monitor evolving protein-quality scoring methodologies across jurisdictions, as these metrics will determine which extrusion technologies and soy fractions retain formulation priority.
Market Dynamics
The EU F-Gas Regulation is forcing food processors to retire high-energy extrusion lines and adopt heat-pump-assisted or electric twin-screw systems, compressing capital planning cycles across European manufacturing.
Growth Catalysts
- Meat-alternative formulation demand:German food manufacturers are expanding extruded soy capacity to supply fibrous protein matrices for plant-based sausages and patties.
- REACH solvent-recovery mandates:Cleaner closed-loop extraction systems are qualifying European processors for preferential supply contracts with multinational food brands.
- High-moisture extrusion:This thermomechanical process is yielding juicier texturized structures that satisfy sensory benchmarks in premium meat analogues.
Market Restraints
- Soybean price volatility:Crush margin compression in Argentina and Brazil transmits directly to extruded soy input costs, destabilizing processor economics.
- Technical limitation in flavor masking:Beany off-notes in high-protein isolates constrain formulation latitude in neutral-tasting applications like dairy alternatives.
- Regulatory friction from EFSA novel-food assessments:Extended safety evaluation timelines delay commercialization of next-generation textured formats in European markets.
Strategic Opportunities
- Aquafeed application expansion:Salmon and shrimp producers in Norway are testing extruded soy protein concentrates as fishmeal replacements.
- Sports nutrition channel innovation:Direct-to-consumer protein bar brands are bypassing traditional ingredient distributors to source textured soy directly.
- China's dual carbon goals:Domestic processors scaling low-carbon extrusion capacity qualify for state subsidies and preferential grid electricity rates.
Industry Challenges
- Extrusion engineering talent scarcity:Food science programs produce few specialists in screw-profile design and die-flow simulation.
- Capex intensity for heat-pump retrofits:Replacing steam-injection systems with electric alternatives demands multi-year payback periods.
- ISO 22000 certification timelines:New entrants face 12-18 month validation cycles before qualifying for major food manufacturer approved-supplier lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded Soy Products Market |
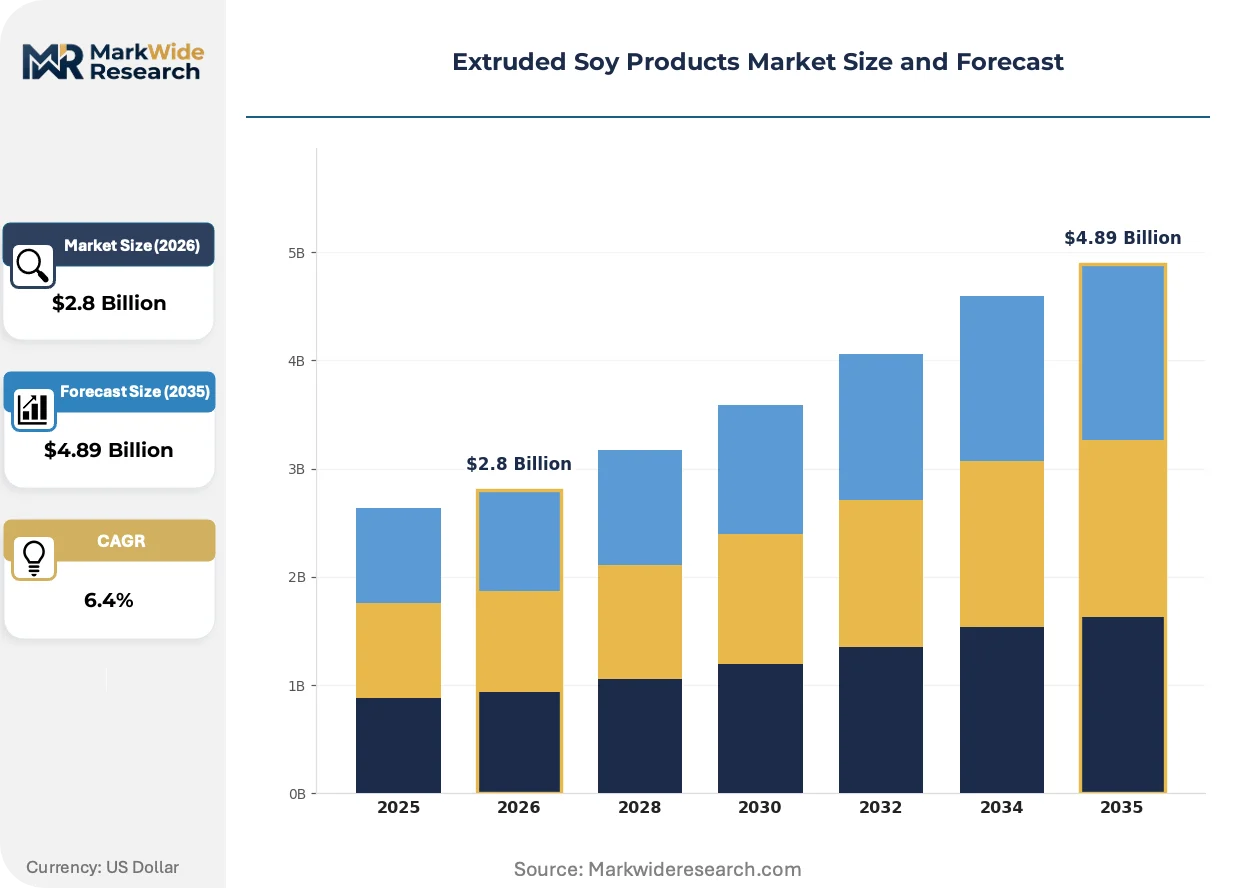
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein Isolate, Soy Flour, Soy Protein Concentrate, Soy Nuggets End User: Food Industry, Feed Industry, Sports Nutrition, Dietary Supplements Application: Snacks, Meat Alternatives, Protein Supplements, Bakery Products Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Roquette Frères, CHS Inc., MGP Ingredients, Bunge Limited, Sonic Biochem, BENEO, Crown Soya Protein Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded Soy Products Market Shifts & Advancements
Thermomechanical processing advances are converging with regulatory energy mandates to reshape equipment procurement and product positioning simultaneously across food and feed channels.
High-moisture extrusion (HME) is unifying texturization and hydration into a single continuous operation, eliminating the intermediate drying stage. European meat-analogue manufacturers are adopting HME lines at replacement cycle acceleration. This unifying architecture is compressing capital footprints and enabling on-site production at brand-owned facilities rather than centralized ingredient plants.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in extrusion cooling systems from 2030, compelling equipment retrofits. Food processors in Germany and the Netherlands are front-loading heat-pump installations to secure engineering capacity. Soy protein isolate production faces the steepest compliance cost given its energy-intensive purification stages.
Ingredient procurement is consolidating through long-term offtake agreements rather than spot-market purchasing. Sports nutrition brands are locking in three-year supply contracts directly with Brazilian crush-and-extrusion complexes. This pattern is most visible in North American direct-to-consumer channels where formulation consistency commands premium positioning.
Extruded Soy Products Market Segmentation
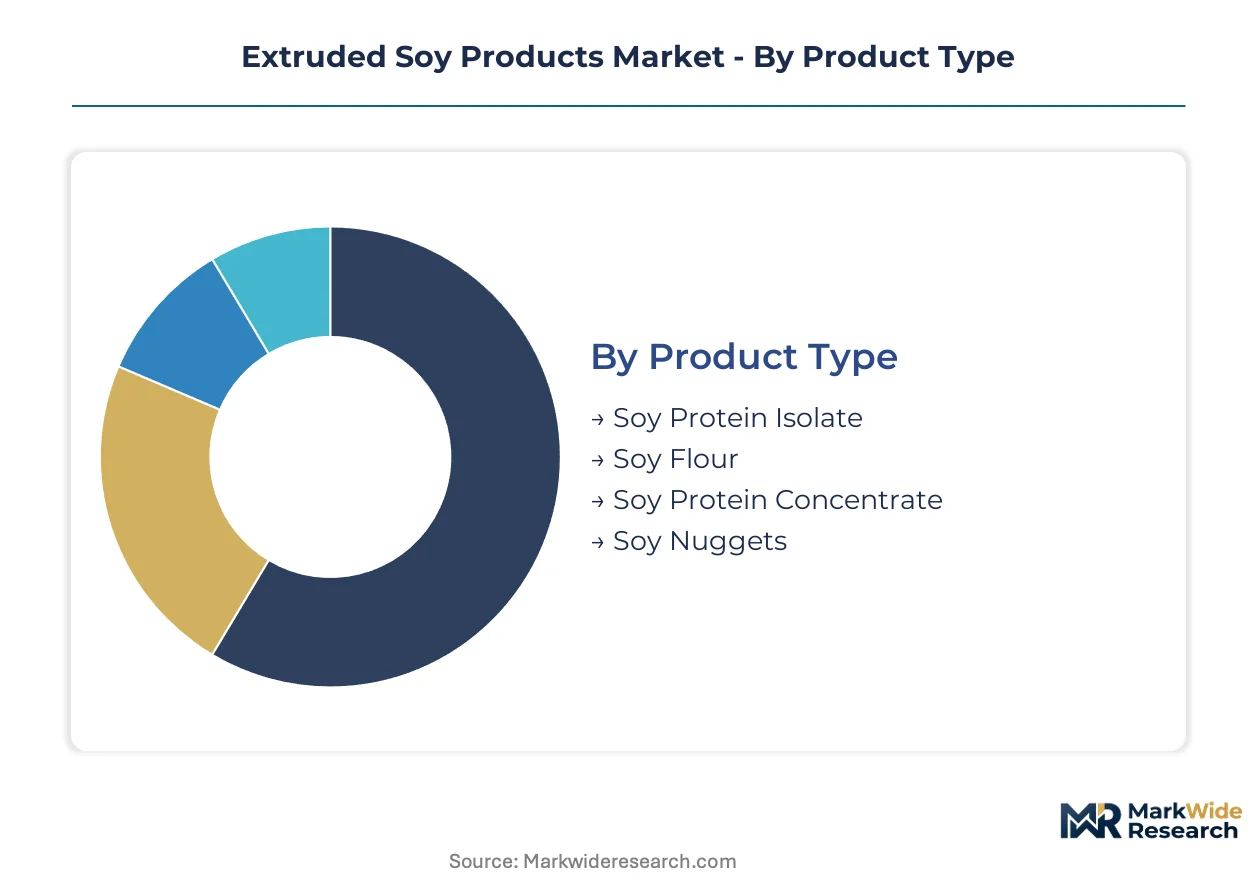
Extruded soy products fragment across protein purity grades, end-use specifications, and channel economics. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Volume concentrates in commodity-grade fractions while premium capture accrues to high-purity isolates with functional certification.
- Soy Protein Isolate:Refined to 90%+ protein content through alkaline extraction and isoelectric precipitation. European meat-analogue manufacturers pay premium multiples for EFSA-compliant isolates with documented allergen thresholds. Soy protein isolate commands the highest margin pool due to its functional purity in premium meat alternatives.
- Soy Nuggets:Texturized chunks formed through thermoplastic extrusion of defatted flour with 50-70% protein content. Asian snack manufacturers in China and Thailand are scaling automated nugget production lines for both retail packaged goods and foodservice distribution. Soy nuggets represent the fastest-expanding category as Asian snack manufacturers scale production.
- Soy Protein Concentrate:Produced through aqueous alcohol washing to reach 65-72% protein while retaining some insoluble fiber. Norwegian aquafeed formulators are qualifying concentrates as fishmeal replacements in salmon diets.
- Soy Flour:Full-fat or defatted milled soybean with 40-50% protein, serving as cost-extender in bakery and feed applications. Brazilian crush facilities ship containerized flour to West African processors for bread fortification programs.
Today's leader: Soy protein isolate. Tomorrow's challenger: Soy nuggets.
End User:
Application maturity separates established food manufacturing from emerging direct-to-consumer channels with divergent procurement patterns.
- Food Industry:Integrated meat processors and plant-based brands source textured soy for analogue formulations requiring fibrous bite and water-binding capacity. German extrusion capacity expansions are targeting this segment specifically.
- Sports Nutrition:Direct-to-consumer protein bar and powder brands are bypassing traditional distributors to contract directly with Brazilian extrusion complexes for formulation consistency. Sports nutrition channels are capturing disproportionate value growth through direct-to-consumer protein positioning.
- Feed Industry:Compound feed manufacturers incorporate extruded soy concentrates into poultry and aquaculture rations for amino acid density. Shrimp producers in Vietnam are testing high-moisture extruded concentrates as partial fishmeal substitutes.
- Dietary Supplements:Capsule and tablet manufacturers require spray-dried isolates with heavy metal certification below Prop 65 thresholds for California distribution.
Established demand anchors food industry procurement. Sports nutrition is climbing the fastest as channel disintermediation accelerates.
Application:
Functional requirements range from structural texturization in meat analogues to dispersibility in beverage systems.
- Meat Alternatives:High-moisture extrusion yields fibrous matrices that replicate muscle tissue in plant-based sausages and patties. European manufacturers are replacing steam-injection lines with heat-pump-assisted systems to meet F-Gas Regulation deadlines.
- Snacks:Puffed and textured nuggets serve as protein fortification vehicles in Asian savory snack categories. Chinese processors are scaling low-carbon extrusion capacity to qualify for state dual-carbon subsidies.
- Protein Supplements:Instantized isolates require agglomeration treatment for cold-water dispersibility in ready-to-mix powders.
- Bakery Products:Defatted flour extends wheat dough while contributing emulsification through retained lecithin fractions.
Meat alternatives dominate absolute volume. Snacks are gaining share fastest through Asian market expansion.
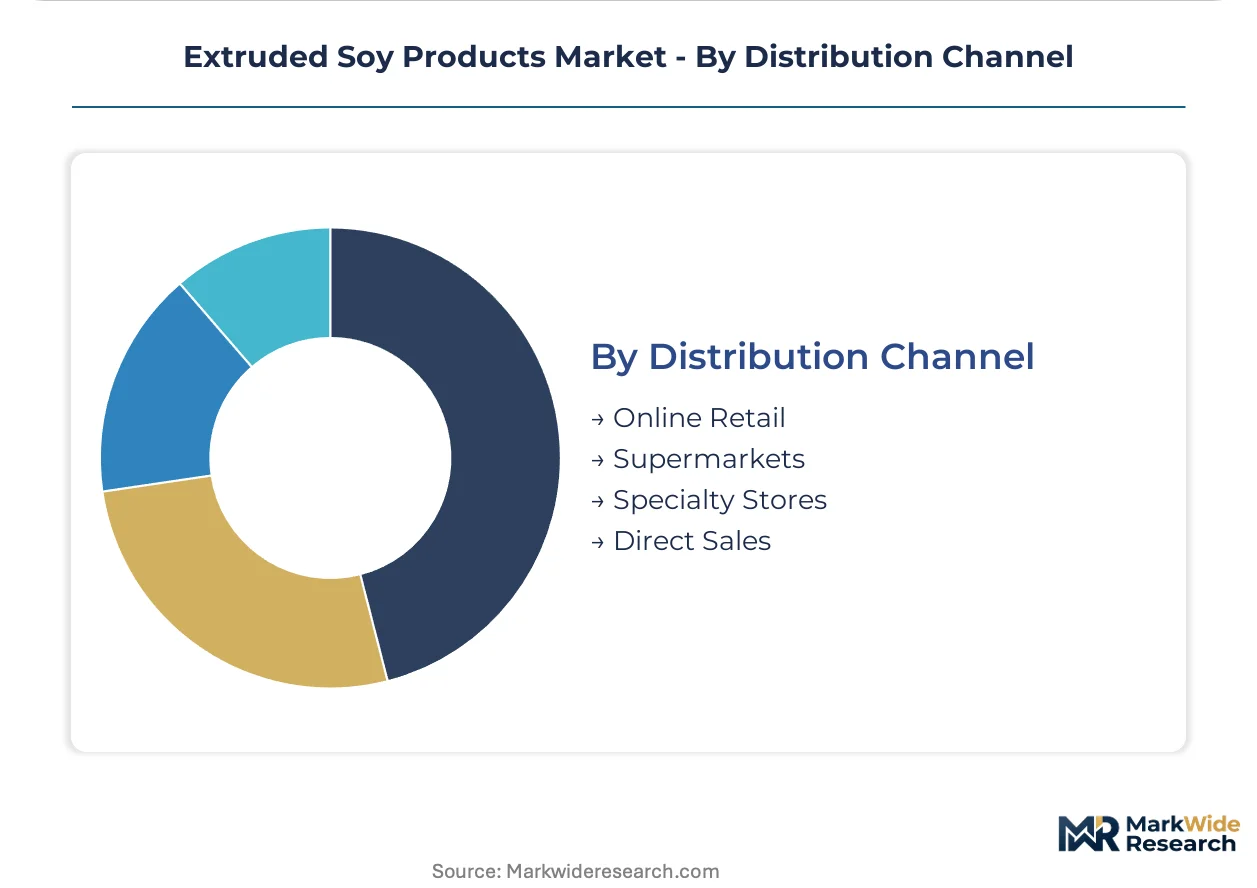
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and certification documentation needs.
- Direct Sales:Major food manufacturers negotiate multi-year offtake agreements with crush-and-extrusion complexes for volume certainty and traceability documentation. Sports nutrition brands are locking in three-year supply contracts directly with Brazilian processors.
- Supermarkets:Retail packaged textured soy for home cooking consolidates through private-label programs with centralized procurement.
- Specialty Stores:Organic and non-GMO certified isolates command shelf-space premiums in health-focused retail channels.
- Online Retail:E-commerce platforms aggregate small-batch specialty extruded products for niche dietary segments.
Direct sales anchors industrial volume. Online retail shows steepest expansion trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion engineering talent clusters in Germany, Brazil, and China anchor regional capacity expansion. Regulatory energy mandates and protein formulation demand are reshaping investment geography.
China
Domestic processors in Shandong and Jiangsu provinces are scaling textured soy protein output for food and feed applications. SAMR enforces GB standards for plant-protein labeling that directly affect import eligibility. Qingdao extrusion complexes qualify for state dual-carbon subsidies through low-carbon capacity installations.
Germany
Food manufacturers in Bavaria and North Rhine-Westphalia are expanding extruded soy capacity for meat-alternative formulations. The EU F-Gas Regulation is accelerating investment in heat-pump-assisted twin-screw systems. Cologne engineering clusters are retrofitting steam-injection lines before the 2030 refrigerant ban deadline.
Brazil
Crush-and-extrusion complexes in Mato Grosso and Paraná are locking in three-year supply contracts with North American sports nutrition brands. Crush margin volatility in Argentina transmits directly to extruded soy input costs. Santos port infrastructure is consolidating containerized flour shipments to West African processors.
United States
FDA protein-labeling standards shape how extruded soy products qualify for nutrient-content claims in meat analogue formulations. Illinois and Iowa processing corridors leverage North American crush capacity to anchor downstream extrusion economics. Chicago-based ingredient distributors are disintermediated by direct-to-consumer protein bar brands.
Norway
Salmon and shrimp producers in Bergen and Trondheim are testing extruded soy protein concentrates as fishmeal replacements. EFSA novel-food assessments govern entry of next-generation textured formats into European commerce. Stavanger aquafeed clusters are qualifying concentrate suppliers through extended safety evaluation protocols.
Extruded Soy Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across protein purity grades and channel economics. The vendor base separates into three strategic archetypes: integrated oilseed processors controlling origination flows, specialty ingredient formulators serving premium meat-analogue manufacturers, and regional extrusion contractors supplying snack and feed channels. Dominant competitive moves include backward integration into crush capacity and multi-year offtake agreements that bypass traditional distribution.
Within the integrated processor tier, Archer Daniels Midland Company exemplifies in-house oilseed-to-isolate production architecture, while Cargill, Incorporated anchors North American crush economics. Bunge Limited occupies a position controlling South American origination flows that feed Asian extrusion demand.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Roquette Frères |
| CHS Inc. |
| MGP Ingredients |
| Bunge Limited |
| Sonic Biochem |
| BENEO |
| Crown Soya Protein Group |
| Others |
Supply & Pricing Matrix
Soybean crush margins in Argentina and Brazil transmit directly into extruded soy pricing tiers, with commodity-grade flour absorbing volatility at the economy level while EFSA-compliant isolates command premium multiples through certification documentation.
Pricing Analysis
Unbundled spot purchasing for soy flour and concentrates exposes buyers to crush margin swings, while bundled long-term offtake agreements for protein isolates lock in formulation consistency. Price differentiation rests on EFSA novel-food certification and ISO 22000 validation, with European meat-analogue manufacturers least sensitive and Asian snack producers most sensitive to input cost shifts. Cost compression in commodity-grade fractions is intensifying as Brazilian crush capacity expands.
Supply Chain Analysis
Direct-to-manufacturer channels handle volume demand from integrated food processors, while distributor networks serve smaller compound feed operations. Supply concentrates in Brazil, China, and Germany, with raw material flows drawing from Mato Grosso soy origination, Shandong crushing corridors, and North Rhine-Westphalia extrusion clusters. Single-source vulnerability runs through Santos port infrastructure for West African flour shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation operates as a regulatory compounder, forcing heat-pump retrofits that consolidate procurement power among capital-rich processors capable of front-loading compliance investments.
For Market Incumbents: Acquire heat-pump engineering capacity and certified isolate production lines to defend against emerging pure-play specialists. Backward integration into Brazilian crush assets secures origination control, while REACH-compliant solvent-recovery systems qualify for multinational brand supply contracts.
For New Entrants and Emerging Players: China's dual carbon goals in Shandong and Jiangsu provinces open a window for low-carbon extrusion capacity qualifying for state grid subsidies. Target sports nutrition direct-to-consumer channels with instantized isolate formulations, leveraging e-commerce subscription models to bypass established distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 22000 certification timelines stretch 12-18 months and extrusion engineering talent scarcity constrains expansion. Mid-cap specialists with captive soy origination and EFSA-compliant isolate capacity present viable acquisition targets. Monitor EFSA novel-food assessment throughput as the signal indicating premium tier capacity release.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Retrofit Investment | EU F-Gas Regulation compliance secures manufacturing continuity beyond the 2030 refrigerant ban deadline. |
| Long-Term Offtake Agreement | Three-year contracts with Brazilian crush-and-extrusion complexes anchor formulation consistency for sports nutrition brands. |
| EFSA Novel-Food Certification | Documented safety evaluation qualifies next-generation textured formats for European meat-analogue formulations. |
| Backward Integration into Crush | Captive soy origination in Mato Grosso insulates processor economics from Argentine margin volatility. |
| Direct-to-Consumer Channel Launch | E-commerce subscription models bypass Chicago-based ingredient distributors for protein bar brands. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with extrusion engineering directors, procurement leads at meat-analogue manufacturers, aquafeed formulators in Norway, and sports nutrition brand operators combined with secondary validation from FDA protein-labeling guidance, EFSA novel-food assessment databases, SAMR GB standards documentation, and customs trade flow records.
Input-output matrices map soy origination through crush, extrusion, and end-use application across the projection horizon. Segmentation dimensions include protein purity grade, end-user industry, functional application, and distribution channel structure. CAGRs derive from elasticity-adjusted demand curves incorporating regulatory energy mandate compliance costs and protein-quality scoring methodology evolution.
Revisions become necessary when EFSA assessment timelines extend, F-Gas Regulation enforcement intensifies, or soybean crush margins in South America destabilize beyond modeled bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
North America Tofu Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Soy Protein Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Plant-Based Chorizo Market