
 Plant-Based Milk Alternatives Market | 2026-2036
Plant-Based Milk Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Milk Alternatives Market Insights
EU Green Deal is restructuring capital allocation for European oat and pea protein processors. Danone S.A. leverages its specialized nutrition infrastructure to sustain clinical-grade positioning. Blue Diamond Growers anchors North American almond sourcing through cooperative grower networks. Oatly Group AB competes on foodservice exclusivity in premium café channels.
Plant-based milk alternatives comprise aqueous extracts of oilseeds, cereals, or legumes formulated to emulate the functional properties of bovine milk, typically achieving protein contents between 0.5% and 3.5% and requiring homogenization and ultra-high-temperature processing for shelf stability. Their primary commercial purpose is to serve consumers with lactose intolerance, milk protein allergies, or dietary preferences excluding animal products. Almond milk occupies the largest volume share among product types but faces water intensity scrutiny in California growing regions. Oat milk registers the fastest expansion trajectory, propelled by neutral flavor profiles and lower allergenicity in foodservice applications. Tetra Packs dominate packaging type preferences due to ambient distribution economics and aseptic filling compatibility.
EFSA governs novel food approvals for emerging protein sources entering European formulations, while FDA maintains standards of identity disputes that constrain labeling conventions in the United States. REACH compliance adds formulation testing burdens for imported fortification additives and stabilizer compounds. Stakeholders must monitor evolving protein content thresholds as regulatory bodies redefine permissible nutritional claims across jurisdictions.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is redirecting agricultural subsidy flows toward sustainable protein crops, forcing processors to reconfigure sourcing networks and reformulate product lines around oat and pea protein bases.
Growth Catalysts
- EU Green Deal subsidy reallocation:European processors gain capital access for oat and pea protein infrastructure expansion. The Farm to Fork Strategy accelerates crop transition timelines.
- Specialty coffee chain procurement:Barista-grade oat formulations anchor bulk procurement contracts from premium café channels. Foodservice exclusivity agreements lock in volume commitments.
- Germany discounter private-label expansion:German retail channels compress branded shelf space while expanding own-brand plant-based milk SKUs. Discounter penetration drives category normalization.
Market Restraints
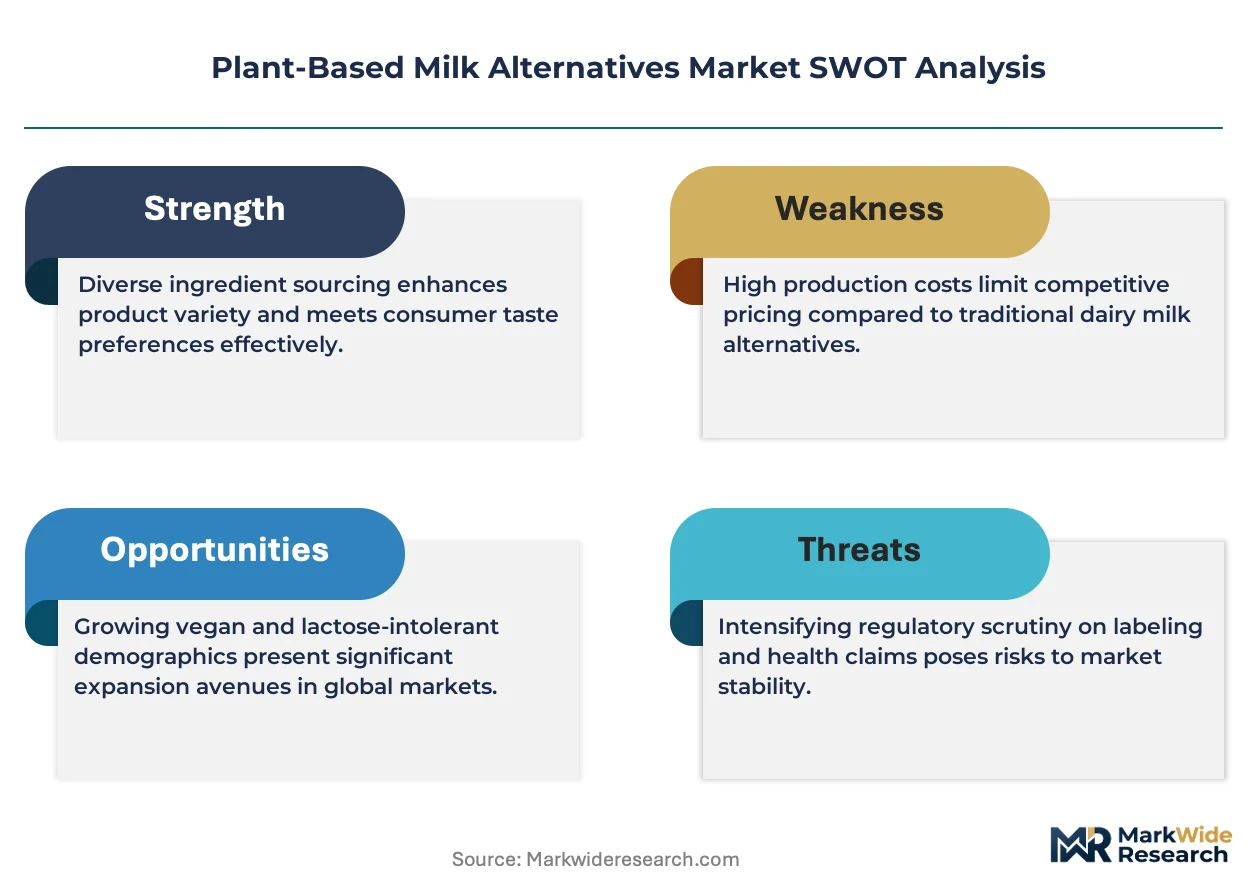
- California almond water intensity:Almond milk production faces scrutiny over groundwater depletion in drought-prone growing regions. Water cost volatility threatens margin stability.
- FDA standards of identity disputes:Labeling conventions for plant-based milk alternatives remain contested in United States jurisdiction. Regulatory friction constrains marketing terminology.
- Protein content threshold uncertainty:EFSA and FDA divergence on permissible nutritional claims creates formulation compliance complexity. Fortification additive approvals vary by geography.
Strategic Opportunities
- Underpenetrated German foodservice:Premium café channel density in Germany lags Nordic benchmarks. Barista-grade oat exclusivity agreements offer first-mover positioning.
- REACH-compliant stabilizer innovation:European formulation testing burdens for imported additives create demand for locally sourced stabilizer compounds. Regional supply chain localization yields compliance advantage.
- Tetra Pack aseptic filling expansion:Ambient distribution economics favor shelf-stable formats in convenience retail. Packaging technology convergence with plant-based substrates enables extended distribution reach.
Industry Challenges
- Homogenization and UHT processing capex:Shelf stability requirements demand capital-intensive ultra-high-temperature infrastructure. Smaller processors face equipment financing barriers.
- Novel food approval timelines:EFSA novel food pathways for emerging protein sources extend commercialization cycles. Emerging legume and cereal bases face multi-year regulatory clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Milk Alternatives Market |
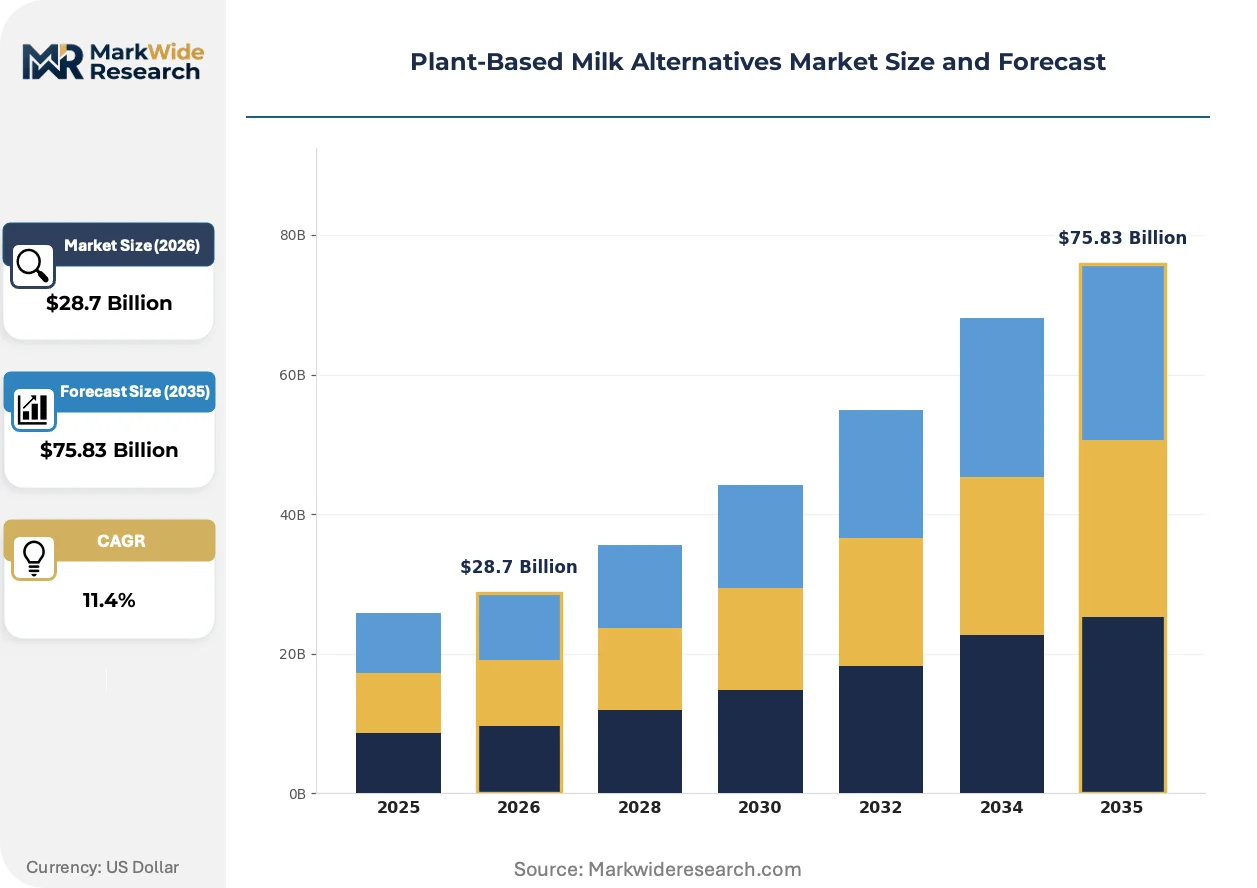
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Foodservice Packaging Type: Tetra Packs, Bottles, Cans, Pouches End User: Households, Restaurants, Cafes, Food Manufacturers |
| Companies Covered | Danone S.A., Blue Diamond Growers, Oatly Group AB, SunOpta Inc., Hain Celestial Group, Vitasoy International Holdings Ltd, Archer-Daniels-Midland Company, Califia Farms, Earth’s Own Food Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Milk Alternatives Market Trends and Innovations
Barista-grade oat formulation technology is compressing the performance gap between plant-based and dairy milk in foodservice applications, while regulatory divergence between EFSA and FDA is fragmenting global product development roadmaps.
Enzymatic hydrolysis of oat starches is rewriting the functional performance of barista-grade formulations. Specialty coffee chains in Germany and Nordic markets are adopting these enzymatically treated oat bases at accelerated procurement cycles. The technology is rewriting the competitive threshold for foodservice exclusivity agreements, compressing the window for proprietary formulation differentiation.
EFSA novel food approval pathways for emerging protein sources are tightening entry requirements for European formulations. Industrial consequence includes extended commercialization timelines for fava bean and lupin-based alternatives. Protein-fortified variants targeting clinical nutrition segments face the most pronounced compliance burdens, with processors accelerating REACH pre-registration for stabilizer compounds.
Café channel procurement is consolidating around single-source oat suppliers with dedicated barista-grade production lines. Premium foodservice accounts in Germany and metropolitan Nordic clusters are displacing multi-source procurement with exclusive supply agreements. This concentration is most visible in Berlin and Copenhagen specialty coffee density zones, where roaster-owned café chains vertically integrate into oat milk supply.
Plant-Based Milk Alternatives Market Segmentation
Plant-based milk alternatives fragment across formulation bases, procurement channels, and end-use specifications. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Formulation chemistry and protein extraction methods define functional performance across beverage and food manufacturing applications.
- Almond Milk:Cold-pressed almond extracts yield 0.5-1.0% protein content with pronounced nut-forward flavor profiles. California's Central Valley growers supply 80% of global almond inputs, exposing processors to water cost volatility from sustained drought conditions.
- Oat Milk:Enzymatically hydrolyzed oat starches achieve 2.0-3.5% protein with neutral taste and superior foam stability. Specialty coffee chains in Germany and Nordic metropolitan clusters anchor procurement through exclusive barista-grade supply agreements.
- Soy Milk:Highest native protein concentration among mainstream alternatives at 3.5-4.0%, requiring isoflavone stabilization and beany off-note masking.
- Coconut Milk:High-fat aqueous emulsion from pressed coconut meat, dominant in Southeast Asian formulations and dairy-free cooking applications.
Almond milk leads on scale; oat milk leads on momentum.
Distribution Channel:
Channel economics diverge sharply between ambient shelf-stable logistics and cold-chain fresh distribution requirements.
- Supermarkets:Mass-market retail commands volume concentration through private-label SKUs, particularly in German discounter channels where branded shelf space compression accelerates category normalization.
- Foodservice:Barista-grade oat formulations lock in premium pricing through café exclusivity agreements. Berlin and Copenhagen roaster-owned chains displace multi-source procurement with single-supplier contracts.
- Online Retail:Direct-to-consumer subscriptions and bulk pantry formats bypass retail slotting fees, enabling niche protein-fortified variants.
- Health Food Stores:Curated organic and allergen-free positioning targets clinical nutrition and pediatric segments with higher per-unit margins.
Supermarkets dominate absolute volume; foodservice captures value expansion.
Packaging Type:
Packaging technology governs shelf stability duration, distribution radius, and aseptic processing capital requirements.
- Tetra Packs:Multi-layer aseptic cartons enable 12-month ambient shelf life with minimal refrigeration infrastructure. Tetra Pak filling equipment convergence with plant-based substrates extends distribution reach into convenience retail.
- Bottles:PET and HDPE formats suit refrigerated fresh segments with shorter shelf life and regional distribution constraints.
- Cans:Metal packaging for barista-grade concentrates and foodservice bulk formats requiring thermal stability.
- Pouches:Flexible film reduces material cost and shipping weight for single-serve and travel-portable applications.
Tetra Packs lead on scale; pouches gain share fastest in on-the-go segments.
End User:
End-use specifications range from household beverage consumption to industrial ingredient functionality in manufactured foods.
- Households:Retail-packaged consumption for direct drinking, cereal, and home cooking applications. Lactose intolerance and milk protein allergy prevalence drives repeat purchase loyalty.
- Cafes:Foam stability, latte art performance, and neutral flavor compatibility with espresso define procurement criteria. Enzymatic hydrolysis technology compresses the performance gap with dairy milk.
- Restaurants:Bulk formats for culinary applications including sauces, soups, and dairy-free dessert preparations.
- Food Manufacturers:Industrial ingredient procurement for plant-based yogurt, ice cream, and bakery applications requiring standardized protein content and emulsion stability.
Households anchor volume; cafes drive premium formulation innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oat and almond processing talent clusters in California, Germany, and Sweden anchor the industry's geographic footprint. These workforce concentrations determine where barista-grade formulation expertise and cooperative grower networks concentrate.
United States
California's Central Valley growers supply the majority of global almond inputs, exposing processors to sustained drought-driven water cost volatility. FDA standards of identity disputes constrain labeling conventions for plant-based milk alternatives in interstate commerce. Los Angeles and San Francisco specialty coffee chains anchor West Coast procurement of barista-grade oat formulations.
Germany
Discounter private-label expansion compresses branded shelf space while accelerating category normalization in mass retail channels. EU Green Deal subsidy reallocation under the Farm to Fork Strategy accelerates crop transition timelines toward sustainable protein sources. Berlin roaster-owned café chains displace multi-source procurement with exclusive oat milk supply agreements.
Sweden
Nordic metropolitan clusters register the highest café channel density per capita, driving premium foodservice volume commitments. EFSA novel food approval pathways govern emerging protein source entry into European formulations. Stockholm and Copenhagen specialty coffee density zones concentrate enzymatically hydrolyzed oat starch procurement.
China
Soy milk consumption traditions create established infrastructure for aqueous extraction and UHT processing capacity expansion. SAMR labeling standards and GB food safety regulations shape permissible nutritional claims and fortification additive approvals. Yangtze River Delta processing hubs concentrate industrial-scale production for domestic and export markets.
Australia
Almond cultivation in the Murray-Darling Basin supplies regional processors with proximity advantages to Asian export markets. TGA-equivalent state-level food standards govern allergen labeling and novel ingredient introductions. Melbourne and Sydney specialty coffee scenes drive barista-grade formulation adoption in Asia-Pacific foodservice channels.
Plant-Based Milk Alternatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, sourcing, and channel strategies. The vendor base stratifies into three tiers: multinational nutrition conglomerates with diversified beverage portfolios, cooperative-backed agricultural processors with captive raw material supply, and venture-scaled oat specialists with foodservice exclusivity positioning. Dominant competitive moves include backward integration into oat milling and enzymatic processing infrastructure, plus exclusive supply agreements locking premium café channels.
Within the cooperative-backed agricultural tier, Blue Diamond Growers represents grower-network aggregation models. Among venture-scaled oat specialists, Oatly Group AB exemplifies foodservice-first positioning. On the multinational nutrition vector, Danone S.A. occupies a diversified conglomerate position leveraging specialized nutrition infrastructure.
| Leading Market Players |
|---|
| Danone S.A. |
| Blue Diamond Growers |
| Oatly Group AB |
| SunOpta Inc. |
| Hain Celestial Group |
| Vitasoy International Holdings Ltd |
| Archer-Daniels-Midland Company |
| Califia Farms |
| Earth's Own Food Company Inc. |
| Others |
Pricing and Supply Chain Analysis
California almond water cost indices cascade through formulation economics, compressing margin structures for processors dependent on Central Valley supply while rewarding oat and pea protein alternatives with more stable input cost profiles. Three-tier pricing structure across premium, standard, and economy levels stratifies according to barista-grade certification, organic sourcing credentials, and private-label contract volumes.
Pricing Analysis
Bundled foodservice supply agreements commanding exclusivity premiums diverge sharply from unbundled retail spot purchasing. Premium-mid-economy pricing differentiation rests on enzymatic hydrolysis certification, EU organic accreditation, and Tetra Pack aseptic filling infrastructure. Cost compression in German discounter channels is intensifying because private-label expansion crowds branded shelf space. Foodservice buyers exhibit lowest price sensitivity due to locked-in volume commitments, while mass-market households face highest sensitivity amid inflation-driven trade-down behavior.
Supply Chain Analysis
REACH-compliant additive certification gates European formulation entry, forcing stabilizer compound localization and extending supplier qualification timelines. Raw material sourcing draws from California almonds, Nordic oats, and Yangtze River Delta soy processing hubs. Dependencies center on enzymatic processing enzymes, multi-layer aseptic carton substrates, and fortification premix compounds. Single-source vulnerability concentrates in California groundwater-restricted almond orchards. Distribution runs through ambient shelf-stable logistics networks anchored by Tetra Pak filling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork Strategy operates as a regulatory compounder, accelerating subsidy reallocation toward sustainable protein crops and reshaping competitive positioning for processors with oat and pea infrastructure.
For Market Incumbents: Hedge against California water cost volatility by accelerating backward integration into Nordic oat milling capacity. Lock in multi-year foodservice exclusivity agreements before enzymatic hydrolysis technology commoditizes. Prioritize REACH pre-registration for stabilizer compounds to defend European formulation access against emerging legume-based entrants.
For New Entrants and Emerging Players: Launch via direct-to-subscription models targeting protein-fortified clinical nutrition segments underserved by mass-market brands. Exploit underpenetrated German café channel density relative to Nordic benchmarks. Pursue white-label manufacturing partnerships with discounter private-label programs to bypass branded slotting fee barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where enzymatic processing capability scarcity intersects with foodservice exclusivity contract backlogs. Long-term viability favors processors with captive oat supply and barista-grade certification infrastructure. Target acquisition archetype: regional oat specialists with Berlin or Copenhagen café channel lock-in. Watch EFSA novel food approval timelines for fava bean and lupin protein sources as inflection indicators for next-generation formulation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Milling | Captive supply secures margin control against Nordic processor concentration. |
| Barista-Grade Certification Investment | Enzymatic hydrolysis capability unlocks premium foodservice exclusivity agreements. |
| REACH-Compliant Stabilizer Localization | Regional additive sourcing accelerates European formulation approval cycles. |
| Discounter Private-Label Partnership | Volume commitments offset branded shelf space compression in German retail. |
| Novel Protein Source Pipeline Development | EFSA pre-submission for fava bean and lupin bases hedges oat supply concentration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with oat processors, specialty coffee chain procurement directors, German discounter category buyers, and EU regulatory affairs specialists with secondary validation. Secondary sources encompassed EFSA novel food submission databases, EU Farm to Fork Strategy implementation reports, California water board allocation records, and Tetra Pak processing equipment deployment filings. Bottom-up volume modeling from formulation base outputs and top-down macroeconomic anchoring were cross-referenced for triangulation.
Comparable historical periods anchored projection parameters across the analysis window, with segmentation dimensions spanning formulation chemistry, distribution channel economics, packaging technology, and end-use specifications. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts and crop transition timelines. Industry-specific forecast inputs included EU subsidy reallocation schedules and enzymatic hydrolysis patent expiration trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended EFSA approval delays or California drought intensification. Model outputs reflect documented assumptions on oat protein content thresholds and foodservice contract renewal rates. A model refresh is warranted upon material change in EU Green Deal implementation pace or FDA standards of identity resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Packed Vegan Foods Market