
 Europe Pea Protein Market | 2026-2036
Europe Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pea Protein Market Foresight
Foodservice distribution is tilting toward direct-to-manufacturer supply contracts as brands seek traceability and shorter ingredient chains. Roquette Frères anchors French production capacity with backward integration into yellow pea sourcing across the Picardy region. Cosucra Groupe Warcoing differentiates through wet-fractionation expertise that preserves protein functionality for meat-alternative applications. Emsland Group competes on modified starch and protein blends, extending its ingredient portfolio into textured formats for European food processors.
Pea protein denotes the protein fraction extracted from Pisum sativum seeds through dry or wet milling, followed by alkaline solubilization and isoelectric precipitation, yielding products with protein content ranging from 50% in flour to 85-90% in isolate grades. Its primary commercial purpose centers on emulsification, gelation, and water-binding in plant-based foods, nutritional powders, and feed formulations. Isolate commands the premium tier in meat-alternative applications where neutral flavor and high solubility justify formulation costs, while textured pea protein is gaining fastest in European foodservice channels supplying quick-service restaurant chains. Concentrate occupies the mid-tier for nutritional supplements targeting fitness enthusiasts, with margin pools deepest where brands combine isolate purity with clean-label positioning.
The European Food Safety Authority governs novel food approvals and protein health claims under EU regulation, while REACH compliance shapes solvent and processing-chemical disclosure for extraction facilities. EFSA's evolving stance on protein quality scores and amino acid profiling directly influences label permissibility and consumer-facing marketing in member states. Stakeholders must monitor whether the EU Green Deal's carbon-border adjustments will reshape sourcing economics for imported versus European-grown yellow peas.
Market Dynamics
Ingredient clustering around Rotterdam and Wageningen is compressing formulation cycle times for European food manufacturers, while the EU Green Deal's carbon-border adjustments threaten to reprice imported versus domestic yellow pea supplies.
Growth Catalysts
- EU Green Deal:Carbon-border adjustment mechanisms incentivize regional sourcing of yellow peas, strengthening domestic protein extraction economics across member states.
- Plant-based meat alternatives:German and French foodservice channels absorb rising isolate volumes as quick-service restaurant chains reformulate core menu items.
- Wet-fractionation technology:Advanced aqueous processing preserves protein functionality for meat-analogue applications, expanding addressable formulation windows.
Market Restraints
- Input cost volatility:Yellow pea prices swing with Black Sea grain corridor disruptions and Canadian harvest variability, squeezing margin pools for isolate producers.
- Supply concentration risk:Picardy region sourcing dominance for Roquette Frères creates geographic single-point vulnerability for French protein security.
- Regulatory friction:EFSA's evolving protein quality scoring methodology delays health claim approvals, constraining consumer-facing marketing permissibility.
Strategic Opportunities
- Underpenetrated geographies:Polish and Romanian food processing sectors offer formulation partnership entry points as regional meat-alternative production scales.
- Regulatory tailwind:F-Gas Regulation mandates accelerate equipment replacement cycles, opening retrofit contracts for low-emission extraction facilities.
- Technology convergence:Precision fermentation and pea protein hybrid formulations unlock novel texture profiles for whole-muscle analogue applications.
Industry Challenges
- Skill scarcity:Food protein chemists with wet-fractionation expertise command premium compensation, constraining facility expansion timelines.
- Capex intensity:Isoelectric precipitation lines and spray-drying towers require substantial upfront investment, limiting mid-tier processor participation.
- Certification complexity:REACH compliance documentation for extraction solvents extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pea Protein Market |
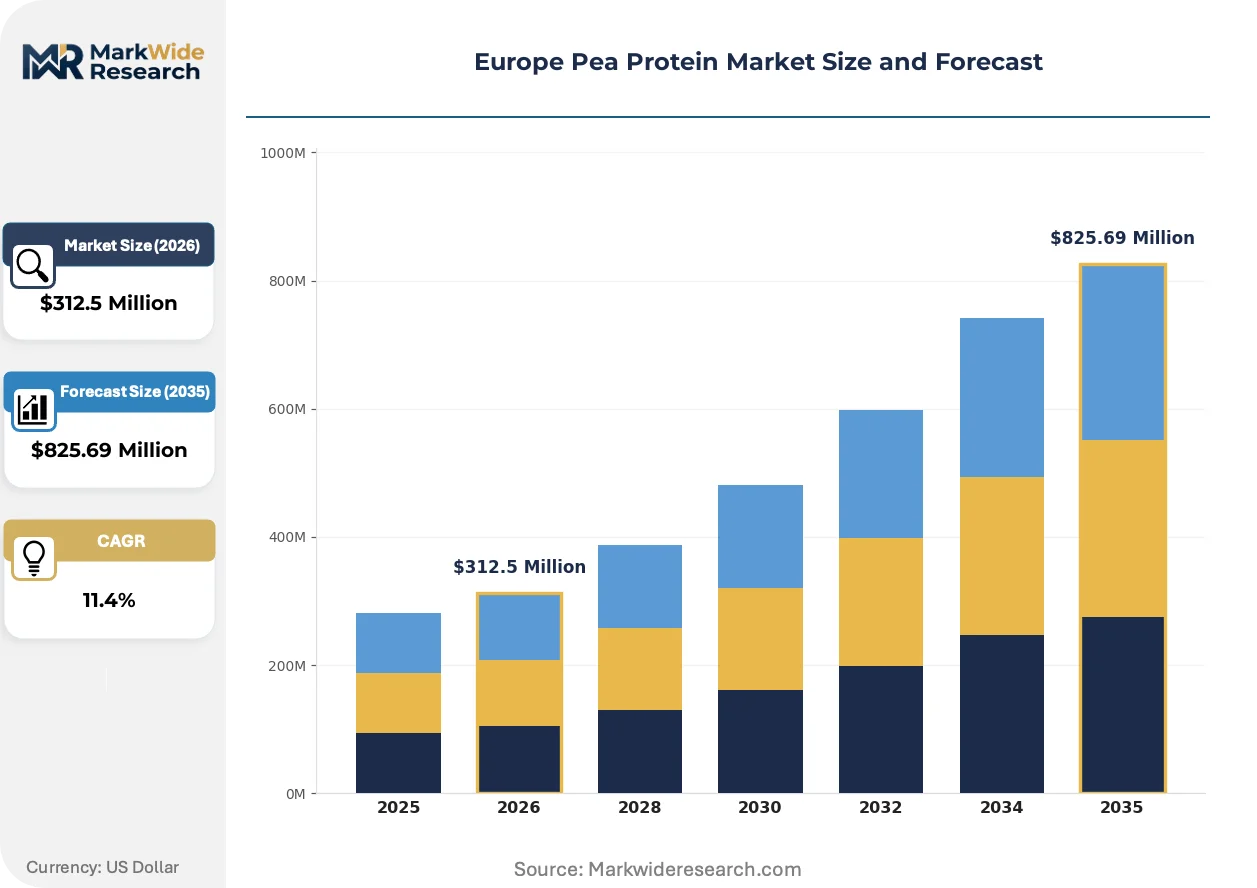
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Flour, Textured Pea Protein Application: Food & Beverages, Nutritional Supplements, Animal Feed, Meat Alternatives Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Vegetarians, Vegans, Fitness Enthusiasts, Health-Conscious Consumers |
| Companies Covered | Roquette Frères, Cosucra Groupe Warcoing, Sotexpro, Emsland Group, Ingredion Incorporated, Archer Daniels Midland Company, Cargill Inc., Kerry Group, A&B Ingredients, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pea Protein Market Shifts & Advancements
Processing technology maturation and regulatory stringency are restructuring competitive advantage around extraction yield and carbon-accounting transparency rather than scale alone.
Enzymatic de-bittering protocols are collapsing the flavor-neutralization cost structure for high-purity isolates. Dutch extraction facilities deploy these biocatalytic systems to reduce downstream masking ingredient loads by half. The technology is compressing premium-tier pricing power for legacy alkaline-extraction assets.
REACH chemical disclosure requirements are tightening solvent recovery and waste-stream documentation for European extraction plants. ECHA's expanded substance restrictions increase compliance overhead for facilities using traditional hexane alternatives. Protein isolate producers in Belgium and France accelerate closed-loop aqueous system investments to preempt enforcement exposure.
Direct-to-manufacturer contracting is displacing traditional ingredient distributor intermediation in foodservice channels. German and French plant-based meat brands negotiate traceability-guaranteed supply agreements that bypass regional wholesalers. This channel compression concentrates procurement leverage with processors demonstrating verified carbon-footprint credentials.
Europe Pea Protein Market Segmentation
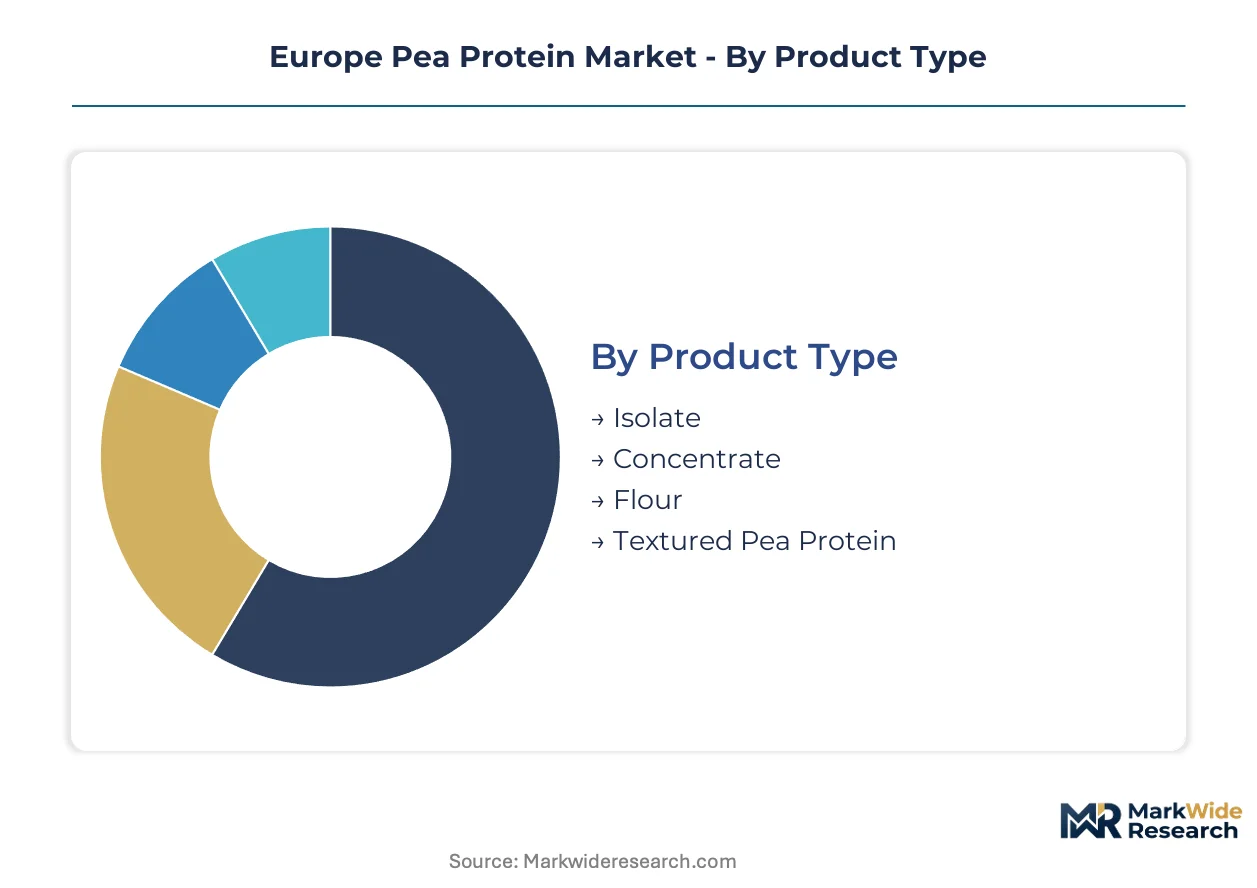
Pea protein segmentation in Europe reflects divergent technical specifications and formulation requirements across food manufacturing tiers. Product-grade differentiation determines extraction investment intensity, while application channels dictate certification and traceability burdens. Understanding these segment dynamics illuminates where margin pools concentrate and where volume expansion faces structural constraints.
Product Type:
Cycle times vary dramatically across extraction grades, with isolate requiring extended precipitation and drying sequences while flour moves through abbreviated milling circuits.
- Isolate:Protein content reaches 85-90% through alkaline solubilization followed by isoelectric precipitation, delivering neutral flavor and high solubility. German and French meat-alternative manufacturers absorb rising volumes as quick-service chains reformulate core menu items, though capex intensity for precipitation lines limits mid-tier processor participation.
- Textured Pea Protein:Extruded fibrous structures replicate meat-like mouthfeel through thermomechanical processing. European foodservice channels supplying quick-service restaurant chains in the Netherlands and Germany are expanding procurement fastest, driven by wet-fractionation technology advances that preserve protein functionality.
- Concentrate:Mid-tier protein content of 50-70% serves nutritional supplement formulations targeting fitness enthusiasts across Belgium and France.
- Flour:Ground whole pea with protein content near 50% anchors bakery and snack applications in Spain and Italy where cost sensitivity dominates.
Isolate anchors the volume base while textured pea protein gains share at the steepest rate.
Application:
Margin depth correlates inversely with formulation complexity, with meat alternatives commanding premium positioning against commoditized feed applications.
- Meat Alternatives:Whole-muscle and restructured analogues demand isolate purity combined with enzymatic de-bittering protocols. Dutch extraction facilities deploying biocatalytic systems supply German and French plant-based brands negotiating direct-to-manufacturer traceability contracts.
- Nutritional Supplements:Powder and bar applications prioritize concentrate economics where clean-label positioning justifies formulation premiums. Fitness enthusiasts in the United Kingdom and Germany drive demand concentration.
- Food & Beverages:Bakery, dairy alternatives, and beverage fortification utilize flour and concentrate grades across Southern European markets.
- Animal Feed:Pea protein co-products from wet-fractionation supply compound feed manufacturers in Poland and Romania facing protein security pressures.
Meat alternatives concentrate the deepest margin pools while animal feed expands most quickly as co-product utilization improves.
Distribution Channel:
Customer proximity determines working capital requirements, with direct sales compressing payment cycles against extended retail shelf placement timelines.
- Direct Sales:Traceability-guaranteed supply agreements bypass traditional distributors as German and French manufacturers seek verified carbon-footprint credentials. Rotterdam and Wageningen ingredient clustering accelerates formulation scale-up for these contracted relationships.
- Online Retail:Nutritional supplement brands reach fitness enthusiasts and health-conscious consumers through direct-to-consumer platforms with subscription mechanics.
- Supermarkets:Mass-market plant-based meat alternatives in France and Germany rely on centralized procurement with extended qualification cycles.
- Specialty Stores:Organic and clean-label positioned products serve niche vegetarian and vegan segments in urban centers.
Direct sales anchors the revenue base while online retail climbs the fastest as subscription models penetrate nutritional supplement segments.
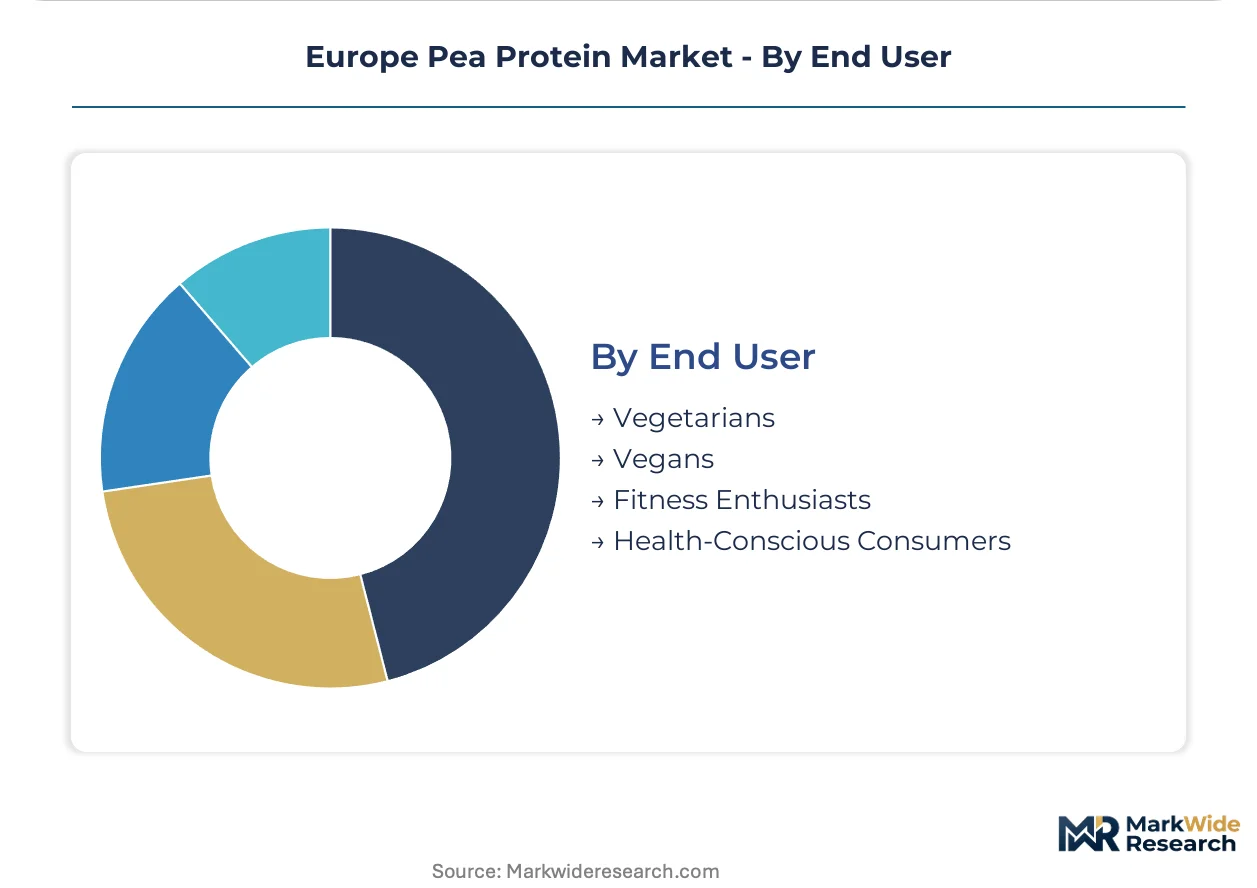
End User:
Purchase frequency and price elasticity diverge sharply across dietary commitment levels, from lifestyle vegetarians to performance-oriented fitness consumers.
- Fitness Enthusiasts:Protein powder and bar consumption drives concentrate demand with repeat purchase cycles and brand loyalty concentration. United Kingdom and German markets show highest per-capita spending.
- Vegans:Strict dietary adherence creates sustained isolate demand for complete amino acid profiles in meat-alternative and dairy-alternative applications.
- Health-Conscious Consumers:Flexitarian purchasing patterns favor blended and fortified products across mainstream retail channels.
- Vegetarians:Lacto-ovo dietary frameworks generate moderate protein supplementation demand alongside dairy and egg alternatives.
Fitness enthusiasts anchor the value base while vegans gain share fastest as meat-alternative menu penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA governs novel food approvals and protein health claims across the European Union, anchoring regulatory coherence for extraction facilities from Belgium to Poland. The EU Green Deal's carbon-border adjustments and REACH chemical disclosure requirements reshape sourcing economics and compliance burdens for member-state processors.
Germany
Quick-service restaurant chains reformulate core menu items with isolate-grade pea protein, absorbing rising volumes from Dutch extraction facilities. The F-Gas Regulation mandates accelerate equipment replacement cycles for food processing plants in North Rhine-Westphalia. Berlin-Brandenburg hosts formulation partnerships between meat-alternative brands and ingredient suppliers seeking verified carbon-footprint credentials.
France
Meat-alternative manufacturers negotiate direct-to-manufacturer traceability contracts bypassing traditional distributors. EFSA's evolving protein quality scoring methodology delays health claim approvals for nutritional supplement brands. Picardy region backward integration into yellow pea sourcing secures supply chains for extraction facilities serving Paris-based foodservice channels.
Netherlands
Ingredient clustering around Rotterdam and Wageningen compresses formulation cycle times for European food manufacturers. REACH compliance documentation for extraction solvents extends product qualification cycles at facilities near the port complex. Dutch wet-fractionation expertise preserves protein functionality for meat-analogue applications supplying German and French buyers.
Belgium
Fitness enthusiasts drive concentrate demand for nutritional powders and bars with repeat purchase cycles concentrated in Flanders. ECHA's expanded substance restrictions increase compliance overhead for facilities using traditional hexane alternatives. Cosucra Groupe Warcoing anchors Walloon production capacity with aqueous processing systems serving clean-label supplement brands.
Poland
Food processing sectors offer formulation partnership entry points as regional meat-alternative production scales. Pea protein co-products from wet-fractionation supply compound feed manufacturers facing protein security pressures. Warsaw and Łódź industrial zones attract mid-tier processors seeking lower capex intensity for precipitation line investments.
Europe Pea Protein Market Competitive Landscape
Vertically integrated multinationals and specialized fractionation houses split the market into distinct capability tiers. French and Belgian processors anchor supply security through backward integration into regional pulse cultivation, while German and Dutch competitors emphasize equipment retrofit contracts and formulation partnerships. Three archetypes dominate: captive-sourcing integrated processors, technology-licensing specialists, and regional toll-manufacturing operators. Capacity expansion and direct-to-manufacturer contracting constitute the dominant competitive moves reshaping channel relationships.
Within the integrated-processor tier, Roquette Frères exemplifies backward integration into Picardy region yellow pea sourcing. Cosucra Groupe Warcoing represents wet-fractionation specialization anchored in Belgian aqueous processing expertise. Emsland Group occupies a position bridging modified starch capabilities with textured protein formats for European food processors. These three entities collectively illustrate how geographic proximity to demand clusters and extraction technology depth determine competitive positioning across the isolate-concentrate-flour spectrum.
| Leading Market Players |
|---|
| Roquette Frères |
| Cosucra Groupe Warcoing |
| Sotexpro |
| Emsland Group |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Cargill Inc. |
| Kerry Group |
| A&B Ingredients |
| Others |
Supply & Pricing Matrix
Rotterdam and Wageningen ingredient clustering concentrates extraction capacity within a 150-kilometer radius, compressing logistics costs for Dutch wet-fractionation facilities and amplifying their pricing leverage over German and French buyers seeking traceability-guaranteed supply contracts.
Pricing Analysis
Price spreads between Picardy-origin isolate and Black Sea-imported concentrate are widening as EU Green Deal carbon-border adjustments reprice landed costs for non-European yellow pea supplies. Three-tier pricing structure across premium isolate, standard concentrate, and economy flour grades anchors the market, with enzymatic de-bittering certification commanding measurable premiums. Pricing pressure stems from enzymatic de-bittering technology diffusion collapsing legacy alkaline-extraction margins. Feed compounders in Poland and Romania exhibit highest price sensitivity, while Dutch meat-alternative manufacturers prioritize carbon-accounting transparency over unit economics.
Supply Chain Analysis
Yellow pea sourcing draws from Picardy region cultivation in France, Canadian prairie harvests, and Black Sea corridor shipments through Romanian port infrastructure. Wet-fractionation facilities rely on aqueous processing chemicals, spray-drying energy inputs, and enzymatic biocatalysts. Single-source vulnerability concentrates in Roquette Frères' Picardy backward integration, where regional weather shocks or disease pressure could disrupt French isolate supply. Distribution runs through direct-to-manufacturer contracting displacing traditional ingredient distributors as German and French brands seek verified carbon-footprint credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe pea protein demand is recovering from input cost volatility cycles as Black Sea grain corridor stabilization and enzymatic de-bittering technology maturation restore margin visibility for extraction processors.
For Market Incumbents: Insulate margin pools by accelerating closed-loop aqueous system investments to preempt ECHA solvent restriction enforcement, while securing long-term offtake contracts with quick-service restaurant chains reformulating core menu items. Threat of precision fermentation hybrid formulations demands preemptive R&D positioning in novel texture profiles. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian food processing partnerships where regional meat-alternative production scaling creates formulation collaboration entry points with lower capex intensity than isolate-grade precipitation line investments. White-space exists in wet-fractionation co-product feed supply contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wet-fractionation specialists with proprietary enzymatic de-bittering protocols over legacy alkaline-extraction assets facing technology obsolescence. Long-term viability hinges on carbon-accounting transparency infrastructure and direct-to-manufacturer channel control. Signal to monitor: EFSA protein quality scoring methodology finalization and its impact on health claim permissibility economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Pulse Cultivation | Picardy region yellow pea sourcing secures supply chains against Black Sea corridor disruptions. |
| Closed-Loop Aqueous System Investment | REACH compliance documentation acceleration preempts ECHA solvent restriction enforcement exposure. |
| Direct-to-Manufacturer Contracting Expansion | Traceability-guaranteed supply agreements bypass traditional distributors for German meat-alternative brands. |
| Enzymatic De-Bittering Technology Deployment | Biocatalytic systems reduce downstream masking ingredient loads by half for isolate producers. |
| Formulation Partnership with Quick-Service Restaurant Chains | Menu reformulation cycles absorb rising isolate volumes from Dutch extraction facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food approval databases, REACH compliance filings, EU customs trade records, and extraction facility capacity disclosures. Protein chemists at wet-fractionation plants, procurement leads at German meat-alternative manufacturers, regulatory affairs specialists navigating ECHA substance restrictions, and foodservice channel distributors contributed primary perspectives. Bottom-up volume modeling triangulates against top-down market sizing from trade flow analysis.
Forecast inputs span isolate-concentrate-flour grade tiers, meat-alternative-nutritional supplement-feed application splits, and direct-online-supermarket channel dynamics across the projection horizon. CAGRs derive from segmented growth rate reconciliation against macro protein substitution elasticity assumptions. EU Green Deal carbon-border adjustment implementation timelines and EFSA protein quality scoring finalization constitute industry-specific forecast sensitivities.
Stress conditions across Black Sea grain corridor stability, Canadian harvest variability, and enzymatic biocatalyst cost curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology diffusion rates. Cross-checking against EFSA novel food approval tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Soy Food Products Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Plant Based Meat Market