
 Plant Based Supplement Market | 2026-2036
Plant Based Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Supplement Market Analytics
Capital intensity divergence between contract manufacturers and in-house formulators is unwinding competitive stability in the plant based supplement sector. Otsuka Holdings leverages integrated fermentation capabilities to anchor its amino acid and botanical extract supply. NOW Health Group competes through vertical control over powder processing and tablet compression lines in North American facilities. Glanbia plc extends its dairy-alternative ingredient expertise into plant protein isolate production for sports nutrition brands.
Plant based supplements comprise concentrated, extracted, or synthesized bioactive compounds derived from botanical, algal, or fungal sources, formulated to deliver targeted nutritional or physiological benefits through standardized delivery systems such as capsules with defined dissolution profiles or protein isolates with minimum 80% purity. Protein powders lead product type revenue due to sports nutrition demand, while gummies capture the fastest growth trajectory as palatability innovations attract hesitant health-conscious consumers. Sports nutrition applications concentrate margin pools among fitness enthusiasts, whereas general health formulations serve the broader vegan and vegetarian base with lower per-unit premiums but higher purchase frequency.
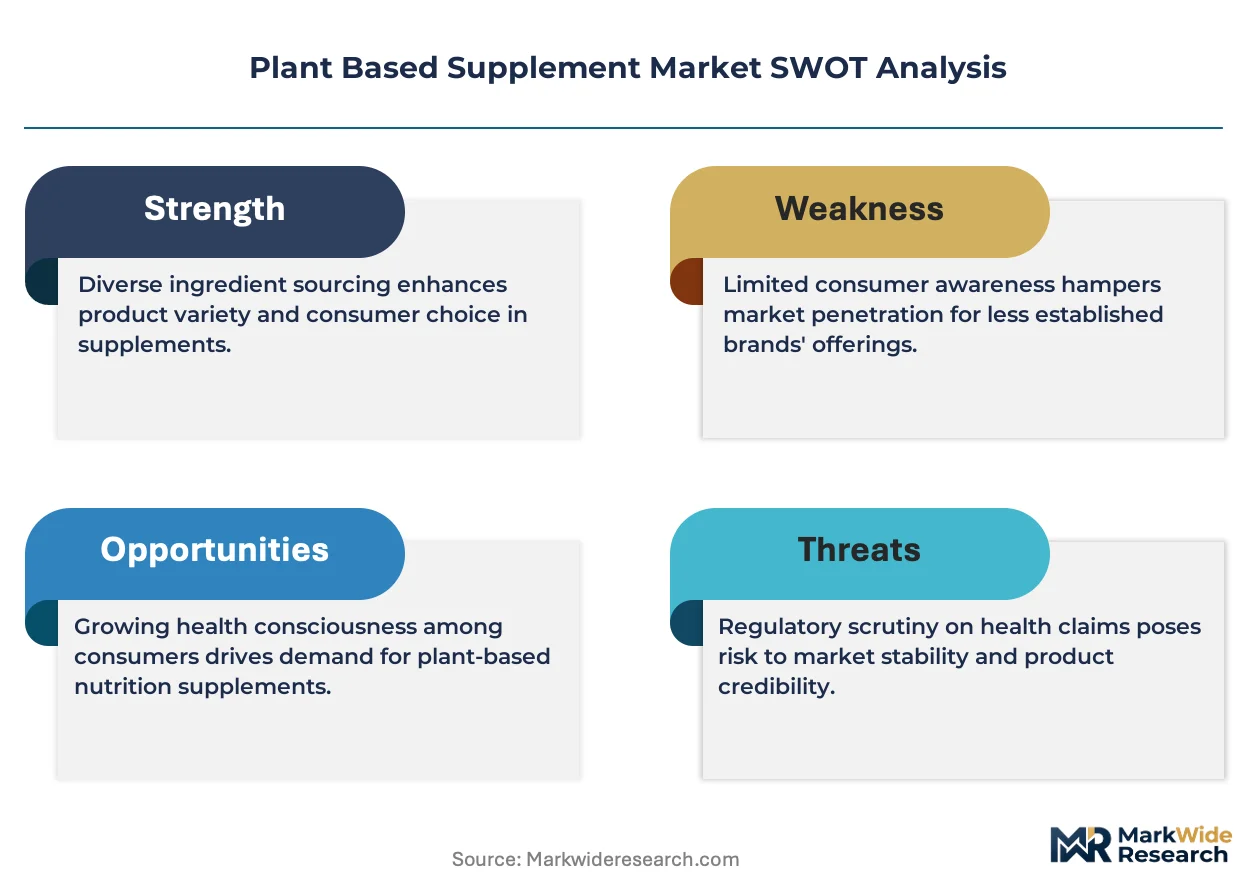
FDA dietary supplement cGMP enforcement and EFSA novel food assessments shape formulation transparency and substantiation requirements across the US and Europe. BIS quality benchmarks in India and China's NMPA health food blue-hat registration process add compliance layers for exporters targeting Asia-Pacific expansion. Stakeholders must monitor evolving protein content verification standards and adapt sourcing strategies as regulatory scrutiny intensifies on label claims and contaminant thresholds.
Market Dynamics
Fitness enthusiasts are compressing protein powder innovation cycles while clean-label mandates from EFSA and FDA force reformulation investments across European and North American supply chains.
Growth Catalysts
- FDA cGMP Enforcement:Stricter facility inspections and documentation requirements are elevating barriers for subscale operators, consolidating volume among certified contract manufacturers.
- Sports Nutrition Demand:Amateur and professional athletes are expanding protein isolate consumption beyond traditional dairy-based products into pea, rice, and hemp formulations.
- Germany Retail Channel Maturity:Discounters and pharmacy chains have normalized plant-based supplement placement, creating template distribution models replicable in adjacent markets.
Market Restraints
- Pea Protein Input Volatility:Yellow pea harvest variability in Canada and Ukraine creates price instability for isolate producers dependent on North American and Black Sea sourcing.
- EFSA Novel Food Assessments:Protracted safety dossier reviews for emerging algal and fungal extracts delay European market entry by 18-36 months versus conventional botanicals.
- Contaminant Threshold Scrutiny:Heavy metal and pesticide residue limits under BIS quality benchmarks and China's NMPA blue-hat registration force costly third-party testing protocols.
Strategic Opportunities
- India Export Expansion:BIS certification alignment and Ayurveda botanical heritage create positioning advantages for ashwagandha and turmeric extract suppliers targeting diaspora and wellness segments.
- Gummy Format Innovation:Palatability-driven delivery systems attract hesitant health-conscious consumers, opening incremental share beyond committed vegan populations.
- EU Green Deal Incentives:Sustainability-linked procurement criteria and carbon border adjustments favor domestic European fermentation and extraction facilities over imported isolates.
Industry Challenges
- Fermentation Scale-Up Talent:Shortage of process engineers capable of translating lab-scale mycelial and algal production to industrial bioreactor operations constrains capacity expansion timelines.
- Dual Certification Burden:Simultaneous pursuit of USDA Organic and Non-GMO Project verification creates documentation complexity and audit scheduling conflicts for multi-market suppliers.
- Legacy ERP Integration:Batch record digitization for FDA 21 CFR Part 11 compliance conflicts with established quality management systems, requiring middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Supplement Market |
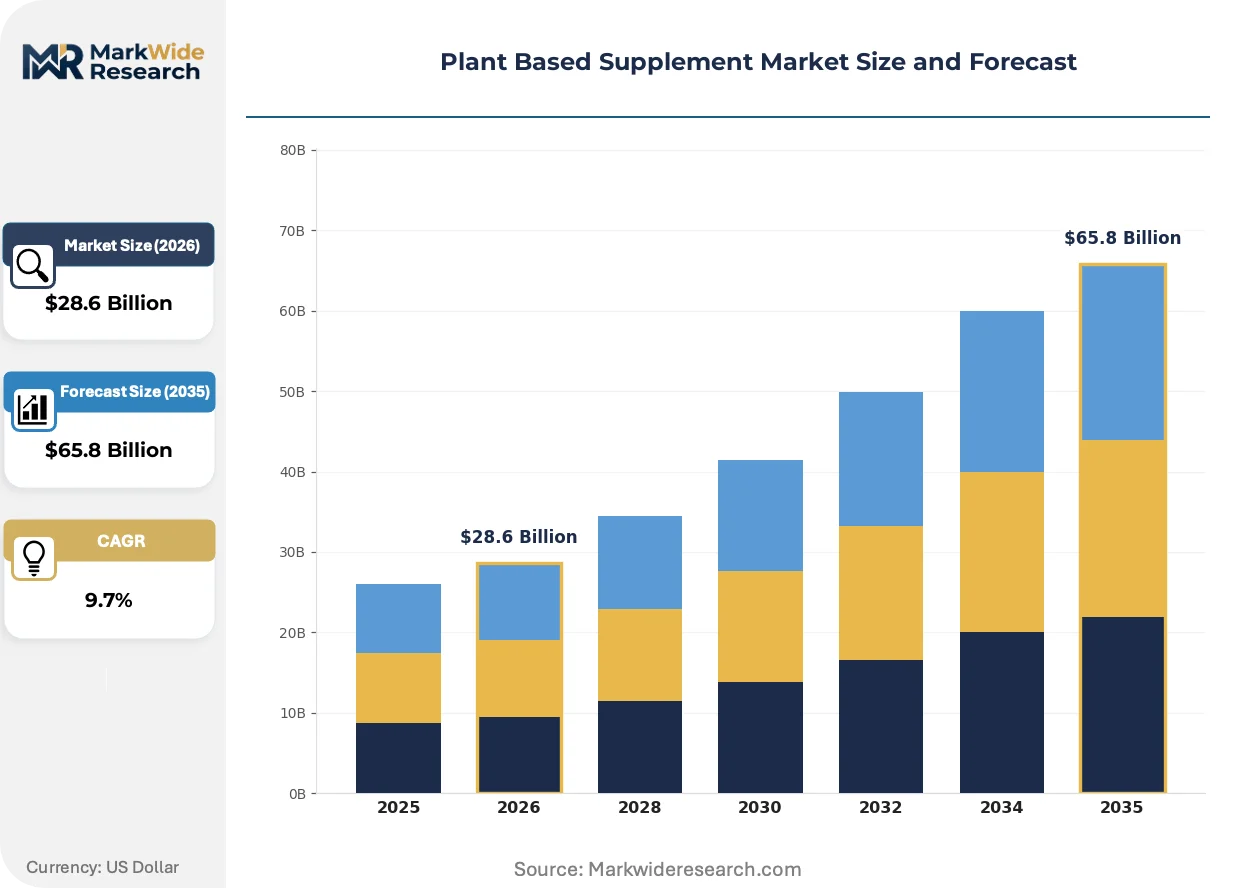
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Capsules, Liquid Extracts, Gummies End User: Fitness Enthusiasts, Vegans, Vegetarians, Health-Conscious Consumers Form: Powder, Tablet, Oil, Drink Mix Application: Sports Nutrition, Weight Management, General Health, Immune Support |
| Companies Covered | Otsuka Holdings Co., Ltd., H&H Group, Nestlé, General Nutrition Centers, Inc., NOW Health Group, Inc., Abbott, Herbalife Ltd., Hormel Foods Corporation, Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Supplement Market Evolving Landscape
Precision fermentation and enzymatic protein extraction are redrawing competitive boundaries between synthetic biology startups and established botanical extractors, while regulatory divergence between jurisdictions fragments standardization efforts.
Precision fermentation for recombinant proteins is bifurcating the amino acid supply landscape. Sports nutrition brands are adopting fermentation-derived L-leucine and L-arginine at accelerating rates. This technology is compressing margins for traditional soy and wheat gluten hydrolysate suppliers while enabling label claims free from agricultural allergen risks.
EFSA's evolving novel food guidance on cell-cultured and precision-fermented ingredients is forcing parallel dossier preparation for structurally identical compounds. Manufacturers must now compile separate toxicology packages for fermentation-derived versus plant-extracted bioactives. Botanical extractors in Italy and Spain are responding by accelerating GRAS self-affirmation pathways for US market access.
Direct-to-consumer subscription models are displacing pharmacy and mass-market retail as the primary acquisition channel for repeat purchasers. Personalized nutrition platforms using at-home microbiome testing are bundling plant-based supplements with algorithmic dosing recommendations. This shift concentrates customer lifetime value capture in Germany and the Netherlands, where digital health integration exceeds Southern European penetration.
Plant Based Supplement Market Segmentation
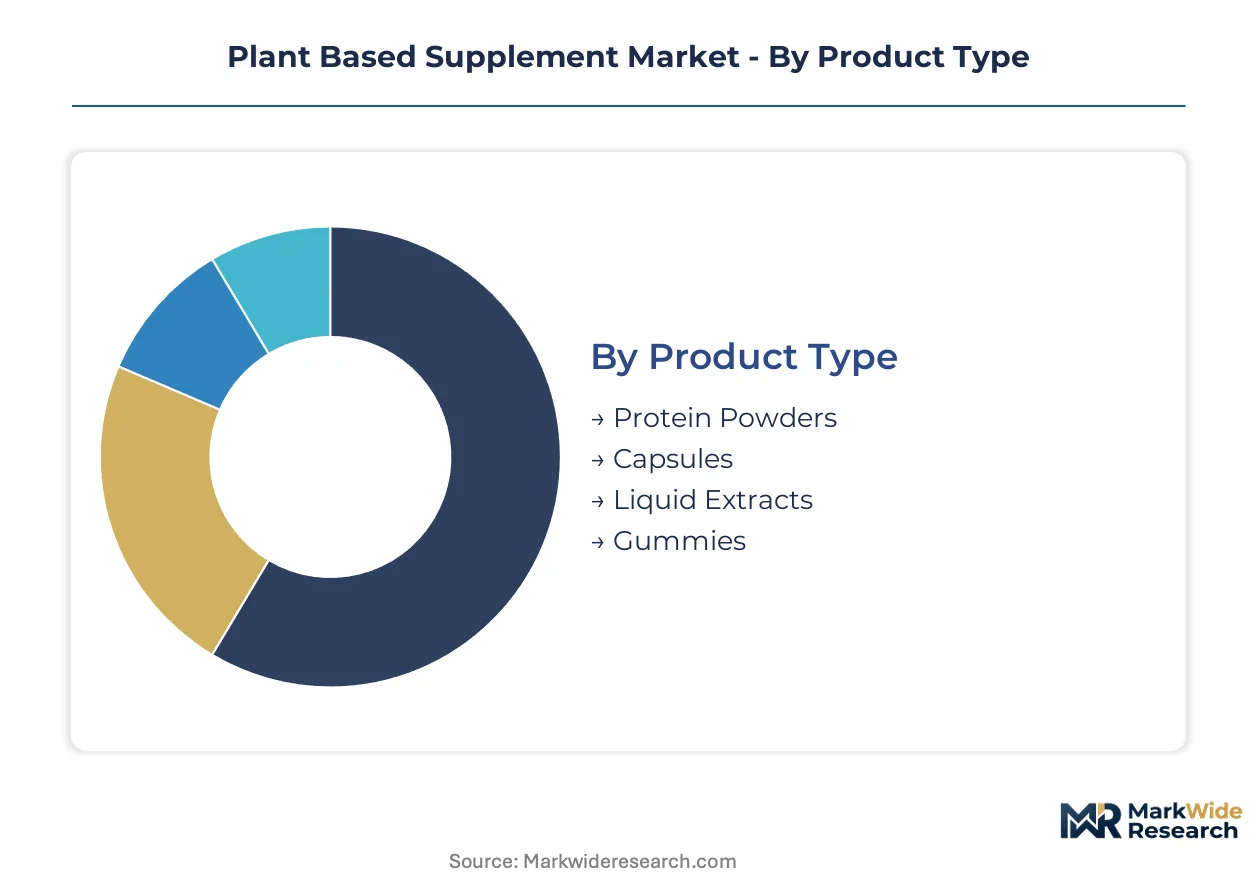
Segmentation in the plant based supplement market reveals how protein delivery formats, user psychographics, and application-specific dosing requirements create distinct margin architectures. Manufacturers configure production lines and certification investments around these divides.
Product Type:
Margin pools concentrate in formats requiring specialized processing equipment and dissolution engineering.
- Protein Powders:Isolates with minimum 80% purity specifications dominate sports nutrition procurement. Demand clusters among German fitness enthusiasts and North American amateur athletes seeking dairy-alternative formulations.
- Gummies:Palatability innovations using pectin bases and natural flavor masking attract hesitant health-conscious consumers. Germany's pharmacy chains and Dutch direct-to-consumer platforms are expanding shelf space fastest for this format.
- Capsules:Standardized delivery systems with defined dissolution profiles serve botanical extract applications.
- Liquid Extracts:Concentrated bioactive suspensions target rapid absorption use cases.
The dominant share belongs to Protein Powders, while Gummies is closing the gap fastest.
End User:
Volume concentration tracks lifestyle commitment intensity and purchase frequency differentials.
- Fitness Enthusiasts:Amateur and professional athletes generate recurring high-volume orders for leucine-enriched isolates. Sports nutrition brands in Germany and the US capture this cohort through subscription models with algorithmic dosing.
- Vegans:Strict dietary adherence drives premium positioning for certified organic and Non-GMO Project verified lines. German discounters have normalized placement, creating template distribution models.
- Vegetarians:Flexibility in dairy consumption creates price sensitivity relative to vegan counterparts.
- Health-Conscious Consumers:Occasional purchasers respond to gummy format innovations and microbiome-personalized recommendations.
Fitness Enthusiasts command the highest per-capita spend, though Health-Conscious Consumers are expanding most quickly through digital health integration.
Form:
Production asset utilization varies sharply across compression, blending, and encapsulation capabilities.
- Powder:Bulk processing lines with spray-drying and agglomeration equipment serve protein isolate scale.
- Tablet:Compression tooling with specific hardness and friability specifications dominates botanical extract delivery.
- Oil:Cold-press and CO2 extraction infrastructure targets omega fatty acid and lipid-soluble compound preservation.
- Drink Mix:Instantized formulations with dispersibility engineering compete in convenience-oriented channels.
Powder holds the installed production base advantage, while Drink Mix is gaining share fastest through single-serve convenience positioning.
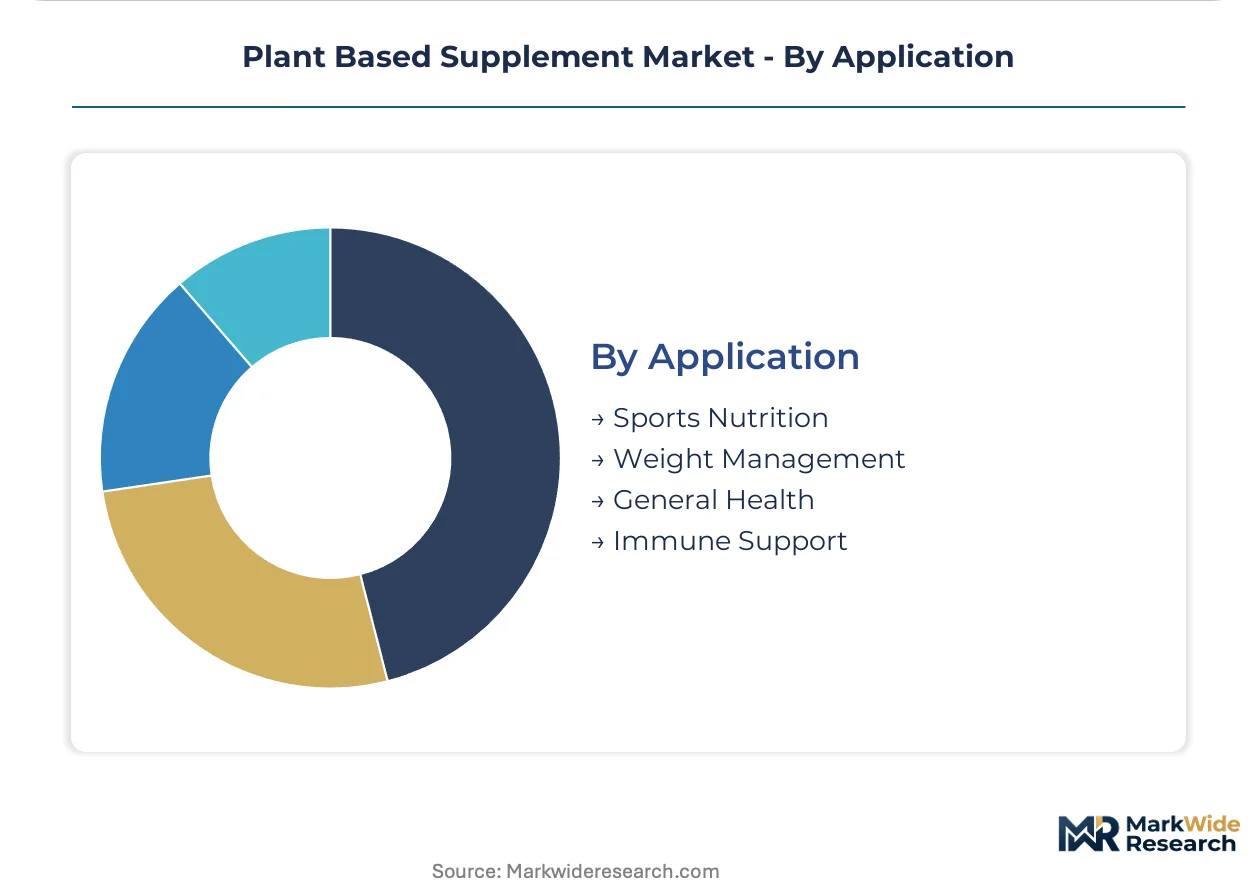
Application:
Pricing power correlates with performance claim substantiation requirements and regulatory scrutiny intensity.
- Sports Nutrition:Protein isolates with amino acid profiling command premium positioning. EFSA health claim assessments and FDA cGMP enforcement elevate compliance costs for market access.
- General Health:Broad vegan and vegetarian base sustains volume through lower per-unit premiums but higher purchase frequency.
- Weight Management:Satiety and metabolic positioning requires clinical dossier preparation for novel botanical extracts.
- Immune Support:Elderberry, echinacea, and adaptogenic formulations face seasonal demand volatility.
Sports Nutrition captures the steepest margin premiums, while Immune Support is climbing the fastest post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with German fitness enthusiasts accepting steep premiums for certified isolates while Indian price-sensitive consumers drive volume through unbranded Ayurveda extracts. Price-insurance mechanisms and subsidy structures explain much of this divergence.
Germany
Fitness enthusiasts and pharmacy chain normalization sustain outsized per-capita consumption of protein isolates and gummy formats. EFSA novel food assessments and EU Green Deal procurement criteria elevate compliance costs for imported botanicals. Berlin-Brandenburg hosts fermentation scale-up facilities serving precision-derived amino acid suppliers to sports nutrition brands.
United States
Amateur athletes and direct-to-consumer subscription platforms concentrate demand for dairy-alternative protein powders. FDA cGMP enforcement and evolving dietary supplement frameworks reshape formulation transparency requirements. Greater Los Angeles and Salt Lake City anchor contract manufacturing clusters with integrated powder processing and tablet compression capabilities.
India
Ayurveda heritage and diaspora export demand position ashwagandha and turmeric extract suppliers for premium positioning. BIS quality benchmarks and FSSAI registration layers add compliance complexity for domestic and export markets. Maharashtra and Gujarat concentrate extraction facilities serving both traditional wellness and modern sports nutrition applications.
China
Domestic sports nutrition adoption and precision fermentation investment accelerate amino acid and alternative protein production. NMPA health food blue-hat registration and dual carbon goals constrain market access timelines and favor domestic bioreactor capacity. Yangtze River Delta clusters host integrated fermentation-to-formulation operations for recombinant protein supply.
Netherlands
Digital health integration and personalized nutrition platforms drive gummy format and microbiome-personalized supplement adoption. EFSA health claim substantiation requirements and REACH chemical safety protocols govern botanical extract imports. Randstad logistics hubs enable rapid fulfillment infrastructure for direct-to-consumer subscription models across Northern Europe.
Plant Based Supplement Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Precision fermentation specialists command premium positioning for recombinant amino acids, while commodity botanical extractors compete on input sourcing scale. The market structures around three archetypes: integrated fermentation-to-formulation operators, contract manufacturers with vertical equipment control, and ingredient suppliers extending dairy-alternative expertise into plant proteins. Dominant competitive moves include backward integration into captive supply chains and geographic certification stacking for multi-market access.
Within the integrated fermentation tier, Otsuka Holdings Co., Ltd. and Glanbia plc exemplify divergent pathways—one anchored in amino acid biotechnology, the other extending dairy processing expertise into isolate production. NOW Health Group, Inc. occupies a position among North American contract manufacturers with in-house powder processing and compression capabilities, representing the vertical equipment control archetype. These three entities illustrate how technology depth, geographic certification breadth, and production asset configuration segment competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Otsuka Holdings Co., Ltd. |
| H&H Group |
| Nestlé |
| General Nutrition Centers, Inc. |
| NOW Health Group, Inc. |
| Abbott |
| Herbalife Ltd. |
| Hormel Foods Corporation |
| Glanbia plc |
| Others |
Value Network & Pricing Analysis
Bioreactor capacity utilization above 85% in German fermentation clusters compresses marginal cost curves for precision-derived amino acids while simultaneously elevating price floors for botanical extractors lacking comparable scale economies. This divergence concentrates margin capture among integrated operators and forces commodity-grade suppliers toward volume-driven, lower-unit-value positioning.
Pricing Analysis
Subscription revenue from algorithmic dosing platforms now exceeds initial product margins for German fitness enthusiasts, shifting lifetime value capture toward recurring service tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified organic isolates from conventional botanicals and unbranded commodity powders. Price erosion runs through standard-tier protein isolates as contract manufacturers add comparable fermentation capacity. Health-conscious occasional purchasers exhibit highest price sensitivity, while amateur athletes in subscription programs accept sustained premiums for personalized formulations.
Supply Chain Analysis
Container availability constraints on Black Sea routes and Vancouver port congestion intermittently disrupt yellow pea isolate shipments to North American tablet compression facilities. Canada, Ukraine, and India anchor global supply for pea protein, ashwagandha rootstock, and turmeric rhizome respectively. Input dependencies rest on Canadian prairie harvest cycles, Ukrainian export corridor stability, and monsoon-dependent Indian extraction yields. Single-source vulnerability concentrates in mycelial fermentation strains held by limited European biobanks. Distribution runs through German pharmacy chains and Dutch direct-to-consumer platforms for premium tiers, with mass-market volume flowing via North American contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in this market, as FDA cGMP certification and EFSA novel food dossiers require 18-36 month lead times that deter rapid competitive replication. Incumbents who stacked multi-jurisdictional approvals first now capture disproportionate shelf space and subscription platform access.
For Market Incumbents: Consolidate backward integration into captive pea protein processing and precision fermentation capacity to offset input volatility from Canadian and Ukrainian harvest variability. Prioritize dual certification investments in USDA Organic and Non-GMO Project verification to defend pharmacy chain placement against emerging contract manufacturers with narrower compliance breadth. Threat concentration sits with synthetic biology startups offering fermentation-derived amino acids at compressed margins.
For New Entrants and Emerging Players: Differentiate on gummy format palatability engineering and Ayurveda heritage positioning for diaspora wellness segments in Europe and North America. Target health-conscious consumers hesitant about traditional powder formats as the most penetrable psychographic, particularly through Dutch and German direct-to-consumer subscription platforms. Go-to-market execution should emphasize at-home microbiome testing bundling to capture algorithmic dosing revenue streams.
For Investors and Strategic Acquirers: Contract manufacturers with integrated powder processing, tablet compression, and bioreactor fermentation capabilities represent the most defensible acquisition archetype for medium-term positioning. Long-term viability hinges on regulatory compliance breadth rather than single-technology leadership, as EFSA and FDA frameworks continue elevating barriers. Signal to monitor: acceleration of EU Green Deal procurement criteria favoring domestic European fermentation facilities over imported isolates.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Recombinant amino acid production in German bioreactor clusters reduces agricultural allergen exposure for sports nutrition brands. |
| Dual Certification Investment | Simultaneous USDA Organic and Non-GMO Project verification unlocks pharmacy chain access in German and Dutch retail networks. |
| Gummy Format Line Expansion | Pectin-based palatability engineering captures health-conscious consumers beyond committed vegan populations in Northern Europe. |
| Backward Integration into Pea Processing | Captive yellow pea isolate production insulates margin stability against Black Sea export corridor disruptions. |
| Direct-to-Consumer Platform Launch | Algorithmic dosing subscriptions concentrate customer lifetime value in digitally integrated German and Netherlands markets. |
Research Methodology
Cross-validation between primary interviews with contract manufacturing executives, sports nutrition brand formulators, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA cGMP inspection records, EFSA novel food assessment databases, and customs trade data for pea protein and botanical extract flows. Bottom-up triangulation from facility-level capacity estimates and top-down reconciliation against retail audit data from German pharmacy chains and Dutch direct-to-consumer platforms ensures dimensional consistency.
Sensitivity analysis across protein purity specifications, fermentation yield assumptions, and subscription retention rates governs the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product format, end-user psychographic intensity, application-specific dosing requirements, and regional regulatory cluster stringency. CAGRs derive from installed capacity expansion schedules, EFSA dossier approval timelines, and digital health platform penetration curves in Northern European markets.
Material uncertainties — regulatory enforcement intensity shifts, harvest volatility in Canadian prairies and Ukrainian Black Sea regions, and precision fermentation yield breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification stacking behavior and subscription platform economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Global Tofu Market
Plant Based Food
Pea Protein Market