
 Flax-Based Protein Market | 2026-2036
Flax-Based Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Flax-Based Protein Market Foresight
Canadian flaxseed processing capacity is realigning toward higher-value protein extraction. Richardson International leverages its Prairie grain elevator network to secure raw material flows. Bioriginal Food & Science Corp. specializes in omega-3 integrated protein formulations for nutraceutical clients. Glanbia Nutritionals competes through its sports nutrition ingredient portfolio, where plant proteins now anchor new product lines.
Flax-based protein encompasses protein fractions derived from flaxseed (Linum usitatissimum), typically containing 30-40% protein by weight with notable fiber and lignan co-content, extracted through mechanical pressing or aqueous separation followed by drying into functional powder forms. Its primary commercial purpose centers on delivering allergen-friendly plant protein with emulsifying properties for food and nutraceutical systems. Powder form dominates current manufacturing throughput due to shelf stability and blending versatility across application categories. Sports nutrition represents the fastest-expanding application segment, while functional foods occupy the mature volume base where margin compression has intensified.
Health Canada and the FDA both exercise jurisdiction over flax protein health claims and novel food approvals, with Canada's PMRA additionally governing pesticide residue thresholds in oilseed crops. The EU's EFSA novel food authorization pathway creates a separate compliance threshold for flax protein isolates entering European formulations. Stakeholders must monitor evolving protein digestibility scoring methodologies, as regulatory bodies weigh amino acid completeness against processing innovation claims.
Market Dynamics
Protein digestibility scoring methodologies are forcing manufacturers to restructure formulation claims and processing investments, as Health Canada and the FDA weigh amino acid completeness against novel extraction techniques.
Growth Catalysts
- Clean-label allergen substitution:Bakeries and meat alternatives manufacturers are accelerating flax protein adoption to replace soy and wheat isolates in free-from product lines, driven by pediatric allergen avoidance protocols.
- Omega-3 functional convergence:Nutraceutical formulators are integrating flax protein with lignan concentrates to capture cardiovascular health positioning in supplement SKUs.
- Prairie processing infrastructure:Manitoba and Saskatchewan elevator networks are retrofitting for protein fractionation, securing captive supply chains for North American ingredient distributors.
Market Restraints
- Input cost volatility:Flaxseed oilseed prices fluctuate with canola substitution demand and biodiesel policy shifts, compressing isolate margins during commodity spikes.
- Supply concentration risk:Over 60% of global flaxseed production originates in the Canadian Prairies, exposing processors to single-region weather and trade policy disruptions.
- Technical limitation:Flax protein's low lysine content relative to WHO reference standards limits standalone nutritional claims without amino acid fortification.
Strategic Opportunities
- Underpenetrated pet nutrition:Premium dog and cat food manufacturers in the United States are testing flax protein for omega-3 delivery in grain-free formulations.
- Regulatory tailwind:Canada's PMRA residue threshold harmonization with Codex Alimentarius is streamlining export certification for Prairie processors entering EU novel food pathways.
- Technology convergence:Aqueous extraction systems combined with membrane filtration are enabling simultaneous protein and mucilage recovery for dual-revenue streams.
Industry Challenges
- Protein functionality expertise gap:Food technologists with emulsion stability optimization for high-fiber protein matrices remain scarce in ingredient R&D departments.
- Capex intensity:Commercial-scale aqueous extraction lines require seven-figure investments in decanter centrifuges and spray-drying towers, limiting mid-processor participation.
- Certification timeline compression:EFSA novel food dossier preparation for flax protein isolates demands 18-24 month toxicology and digestibility studies, delaying European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flax-Based Protein Market |
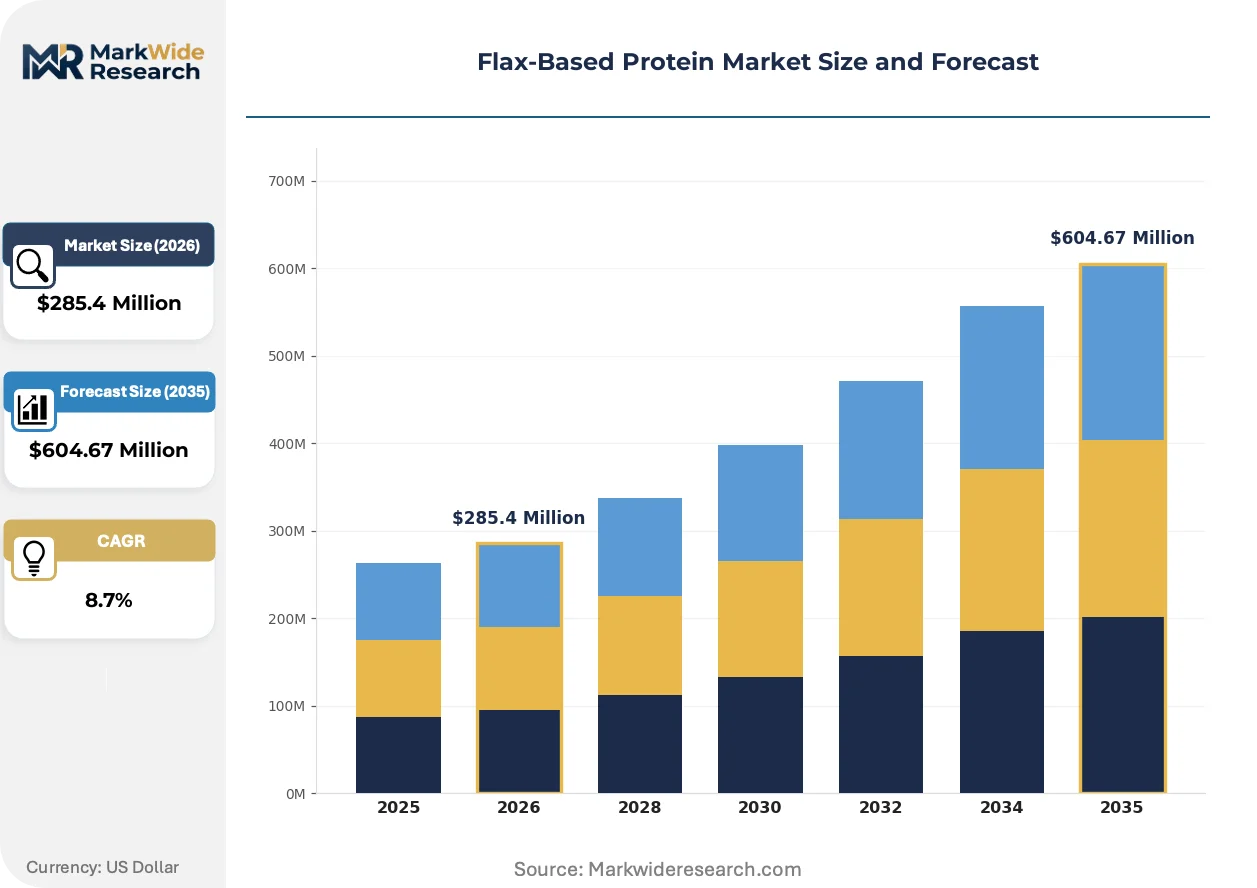
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flax Protein Concentrate, Flax Protein Isolate, Flaxseed Meal, Flax Protein Hydrolysate Application: Sports Nutrition, Dietary Supplements, Functional Foods, Animal Feed, Personal Care End User: Food Manufacturers, Nutraceutical Companies, Feed Producers, Cosmetics Producers Form: Powder, Liquid, Granules, Capsules |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Glanbia Nutritionals, Austrade Inc., Richardson International, Bioriginal Food & Science Corp., Bunge Limited, Ingredion Incorporated, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flax-Based Protein Market Shifts & Advancements
Processing technology and regulatory clarity are converging to reshape competitive positioning in plant protein ingredient supply. Three developments are restructuring how flax protein enters food and nutraceutical systems.
Membrane filtration systems are automating the separation of protein fractions from flaxseed meal with precision that mechanical pressing cannot match. Sports nutrition contract manufacturers in Canada are installing these lines at pilot scale. The technology is automating quality consistency in isolate production, reducing batch-to-batch variation that previously limited high-value applications.
EFSA's updated novel food guidance on protein hydrolysates is clarifying dossier requirements for flax-derived ingredients entering European formulations. The regulation tightens amino acid profiling standards while streamlining approval timelines for mechanically processed variants. Isolate suppliers targeting Germany and France are restructuring toxicology packages to align with the new protein characterization protocols.
Direct procurement relationships between Prairie processors and CPG brand R&D teams are displacing traditional ingredient distributor intermediaries. Sports nutrition and functional food verticals in the United States are establishing annual offtake agreements with Manitoba extraction facilities. The shift concentrates volume commitments with processors demonstrating certified organic and non-GMO verification chains.
Flax-Based Protein Market Segmentation
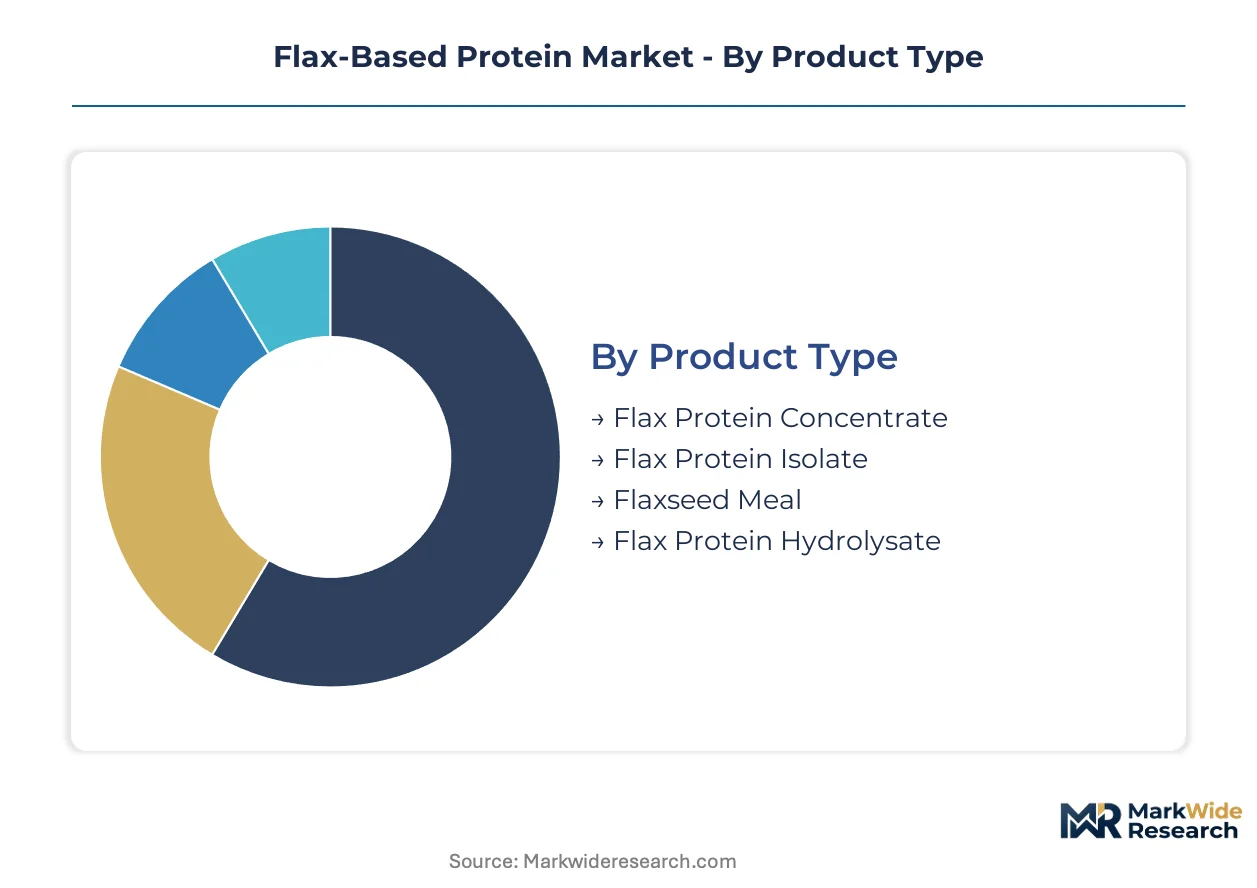
Segmentation in flax-based protein markets reveals how capital deployment and technical capabilities concentrate across extraction tiers and end-use specifications. Manufacturers align facility investments with margin structures inherent to each product grade and application requirement.
Product Type:
Capital intensity escalates sharply from mechanical pressing through aqueous extraction to hydrolysate production, with membrane filtration and enzymatic systems demanding seven-figure equipment commitments.
- Flax Protein Concentrate:Contains 50-70% protein with retained fiber and oil fractions, produced through dry mechanical separation. Food manufacturers in Canada and the United States absorb the majority of concentrate volume for bakery and meat alternative formulations where cost sensitivity outweighs purity requirements.
- Flax Protein Isolate:Delivers 85-90% protein purity via aqueous extraction combined with isoelectric precipitation. Nutraceutical companies in Germany and France are expanding isolate procurement for amino acid-fortified supplement lines, constrained by EFSA novel food dossier timelines and lysine completeness standards.
- Flaxseed Meal:Co-product of oil extraction retaining 30-40% protein with high fiber content. Feed producers in the United States source meal for dairy ration formulations.
- Flax Protein Hydrolysate:Enzymatically cleaved peptides with enhanced bioavailability. Sports nutrition formulators in Canada are piloting hydrolysate integration for rapid-absorption protein beverages.
Flax Protein Concentrate absorbs the bulk of installed capacity; Flax Protein Isolate is expanding most quickly.
Application:
Margin structures diverge across applications, with sports nutrition commanding premium pricing for amino acid profiling while functional foods operate on compressed ingredient costs.
- Sports Nutrition:Protein powders, ready-to-drink beverages, and recovery formulations targeting athletic performance. Canadian contract manufacturers are installing dedicated flax isolate blending lines to serve US sports nutrition brands seeking allergen-free positioning.
- Dietary Supplements:Capsule and tablet formats emphasizing cardiovascular health through lignan-protein co-delivery. Nutraceutical distributors in California and New York are expanding omega-3 integrated SKUs.
- Functional Foods:Bakery, pasta, and meat alternative applications where emulsifying properties replace gluten or soy. German and Dutch food technologists are reformulating clean-label bread lines with flax concentrate.
- Animal Feed:Dairy and poultry rations leveraging residual meal protein. Wisconsin and Idaho dairy cooperatives are testing flax meal inclusion rates.
- Personal Care:Hair and skin formulations utilizing flax protein film-forming characteristics. French cosmetics laboratories are developing protein-lignan complexes for anti-aging topicals.
Functional Foods commands the largest volume commitments; Sports Nutrition is climbing the fastest.
End User:
Procurement sophistication varies by buyer type, with nutraceutical companies demanding certificate-of-analysis depth that feed producers rarely require.
- Food Manufacturers:Multinational bakery and meat alternative producers specifying organic and non-GMO verification chains. Prairie processors are retrofitting elevators to secure captive supply for annual offtake agreements.
- Nutraceutical Companies:Supplement brands requiring amino acid profiling and digestibility scoring documentation. Health Canada and FDA labeling clarity is reshaping their formulation claim strategies.
- Feed Producers:Dairy and poultry operations prioritizing cost-per-unit-protein over functional specifications. Manitoba and Saskatchewan elevator networks serve this segment through bulk meal distribution.
- Cosmetics Producers:Premium skincare and haircare formulators seeking film-forming and moisture-binding properties. French and Italian cosmetics clusters are testing flax hydrolysate integration.
Food Manufacturers dominate current procurement volume; Nutraceutical Companies are gaining share fastest.
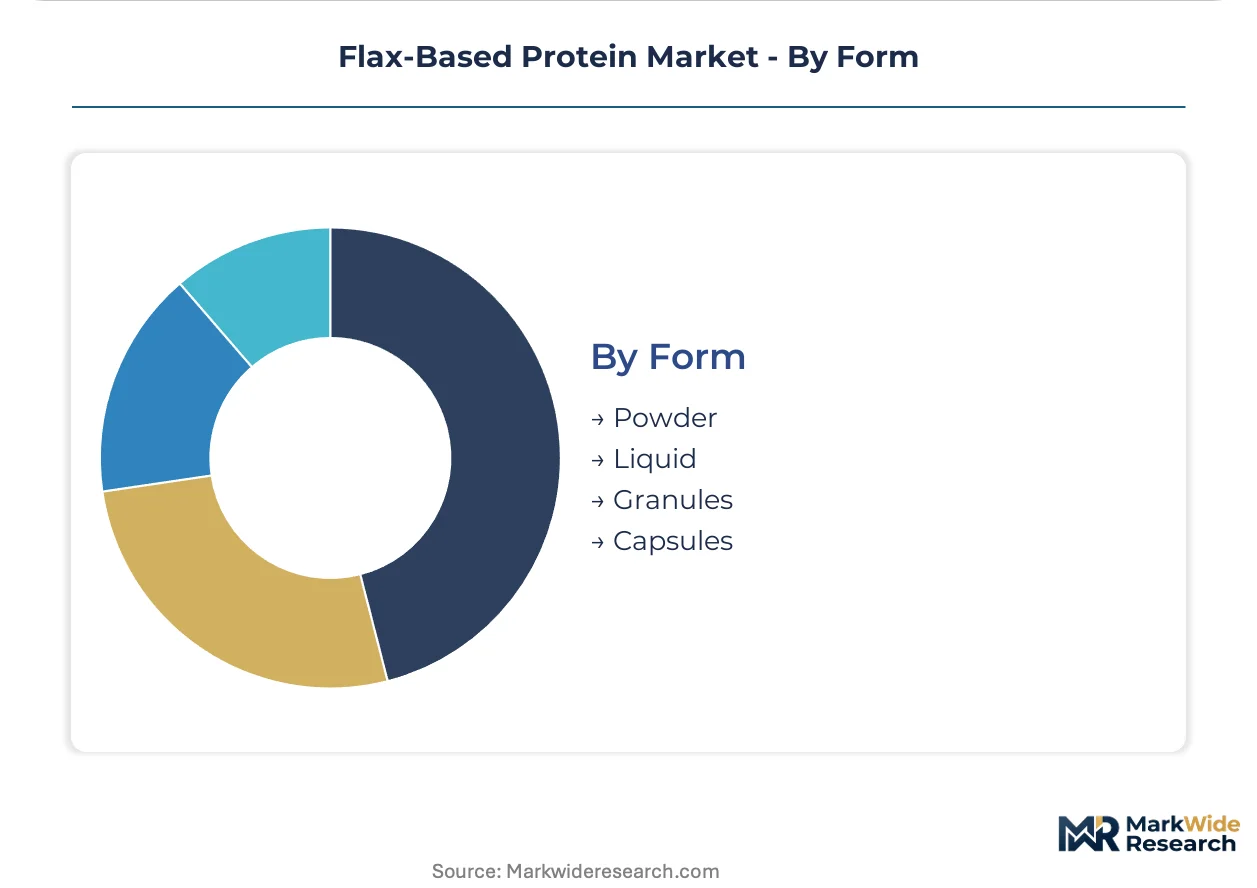
Form:
Processing infrastructure and shelf stability requirements segment manufacturing investment between spray-dried powders and specialized liquid handling systems.
- Powder:Dominates manufacturing throughput due to shelf stability, blending versatility, and lower logistics costs. Spray-drying towers at Manitoba extraction facilities process the majority of North American powder output.
- Liquid:Ready-to-drink protein beverages and beverage fortification requiring aseptic processing. Canadian sports nutrition brands are piloting liquid flax protein concentrates.
- Granules:Controlled-release formulations and feed pelleting applications. US pet food manufacturers are testing granulated flax protein for omega-3 delivery in grain-free formulations.
- Capsules:Dietary supplement delivery with precise dosing requirements. Nutraceutical encapsulation facilities in California and New Jersey are expanding flax protein capsule lines.
Powder captures the majority of processing capacity; Liquid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canadian Prairies anchor flax-based protein supply chains, with Manitoba and Saskatchewan elevator networks retrofitting for protein fractionation. Processing infrastructure concentrates where flaxseed cultivation density meets grain handling expertise.
Canada
Sports nutrition contract manufacturers in Manitoba are installing dedicated flax isolate blending lines to serve US brands seeking allergen-free positioning. Health Canada and the PMRA govern pesticide residue thresholds in oilseed crops while streamlining export certification alignment with Codex Alimentarius. Winnipeg and Saskatoon extraction facilities are securing annual offtake agreements with CPG brand R&D teams.
United States
Premium dog and cat food manufacturers are testing flax protein for omega-3 delivery in grain-free formulations, expanding beyond human nutrition. The FDA's updated guidance on plant protein labeling clarity is reshaping product positioning strategies for nutraceutical companies. California and New York nutraceutical distributors are expanding omega-3 integrated SKUs through capsule and tablet formats.
Germany
Food technologists in German bakery clusters are reformulating clean-label bread lines with flax concentrate to replace gluten and soy isolates. EFSA's novel food authorization pathway creates compliance thresholds for flax protein isolates entering European formulations. Cologne and Frankfurt ingredient distributors are restructuring toxicology packages to align with updated protein characterization protocols.
France
Premium skincare and haircare formulators in French cosmetics laboratories are developing protein-lignan complexes for anti-aging topicals. EFSA's tightened amino acid profiling standards affect dossier preparation timelines for flax-derived ingredients. Paris and Lyon encapsulation facilities are expanding flax protein capsule lines for precise dosing requirements.
Netherlands
Dutch food manufacturers are accelerating flax protein adoption in meat alternative formulations driven by pediatric allergen avoidance protocols. The EU Green Deal and CSRD reporting requirements influence sustainable sourcing verification for Prairie processors. Amsterdam and Rotterdam ingredient distributors are establishing direct procurement relationships displacing traditional intermediaries.
Flax-Based Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue omega-3 functional convergence and pet nutrition adjacencies. The market structures around three archetypes: Prairie-anchored processors with captive grain elevator networks, diversified nutrition ingredient houses with sports nutrition portfolios, and specialized omega-3 integrated formulators serving nutraceutical clients. Capacity expansion and strategic partnerships dominate competitive moves, with aqueous extraction line investments and annual offtake agreements concentrating volume commitments.
Within the diversified nutrition tier, Glanbia Nutritionals and Ingredion Incorporated exemplify ingredient houses competing through sports nutrition portfolios where plant proteins anchor new product lines. Richardson International and Bioriginal Food & Science Corp. represent Prairie-anchored specialists leveraging Manitoba and Saskatchewan infrastructure. Cargill, Incorporated and Archer Daniels Midland Company occupy positions as integrated agribusiness operators with oilseed processing scale. Roquette Frères and Bunge Limited sit within the European and global oilseed processing tier.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Glanbia Nutritionals |
| Austrade Inc. |
| Richardson International |
| Bioriginal Food & Science Corp. |
| Bunge Limited |
| Ingredion Incorporated |
| Roquette Frères |
| Others |
Supply & Pricing Matrix
Captive upstream control over Prairie elevator networks anchors both supply security and pricing power for Canadian flax protein processors, creating structural advantages that commodity traders and independent formulators cannot replicate without seven-figure extraction investments.
Pricing Analysis
Service bundling separates contract-based offtake agreements with certified organic verification from spot-market concentrate sales lacking technical support. Three-tier pricing structure across premium isolate, standard concentrate, and economy meal tiers reflects protein purity, amino acid profiling depth, and EFSA dossier completion status. Cost compression in concentrate tiers is intensifying because Manitoba processors are expanding mechanical pressing capacity faster than isolate demand growth. Feed producers exhibit highest price sensitivity, while German nutraceutical companies absorbing EFSA-compliant isolate volumes show lowest elasticity.
Supply Chain Analysis
Meal and fiber co-product streams flow back into dairy rations and pet nutrition formulations, minimizing waste disposal costs while capturing secondary revenue. Raw material sourcing draws from Manitoba, Saskatchewan, and North Dakota flaxseed cultivation belts where oilseed processing infrastructure concentrates. Supply chain risk centers on single-region weather exposure across the Canadian Prairies, with drought or frost events capable of disrupting global isolate availability. Distribution runs through direct procurement relationships between extraction facilities and CPG brand R&D teams, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around aqueous extraction capacity and EFSA novel food certification timelines prop pricing power for qualified processors, creating a seller-favorable environment where volume commitments outrun installed capacity.
For Market Incumbents: Deepen backward integration into certified organic flaxseed acreage through long-term grower contracts, securing captive supply against commodity price spikes. Expand membrane filtration capacity in Manitoba to capture sports nutrition isolate demand before competitors complete facility permitting. Prioritize EFSA dossier completion for hydrolysate variants to lock in European nutraceutical offtake.
For New Entrants and Emerging Players: Direct-to-veterinarian digital channels offer the most penetrable route for premium pet nutrition flax protein positioning, bypassing established human-food distributor relationships. Target US grain-free pet food manufacturers with omega-3 functional convergence messaging, emphasizing lignan-protein co-delivery. Lead with certified organic verification and small-batch flexibility that Prairie giants cannot match.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified nutrition ingredient houses seeking plant protein portfolio completion. Long-term viability hinges on aqueous extraction technology scale and regulatory certification depth rather than commodity trading relationships. Monitor EFSA novel food approval timelines for flax protein hydrolysates as the inflection signal for European market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Manitoba processors installing automated protein fractionation lines reduce batch-to-batch variation for sports nutrition clients. |
| EFSA Novel Food Dossier Completion | Isolate suppliers restructuring toxicology packages align with tightened amino acid profiling standards for German and French market entry. |
| Direct Procurement Relationship Formation | Annual offtake agreements between Prairie extraction facilities and US CPG R&D teams displace traditional distributor intermediaries. |
| Certified Organic Acreage Integration | Backward control over Saskatchewan and Manitoba grower contracts secures non-GMO verification chains for premium tier positioning. |
| Pet Nutrition Formulation Partnership | US premium dog and cat food manufacturers testing flax protein omega-3 delivery open grain-free formulation white space. |
Research Methodology
Independent corroboration across Health Canada regulatory filings, EFSA novel food authorization databases, and Prairie grain elevator capacity reports underwrites the qualitative findings. Primary interviews with extraction facility operations managers, sports nutrition contract manufacturing executives, and German nutraceutical formulators combined with secondary validation from FDA guidance documents, USDA oilseed production statistics, and Codex Alimentarius residue threshold standards. Bottom-up facility capacity modeling and top-down demand segmentation triangulation anchored volume estimates.
Comparable historical periods spanning mechanical pressing expansion and aqueous extraction adoption cycles anchored the forecast window calibration. The analytical framework segments across product type tiers, application verticals, end-user procurement sophistication levels, and geographic regulatory clusters throughout the forecast period. CAGRs derived from protein digestibility scoring evolution, clean-label substitution rates in bakery and meat alternatives, and omega-3 functional convergence adoption curves in nutraceutical formulations.
The model holds under stable Health Canada and FDA labeling guidance conditions; deviation in EFSA amino acid profiling standard revisions or Prairie drought frequency would shift isolate premium sustainability. Practitioners should monitor EFSA hydrolysate dossier approval velocities and Manitoba membrane filtration capacity commissioning schedules for early demand-supply balance signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Soy- Based Food Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Plant Chocolate Protein Powder Market