
 Fermented Plant-Based Food Market | 2026-2036
Fermented Plant-Based Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Plant-Based Food Market Insights
Specialty store distribution is fragmenting as fermented plant-based SKUs multiply beyond traditional health-food aisles into conventional retail. Danone S.A. leverages its dairy-alternative infrastructure to secure refrigerated placement across European supermarket chains. Nestlé S.A. anchors its position through controlled-temperature supply networks that preserve live cultures in transit. GT's Living Foods differentiates via unpasteurized, raw-fermentation positioning that commands premium placement in independent grocers.
Fermented plant-based food denotes products derived from legumes, vegetables, or grains subjected to controlled microbial transformation, typically involving Lactobacillus, Aspergillus, or Rhizopus cultures at temperatures between 20°C and 35°C over periods ranging from 24 hours to several weeks, yielding bioactive compounds including organic acids, peptides, and viable probiotics intended for human consumption. The primary commercial purpose centers on delivering functional nutrition with extended shelf stability without synthetic preservatives. Tempeh and kimchi currently lead product type traction, with tempeh sustaining margin pools through its protein density and clean-label appeal while kimchi captures velocity in Asian and Western fusion cuisines. Probiotics functionality commands the strongest pricing power within functionality segments, as live-culture claims require cold-chain integrity that filters out lower-capability competitors.
FDA oversight of fermented food safety through hazard analysis requirements, combined with EFSA novel food assessments for non-traditional fermentation substrates, shapes market access timelines and capital deployment decisions. BIS standards in India and FSSAI labeling mandates for probiotic count claims add compliance layers for exporters targeting South Asian markets. Stakeholders must monitor evolving strain-specific health claim regulations, as jurisdictions diverge on whether generic probiotic labeling suffices or controlled human studies become mandatory for market participation.
Market Dynamics
Live-culture cold-chain integrity requirements are bifurcating the competitive landscape between capitalized operators with refrigerated distribution networks and ambient-stable commodity producers, concentrating margin capture among temperature-capable players.
Growth Catalysts
- EFSA Novel Food pathways:Streamlined safety assessments for traditional fermentation substrates accelerate European market entry for heritage formats like tempeh and natto.
- Microbiome health positioning:Clinical validation of strain-specific benefits drives pharmacy and clinic channel expansion for refrigerated probiotic foods in Germany and South Korea.
- Urban health-food corridor density:Seoul, Berlin, and Los Angeles cluster specialty retail and foodservice demand, creating efficient last-mile distribution nodes for live-culture products.
Market Restraints
- Soybean price volatility:Tempeh margins compress during South American harvest disruptions, exposing protein-dependent operators to agricultural commodity cycles.
- Cold-chain infrastructure gaps:Last-mile refrigerated capacity constraints in secondary Indian and Southeast Asian cities limit viable distribution radius for unpasteurized SKUs.
- FDA hazard analysis compliance:Preventive control requirements for acidified foods impose documentation burdens that favor larger facilities over artisanal producers.
Strategic Opportunities
- FSSAI probiotic count standardization:India's emerging labeling mandates create first-mover advantage for exporters with validated culture enumeration protocols.
- Controlled-environment fermentation:Precision temperature and humidity systems enable consistent quality in non-traditional production geographies.
- Direct-to-subscription channels:Cold-chain subscription models bypass conventional retail slotting fees while capturing recurring revenue from committed microbiome-conscious consumers.
Industry Challenges
- Strain banking and IP control:Proprietary culture isolation and patent thickets around commercial Lactobacillus and Rhizopus strains create licensing friction for new entrants.
- Live-culture shelf-life verification:Accelerated stability testing protocols require specialized analytical capacity that strains mid-tier quality assurance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Plant-Based Food Market |
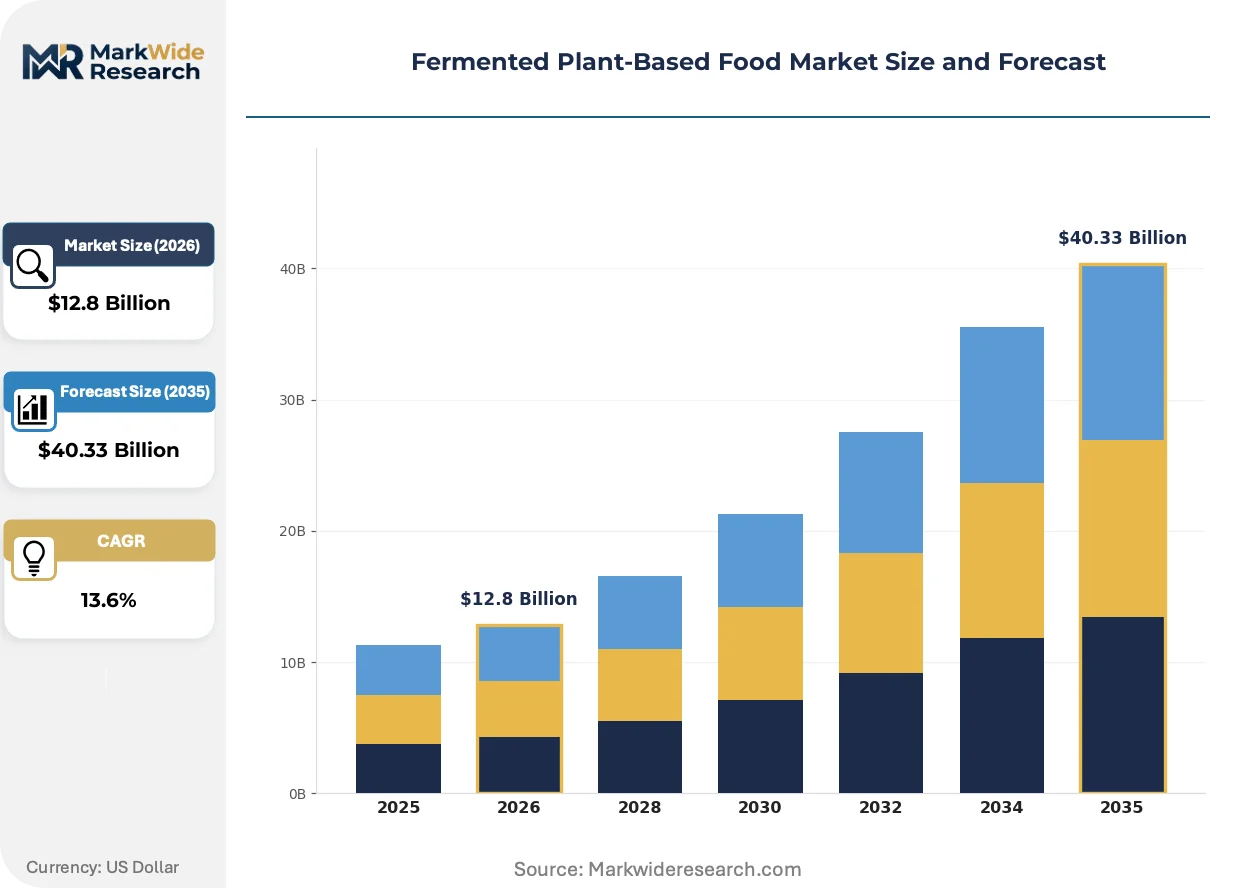
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $40.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempeh, Kimchi, Sauerkraut, Miso End Use: Households, Restaurants, Cafes, Health Food Stores Functionality: Probiotics, Antioxidants, Nutrient-Rich, Digestive Health Distribution Channel: Online, Supermarkets, Specialty Stores, Farmers Markets |
| Companies Covered | Danone S.A., Nestlé S.A., General Mills, Inc., GT’s Living Foods, Lifeway Foods, Califia Farms, LLC, Yakult Honsha Co., Ltd., Chobani, LLC, Perfect Day, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Plant-Based Food Market Trends and Innovations
Sensor-enabled fermentation monitoring is compressing batch-to-batch variability while regulatory jurisdictions race to codify live-culture claims, reshaping how producers validate and communicate functional benefits.
Smart fermentation systems deploying IoT-enabled pH and temperature logging is digitizing quality assurance workflows across commercial tempeh and kimchi facilities. Mid-scale producers in South Korea and Germany adopt cloud-connected bioreactors to reduce spoilage rates and standardize organic acid profiles. This digitization enables real-time intervention that preserves viable probiotic counts through distribution.
EU Green Deal Farm-to-Fork targets are mandating reduced synthetic additive dependence in processed foods, elevating fermentation-derived preservation as a compliant pathway. EFSA guidance on fermented food health claims tightens substantiation requirements, forcing reformulation toward strains with documented clinical outcomes. Premium-positioned brands respond by commissioning human intervention studies for specific Lactobacillus subspecies.
Health-food buyers now prioritize verified live-culture counts over generic probiotic labeling, compressing preference toward third-party certified products. Independent grocers in Los Angeles and Berlin curate refrigerated sets around transparency protocols that disclose strain identity and CFU viability at expiration. This certification-driven preference shift disadvantages ambient-stable competitors lacking cold-chain credibility.
Fermented Plant-Based Food Market Segmentation
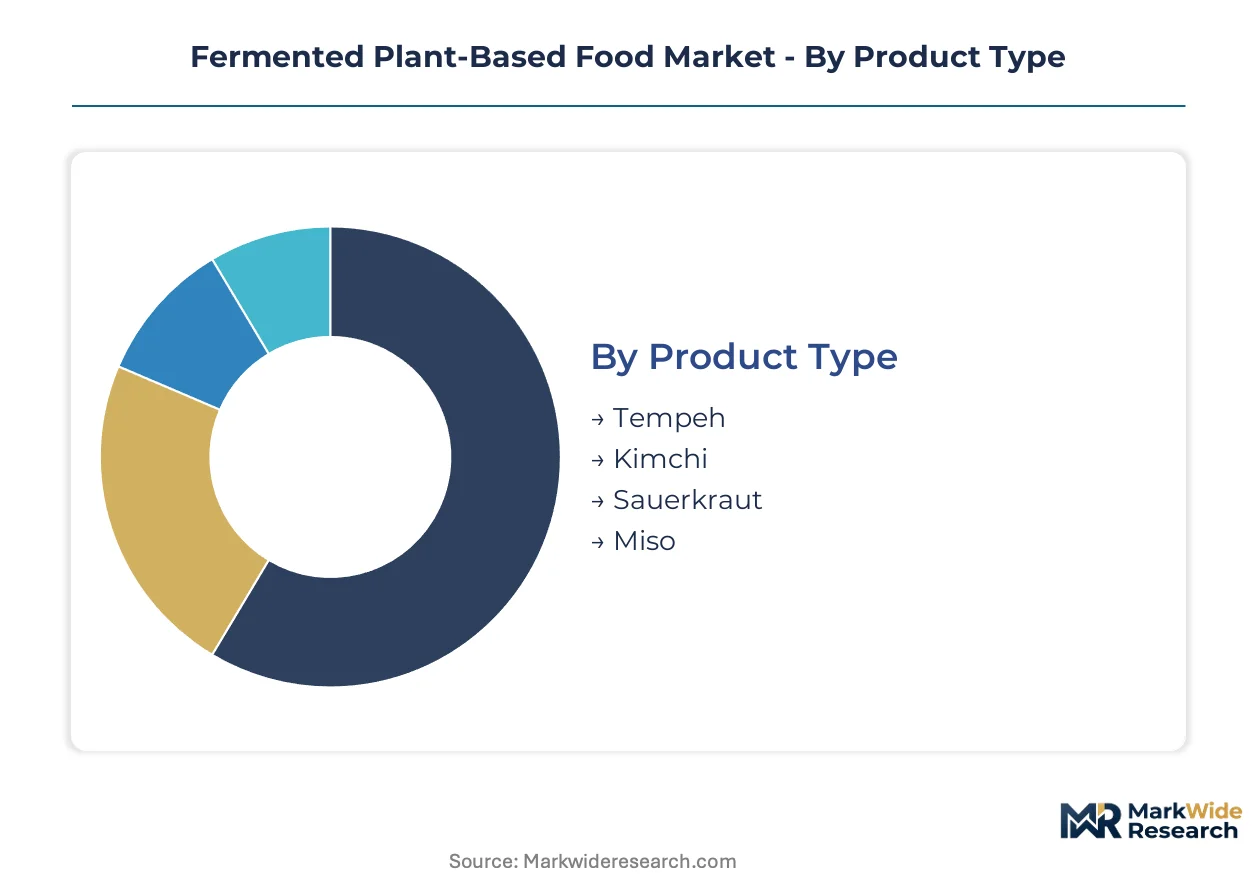
Fermented plant-based food segmentation reveals how cold-chain requirements and microbiome positioning split commercial strategies. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across formats, with live-culture products demanding cold-chain monitoring and culture viability guarantees that ambient-stable alternatives avoid.
- Tempeh:Rhizopus-fermented soybean cakes deliver protein density exceeding 15g per 100g serving with complete amino acid profiles. Demand clusters in Berlin and Los Angeles health-food corridors where clean-label positioning commands refrigerated placement premiums. Margin pools concentrate among operators with controlled-temperature supply networks.
- Kimchi:Lactobacillus-driven fermentation of napa cabbage and radishes produces lactic acid concentrations between 0.6% and 1.5%. Seoul's urban health-food corridors anchor velocity, with fusion cuisine adoption expanding into Los Angeles restaurants seeking fermented depth without animal ingredients. Cold-chain integrity filters out lower-capability competitors.
- Sauerkraut:Shredded cabbage fermentation delivers ambient-stable formats with reduced service intensity. German retail chains stock pasteurized variants alongside live-culture premium lines.
- Miso:Aspergillus-fermented soybean paste requires extended aging periods creating inventory carrying costs. Japanese and South Korean production traditions dominate supply.
Tempeh holds the largest share; momentum sits with kimchi as Western fusion cuisine adoption accelerates.
End Use:
Application concentration determines pricing power, with foodservice operators prioritizing consistent culture viability while household buyers emphasize convenience and label transparency.
- Households:Direct-to-consumer channels capture recurring revenue from microbiome-conscious subscribers. Cold-chain subscription models bypass conventional retail slotting fees.
- Restaurants:Foodservice operators in Seoul, Berlin, and Los Angeles cluster demand for unpasteurized formats. Live-culture claims require documented strain identity and CFU viability.
- Cafes:Smaller operators favor ambient-stable fermented ingredients to reduce refrigeration capital requirements. Menu integration focuses on flavor complexity rather than probiotic positioning.
- Health Food Stores:Independent grocers curate refrigerated sets around third-party certification protocols. Transparency requirements disadvantage generic probiotic labeling.
Households dominate volume; restaurants generate the steepest expansion trajectory as foodservice fermentation menus proliferate.
Functionality:
Cost tier stratification separates premium-positioned clinical-validation formats from commodity preservation claims, with strain-specific substantiation commanding pricing multiples.
- Probiotics:Live-culture claims require cold-chain integrity and enumerated CFU counts at expiration. EFSA guidance tightens substantiation requirements, forcing reformulation toward strains with documented clinical outcomes.
- Antioxidants:Fermentation-derived phenolic compounds appeal to clean-label positioning without live-culture logistics. Ambient distribution reduces capital requirements.
- Nutrient-Rich:Bioactive peptide and vitamin B12 enhancement targets vegetarian nutritional gaps. Tempeh anchors this positioning through protein density.
- Digestive Health:Organic acid profiles from lactic fermentation support gut comfort claims without specific strain identification. Regulatory burden remains lighter than probiotic positioning.
Probiotics commands premium pricing; digestive health is gaining share fastest as entry barriers attract mid-tier competitors.
Distribution Channel:
Supply concentration among temperature-capable operators creates channel-specific margin structures, with specialty retail capturing certification premiums and online channels absorbing logistics complexity.
- Online:Direct-to-subscription models enable cold-chain control from fermentation facility to consumer door. Recurring revenue structures reward culture viability guarantees.
- Supermarkets:European chains expand refrigerated shelf space for heritage formats like tempeh and kimchi. Danone leverages dairy-alternative infrastructure for placement.
- Specialty Stores:Independent grocers in Los Angeles and Berlin curate around transparency protocols. Third-party certification filters assortment.
- Farmers Markets:Local producers bypass regulatory documentation burdens for direct sale. Limited scale constrains strain banking investment.
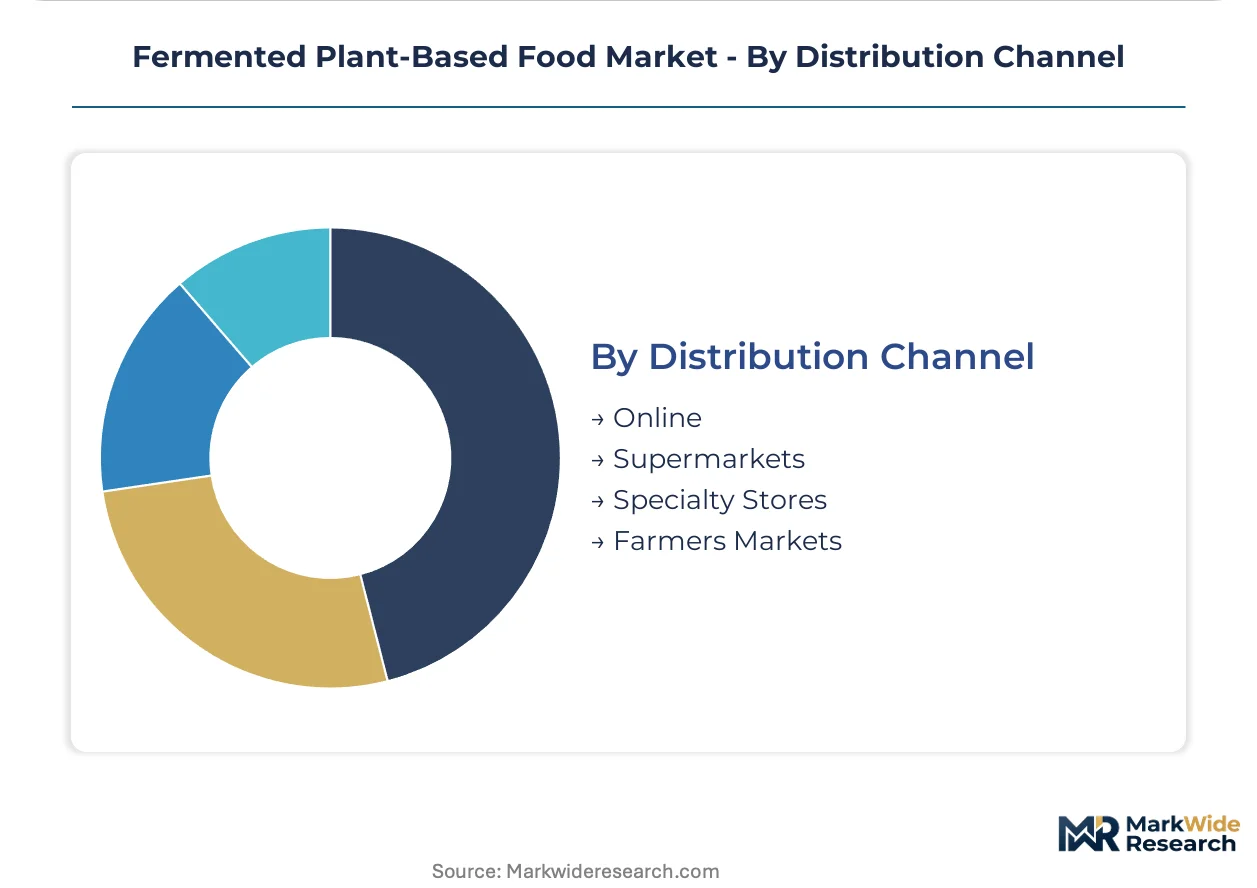
Supermarkets hold the largest share; online channels represent the fastest-growing trajectory as subscription microbiome commerce scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European distribution capacity for live-culture products, while Incheon International Airport's pharmaceutical-grade cargo terminals anchor South Korean export logistics for fermented foods.
United States
FDA hazard analysis requirements for acidified foods filter artisanal producers from scaled operations. Los Angeles health-food corridors cluster independent grocers curating third-party certified refrigerated sets. Subscription cold-chain models bypass conventional retail slotting fees in California urban markets.
Germany
EFSA novel food assessments for non-traditional fermentation substrates reshape product approval timelines. Berlin's urban health-food corridors concentrate specialty retail demand for tempeh and unpasteurized kimchi. Pharmacy channel expansion for refrigerated probiotic foods accelerates in Bavaria and North Rhine-Westphalia.
South Korea
MFDS strain-specific health claim regulations drive clinical validation investments for Lactobacillus subspecies. Seoul's dense health-food corridor network creates efficient last-mile nodes for live-culture distribution. Cloud-connected bioreactors digitize quality assurance in Gyeonggi-do fermentation facilities.
India
FSSAI probiotic count labeling mandates create compliance layers for exporters targeting South Asian markets. Cold-chain infrastructure gaps in secondary cities constrain distribution radius for unpasteurized SKUs. Maharashtra and Karnataka urban corridors pilot refrigerated placement for heritage fermentation formats.
Japan
METI standards for controlled-environment fermentation enable consistent quality in non-traditional production geographies. Tokyo's foodservice operators demand documented strain identity and CFU viability for menu integration. Precision temperature systems reduce spoilage rates in Chubu region commercial facilities.
Fermented Plant-Based Food Market Competitive Landscape
On the supply side, the industry is bifurcating between capitalized operators with refrigerated distribution networks and ambient-stable commodity producers. Three strategic archetypes dominate: multinational food conglomerates leveraging dairy-alternative infrastructure, specialized live-culture purists commanding premium placement, and controlled-fermentation technology providers. Competitive moves concentrate on cold-chain capacity expansion and strain banking intellectual property control.
Within the multinational tier, Danone S.A. and Nestlé S.A. exemplify scale-driven refrigerated placement strategies across European supermarket chains. GT's Living Foods occupies a position among specialized live-culture purists, anchoring premium positioning in independent grocer channels through unpasteurized fermentation protocols.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestlé S.A. |
| General Mills, Inc. |
| GT's Living Foods |
| Lifeway Foods |
| Califia Farms, LLC |
| Yakult Honsha Co., Ltd. |
| Chobani, LLC |
| Perfect Day, Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in South Korean controlled-environment fermentation facilities is compressing batch economics and forcing producers toward either premium live-culture positioning or ambient-stable commoditization, with cold-chain capability becoming the decisive pricing discriminator.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain integrity. Premium tiers command placement multiples through third-party CFU viability certification and documented strain identity. Pricing pressure stems from soybean input volatility in Brazilian supply corridors. Household subscribers exhibit lowest price sensitivity; foodservice operators in Los Angeles and Berlin negotiate hardest on volume contracts.
Supply Chain Analysis
Tariff exposure between the United States and China on fermentation equipment components dominates supply chain risk assessment. Production gravity centers on Indonesia, South Korea, and Germany for heritage formats. Rhizopus starter cultures, napa cabbage varietals, and refrigerated transport units constitute critical input dependencies. Distribution runs through temperature-capable logistics networks anchored at Rotterdam and Incheon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermented plant-based food markets are cycling through a recovery phase as South American soybean harvests stabilize and cold-chain infrastructure investments in Seoul and Berlin mature.
For Market Incumbents: Harden cold-chain capacity in Gyeonggi-do and Bavaria to defend margin pools against ambient-stable commodity entrants. Prioritize strain banking intellectual property control through proprietary Lactobacillus isolation protocols. EFSA novel food assessment streamlining creates consolidation opportunity for heritage format producers with validated safety dossiers. For New Entrants and Emerging Players: Mid-tier Indian urban corridors represent the most penetrable entry point as FSSAI probiotic count standardization creates first-mover compliance advantages. Target direct-to-subscription channels in Maharashtra and Karnataka to bypass conventional retail slotting barriers. Cloud-connected fermentation monitoring systems enable quality parity without legacy infrastructure investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-environment fermentation technology providers. Five-to-ten-year viability favors acquisition targets with validated culture enumeration protocols and refrigerated distribution node control. Monitor EFSA strain-specific health claim guidance evolution as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Investment | Proprietary culture isolation secures IP moats against generic probiotic competitors in European markets. |
| Cold-Chain Capacity Expansion | Refrigerated logistics node control filters out temperature-incapable rivals in Seoul and Berlin corridors. |
| Direct-to-Subscription Launch | Recurring revenue models bypass supermarket slotting fees while capturing microbiome-conscious household demand. |
| Clinical Validation Partnership | Human intervention studies for specific Lactobacillus subspecies satisfy tightening EFSA substantiation requirements. |
| Controlled-Environment Technology Licensing | Precision fermentation systems enable quality consistency in non-traditional production geographies like India. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation facility operations directors, refrigerated logistics procurement managers, retail category buyers, and regulatory affairs specialists, then refined against customs records, EFSA novel food submission databases, cold-chain infrastructure investment filings, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Demand-supply-balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled include product type, functionality claim tier, distribution channel, and regional cold-chain maturity. CAGRs derived from historical trajectory analysis adjusted for regulatory pathway acceleration and input cost volatility. Forecast inputs incorporated soybean futures curve movements and refrigerated transport capacity expansion pipelines.
Practitioners should monitor South American agricultural output volatility, EFSA strain-specific claim guidance evolution, and Indian cold-chain infrastructure buildout pace for early signals. Forecasts reflect assumptions around regulatory pathway stability and commodity input normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Rice Protein Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
Middle East and Africa Plant-Based Meat and Dairy Products Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Germany Soy Protein Market
Plant Based Food
Europe Meat Substitutes Market