
 Kava Root Extract Market | 2026-2036
Kava Root Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Kava Root Extract Market Analysis
Single-serve capsule and tincture bundling is shifting buyer choice away from bulk powder toward convenience-oriented configurations. NOW Foods leverages vertical integration from Pacific Island sourcing to finished goods, sustaining consistent supply for North American retailers. Gaia Herbs differentiates through certified organic kava cultivars and stringent heavy-metal testing protocols. Kona Kava Farm anchors its position through direct farm-to-consumer channels that control pricing and traceability narratives.
Kava root extract is a concentrated preparation derived from the rhizome of Piper methysticum, standardized typically to 30% kavalactones by weight through supercritical CO2 or ethanol extraction, and used primarily for anxiolytic and sedative applications in dietary supplements and functional beverages. Powder formulations retain the largest volume share due to lower unit costs and flexibility in bulk manufacturing, though capsules capture margin pools through dosage precision and compliance advantages in regulated markets. Liquid extracts and tinctures represent the fastest-growing configuration as beverage innovators and wellness centers seek rapid-onset delivery formats.
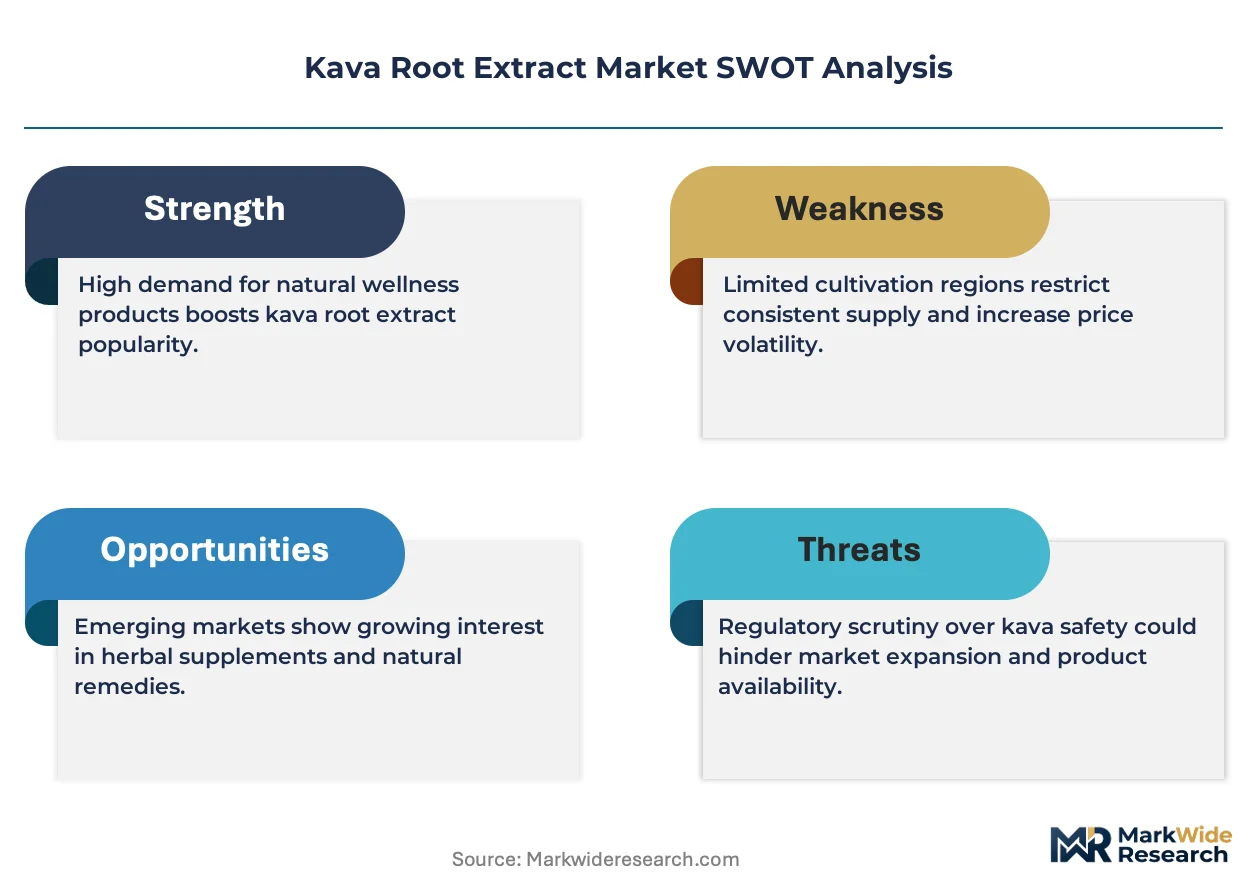
FDA maintains active import alerts on kava-containing products, compelling suppliers to demonstrate GMP compliance and raw material identity testing for US market entry. EFSA has assessed kavalactone hepatotoxicity risk, creating a fragmented European landscape where national regulators like Germany's BfArM impose stricter controls than peripheral markets. Pacific Island quality standards and organic certification programs increasingly function as de facto trade requirements rather than optional premiums. Stakeholders must monitor evolving pharmacovigilance data and preemptively invest in clinical safety documentation to defend shelf space against competing adaptogens.
Market Dynamics
FDA import alerts on kava-containing products are forcing suppliers to restructure compliance infrastructure around raw material identity testing and GMP documentation, diverting capital from product innovation toward regulatory defense.
Growth Catalysts
- Supercritical CO2 extraction:This solvent-free technology preserves kavalactone integrity while eliminating residual ethanol concerns, opening formulation pathways for clean-label dietary supplements.
- Natural stress management demand:Wellness centers and functional beverage innovators are incorporating kava tinctures into relaxation-focused product lines as consumers seek alternatives to synthetic anxiolytics.
- US specialty health retail expansion:Direct-to-consumer e-commerce channels and boutique supplement retailers are building dedicated kava sections, normalizing the ingredient for mainstream anxiety-support shoppers.
Market Restraints
- EFSA hepatotoxicity assessments:European national regulators have imposed divergent kavalactone limits, fragmenting market access and forcing suppliers to maintain multiple formulation specifications.
- Pacific Island supply concentration:Vanuatu, Fiji, and Tonga dominate raw root cultivation, exposing buyers to cyclone disruption and political instability in small-island developing states.
- Kratom and CBD substitution:These competing botanical anxiolytics command larger marketing budgets and clearer regulatory pathways in North American markets.
Strategic Opportunities
- German BfArM pathway navigation:Suppliers who secure pharmacy-only distribution status can access Europe's highest-margin channel for anxiolytic botanicals.
- Liquid extract beverage innovation:Ready-to-drink relaxation shots and adaptogenic seltzers represent whitespace beyond traditional capsule and powder formats.
- Pacific Island organic certification:Farm-level traceability programs are becoming de facto trade requirements, rewarding early investors with preferential sourcing relationships.
Industry Challenges
- Pharmacovigilance documentation gaps:Suppliers lack longitudinal safety data to defend shelf space against ashwagandha and rhodiola with stronger clinical portfolios.
- Heavy-metal testing infrastructure:Volcanic soil cultivation in source regions necessitates capital-intensive ICP-MS equipment for cadmium and lead screening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kava Root Extract Market |
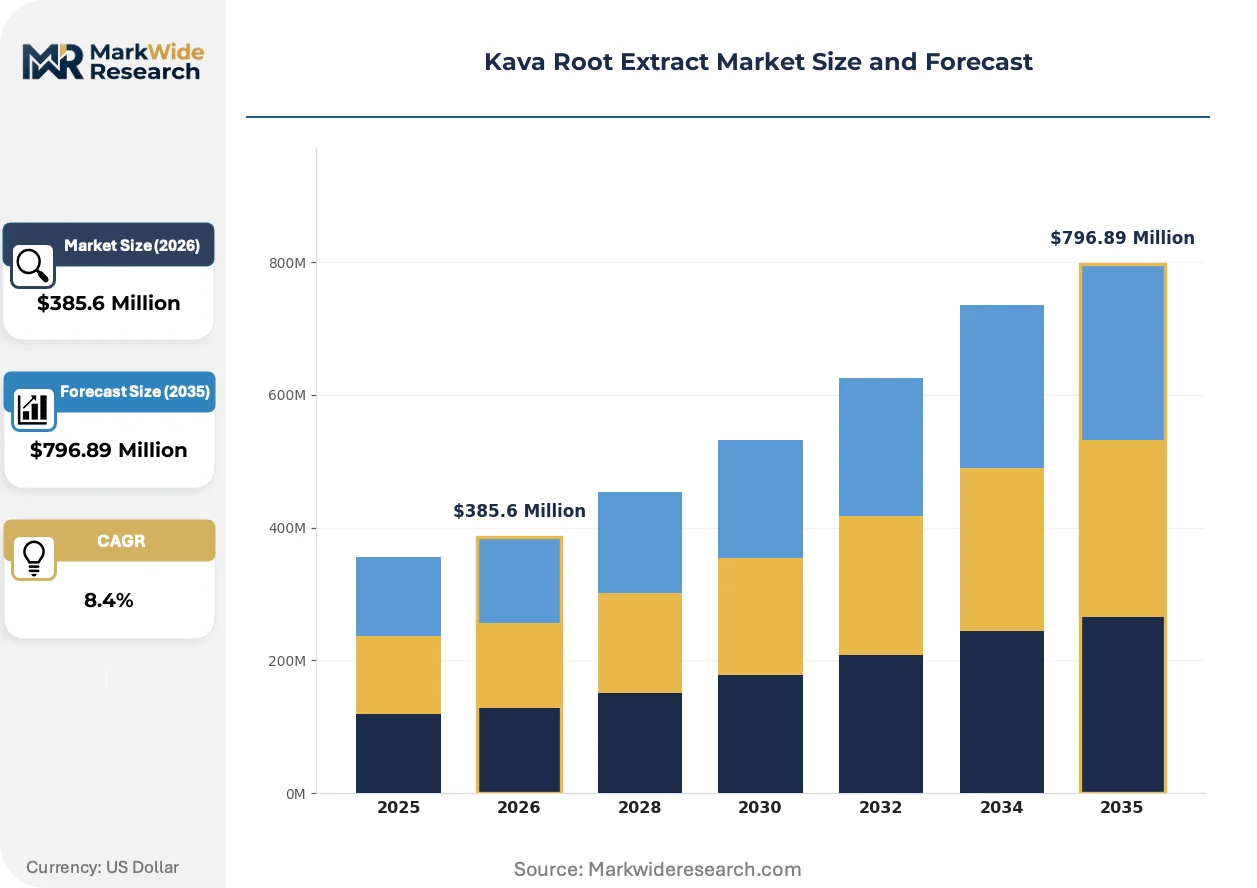
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tincture End User: Retail Consumers, Health Practitioners, Wellness Centers, Online Shoppers Application: Relaxation, Sleep Aid, Stress Relief, Dietary Supplement Distribution Channel: Supermarkets, Health Stores, E-commerce, Specialty Shops |
| Companies Covered | Gaia Herbs, NOW Foods, Botanic Healthcare, Kona Kava Farm, Fiji Kava Australia Ltd, Root of Happiness, Best Nutrition Product Inc., Mountain Rose Herbs, Natural Factors Nutritional Products Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kava Root Extract Market Emerging Trajectories
Extraction technology and regulatory documentation standards are converging to reshape how kava root extract moves from Pacific Island farms to finished goods shelves.
Supercritical CO2 extraction systems are modularizing production capacity for mid-scale supplement manufacturers. Equipment suppliers now offer containerized 50-liter units that eliminate the capital barrier of industrial-scale installations. This distributed processing model is compressing geographic distance between raw material reception and finished extract output.
REACH compliance documentation for novel botanical extracts is tightening substance characterization requirements. ECHA mandates for full constituent profiling now extend to kavalactone stereoisomer identification. German and French contract manufacturers are investing in chiral chromatography capabilities to preempt regulatory rejection at port of entry.
Subscription-based replenishment is displacing one-time bulk powder purchases among US direct-to-consumer channels. Wellness platforms are bundling monthly kava capsule shipments with meditation app access and sleep tracking integration. This behavioral shift concentrates customer lifetime value while reducing price sensitivity to per-unit extract costs.
Kava Root Extract Market Segmentation
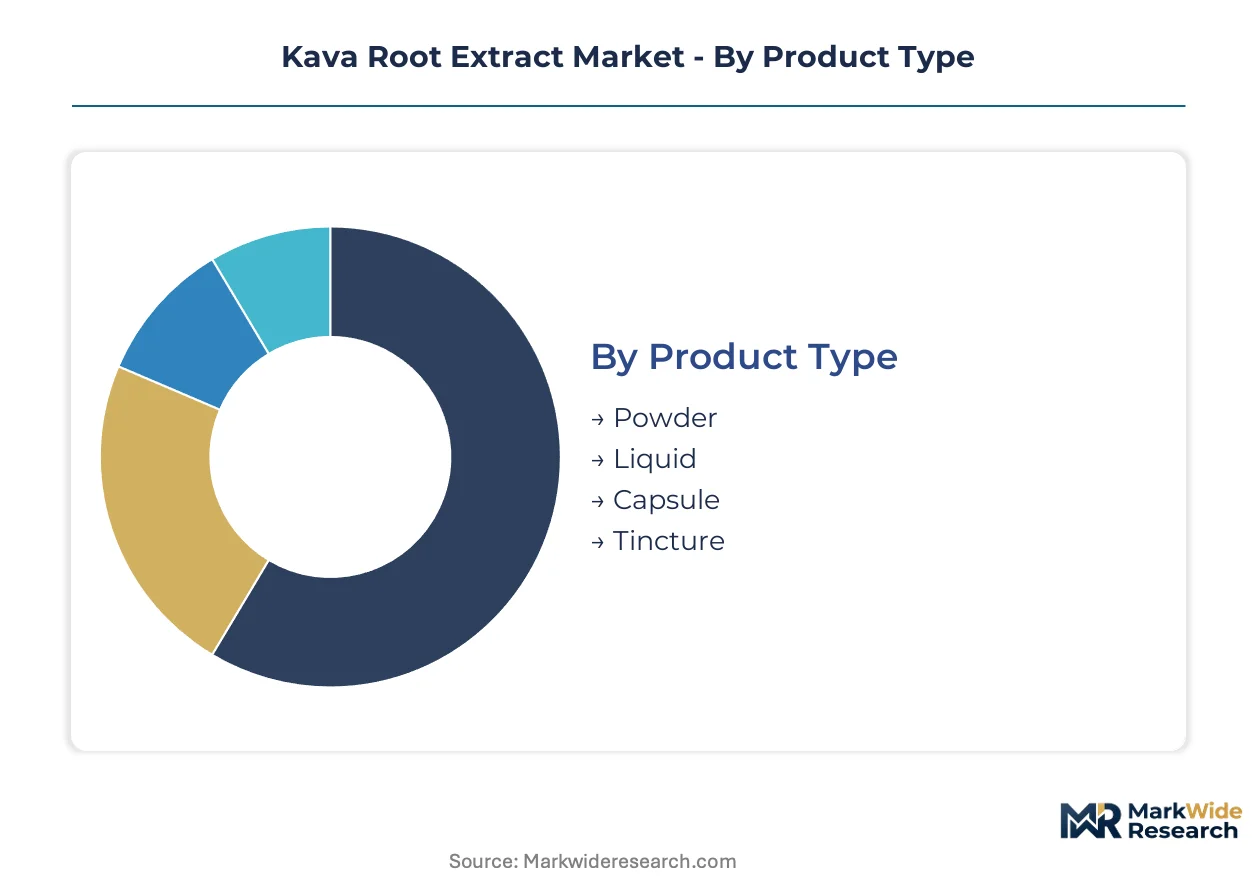
Kava extract suppliers configure product portfolios around divergent buyer sophistication levels and regulatory tolerance. Segmentation discipline separates bulk commodity plays from premium positioning strategies. Each dimension carries distinct margin implications and compliance burdens.
Product Type:
Powder commands volume through manufacturing flexibility, while liquid formats capture premium pricing through rapid bioavailability claims.
- Liquid:Supercritical CO2 or ethanol-derived concentrates standardized to 30% kavalactones enable rapid-onset delivery for functional beverage innovators. Wellness centers in the United States favor tincture formats for customizable dosing protocols, though FDA import alerts impose GMP documentation burdens on liquid suppliers.
- Capsule:Pre-measured unit doses simplify compliance with pharmacy-only distribution requirements in Germany's BfArM-regulated channel. NOW Foods and Gaia Herbs dominate this tier through certified organic sourcing and heavy-metal testing infrastructure that satisfies retail pharmacy gatekeepers.
- Powder:Bulk kavalactone material serves contract manufacturers blending multi-ingredient dietary supplements. Unit economics favor high-volume buyers with in-house encapsulation capacity.
- Tincture:Alcohol-based extracts target traditional use segments and home-compounding practitioners. Regulatory complexity varies by jurisdiction based on ethanol content thresholds.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquid.
End User:
Channel sophistication determines specification requirements and price elasticity across buyer categories.
- Wellness Centers:Licensed practitioners demand certificate of analysis documentation and batch-specific kavalactone profiles for liability protection. Subscription replenishment models are displacing one-time bulk purchases as platforms bundle kava with meditation app access.
- Online Shoppers:Direct-to-consumer channels normalize kava for anxiety-support seekers through educational content and review aggregation. Kona Kava Farm's farm-to-consumer traceability narratives resonate with this segment's provenance preferences.
- Retail Consumers:Mass-market buyers prioritize convenience and brand recognition over cultivar specificity. Shelf placement in specialty health retailers drives trial.
- Health Practitioners:Naturopathic and integrative medicine providers prescribe kava for stress management protocols requiring clinical safety documentation.
Volume concentrates with Online Shoppers. Margin expansion is steepest with Wellness Centers.
Application:
Functional positioning determines formulation complexity and competitive set overlap with other adaptogens.
- Stress Relief:Anxiolytic positioning competes directly with ashwagandha and rhodiola extracts, forcing suppliers to invest in pharmacovigilance documentation gaps. EFSA hepatotoxicity assessments fragment European market access for this application.
- Dietary Supplement:Capsule and tablet formats dominate this regulatory pathway, with FDA import alerts compelling raw material identity testing for US entry.
- Sleep Aid:Sedative applications require distinct kavalactone ratios emphasizing dihydrokavain and dihydromethysticin content.
- Relaxation:Functional beverage innovators incorporate kava tinctures into ready-to-drink relaxation shots, representing whitespace beyond traditional supplement formats.
Regulatory scrutiny is heaviest for Stress Relief. Formulation innovation is expanding fastest in Relaxation.
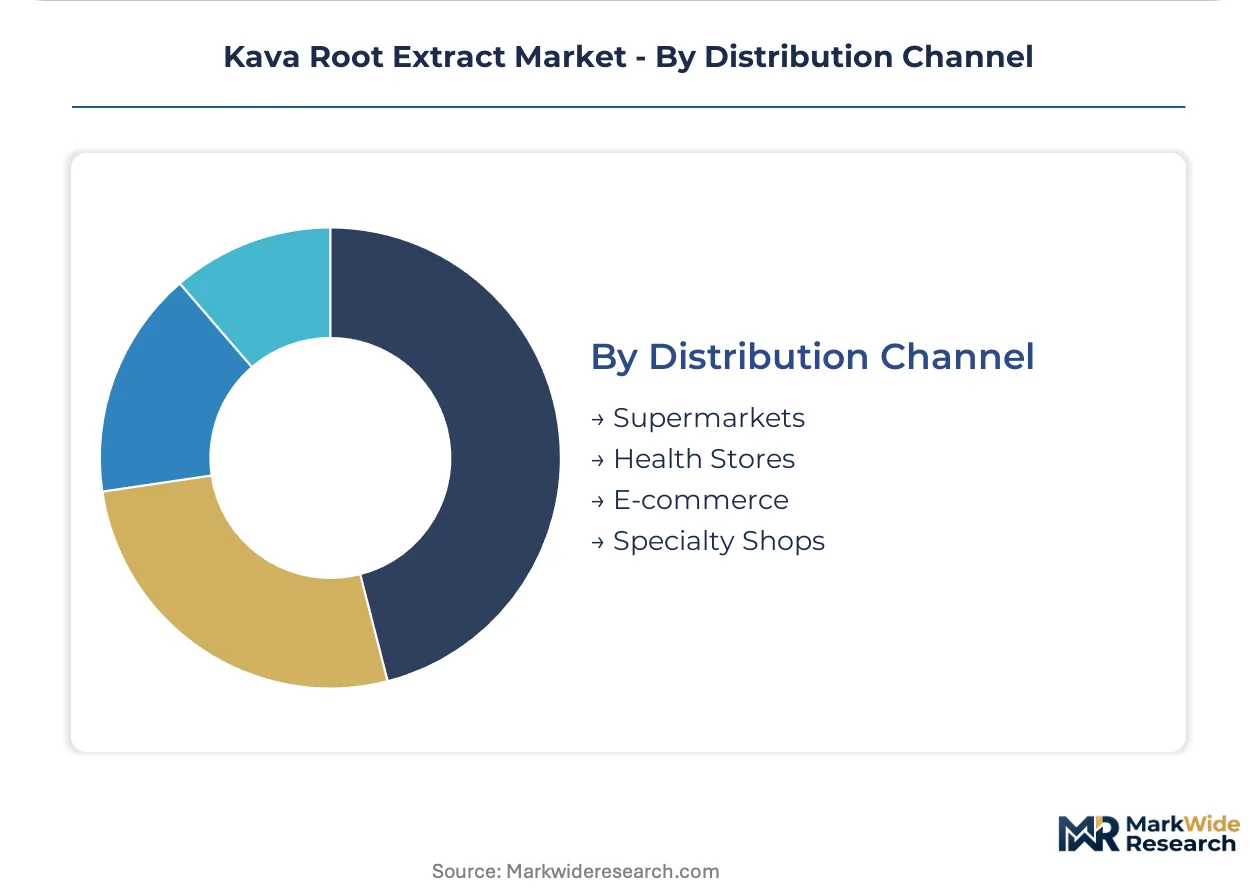
Distribution Channel:
Channel selection dictates compliance infrastructure investment and brand control parameters.
- E-commerce:Direct-to-consumer platforms bypass retail margin stacking while enabling subscription-based replenishment. Pacific Island organic certification functions as de facto trade requirement for premium positioning.
- Health Stores:Specialty retailers like those stocking NOW Foods and Gaia Herbs products require GMP compliance and third-party testing documentation.
- Specialty Shops:Boutique supplement retailers curate kava sections for mainstream anxiety-support shoppers, normalizing the ingredient through staff education.
- Supermarkets:Mass retail penetration remains limited by regulatory caution and consumer education gaps.
Established presence sits with Health Stores. Channel expansion is gaining share fastest through E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Island nations cultivate nearly all commercial kava root, while consumption concentrates in North American and European wellness markets. This geographic disconnect shapes trade flows, regulatory scrutiny, and value capture patterns across the supply chain.
United States
Specialty health retailers and direct-to-consumer e-commerce channels drive kava extract volume, with subscription-based replenishment models displacing one-time bulk purchases. FDA import alerts on kava-containing products compel suppliers to demonstrate GMP compliance and raw material identity testing for market entry. California-based wellness platforms bundle monthly kava shipments with meditation app access, concentrating customer lifetime value in the Pacific Coast corridor.
Germany
Pharmacy-only distribution channels command premium pricing for anxiolytic botanicals, with BfArM imposing stricter kavalactone limits than peripheral European markets. EFSA hepatotoxicity assessments have fragmented national regulatory pathways, forcing suppliers to maintain multiple formulation specifications. The Baden-Württemberg region hosts contract manufacturers investing in chiral chromatography capabilities to preempt port-of-entry rejection.
Vanuatu
Cyclone exposure and political instability in this small-island developing state concentrate raw material supply risk for global extract processors. Pacific Island quality standards and organic certification programs function as de facto trade requirements rather than optional premiums. Port Vila serves as the primary export hub, with farm-level traceability programs rewarding early investors with preferential sourcing relationships.
Australia
Therapeutic Goods Administration (TGA) scheduling of kava permits commercial import under strict quality standards, creating a regulated pathway distinct from neighboring Pacific markets. Domestic demand for traditional use segments supports tincture and noble cultivar specialists. Queensland's subtropical climate enables limited domestic cultivation trials, though commercial scale remains dependent on Pacific Island imports.
Fiji
Noble kava cultivar production sustains premium positioning in international extract markets, with cyclone disruption periodically constraining export volumes. The national kava quality standard certification program enables traceability claims that resonate with North American direct-to-consumer channels. Suva-based processors coordinate farm-gate purchasing across Viti Levu's volcanic soil cultivation zones, necessitating capital-intensive heavy-metal screening infrastructure.
Kava Root Extract Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with Pacific Island sourcing relationships and certified organic positioning. Mid-scale supplement manufacturers and direct-to-consumer farm brands occupy distinct tiers, with regulatory documentation capabilities separating pharmacy-channel suppliers from mass-market entrants. Consolidation pressure operates through backward integration into cultivation and forward integration into subscription-based distribution. Technology licensing for supercritical CO2 extraction and strategic partnerships with wellness platforms represent dominant competitive moves.
Among North American supplement specialists, Gaia Herbs and NOW Foods exemplify the certified organic, heavy-metal-tested archetype that satisfies retail pharmacy gatekeepers in regulated channels. Kona Kava Farm occupies a position within the direct farm-to-consumer tier, leveraging traceability narratives and subscription replenishment models that bypass traditional retail margin stacking. These three companies represent contrasting pathways to market access: regulatory compliance infrastructure, vertical sourcing control, and behavioral platform integration.
| Leading Market Players |
|---|
| Gaia Herbs |
| NOW Foods |
| Botanic Healthcare |
| Kona Kava Farm |
| Fiji Kava Australia Ltd |
| Root of Happiness |
| Best Nutrition Product Inc. |
| Mountain Rose Herbs |
| Natural Factors Nutritional Products Ltd. |
| Others |
Supply Flow & Price Mechanics
Specialized supercritical CO2 extraction technicians in Germany's Baden-Württemberg region command wage premiums that compress pricing spreads between pharmacy-grade and standard-tier kava extracts. Labor-cost differentials between European contract manufacturers and Pacific Island processors create a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Margin tightening in standard-grade powder reflects cyclone-driven supply interruptions from Vanuatu and Fiji. Three-tier pricing separates certified organic noble cultivar extracts from conventionally sourced materials from economy-grade bulk commodity powders. Cost compression in the economy tier accelerates because wellness centers and beverage innovators demand traceability documentation that smaller Pacific Island processors cannot furnish. Online shoppers exhibit the highest price sensitivity, while German pharmacy-channel buyers accept substantial premiums for BfArM-compliant documentation.
Supply Chain Analysis
Direct-to-consumer e-commerce channels handle subscription replenishment demand from North American anxiety-support seekers. Raw material sourcing draws from Vanuatu, Fiji, and Tonga, with noble cultivar production concentrated in Fiji's Viti Levu volcanic soil zones. Supply chain risk centers on cyclone exposure in small-island developing states that periodically constrains export volumes. Distribution runs through farm-to-consumer platforms, specialty health retailers, and German pharmacy-only channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pacific Island cultivation capacity limits constrain raw material availability, propping extract pricing across all tiers and rewarding early movers with secured sourcing relationships.
For Market Incumbents: Hedge against kratom and CBD substitution threats by deepening clinical safety documentation investments that ashwagandha and rhodiola competitors already possess. Secure backward integration into Vanuatu farm-level traceability programs before organic certification becomes mandatory for US retail access. Channel control through subscription-based replenishment platforms concentrates customer lifetime value and reduces price sensitivity. For New Entrants and Emerging Players: Wellness platforms bundling kava with behavioral health apps represent the most penetrable channel for digital-native entrants. White-space targets include ready-to-drink relaxation shots and adaptogenic seltzers beyond traditional supplement formats. A farm-to-consumer traceability narrative anchored in Pacific Island provenance claims bypasses retail margin stacking and resonates with provenance-seeking online shoppers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale supplement manufacturers possessing supercritical CO2 extraction capabilities and German BfArM pathway expertise given EFSA regulatory fragmentation across European markets. Long-term viability hinges on pharmacovigilance data accumulation that defends shelf space against better-documented adaptogens. Monitor ECHA substance characterization requirements for kavalactone stereoisomer identification as an inflection indicator for compliance infrastructure investment needs.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Modular 50-liter containerized units from equipment suppliers compress geographic distance between Pacific Island raw material reception and finished extract output. |
| German BfArM Pharmacy-Only Distribution | Pharmacy-channel status unlocks Europe's highest-margin pathway for anxiolytic botanicals despite stricter kavalactone limits than peripheral markets. |
| Pacific Island Organic Certification Investment | Farm-level traceability programs function as de facto trade requirements rather than optional premiums for North American retail access. |
| Subscription-Based Replenishment Platform | Monthly kava shipments bundled with meditation app access concentrate customer lifetime value while reducing per-unit price sensitivity. |
| Chiral Chromatography Capability Addition | ECHA mandates for full constituent profiling extend to kavalactone stereoisomer identification, preempting port-of-entry rejection in REACH-regulated markets. |
Methodological Framework
Customs and trade data from Pacific Island export authorities, FDA import alert documentation, and EFSA scientific opinions formed the secondary backbone of this analysis. Primary interviews with supercritical CO2 equipment suppliers, Pacific Island farm cooperatives, German contract manufacturers, and US specialty health retail buyers combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling anchored volume estimates in Pacific Island cultivation capacity and extraction yield rates, while top-down cross-checks validated against dietary supplement channel throughput data. Segmentation dimensions included product type, end-user sophistication, application positioning, and distribution channel regulatory burden. CAGRs were derived from demand elasticity modeling across the projection horizon, incorporating FDA enforcement patterns and EFSA pharmacovigilance assessments as industry-specific forecast inputs.
Caveats apply where cyclone frequency in Vanuatu, Fiji, and Tonga or EFSA hepatotoxicity reassessments could materially shift the outlook. Practitioners should monitor Pacific Island climate patterns and European national regulator divergence for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Global Tofu Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Global Plant Based Milk Market