
 Frozen Pizza Market | 2026-2036
Frozen Pizza Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Pizza Market Intelligence
Multi-sourced cheese and tomato supply is hardening into a risk-management priority as climate volatility disrupts Mediterranean and Californian growing regions. Conagra Brands Inc. leverages its vertical milling and sauce operations to buffer input cost swings across retail and food-service channels. Schwan's Company anchors much of the institutional quick-service segment through dedicated distribution contracts with national chains. Nestlé S.A. competes on clean-label reformulation, removing artificial preservatives from its DiGiorno and Stouffer's lines ahead of retailer mandates.
Frozen pizza denotes a par-baked or fully baked flatbread base topped with sauce, cheese, and other ingredients, then blast-frozen at minus 40 degrees Fahrenheit to arrest microbial activity and preserve texture through six-to-twelve-month shelf life. The primary commercial purpose is to deliver restaurant-style convenience in home and institutional settings without requiring skilled labor or capital equipment. Thin crust and gluten-free product types are capturing disproportionate margin pools as health-positioned brands command price premiums in specialty food stores and online retail channels. Supermarkets and wholesale clubs still dominate volume throughput, though online retail is expanding fastest among households seeking subscription-based replenishment and limited-edition topping variety drops.
The FDA's updated Nutrition Facts labeling and sodium reduction targets are forcing reformulation across pepperoni and cheese-heavy SKUs, while the USDA's Bioengineered Food Disclosure Standard affects crust and topping supply chains with genetically modified wheat or corn derivatives. The EU Green Deal's packaging waste directives are pushing Dr. Oetker GmbH and Palermo Villa Inc. to pilot fiber-based trays and reduce plastic film layers in European export lines. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility laws in California reshape freezer logistics and renewable energy claims across the cold chain.
Market Dynamics
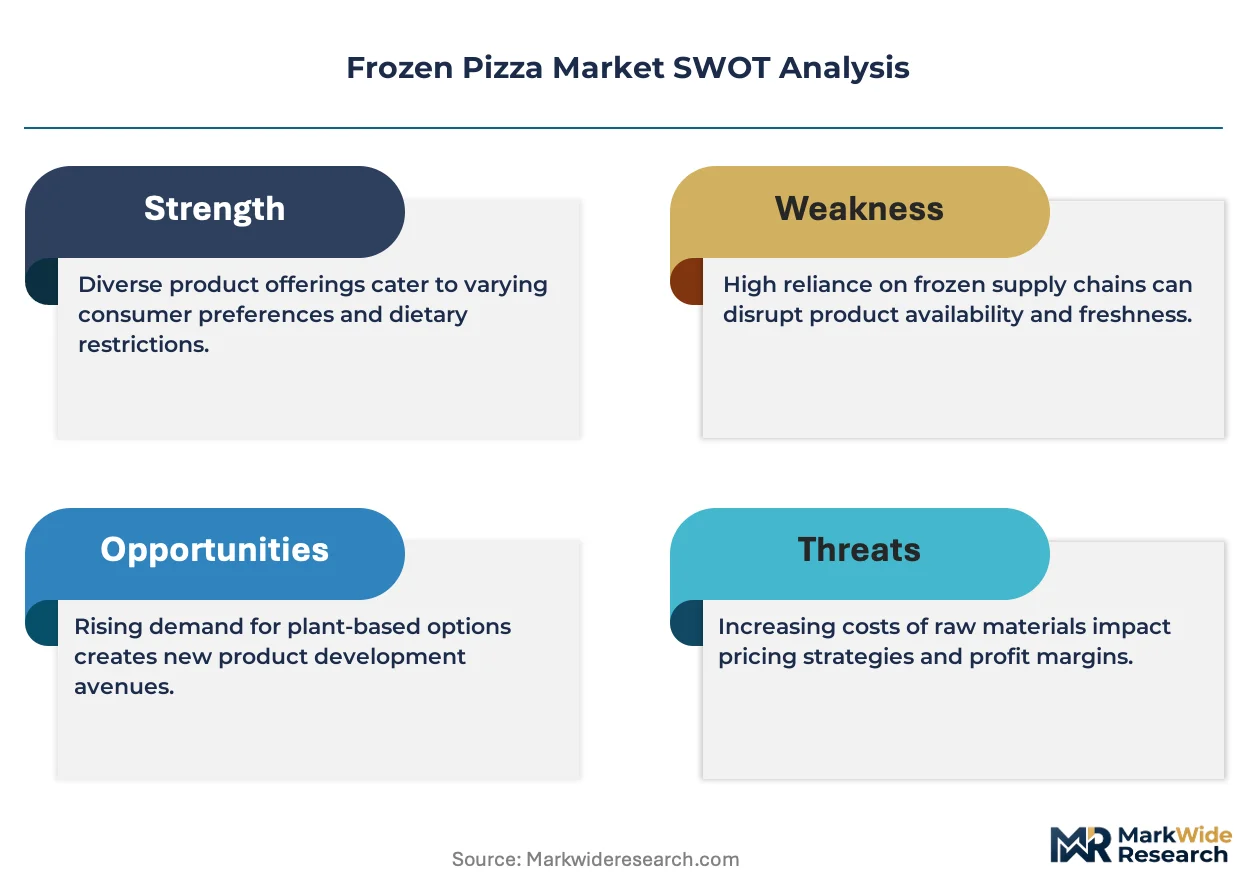
Blast-freezing infrastructure concentration among a handful of cold-chain operators is reshaping margin capture across retail and food-service channels, while regulatory sodium ceilings and packaging waste mandates force simultaneous reformulation and material substitution.
Growth Catalysts
- Quick-service procurement scaling:National restaurant chains are expanding frozen pizza back-of-house deployment to standardize output and reduce labor dependency across franchise networks.
- EU Farm to Fork Strategy:Sodium reduction targets and clean-label mandates are accelerating premium SKU development as manufacturers reposition portfolios ahead of 2025-2030 compliance deadlines.
- Subscription replenishment models:Direct-to-consumer platforms are capturing repeat-purchase households through limited-edition topping variety drops and auto-replenishment algorithms.
Market Restraints
- Tomato and cheese input volatility:Climate disruption across Mediterranean and Californian growing regions is hardening multi-sourced supply into a risk-management priority with limited near-term hedging instruments.
- Blast-freezing capacity concentration:Third-party cold-chain infrastructure sits with a narrow supplier base, creating bottleneck risk during peak seasonal demand surges.
- Refrigerated logistics substitution:Fresh pizza delivery platforms and ghost kitchens are capturing convenience-oriented households through 30-minute delivery promises.
Strategic Opportunities
- Gluten-free and thin-crust white space:Health-positioned brands command price premiums in specialty food stores and online retail channels where conventional mass-market players remain underrepresented.
- Renewable cold-chain claims:Extended producer responsibility laws in California and dual carbon goals in China are creating first-mover advantage for freezer logistics operators with verified renewable energy sourcing.
- Fiber-based packaging pilots:EU Green Deal packaging waste directives are opening procurement contracts for manufacturers with validated fiber tray and reduced plastic film solutions.
Industry Challenges
- Reformulation timeline compression:FDA updated Nutrition Facts labeling and sodium reduction targets are forcing simultaneous pepperoni and cheese-heavy SKU rework with limited formulation flexibility.
- Clean-label preservative removal:Retailer mandates for artificial preservative elimination are compressing shelf-life guarantees and requiring cold-chain integrity investments.
- Bioengineered ingredient disclosure:USDA Bioengineered Food Disclosure Standard affects crust and topping supply chains with genetically modified wheat or corn derivatives, complicating supplier certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Pizza Market |
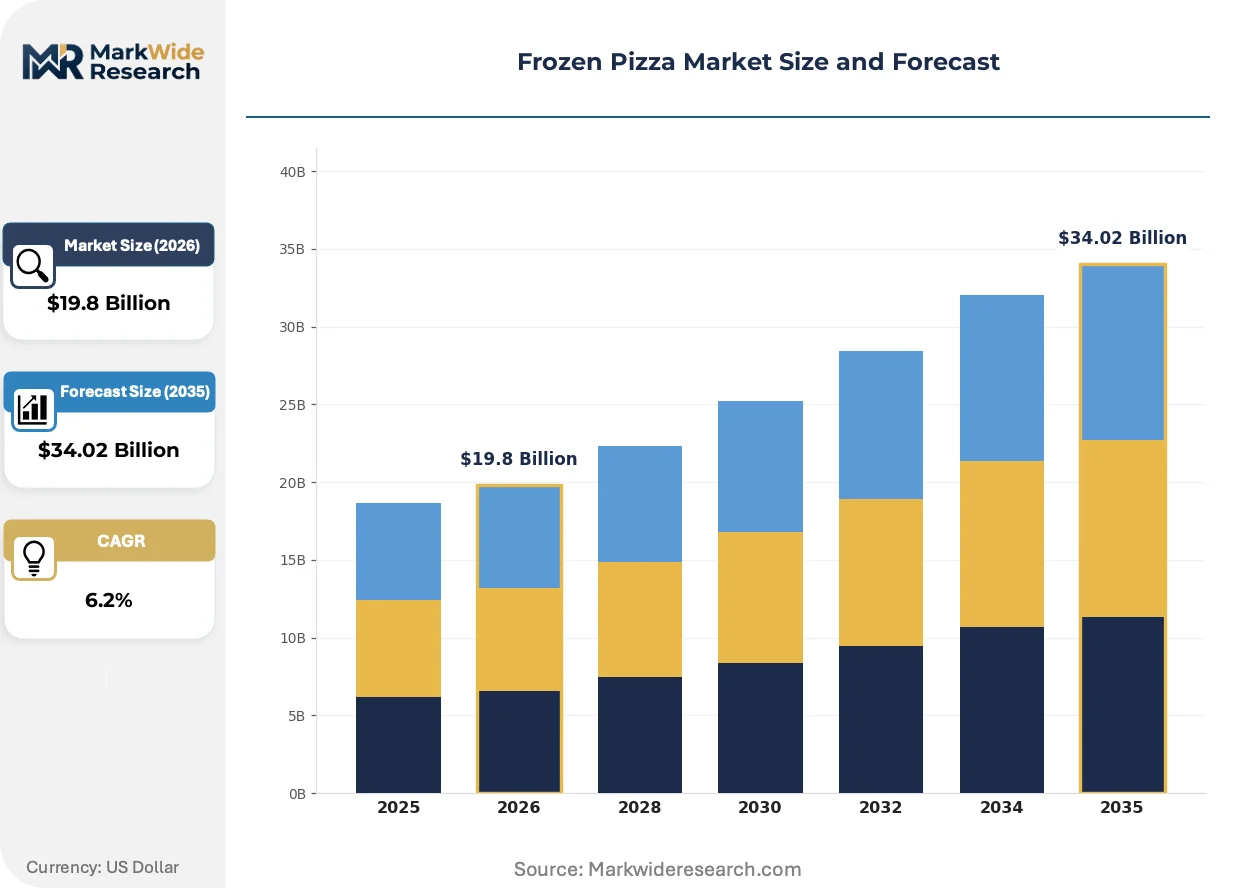
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.02 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stuffed Crust, Thin Crust, Deep Dish, Brick Oven, Gluten-Free, Vegan Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Food Stores, Wholesale Clubs Customer Type: Households, Quick Service Restaurants, Caterers, Food Service Operators, College Cafeterias Topping Variety: Pepperoni, Cheese, Vegetable Medley, Meat Lovers, Margherita, Hawaiian |
| Companies Covered | Conagra Brands Inc., Schwan's Company, Nestlé S.A., Amy's Kitchen Inc., Daiya Foods Inc., General Mills Inc., Palermo Villa Inc., Caulipower LLC, Dr. Oetker GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Pizza Market Strategic Shifts & Innovations
Refrigeration technology and packaging material science are converging to extend shelf-life claims while regulatory pressure on sodium and waste accelerates product architecture redesign across premium and private-label lines.
High-pressure processing and modified-atmosphere packaging are expanding into frozen pizza applications to support clean-label preservative removal. Premium private-label lines at wholesale clubs are adopting these technologies fastest to differentiate against national brands. The structural consequence is that shelf-life extension without artificial additives is expanding into a viable competitive wedge for retailers with captive cold-chain control.
EU Green Deal packaging waste directives are forcing fiber-based tray pilots and plastic film layer reduction across European export lines. Dr. Oetker GmbH and Palermo Villa Inc. are restructuring supplier contracts to secure molded fiber capacity ahead of 2025 implementation waves. Frozen pizza SKUs bound for German and French retail are most affected, with manufacturers absorbing upfront tooling costs to maintain shelf placement.
Household replenishment behavior is fragmenting across subscription platforms and limited-edition drops rather than traditional supermarket stocking-up. Online retail channels are capturing fastest growth among urban households seeking variety rotation without freezer overstock. This pattern is most visible in United States coastal metros where delivery density supports frozen last-mile economics.
Frozen Pizza Market Segmentation
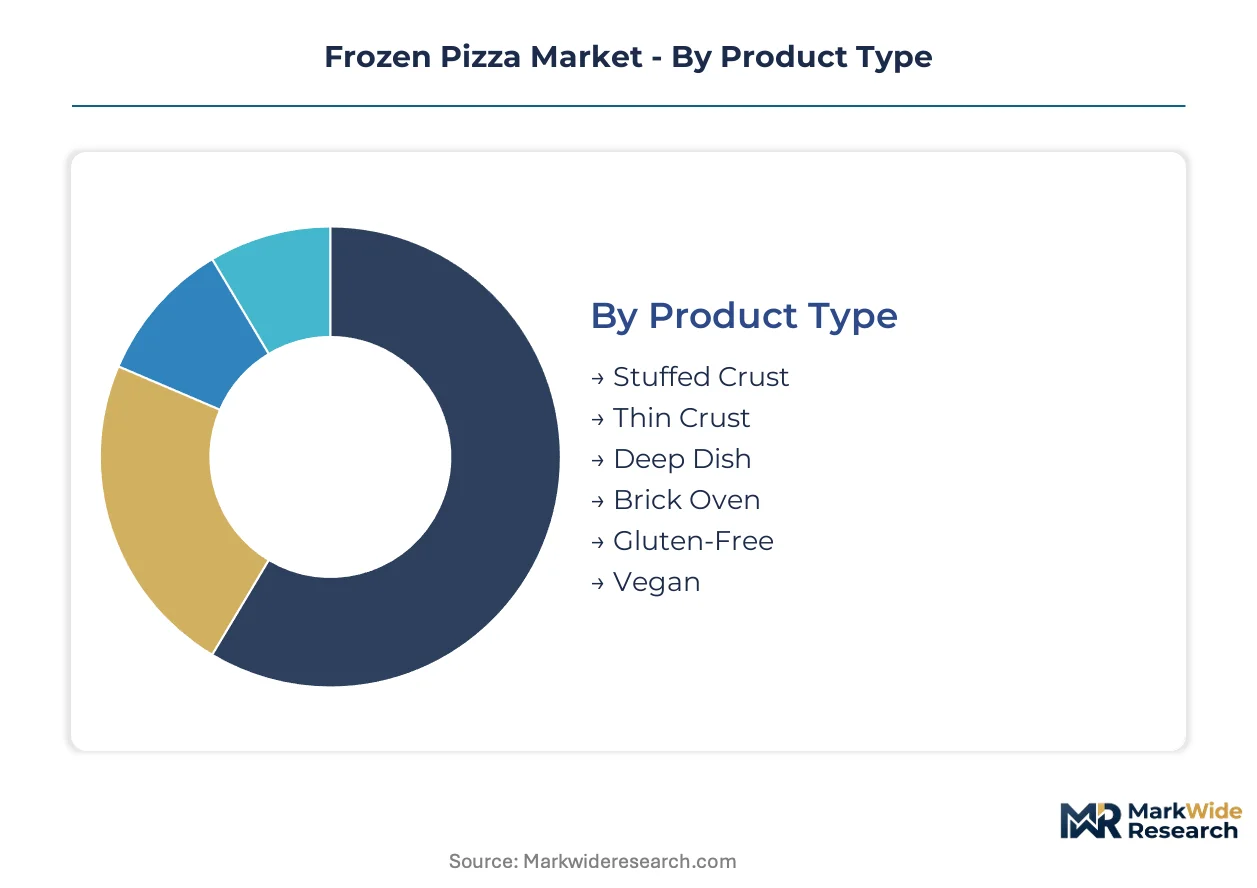
Frozen pizza segmentation reveals how supply chain configuration and channel economics concentrate margin capture across distinct product architectures. Understanding these divides exposes where reformulation investments and cold-chain partnerships deliver competitive separation.
Product Type:
Blast-freezing infrastructure concentrates among operators with dedicated thin-crust and gluten-free production lines, locking in margin premiums for health-positioned formats.
- Thin Crust:Par-baked bases with reduced dough mass freeze faster and transport more densely. Quick service restaurants in the United States deploy this format for speed-of-service consistency across franchise networks.
- Gluten-Free:Alternative flour formulations—rice, tapioca, almond—require segregated production lines to prevent cross-contamination. Specialty food stores in California and New York metropolitan areas command price premiums for certified-clean-label SKUs.
- Stuffed Crust:Cheese-injection equipment demands higher capital intensity and longer freeze times.
- Deep Dish:Extended bake profiles and heavier thermal mass limit distribution radius.
- Brick Oven:Artisan positioning targets wholesale club private-label programs.
- Vegan:Plant-based cheese supply chains remain fragmented across European and North American suppliers.
Today's leader: Thin Crust. Tomorrow's challenger: Gluten-Free.
Distribution Channel:
Channel selection dictates cold-chain partnership requirements and promotional calendar alignment, with volume throughput and margin structure diverging sharply across formats.
- Supermarkets:Traditional grocers with in-aisle freezer doors dominate unit velocity and trade promotion spending. Retailer mandates for clean-label reformulation are compressing shelf-life guarantees across pepperoni-heavy SKUs.
- Online Retail:Subscription algorithms and limited-edition drops capture repeat-purchase households in United States coastal metros with delivery density supporting frozen last-mile economics.
- Convenience Stores:Smaller freezer footprints favor single-serve and impulse formats.
- Specialty Food Stores:Curated assortments prioritize gluten-free and vegan certifications.
- Wholesale Clubs:Pallet-scale procurement and captive cold-chain control enable private-label premium positioning.
Supermarkets anchor current volume. Online retail climbs fastest on replenishment automation.
Customer Type:
End-user operational constraints determine formulation flexibility and portion specifications, with institutional procurement scaling fastest on labor-reduction imperatives.
- Quick Service Restaurants:National chains standardize back-of-house deployment to eliminate skilled pizza-making labor. Dedicated distribution contracts with blast-freezing operators lock in supply security during seasonal demand surges.
- Households:Home consumption centers on convenience and variety rotation without freezer overstock.
- Caterers:Event-driven demand requires flexible portion sizing and rapid thaw protocols.
- Food Service Operators:Contract feeding accounts prioritize cost controls over topping innovation.
- College Cafeterias:High-volume, limited-variety procurement favors cheese and pepperoni staples.
Quick Service Restaurants lead institutional uptake. Food Service Operators present untapped reformulation partnership potential.
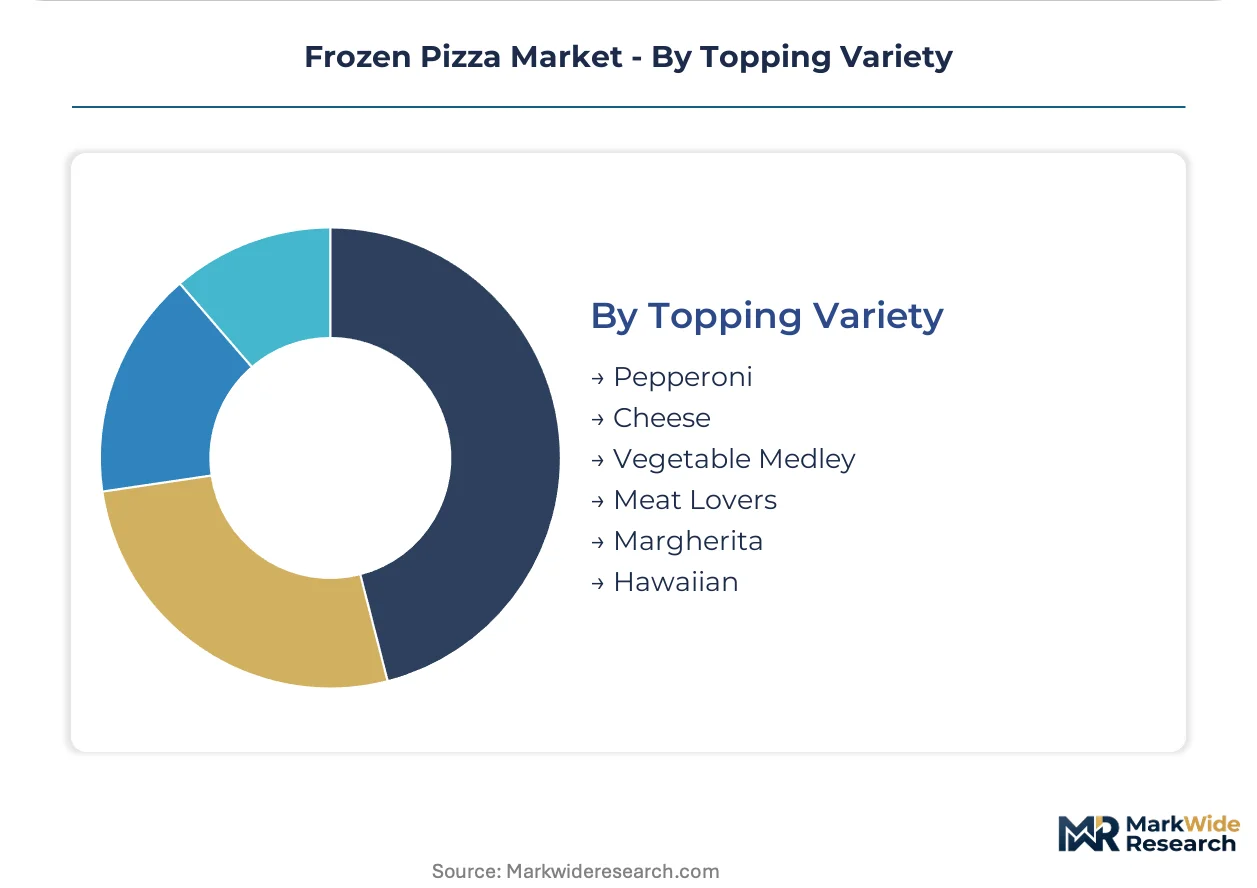
Topping Variety:
Input sourcing geography and sodium reduction targets concentrate reformulation risk on cured meat and cheese-heavy combinations, pushing vegetable-forward innovation.
- Pepperoni:Cured pork and beef sausage slices face FDA sodium ceiling pressures. USDA Bioengineered Food Disclosure Standard complicates feed grain certification through the supply chain.
- Cheese:Multi-sourced mozzarella and provolone expose manufacturers to climate volatility across Mediterranean and Californian dairy regions.
- Vegetable Medley:Bell peppers, onions, and mushrooms offer cleaner-label positioning with lower regulatory scrutiny.
- Meat Lovers:Multiple cured proteins compound sodium and preservative disclosure burdens.
- Margherita:Minimal topping architecture highlights sauce and crust quality differentiation.
- Hawaiian:Pineapple supply concentrates in Southeast Asian and Central American growing regions.
Pepperoni dominates current SKUs. Vegetable Medley gains on clean-label repositioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors frozen pizza manufacturing density through legacy meatpacking infrastructure and central cold-chain distribution. Quick-service procurement scaling and clean-label reformulation pressures concentrate competitive investment across distinct national markets.
United States
Private-label and premium artisan lines command expanded shelf space in wholesale clubs and specialty retailers. FDA sodium reduction targets and updated Nutrition Facts labeling compress reformulation timelines for pepperoni-heavy SKUs. Chicago and Minneapolis-St. Paul industrial corridors concentrate blast-freezing capacity and dedicated distribution contracts with national quick-service chains.
Germany
Dr. Oetker GmbH anchors European private-label and branded production through captive milling and sauce operations. EU Green Deal packaging waste directives and EFSA clean-label mandates accelerate fiber-based tray pilots and sodium reduction investments. North Rhine-Westphalia and Lower Saxony dairy regions supply mozzarella networks facing climate volatility hedging requirements.
China
Dual carbon goals and extended producer responsibility laws reshape freezer logistics and renewable energy claims across the cold chain. SAMR processed food labeling standards tighten ingredient disclosure for crust and topping supply chains. Yangtze River Delta cold-chain operators pilot renewable-powered blast-freezing infrastructure ahead of 2025 compliance waves.
Italy
Artisan positioning and Margherita-format premium lines capture price premiums in specialty retail channels. EFSA sodium ceilings and EU Farm to Fork Strategy compliance deadlines accelerate clean-label reformulation. Emilia-Romagna tomato processing clusters face climate disruption hardening multi-sourced supply into risk-management priority.
United Kingdom
Subscription-based replenishment and online retail channels capture fastest growth among urban households seeking variety rotation. FSA salt reduction targets and plastic packaging levies compress shelf-life guarantees and material substitution timelines. London metropolitan cold-chain density supports frozen last-mile economics for direct-to-consumer platforms.
Frozen Pizza Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue health-positioned and clean-label adjacent spaces. The vendor base clusters around three structural tiers: multinational packaged food conglomerates with captive cold-chain control, mid-scale specialists in gluten-free and alternative-flour formats, and private-label manufacturers serving wholesale club and quick-service channels. Dominant competitive moves include backward integration into tomato milling and cheese supply to buffer input cost swings, and strategic partnerships with third-party blast-freezing operators to secure seasonal capacity.
Among North American packaged food conglomerates, Conagra Brands Inc. and General Mills Inc. exemplify scale-driven archetypes with vertical milling and sauce operations. Nestlé S.A. occupies a clean-label reformulation position, while Dr. Oetker GmbH represents European private-label and branded integration. Schwan's Company anchors dedicated distribution contract structures with national quick-service chains.
| Leading Market Players |
|---|
| Conagra Brands Inc. |
| Schwan's Company |
| Nestlé S.A. |
| Amy's Kitchen Inc. |
| Daiya Foods Inc. |
| General Mills Inc. |
| Palermo Villa Inc. |
| Caulipower LLC |
| Dr. Oetker GmbH |
| Others |
Cost & Logistics Intelligence
Cheese and tomato input costs cascade through three pricing tiers as climate volatility across Mediterranean and Californian growing regions forces buyers to absorb premium-grade premiums or trade down to private-label economy lines. Quick-service chains with dedicated distribution contracts lock in contract-based pricing, while spot-market exposure concentrates among smaller food-service operators without backward integration into milling or dairy networks.
Pricing Analysis
Input-cost pass-through operates through contract-based long-term offtake for quick-service chains and spot-market exposure for smaller buyers, with price differentiation hinging on volume scale and clean-label certification tier. Premium-mid-economy pricing differentiation separates gluten-free certified SKUs in specialty retail from mass-market cheese-and-pepperoni staples. Pricing pressure stems from sodium reduction reformulation costs and fiber-based packaging tooling investments. Quick-service chains exhibit lowest price sensitivity due to labor-reduction imperatives, while college cafeterias and contract feeders face highest pressure on per-unit procurement costs.
Supply Chain Analysis
Dual-sourcing requirements for mozzarella and tomato paste now mandate multi-supplier qualification across Italy, California, and Wisconsin dairy networks as buyers hedge climate disruption. Raw material dependencies center on durum wheat for crust formulations, cheese cultures from Emilia-Romagna and Lower Saxony, and modified-atmosphere packaging films. Supply chain risk concentrates in single-source vulnerability for blast-freezing capacity during peak seasonal surges. Distribution runs through captive cold-chain networks for wholesale clubs and third-party logistics for supermarket retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier repositioning as health-positioned SKUs command price premiums and reformulation costs concentrate among slower-moving competitors.
For Market Incumbents: Extend clean-label certification coverage ahead of retailer mandates to compress competitor shelf-life guarantees. Secure dedicated blast-freezing contracts before peak seasonal capacity crunches. Threat substitution from fresh pizza delivery platforms demands cold-chain integrity investments that smaller players cannot match. Backward integration into tomato milling buffers input volatility.
For New Entrants and Emerging Players: Begin with gluten-free and thin-crust white space in United States coastal metros where specialty food stores lack certified-clean-label alternatives. The most penetrable segment is online retail subscription platforms seeking limited-edition topping variety drops. A direct-to-consumer go-to-market angle with auto-replenishment algorithms bypasses supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale gluten-free specialists because blast-freezing capacity concentration creates exit demand from players lacking cold-chain control. Long-term viability hinges on reformulation capability and retailer relationship depth. Acquisition target archetype: certified-clean-label manufacturers with segregated production lines. The signal to watch is wholesale club private-label program expansions into premium health-positioned tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | Nestlé's preservative removal from DiGiorno lines preempts FDA sodium ceiling mandates. |
| Fiber-Based Packaging Transition | Dr. Oetker's molded fiber tray pilots secure German retail shelf placement under EU Green Deal. |
| Subscription Platform Launch | Direct-to-consumer algorithms capture coastal metro households seeking variety rotation. |
| Blast-Freezing Capacity Lock-In | Schwan's dedicated distribution contracts eliminate seasonal supply security risk. |
| Backward Integration into Milling | Conagra's vertical sauce operations buffer tomato input cost swings across channels. |
Research Approach
Coverage spans the United States, Germany, China, Italy, and the United Kingdom, with primary inputs from each market gathered through interviews with frozen pizza brand managers, supermarket category buyers, quick-service chain procurement directors, cold-chain logistics operators, and regulatory affairs specialists. Secondary validation draws from FDA nutrition labeling filings, EU Farm to Fork Strategy documentation, SAMR processed food standards, Nielsen retail audit data, and customs trade records. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product architecture, distribution channel, end-user operational type, and topping input sourcing geography. CAGRs derive from trend extrapolation of quick-service procurement scaling, subscription platform penetration curves, and clean-label SKU share shifts. Industry-specific forecast inputs incorporate blast-freezing capacity utilization rates and renewable cold-chain infrastructure buildout timelines.
Caveats apply where regulatory enforcement timelines or climate disruption severity could materially shift the outlook. Forecasts reflect assumptions about sodium reduction compliance deadlines, fiber-based packaging cost curves, and quick-service labor substitution rates. Deviation in EU Green Deal implementation pace or California extended producer responsibility enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Bangladesh Frozen Food Market