
 Plant Based Protein Market | 2026-2036
Plant Based Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Protein Market Intelligence
Revenue from specialized protein isolates is tilting the market's margin pool away from commodity-grade concentrates and flours. Archer Daniels Midland Company leverages its extensive agricultural sourcing network to secure a cost advantage in mature segments like soy and wheat proteins. Roquette Frères specializes in pea protein, dominating a fast-growing segment with its advanced extraction technologies. Cargill, Incorporated competes across multiple protein types, utilizing its global manufacturing and logistics footprint to serve large food manufacturers.
Plant based proteins are ingredients derived from sources like soy, peas, and rice, processed to achieve high protein concentrations, often exceeding 80% purity for isolates. Their primary commercial purpose is to enhance the nutritional profile and texture of food products, serving as functional alternatives to animal-derived proteins. Soy protein and pea protein are the largest product type segments, while the isolate form commands a significant price premium over concentrates. The sports nutrition application represents a consistent, high-margin category for manufacturers.
The US FDA's GRAS notification process and the European Food Safety Authority's (EFSA) novel food regulations govern market entry for new ingredients like sacha inchi protein. In India, the FSSAI sets standards for protein content and labeling, directly influencing product formulations and consumer trust. The strategic decision for suppliers is whether to pursue cost parity with animal proteins or differentiate on unique functionality and sustainability claims.
Market Dynamics
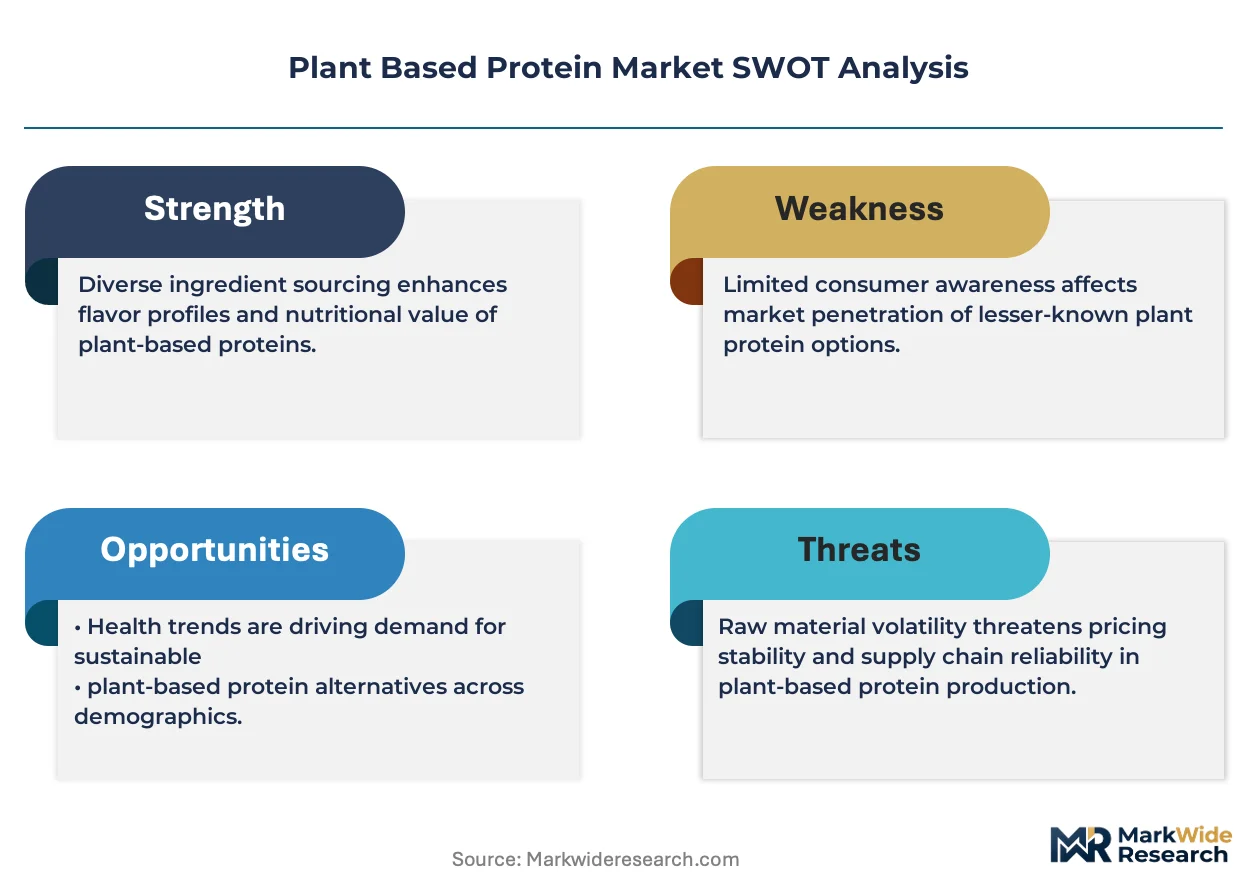
The market's central dynamic is the strategic tension between achieving cost parity with animal-derived proteins and differentiating products based on unique functionality and sustainability credentials. Advanced processing technologies are the primary lever for navigating this competitive landscape.
Growth Catalysts
- Clean Label Demand:Consumer preference for non-GMO and minimally processed ingredients in food products, particularly in Germany, drives uptake of plant proteins like pea and rice in meat alternatives and baked goods.
- Regulatory Clarity:The US FDA's Generally Recognized as Safe (GRAS) notification process provides a defined pathway for introducing novel proteins, reducing market entry uncertainty for ingredient innovators.
- Corporate Sustainability Goals:Food manufacturers are incorporating plant proteins to meet internal ESG targets and reduce the carbon footprint of their supply chains, creating consistent B2B demand.
Market Restraints
- Input Crop Volatility:The supply and pricing of key raw materials, such as yellow peas and non-GMO soybeans, are subject to significant fluctuation based on climate events and geopolitical trade policies.
- Organoleptic Hurdles:Persistent off-notes and undesirable textures in some lower-grade plant proteins limit their application in sensitive products like dairy-free yogurts and beverages without costly masking agents.
- Processing Capital Intensity:The high capital expenditure required for building wet fractionation facilities to produce high-purity isolates creates a barrier to entry and concentrates supply among a few large players.
Strategic Opportunities
- Novel Protein Commercialization:Ingredients like fava bean and chickpea protein offer unique functional benefits, such as superior emulsification or gelling properties, creating white space in specialized food applications.
- Hybrid Product Formulation:Combining plant proteins with cell-cultured fats or fermentation-derived ingredients allows for the creation of next-generation alternative products with enhanced flavor and performance.
- Functional Fortification in India:Addressing protein deficiency through the fortification of staple foods presents a significant opportunity, supported by FSSAI standards that encourage higher nutritional content.
Industry Challenges
- Texturization Skill Gap:A shortage of food scientists and process engineers with expertise in high-moisture extrusion technology constrains the development of more sophisticated whole-muscle meat analogues.
- Resource-Intensive Processing:The significant water and energy consumption associated with protein isolation challenges the sustainability narrative and exposes producers to volatile utility costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Protein Market |
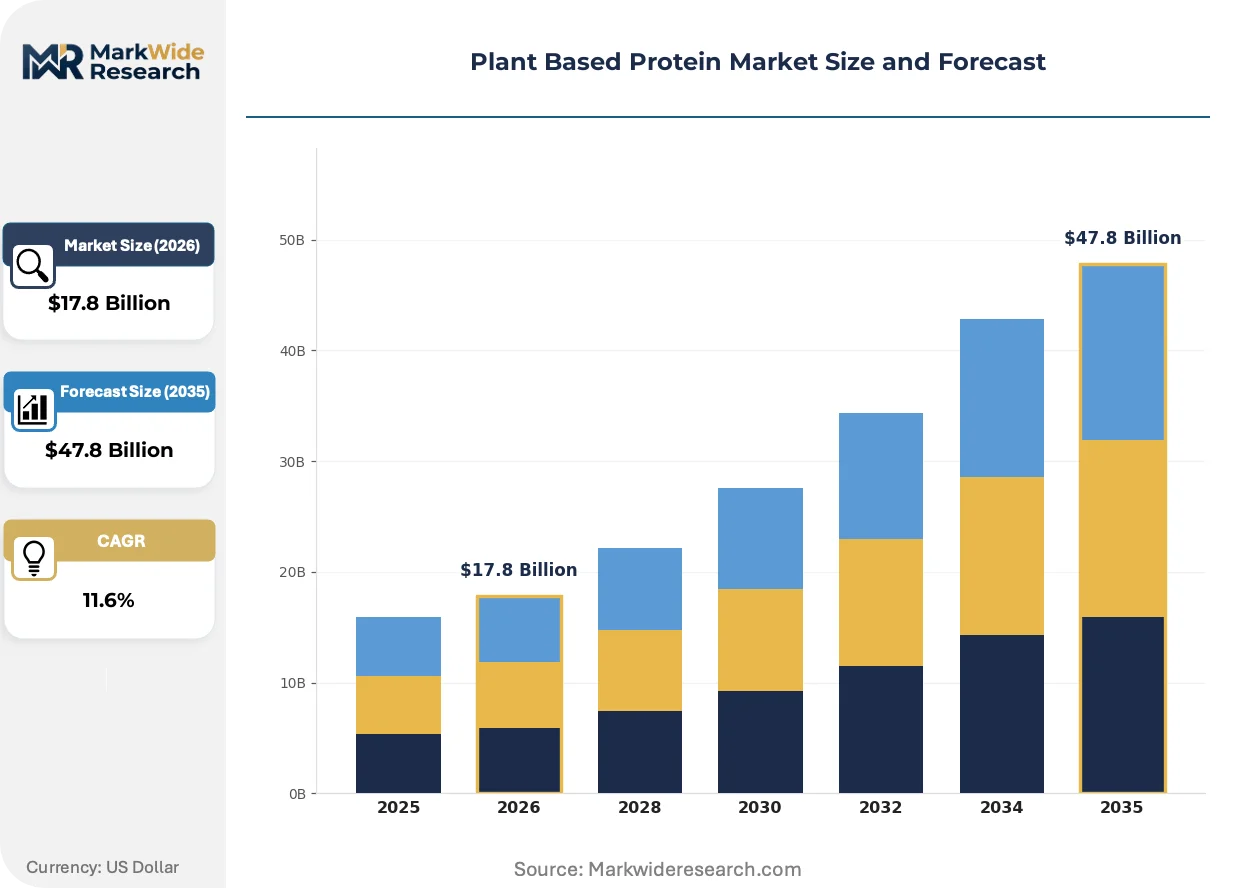
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $47.8 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Wheat Protein, Pumpkin Seed Protein, Sacha Inchi Protein Application: Sports Nutrition, Dietary Supplements, Infant Nutrition, Functional Foods, Meat & Poultry Alternatives, Bakery & Confectionery Form: Isolate, Concentrate, Textured, Hydrolyzed, Flour, Powder End User: Food Manufacturers, Beverage Manufacturers, Nutraceutical Companies, Animal Feed Producers, Personal Care Firms, Pharmaceutical Manufacturers |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Kerry Group PLC, Roquette Frères, Ingredion Incorporated, Burcon NutraScience Corporation, Cosucra Groupe Warcoing SA, Conagra Brands, Monde Nissin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Protein Market Strategic Shifts & Innovations
The convergence of advanced food science and evolving consumer expectations for both nutrition and sustainability is reshaping the ingredient landscape. Innovations focus not just on protein content but on delivering specific functional outcomes, from texture to solubility.
Advanced texturization methods like high-moisture extrusion (HME) are critical for creating fibrous structures from plant protein concentrates. Food manufacturers developing meat and poultry alternatives are rapidly adopting this technology to improve product quality. The use of HME is collapsing the perceived textural gap between plant-based products and conventional animal-based whole muscle cuts, enabling a new class of premium alternatives.
The European Food Safety Authority's (EFSA) novel food regulation governs market access for new protein ingredients within the EU. This framework imposes a rigorous, data-intensive approval process, requiring extensive safety and toxicological studies before commercialization. Innovators developing proteins from sources like algae or fungi are most affected, as the lengthy timeline can slow market entry compared to pathways in other jurisdictions.
A demand-side shift from single-source fortification to strategic multi-protein blending is gaining momentum. This trend disrupts the business model for suppliers of commodity proteins, as formulators now seek synergistic combinations to meet specific functional goals. The sports nutrition category prominently displays this shift, where blends of pea, rice, and pumpkin protein are used to achieve a complete amino acid profile and superior mouthfeel.
Plant Based Protein Market Segmentation
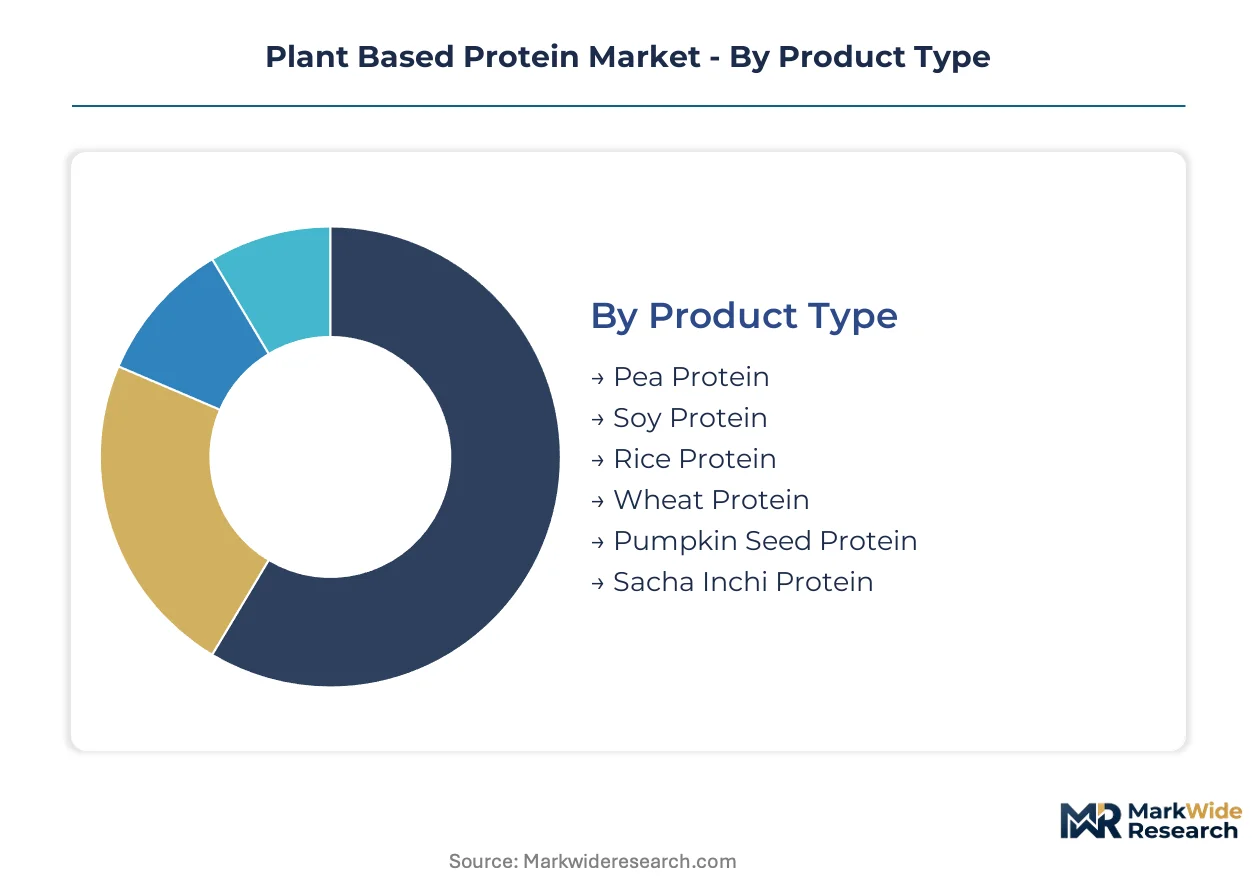
Market segmentation provides a structured view of the plant-based protein landscape, highlighting areas of concentrated demand and specialized product development. Understanding these distinct categories allows manufacturers to tailor ingredient formulations and market strategies for specific end-use applications and consumer needs.
Product Type:
Product type segmentation highlights the diverse raw material sources and their processed forms that constitute the market's supply base.
- Pea Protein:This protein is extracted from yellow peas, offering a neutral flavor profile and high digestibility, making it suitable for a wide range of food formulations. Demand is concentrating in Europe for meat and poultry alternatives, driven by clean label preferences and non-GMO sourcing.
- Soy Protein:Derived from soybeans, this widely available protein offers excellent functional properties like emulsification and water binding, making it a cost-effective solution. The United States food manufacturing sector heavily utilizes soy protein in various applications, balancing cost efficiency with nutritional fortification.
- Rice Protein:Extracted from brown rice, this hypoallergenic protein is favored in allergen-free formulations and sports nutrition products.
- Wheat Protein:Sourced from wheat, this protein provides unique viscoelastic properties, making it valuable in bakery and confectionery applications.
- Pumpkin Seed Protein:This nutrient-dense protein offers a distinct flavor and is increasingly used in niche health food products and protein bars.
- Sacha Inchi Protein:Derived from the sacha inchi seed, this novel protein is gaining traction for its complete amino acid profile and sustainability claims.
Soy Protein holds installed capacity. Pea Protein is rotating up the share rankings.
Application:
Application areas define the primary commercial purpose and end-use sectors for plant-based protein ingredients.
- Meat & Poultry Alternatives:Plant proteins are texturized and formulated to mimic the sensory attributes of animal meat, serving as primary ingredients in plant-based burgers, sausages, and chicken substitutes. This application is expanding most quickly in Germany, where consumer demand for sustainable and non-GMO options is particularly strong.
- Sports Nutrition:These products leverage plant proteins for muscle recovery, growth, and sustained energy, often formulated as powders, bars, and ready-to-drink beverages. This high-margin category consistently sees strong demand in the United States, driven by active lifestyle trends and clean label preferences.
- Dietary Supplements:Plant proteins are incorporated into capsules, tablets, and powders to address nutritional gaps or specific health concerns for a broad consumer base.
- Functional Foods:This segment includes foods fortified with plant proteins to enhance nutritional content, such as protein-enriched yogurts, cereals, and snacks.
- Infant Nutrition:Specialized plant protein formulations provide essential amino acids for infant development, particularly for babies with dairy allergies or specific dietary needs.
- Bakery & Confectionery:Plant proteins improve texture, moisture retention, and nutritional value in baked goods, breads, and sweet treats.
Demand for Meat & Poultry Alternatives remains strong. Sports Nutrition demonstrates the steepest expansion trajectory.
Form:
The form of plant protein dictates its purity level, functional characteristics, and suitability for various manufacturing processes.
- Isolate:Characterized by protein content often exceeding 80%, isolates undergo extensive processing to remove non-protein components like fats and carbohydrates. Isolate forms command a significant price premium in the sports nutrition sector, where high purity and solubility are critical for product performance.
- Concentrate:These forms typically contain 60-80% protein, retaining more of the original source material's components, making them a more cost-effective option. Food manufacturers leverage concentrates in bulk applications like meat alternatives to balance cost and functionality.
- Textured:Plant proteins are processed through extrusion to create fibrous structures that mimic the chewiness of meat, primarily used in meat analogues.
- Hydrolyzed:Proteins are broken down into smaller peptides, enhancing digestibility and reducing allergenicity, often used in specialized nutritional products.
- Flour:Minimally processed plant protein flours retain most of the original ingredient's composition and are used as a foundational ingredient in baked goods and snacks.
- Powder:A general category for dried and ground plant proteins, offering versatility across various food and beverage formulations.
Purity levels in Isolate drive premium pricing. Concentrate offers a cost-effective bulk solution.
End User:
Customer groups delineate the primary industries and businesses that procure plant-based protein ingredients for their product development.
- Food Manufacturers:These companies integrate plant proteins into a wide array of consumer food products, from snacks and beverages to ready meals and dairy alternatives. Large food manufacturers, including Cargill, Incorporated, prioritize consistent supply and functional performance for their extensive product portfolios.
- Nutraceutical Companies:Specialized firms develop health-oriented products, including dietary supplements and functional foods, leveraging plant proteins for their nutritional benefits. These companies often seek specific amino acid profiles and high-purity isolates for their formulations.
- Beverage Manufacturers:Companies producing drinks, such as protein shakes, smoothies, and plant-based milks, utilize plant proteins for nutritional enhancement and texture.
- Animal Feed Producers:Plant proteins serve as a sustainable and nutritious ingredient in animal feed formulations, reducing reliance on animal-derived proteins.
- Personal Care Firms:Some personal care companies incorporate plant proteins into cosmetic and skincare products for their moisturizing and restorative properties.
- Pharmaceutical Manufacturers:A niche application where plant proteins are used in specific medical nutrition products or as excipients in drug formulations.
Procurement from Food Manufacturers focuses on scale. Nutraceutical Companies seek specialized ingredient functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plant-based protein market exhibits diverse consumption patterns across major geographies. While the United States emphasizes sports nutrition and functional foods, Germany prioritizes clean label and non-GMO sources for meat alternatives. This regional variation influences product development and regulatory approaches.
United States
Demand for plant-based proteins in the United States is consistently strong, driven by sports nutrition and dietary supplement applications. The US FDA's GRAS notification process provides a clear regulatory framework for novel ingredient introduction. California and the Northeast corridor show high concentration of nutraceutical companies and food manufacturers leveraging these proteins.
Germany
Germany demonstrates significant demand for non-GMO plant proteins, particularly in the meat and poultry alternatives segment. European Food Safety Authority (EFSA) regulations on novel foods and clean label requirements shape ingredient choices. Food innovation clusters in cities like Berlin and Hamburg are actively developing new plant-based product formulations.
India
India presents a substantial opportunity for functional fortification, addressing widespread protein deficiency through staple foods. The FSSAI sets content and labeling standards, directly influencing product formulations. States like Maharashtra and Karnataka are emerging as hubs for food processing and nutritional product development.
France
French consumers show a growing interest in plant-based proteins, particularly in dairy-free alternatives and specialized food applications. EFSA's stringent novel food regulations apply across the European Union, including France, impacting market entry for new ingredients. Research centers in Paris and Lyon contribute to advancements in plant protein extraction and formulation.
Canada
Canadian demand for plant-based proteins is expanding in both health-conscious consumer products and ingredient manufacturing. Health Canada's food regulations guide product claims and safety assessments for protein-enriched foods. Agricultural regions in the Prairies are developing infrastructure for processing local pulse crops into protein ingredients.
Plant Based Protein Market Key Industry Players
Capability concentration sits with one tier of specialized ingredient producers; scale advantage sits with another tier of diversified agricultural giants. The market structure is tiered, featuring large-scale commodity suppliers, specialized protein innovators, and integrated food manufacturers. Strategic archetypes include raw material processors, functional ingredient developers, and end-product formulators. Dominant competitive moves involve significant capacity expansion to meet demand and strategic partnerships to secure novel protein access.
Archer Daniels Midland Company, a diversified agricultural processing firm, anchors the commodity-grade protein segment, leveraging its extensive agricultural sourcing network to secure cost advantages in mature markets like soy and wheat proteins. Roquette Frères exemplifies specialization, dominating the fast-growing pea protein market through advanced extraction technologies and a focus on high-purity isolates. Cargill, Incorporated sits within the integrated food manufacturer archetype, utilizing its global manufacturing and logistics footprint to compete across multiple protein types and serve large food manufacturers with diverse product portfolios. These companies collectively shape the supply dynamics for various plant protein forms.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Kerry Group PLC |
| Roquette Frères |
| Ingredion Incorporated |
| Burcon NutraScience Corporation |
| Cosucra Groupe Warcoing SA |
| Conagra Brands |
| Monde Nissin Corporation |
| Others |
Cost & Logistics Intelligence
Canadian Prairies' processing capacity for pulse crops directly influences global pea protein availability, impacting downstream pricing power for specialized isolates. This dynamic creates a strategic tension between raw material cost and advanced ingredient functionality.
Pricing Analysis
Long-term offtake agreements and commodity spot purchases define the dominant pricing structures for plant-based proteins. Price differentiation stems from purity levels, non-GMO certifications, and specialized functional properties like enhanced solubility or emulsification. Pricing softness reflects persistent input crop volatility, particularly for yellow peas and non-GMO soybeans. Food manufacturers leveraging bulk concentrates demonstrate higher price sensitivity compared to sports nutrition brands demanding high-purity isolates.
Supply Chain Analysis
Upstream feedstock sourcing for plant-based proteins centers on agricultural regions like the United States for soy, Canada for peas, and India for various pulses. Raw material dependencies include yellow peas, non-GMO soybeans, and brown rice. Commodity price volatility, driven by climate events and geopolitical trade policies, represents a significant structural risk. Distribution runs through a B2B model, supplying large food manufacturers and nutraceutical companies with bulk ingredients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant-based protein market is undergoing a platform-economics inflection, driven by the emergence of multi-protein blending ecosystems to achieve specific functional outcomes.
For Market Incumbents: Insulate core market share by investing in advanced texturization technologies like high-moisture extrusion, countering the threat of novel protein entrants with superior product performance. Secure long-term sourcing agreements for key raw materials to mitigate input crop volatility. Further capacity additions in high-purity isolates will reinforce their position against substitute technologies.
For New Entrants and Emerging Players: Underpenetration in specialized food applications, such as fava bean and chickpea protein, offers significant white space. Target specific functional benefits like superior emulsification or gelling properties to differentiate products. A go-to-market angle focusing on sustainability claims and unique organoleptic profiles can capture niche segments, particularly in Europe.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural giants seeking to divest non-core protein assets, as well as specialized protein innovators with proprietary extraction technologies. Long-term viability rests on securing access to novel protein sources and advanced processing capabilities over the next decade. The signal to watch is the acceleration of M&A activity within the novel protein commercialization space.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Pea Protein | Expands supply to meet growing demand in meat and poultry alternatives, particularly in Europe. |
| Investment in High-Moisture Extrusion | Enables the creation of more sophisticated whole-muscle meat analogues, closing the textural gap. |
| Strategic Partnerships for Non-GMO Sourcing | Mitigates input crop volatility and addresses clean label demand from food manufacturers. |
| R&D in Novel Protein Extraction | Unlocks unique functional benefits from ingredients like fava bean or chickpea, creating specialized food applications. |
| Market Entry for Functional Fortification in India | Addresses widespread protein deficiency and leverages FSSAI standards to build consumer trust. |
Research Approach
Operator-level perspectives from food scientists, R&D directors, procurement managers, and regulatory affairs specialists anchored the qualitative base for this analysis. This primary research was rigorously validated through secondary data sources, including company annual reports, scientific journals, and government food safety databases from the US FDA, EFSA, and FSSAI. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy.
Scenario-bracketing framing informed the analytical framework used to project market trends across the analysis window. Segmentation dimensions modeled included product type, application, form, end user, and regional regulatory environment. Compound annual growth rates were derived from historical data analysis and projected market drivers. Industry-specific forecast inputs included raw material availability projections and consumer preference shifts towards plant-based diets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified agricultural giants or specialized protein innovators would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Cross-checking against external market intelligence reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Extruded Soy Products Market