
 Ground Fault Circuit Interrupter Market | 2026-2036
Ground Fault Circuit Interrupter Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Fault Circuit Interrupter Market Analysis
Silicon carbide is repositioning GFCI semiconductor economics toward higher thermal tolerance and faster fault response. Eaton leverages vertical integration across its electrical components portfolio to control cost structures in residential GFCI production. Schneider Electric anchors its position through deep channel relationships with electrical contractors in North American distribution. Legrand differentiates via specialization in premium self-test and combination arc-fault product lines.
A ground fault circuit interrupter is a safety device that monitors current imbalance between energized and neutral conductors, interrupting power within 25 milliseconds when it detects leakage exceeding 4-6 milliamperes to prevent electrocution. Its primary purpose is protecting personnel from ground faults in environments where moisture, conductive surfaces, or equipment degradation elevate shock risk. Residential GFCI dominates volume as code mandates expand to cover kitchens, laundry areas, and basements in single-family and multifamily construction. Self-test technology leads value creation by automating periodic functionality verification and reducing manual inspection burdens for electrical contractors and facility managers.
The National Electrical Code, enforced by local authorities having jurisdiction across the United States, mandates GFCI installation in an expanding list of residential and commercial locations, directly stimulating replacement and new-build demand. OSHA construction safety standards require portable GFCI protection on job sites, creating a parallel enforcement channel for industrial-grade product sales. Stakeholders must monitor evolving NEC amendment cycles and state-level adoption timelines to anticipate compliance-driven procurement waves and inventory positioning.
Market Dynamics
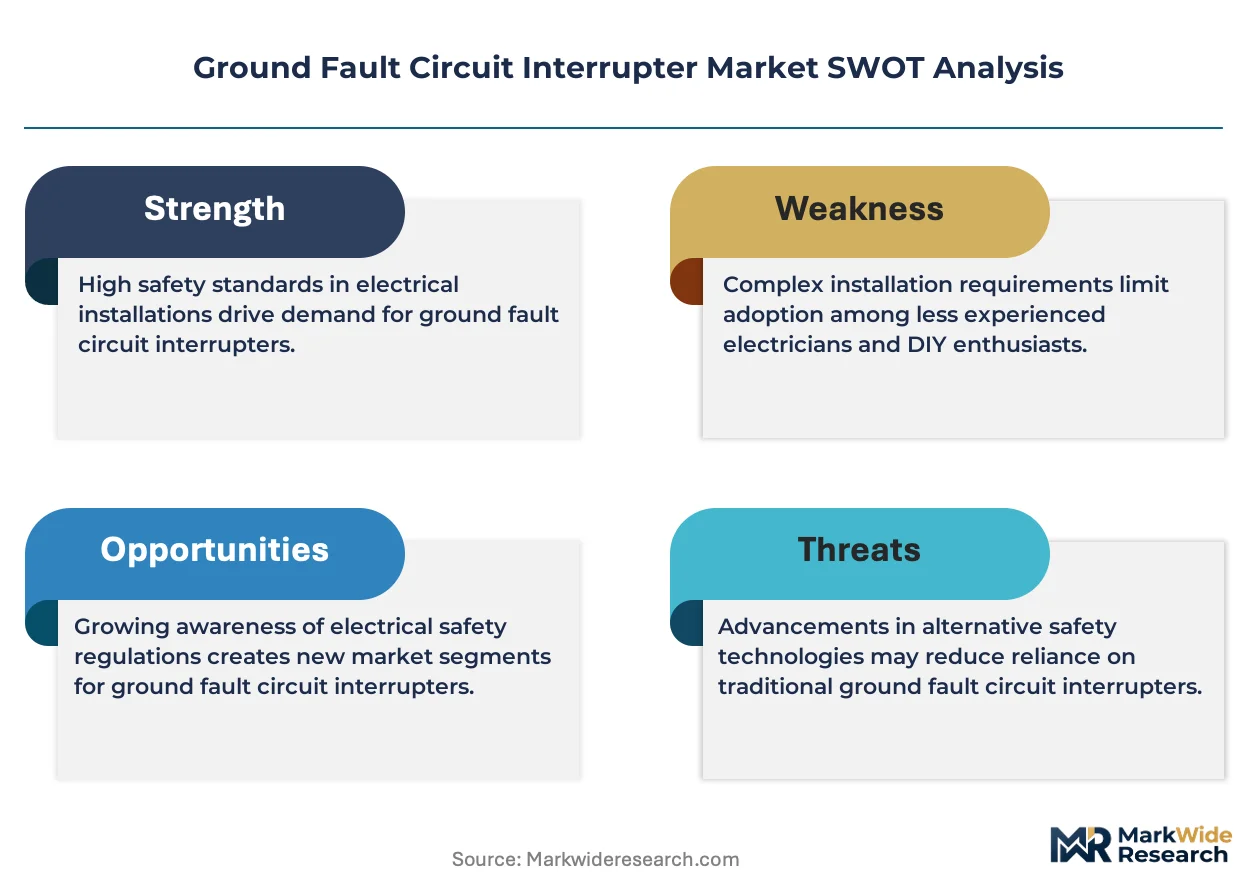
The National Electrical Code's expanding coverage mandate is tightening compliance windows across residential and commercial construction, forcing accelerated replacement cycles and specification upgrades in electrical distribution systems.
Growth Catalysts
- Code mandate expansion:NEC requirements now cover kitchens, laundry areas, and basements in single-family and multifamily dwellings, directly stimulating new-build and retrofit installations across the United States.
- Silicon carbide semiconductor adoption:Wide-bandgap materials enable faster fault response and higher thermal tolerance, improving device reliability in moisture-prone environments.
- OSHA construction standards:Portable GFCI protection requirements on job sites create sustained demand for industrial-grade portable units in commercial building and infrastructure projects.
Market Restraints
- Copper and rare earth input volatility:Semiconductor-grade silicon and magnetic core materials face price swings that compress margin structures for standardized residential receptacles.
- Contractor channel concentration:Electrical distribution in North America runs through consolidated wholesaler networks, limiting pricing autonomy for manufacturers without direct contractor relationships.
- Legacy aluminum wiring incompatibility:Older residential stock with aluminum branch circuits requires specialized GFCI designs, fragmenting SKU requirements and inventory carrying costs.
Strategic Opportunities
- Self-test automation convergence:Integration of periodic functionality verification with smart home energy management systems opens specification opportunities in premium residential segments.
- California Title 24 alignment:The state's building energy efficiency standards create a regulatory laboratory for advanced safety-device integration with load management controls.
- Commercial kitchen modernization:Food service facility upgrades driven by health department electrical safety inspections represent an underpenetrated application vertical beyond traditional residential dominance.
Industry Challenges
- Licensed electrician shortage:Journeyman pipeline constraints in Texas and Florida extend installation backlogs and delay revenue recognition on specification wins.
- UL 943 certification timeline:Revised trip-time and endurance testing protocols extend new product validation cycles, compressing competitive response windows.
- Multi-brand interoperability:Load-side compatibility with downstream AFCIs and surge protective devices creates field troubleshooting complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Fault Circuit Interrupter Market |
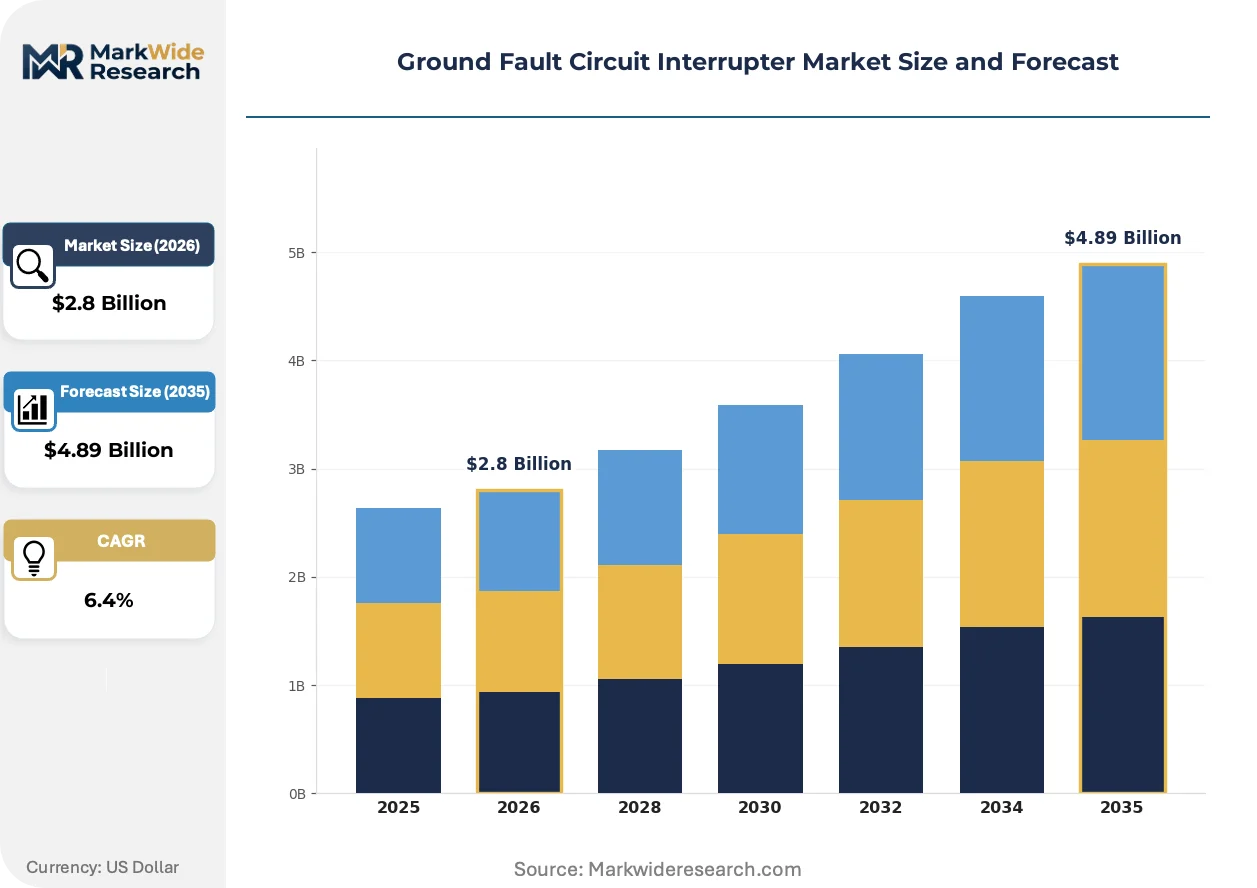
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential GFCI, Commercial GFCI, Portable GFCI, Industrial GFCI, Electrical Panel GFCI Technology: Manual Reset, Automatic Reset, Self-Test, Combination Arc-Fault, GFCI with AFCI Application: Home Electrical Safety, Construction Sites, Outdoor Equipment, Wet Locations, Healthcare Facilities End User: Electrical Contractors, Facility Managers, Electrical Inspectors, Safety Consultants |
| Companies Covered | Leviton, Eaton, ABB, Hubbell, Siemens, Schneider Electric, Legrand, Littelfuse, Sensata Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Fault Circuit Interrupter Market Emerging Trajectories
Semiconductor material transitions and automated diagnostic capabilities are compressing fault-response windows while embedding intelligence directly into branch circuit protection devices.
Silicon carbide power semiconductors are decentralizing thermal management architectures in GFCI designs by enabling higher operating temperatures without external heat sinking. Electrical contractors in high-humidity coastal markets are specifying SiC-based units for outdoor and basement applications where conventional silicon devices experience accelerated degradation. This material shift is decentralizing the historical trade-off between device compactness and environmental durability.
OSHA's updated construction safety directives are mandating portable GFCI deployment on temporary power distribution systems for all 120-volt single-phase circuits. The enforcement expansion affects general contractors and specialty trades across commercial building and infrastructure verticals. Industrial-grade portable manufacturers are responding with sealed housings and automatic self-test features to reduce field failure liability.
Electrical contractor procurement patterns are consolidating around integrated safety-device platforms that bundle GFCI, AFCI, and surge protection in single-receptacle form factors. Wholesale distributors are displacing standalone GFCI SKUs with combination units that reduce inventory complexity and improve average transaction values. This specification bundling is most visible in Texas and California new residential construction where code adoption cycles run ahead of national baselines.
Ground Fault Circuit Interrupter Market Segmentation
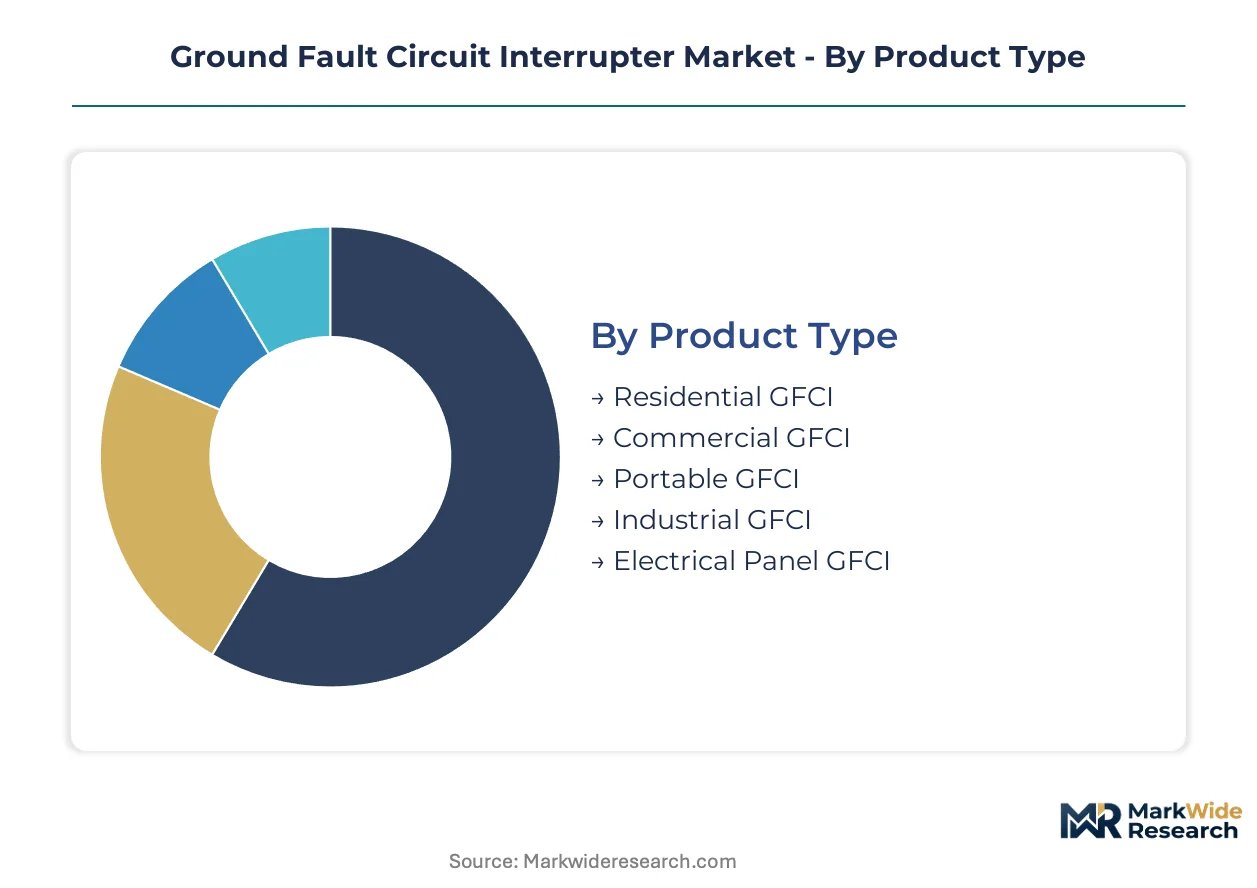
GFCI segmentation reflects divergent upgrade cycles across residential, commercial, and industrial electrical infrastructure. Each dimension—product form, intelligence level, application environment, and procurement authority—carries distinct replacement timelines and specification requirements that shape vendor portfolio priorities.
Product Type:
Replacement cycles vary sharply between permanently installed branch-circuit protection and portable job-site units, with code-mandated retrofit windows driving bulk procurement timing.
- Residential GFCI:Standard receptacle and circuit-breaker formats dominate unit volume. NEC expansion to kitchens, laundry areas, and basements in single-family and multifamily construction drives replacement waves in California and Texas housing markets.
- Commercial GFCI:Specification-grade receptacles with enhanced durability ratings serve retail, office, and hospitality environments. Health department electrical safety inspections in food service facilities are accelerating kitchen and service area upgrades beyond baseline code compliance.
- Portable GFCI:OSHA construction standards mandate deployment on temporary power distribution systems for 120-volt single-phase circuits. Sealed housings and automatic self-test features reduce field failure liability for general contractors.
- Industrial GFCI:Heavy-duty enclosures withstand manufacturing floor conditions and extended duty cycles. Demand concentrates in automotive and chemical processing plants where moisture exposure elevates personnel risk.
- Electrical Panel GFCI:Circuit-breaker integration protects entire branch circuits from distribution panels. New construction specifications favor this format for whole-house protection in premium residential segments.
Volume placements concentrate in Residential GFCI; the faster expansion belongs to Electrical Panel GFCI.
Technology:
Intelligence integration is compressing fault-response windows while embedding automated diagnostic capabilities that reduce manual inspection burdens.
- Manual Reset:Basic electromechanical designs require user intervention after trip events. Cost-sensitive retrofit applications in older housing stock sustain residual demand despite functionality limitations.
- Automatic Reset:Self-restoring operation suits unmanned equipment and remote installations. Agricultural and utility applications specify these units for irrigation pumps and outdoor lighting circuits.
- Self-Test:Periodic functionality verification automates compliance documentation for electrical contractors and facility managers. Silicon carbide semiconductor adoption enables faster fault response and higher thermal tolerance in moisture-prone environments.
- Combination Arc-Fault:Dual-mode protection integrates GFCI leakage detection with series and parallel arc-fault interruption. Wholesale distributors are displacing standalone SKUs with these combination units to reduce inventory complexity.
- GFCI with AFCI:Distinct circuit-breaker implementations separate ground-fault and arc-fault protection functions. Texas and California new residential construction specify these ahead of national code adoption baselines.
Procurement is shifting toward Combination Arc-Fault; Self-Test commands the steepest expansion trajectory as code cycles mandate automated verification.
Application:
Environmental risk profiles determine specification grade, with moisture exposure and personnel density dictating trip sensitivity and enclosure sealing requirements.
- Home Electrical Safety:Kitchen, bathroom, basement, and outdoor receptacle protection dominates code-mandated installations. NEC amendment cycles directly stimulate replacement demand as coverage expands to additional dwelling spaces.
- Construction Sites:Temporary power distribution for tools and equipment requires portable and cord-connected GFCI protection. OSHA enforcement actions against general contractors sustain industrial-grade unit demand.
- Outdoor Equipment:Pool pumps, spa equipment, and landscape lighting specify weather-resistant housings with enhanced sealing. Coastal markets in Florida and the Gulf states accelerate degradation of conventional silicon devices.
- Wet Locations:Commercial kitchens, car washes, and agricultural processing demand specialized designs with corrosion-resistant components. Health department inspections drive food service facility electrical safety upgrades.
- Healthcare Facilities:Patient care areas require hospital-grade receptacles with superior grounding and retention force. Isolated power systems in operating suites add complexity to GFCI specification.
Unit demand clusters in Home Electrical Safety; Healthcare Facilities show the fastest share gain as patient safety protocols tighten.
End User:
Procurement authority and technical sophistication determine channel access, with licensed electrical professionals controlling specification in code-compliant installations.
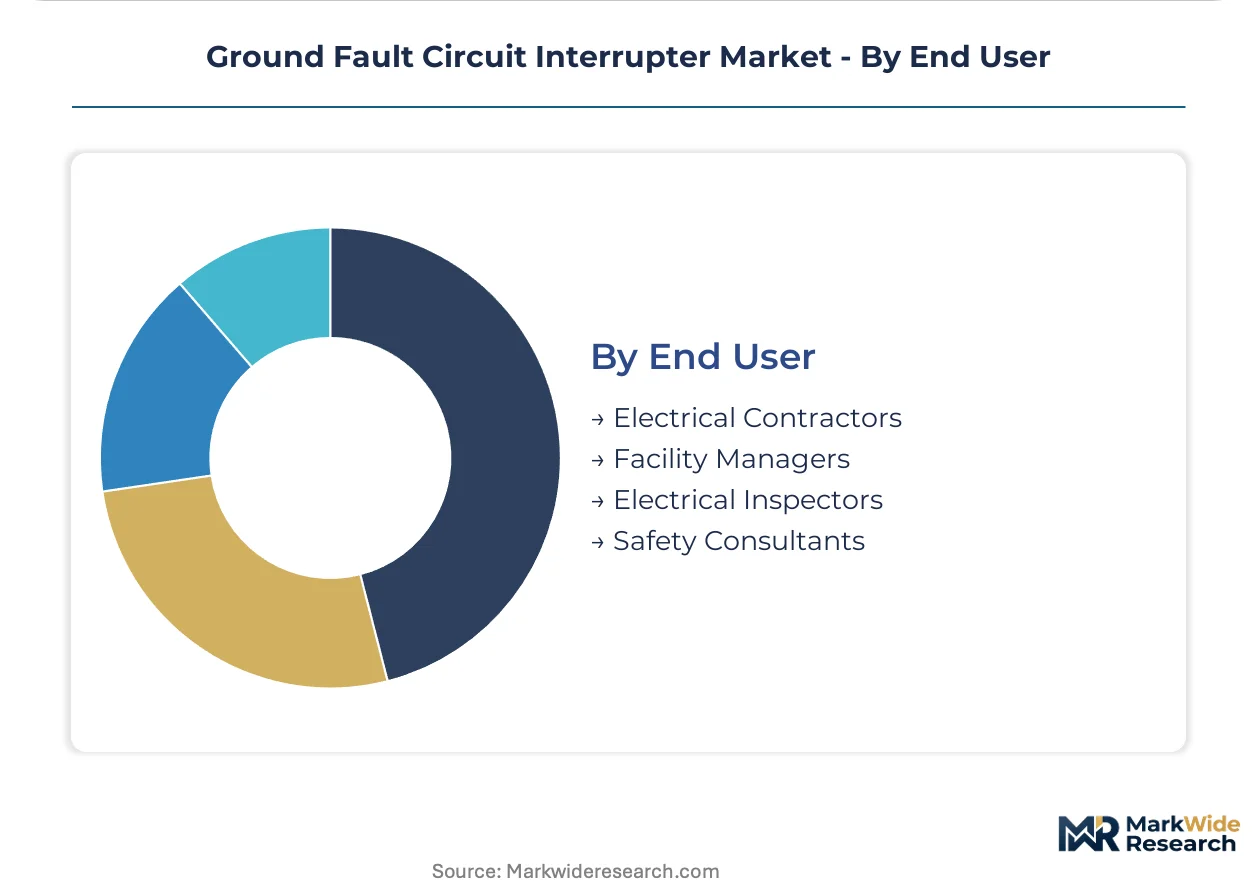
- Electrical Contractors:Licensed professionals specify and install the majority of permanent GFCI devices. Journeyman pipeline constraints in Texas and Florida extend installation backlogs and delay revenue recognition.
- Facility Managers:Commercial and institutional maintenance departments manage replacement cycles and compliance documentation. Self-test automation reduces their manual inspection burdens and liability exposure.
- Electrical Inspectors:Local authorities having jurisdiction enforce NEC compliance and approve installations. Their interpretation of code amendments directly shapes regional specification timing.
- Safety Consultants:Third-party auditors recommend GFCI upgrades for liability reduction and insurance compliance. Industrial and healthcare clients retain these advisors for risk assessment beyond baseline code requirements.
Electrical Contractors control the largest placement volume; Safety Consultants are gaining influence fastest as liability litigation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction code enforcement concentrates GFCI procurement in jurisdictions with aggressive electrical safety adoption timelines. Regional demand patterns track housing permit velocity, renovation inspection backlogs, and state-level NEC amendment schedules.
United States
Residential housing starts in California and Texas drive bulk GFCI installations for new single-family and multifamily dwellings. The National Electrical Code mandate expansion to kitchens, laundry areas, and basements tightens compliance windows nationwide. Houston and Dallas-Fort Worth electrical contractors face extended installation backlogs due to journeyman pipeline constraints.
Canada
Provincial building code harmonization with NEC standards accelerates GFCI retrofit demand in Ontario and British Columbia renovation markets. Health Canada electrical safety directives align with OSHA-inspired construction site protection requirements. Toronto and Vancouver commercial kitchen modernization projects specify weather-resistant GFCI units for food service facility upgrades.
Germany
Industrial facility electrical safety upgrades in Baden-Württemberg and Bavaria sustain demand for panel-integrated GFCI protection. The VDE certification framework enforces rigorous fault-response testing that favors silicon carbide semiconductor adoption. Stuttgart automotive manufacturing plants specify heavy-duty GFCI enclosures for moisture-prone assembly floor environments.
China
Urban residential construction in the Yangtze River Delta and Pearl River Delta drives receptacle-format GFCI volume. GB standards for electrical safety in wet locations tighten specification requirements for commercial kitchen and outdoor equipment applications. Shenzhen and Shanghai electrical component distributors stock combination AFCI-GFCI units ahead of anticipated code convergence.
India
Smart city infrastructure investments in Maharashtra and Karnataka create specification opportunities for self-test GFCI integration with energy management systems. The Central Electricity Authority building code amendments expand protection mandates to residential basements and outdoor circuits. Mumbai and Bengaluru electrical contractors report rising demand for portable GFCI units on construction job sites.
Ground Fault Circuit Interrupter Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with established electrical component conglomerates controlling permanent installation channels and regional fabricators capturing portable unit volume. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive distribution networks, specialized safety-device pure-plays with deep contractor relationships, and contract manufacturers serving private-label wholesale brands. Consolidation activity concentrates on acquiring self-test and combination-arc-fault technology portfolios. Geographic expansion into Texas and California construction markets represents the dominant competitive move as housing permit velocity outpaces national baselines.
Among diversified electrical component conglomerates, Eaton, Schneider Electric, and Legrand exemplify archetypes with upstream control over semiconductor sourcing and captive distribution networks. Eaton represents the vertically integrated industrial conglomerate with cost-structure command across residential production lines. Schneider Electric anchors the contractor-relationship specialist archetype through deep North American electrical wholesaler partnerships. Legrand occupies the premium-product differentiation position via specialization in self-test and combination arc-fault receptacle formats.
| Leading Market Players |
|---|
| Leviton |
| Eaton |
| ABB |
| Hubbell |
| Siemens |
| Schneider Electric |
| Legrand |
| Littelfuse |
| Sensata Technologies |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor sourcing through in-house silicon carbide fabrication anchors Eaton's cost-structure command across residential GFCI production lines. This backward integration shields margin positions against copper and rare earth input volatility while compressing procurement lead times for standardized receptacle formats.
Pricing Analysis
Volume placements in standard residential receptacles generate thin margins, while premium self-test and combination arc-fault units capture wider spreads. Three-tier pricing structure across premium, standard, and economy levels reflects UL 943 certification grade and silicon semiconductor material tier. Cost compression in economy residential units is intensifying because contractor channel concentration limits pricing autonomy for manufacturers without direct electrical wholesaler relationships. Electrical contractors exhibit highest price sensitivity on bulk new-build specifications; facility managers in healthcare and commercial segments demonstrate lowest sensitivity due to liability-driven procurement protocols.
Supply Chain Analysis
Regional distribution centers in Texas and California operate as hub-and-spoke nodes feeding electrical wholesaler networks across western and southern construction corridors. Manufacturing concentration centers on Mexico for assembly labor cost advantages, China for semiconductor-grade silicon and magnetic core materials, and the United States for final UL certification and quality verification. Supply chain risk hinges on single-source vulnerability for silicon carbide substrates, where limited qualified vendors constrain rapid capacity scaling. Distribution runs through consolidated electrical wholesaler networks that bundle GFCI procurement with broader electrical component purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GFCI market sits in a silicon carbide semiconductor transition phase, with wide-bandgap materials displacing conventional silicon architectures in moisture-prone and high-temperature applications.
For Market Incumbents: Extend captive silicon carbide sourcing agreements to lock in substrate supply ahead of competing demand from automotive and renewable energy sectors. Deepen contractor-direct relationships in Texas and California to bypass wholesaler channel concentration that erodes pricing autonomy. Invest in UL 943 certification pre-validation to compress competitive response windows when revised trip-time protocols take effect.
For New Entrants and Emerging Players: The price-point gap between premium combination arc-fault units and economy manual-reset receptacles creates specification white space for mid-tier self-test products with automated diagnostic features. Target commercial kitchen modernization verticals in food service facilities, where health department electrical safety inspections drive upgrade cycles beyond baseline code compliance. Pursue private-label partnerships with regional electrical distributors seeking to displace standalone SKUs with combination safety-device platforms.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electrical component conglomerates seeking self-test and combination-arc-fault technology portfolios. Long-term viability favors vendors with backward integration into semiconductor sourcing and established contractor channel relationships. Monitor NEC amendment adoption timelines across state-level jurisdictions as the primary inflection indicator for compliance-driven procurement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Adoption | Wide-bandgap materials enable faster fault response in moisture-prone basement and outdoor applications. |
| Self-Test Automation Integration | Automated periodic verification reduces manual inspection burdens for electrical contractors and facility managers. |
| Combination Arc-Fault Platform Development | Dual-mode protection consolidates inventory complexity for wholesale distributors serving residential construction. |
| Contractor Channel Direct Relationships | Bypassing wholesaler concentration restores pricing autonomy and accelerates specification influence in Texas and California. |
| California Title 24 Alignment | State building energy efficiency standards create regulatory laboratory for advanced safety-device integration with load controls. |
Methodological Framework
Independent corroboration across electrical contractor interviews, electrical inspector consultations, and wholesale distributor operational data underwrites the qualitative findings in this study. Primary fieldwork engaged licensed electricians, facility managers at commercial and healthcare institutions, and procurement leads at regional electrical distribution networks. Secondary validation drew from National Electrical Code amendment documentation, OSHA construction safety directive filings, UL certification protocol updates, and housing permit velocity data from California and Texas metropolitan statistical areas. Bottom-up unit demand modeling triangulates against top-down construction spending allocation estimates.
Comparable-period anchoring to historical NEC adoption cycles and state-level amendment timelines structured the projection framework across the analysis window. Segmentation dimensions modeled include product form factor, intelligence level technology tier, application environment risk profile, and procurement authority archetype. CAGRs derive from regression against construction permit trajectories, copper price index movements, and semiconductor material cost curves. Industry-specific forecast inputs incorporate journeyman electrician pipeline constraints and UL 943 certification timeline extensions.
Inputs from electrical contractor panels and wholesale distributor operational databases were available through the study window; gaps in real-time construction permit volatility introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding NEC amendment adoption schedules and silicon carbide substrate supply expansion. Copper and rare earth commodity price swings, licensed electrician shortage severity in Texas and Florida, and multi-brand interoperability field failures represent specific risk factors that could revise trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Insulator Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Vacuum Interrupter Market