
 Ceiling Fans Market | 2026-2036
Ceiling Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Ceiling Fans Market Intelligence
The shift toward brushless DC motor technology is unwinding the traditional dominance of lower-cost AC motor fans. Hunter Fan Company leverages its long-standing brand reputation in the premium residential segment. In contrast, Havells sustains a strong position in the rapidly expanding Indian market through extensive distribution networks. Crompton Greaves also competes fiercely in South Asia with a wide product portfolio.
Ceiling fans are air-circulating devices, typically using blades with a specific pitch between 12 and 16 degrees to move air efficiently. Their primary function is to enhance thermal comfort and reduce HVAC energy load in enclosed spaces. The residential end-user segment remains the largest by volume, but the fastest-growing category is smart fans, which integrate remote control and Bluetooth connectivity. Energy-efficient fans utilizing DC motor technology command higher margins compared to conventional AC motor models.
Product design and market access are shaped by energy efficiency regulations, such as the EPA's ENERGY STAR program in the United States and the EU's Ecodesign Directive. In India, Bureau of Indian Standards (BIS) certification is mandatory, influencing safety and performance benchmarks for all manufacturers. Vendor differentiation will increasingly depend on the ability to integrate smart features and meet evolving regional energy consumption standards.
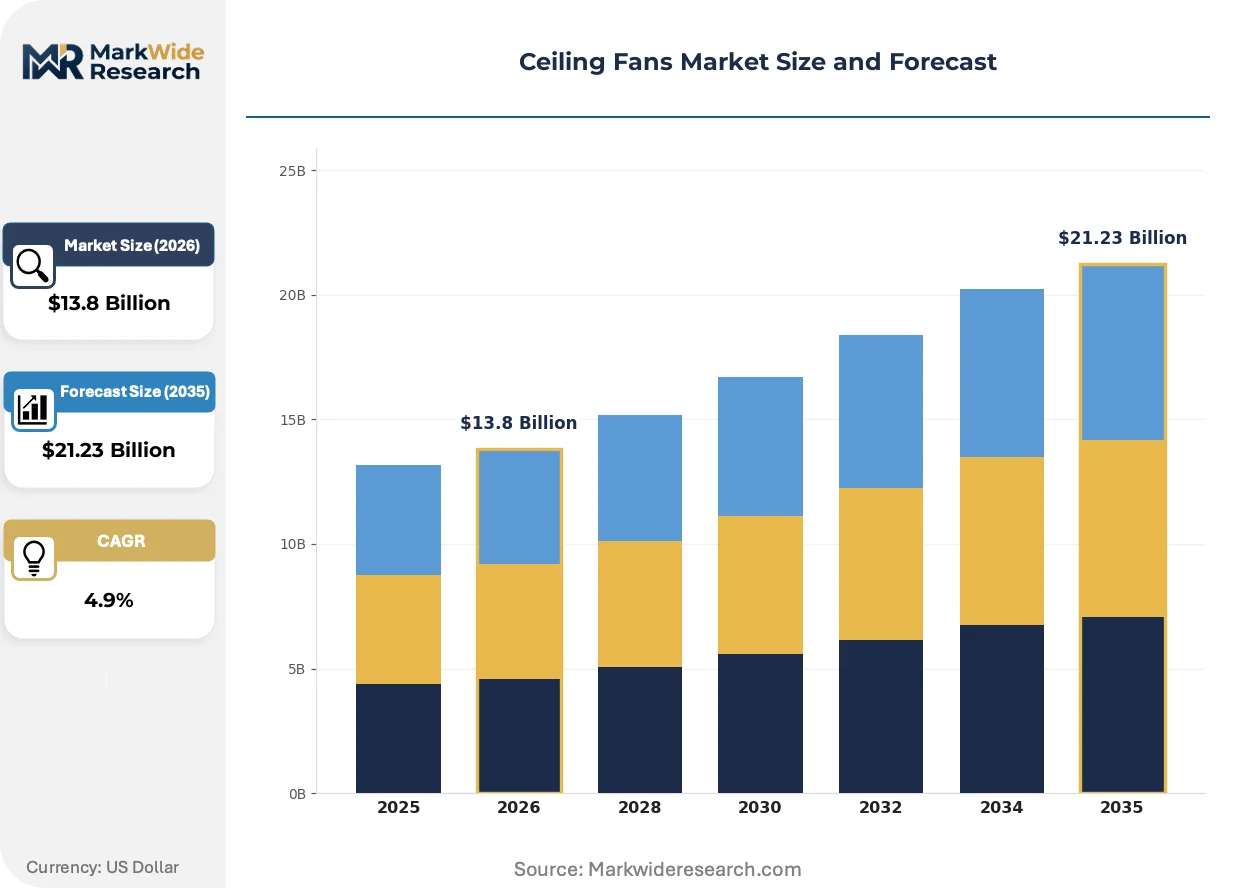
Market Dynamics
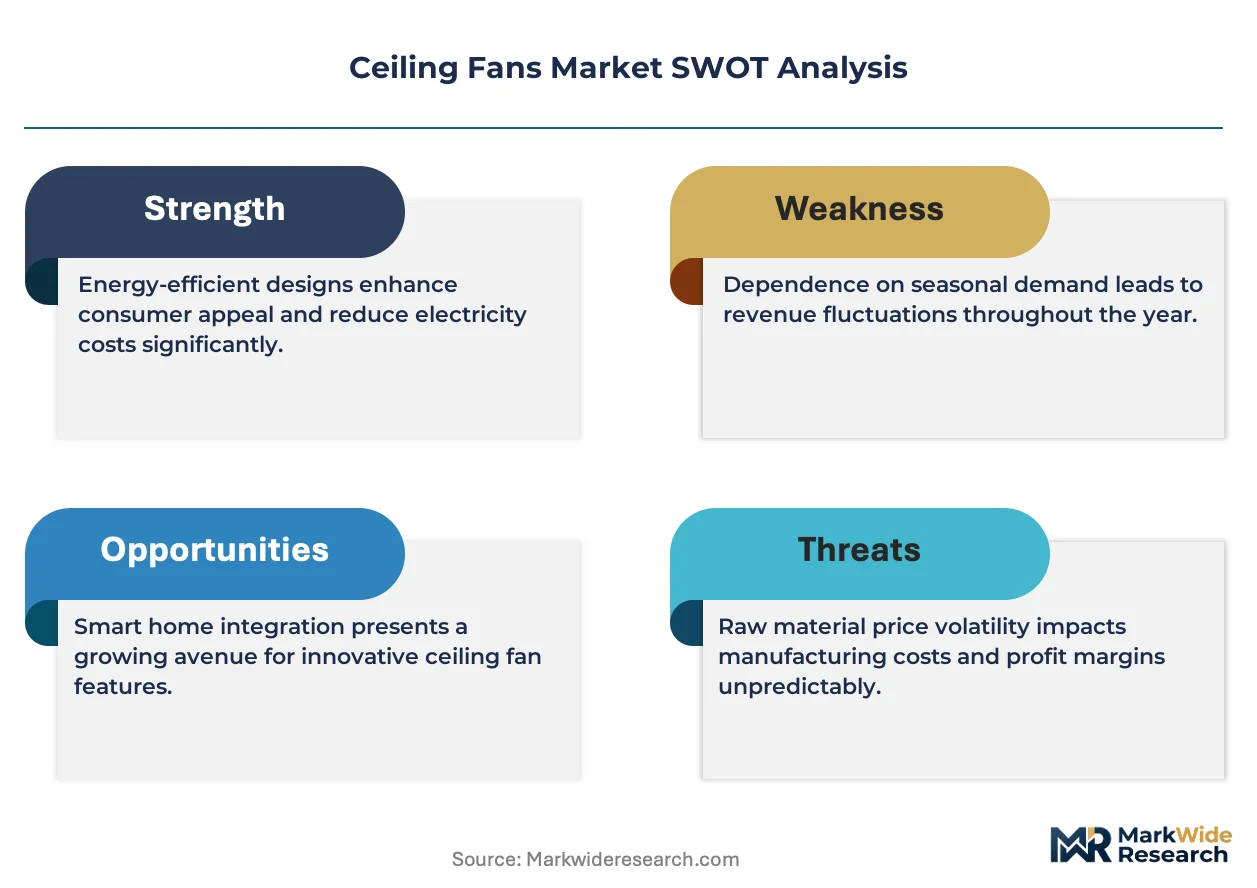
The ceiling fan market is defined by a technology-driven value shift, where energy efficiency mandates from regulators like the US Department of Energy are compelling a transition from traditional AC motors to more efficient, higher-margin DC motor technology.
Growth Catalysts
- Residential Electrification:Widespread grid expansion and rural electrification programs, particularly across India, are creating a vast first-time buyer market for essential home appliances including ceiling fans.
- Hospitality Sector Specifications:The global hospitality industry's focus on guest comfort and energy reduction in new builds and renovations drives demand for decorative and smart fans.
- Energy Efficiency Mandates:Regulations such as the EPA's ENERGY STAR program in the United States create a clear market incentive for manufacturers to produce and consumers to purchase higher-efficiency models.
Market Restraints
- AC Motor Cost Structure:The established, low-cost manufacturing base for traditional AC motor fans creates significant price competition and inertia, slowing adoption of more expensive DC motor technologies.
- Raw Material Price Volatility:Fluctuations in the prices of copper for motor windings and electrical steel for laminations directly impact production costs and can compress manufacturer margins. -
- Substitution by Air Conditioning:In markets with high disposable incomes, the increasing affordability and prevalence of split and central air conditioning systems limit the fan market's growth potential.
Strategic Opportunities
- Smart Home Ecosystem Integration:Developing fans with native support for platforms like Google Home and Amazon Alexa allows manufacturers to tap into the growing connected home market.
- HVLS Fan Applications:High-volume, low-speed (HVLS) fans present an opportunity in large commercial and industrial spaces like warehouses and gymnasiums not well-served by traditional fans.
- Ecodesign Directive Alignment:Proactively designing products that exceed the EU's Ecodesign Directive requirements can provide a competitive advantage and secure market access in Europe.
Industry Challenges
- Component Supply Chain Concentration:Over-reliance on a limited number of suppliers in specific regions of China for critical electronic components and brushless DC motors creates significant geopolitical and logistical risks.
- Navigating BIS Certification:The mandatory Bureau of Indian Standards (BIS) certification process for fans sold in India presents a complex and time-consuming compliance hurdle for all manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceiling Fans Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $21.23 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fans, Energy-Efficient Fans, Smart Fans, Decorative Fans Technology: DC Motor, AC Motor, Remote Control, Bluetooth End User: Residential, Commercial, Industrial, Hospitality Size: Small, Medium, Large, Extra Large |
| Companies Covered | Crompton Greaves, Havells, Hunter Fan Company, Minka Group, Panasonic, Honeywell, Orient Electric, Lithonia Lighting, Westinghouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceiling Fans Market Strategic Shifts & Innovations
Product innovation is converging on two fronts: the integration of smart, connected features and the relentless engineering pursuit of greater energy efficiency. This dual focus is redefining product tiers and competitive differentiation, moving beyond simple aesthetics and air movement.
Brushless DC motor technology provides superior energy efficiency and quieter operation through electronic commutation. The premium residential segment and commercial specifiers are leading adoption, driven by long-term cost-of-ownership calculations. This technology is decomposing the market's traditional price-volume structure, establishing a distinct high-performance tier separate from legacy AC motor products.
India's Bureau of Energy Efficiency (BEE) Star Labeling Program has become a powerful market force, making energy performance a primary consumer consideration. The regulation compels manufacturers to innovate toward higher star ratings, as lower-rated models are becoming less commercially viable. This affects the mass-market residential segment most acutely, reshaping product portfolios across the subcontinent.
Consumer purchasing behavior is increasingly migrating from physical retail to online channels, including direct-to-consumer (D2C) websites and major e-commerce platforms. This trend disrupts the long-standing dominance of electrical distributor and home improvement store channels, forcing brands to invest in digital marketing and logistics. The shift is most pronounced in North America for DIY residential installations.
Ceiling Fans Market Segmentation
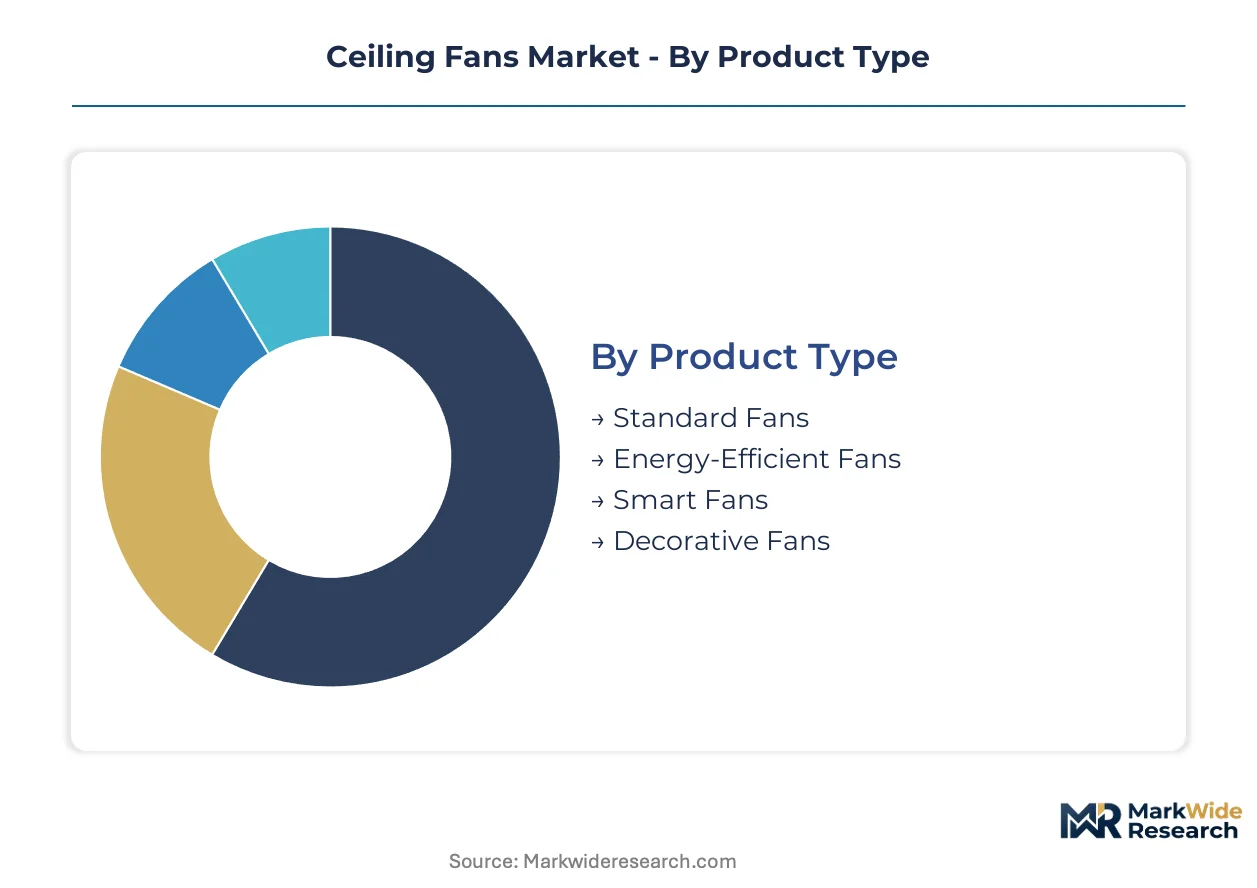
The global ceiling fans market categorizes products and technologies based on their distinct functional attributes and end-user applications. Understanding these segments provides clarity on demand drivers, technological shifts, and competitive landscapes across diverse geographic regions. This segmentation analysis highlights where market value aggregates and where future expansion efforts will concentrate.
Product Type:
The product type segmentation reveals shifts in consumer preferences and regulatory impacts across different global markets. Standard fans maintain widespread presence in developing economies, while advanced models gain traction in more regulated or affluent regions.
- Smart Fans:These models integrate with smart home ecosystems, offering remote control via apps, voice assistants, and automated scheduling for enhanced user convenience. Demand for smart fans is expanding rapidly in North America and Western Europe, driven by connected home trends and consumer desire for integrated appliance control.
- Energy-Efficient Fans:Engineered to consume less power, these fans often incorporate DC motor technology and advanced aerodynamic blade designs. Regulatory mandates from bodies like the US Department of Energy and India's BEE Star Labeling program are compelling manufacturers and consumers toward these more efficient models, particularly in price-sensitive markets like India.
- Standard Fans:These traditional models utilize AC motors and offer basic on/off and speed control, representing the foundational product tier. Their lower manufacturing cost ensures continued high volume sales in price-conscious residential markets across Asia and Africa.
- Decorative Fans:Designed with aesthetic appeal as a primary consideration, these fans often feature unique finishes, lighting integration, and designer-inspired styles. The hospitality sector and premium residential renovations in developed markets frequently specify decorative fans.
Standard Fans holds the largest share; momentum sits with Smart Fans.
Technology:
Technology segmentation underscores the varying cost structures and performance capabilities that define product offerings and target customer segments. Higher-margin technologies often align with specific regulatory compliance or premium market positioning.
- DC Motor:Brushless direct current motors offer superior energy efficiency, quieter operation, and precise speed control compared to traditional AC motors. These premium components command higher margins and are increasingly specified in energy-conscious markets and for smart fan applications.
- AC Motor:Alternating current motors represent the conventional and most widely adopted technology for ceiling fans due to their established manufacturing base and lower unit cost. This technology dominates the mass-market residential segment, particularly in regions with less stringent energy efficiency standards.
- Remote Control:This feature provides convenient operation from a distance, enhancing user comfort without requiring physical interaction with the fan unit. Remote control functionality is a common upgrade across mid-range and premium fan models globally.
- Bluetooth:Bluetooth connectivity enables direct control of fan functions via a smartphone app, often serving as a gateway to more advanced smart features. This technology primarily serves the connected home segment, integrating fans into broader smart appliance ecosystems.
DC Motor technology commands higher margins, while AC Motor technology dominates volume sales.
End User:
The end-user segmentation highlights the diverse application areas for ceiling fans, each with specific requirements for performance, aesthetics, and operational scale. Different sectors prioritize distinct fan attributes, influencing product development.
- Residential:This segment encompasses individual homes and apartments, representing the largest volume market for ceiling fans. Widespread residential electrification programs, particularly in India, continue to drive substantial first-time buyer demand.
- Hospitality:Hotels, resorts, and restaurants specify ceiling fans for guest comfort and aesthetic enhancement in common areas and guest rooms. The global hospitality industry's focus on energy reduction and guest experience drives demand for decorative and smart models.
- Commercial:This category includes office buildings, retail stores, and educational institutions, where fans contribute to climate control and air circulation. Commercial applications often prioritize durability, quiet operation, and integration with building management systems.
- Industrial:Warehouses, factories, and large workshops utilize high-volume, low-speed (HVLS) fans to improve air circulation and thermal comfort over vast spaces. These applications demand robust construction and powerful air movement capabilities.
The residential segment drives the largest market share, with hospitality exhibiting significant expansion.
Size:
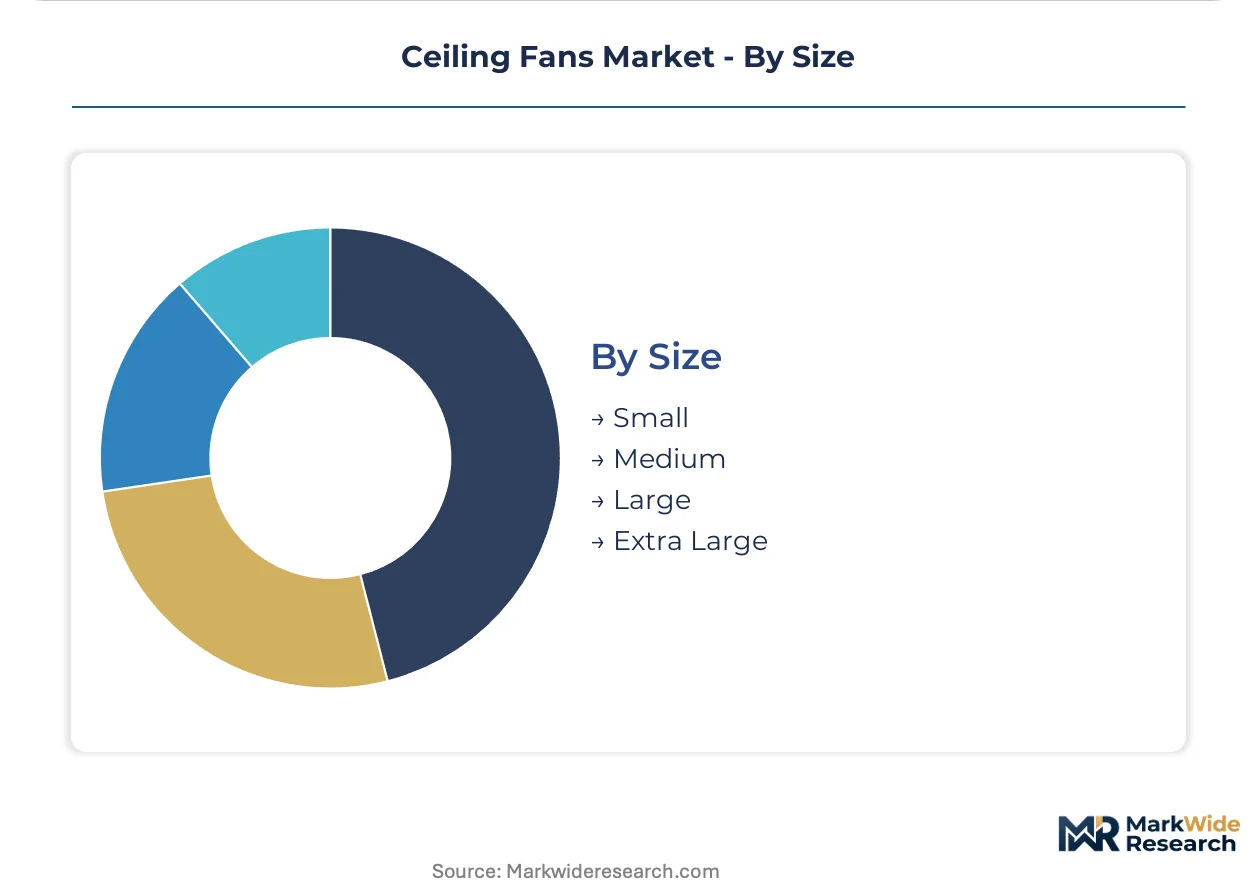
The size segmentation reflects the varying physical dimensions of ceiling fans, which directly correlate with their intended application and air delivery capacity. Different room sizes and ceiling heights necessitate specific fan dimensions for optimal performance.
- Large:Fans in this category typically feature blade spans exceeding 50 inches, designed for larger rooms, commercial spaces, or industrial applications. These fans deliver substantial airflow, often incorporating advanced motor technologies for efficiency.
- Medium:These fans generally have blade spans between 40 and 50 inches, suitable for average-sized residential rooms and smaller commercial settings. Medium fans represent a versatile and widely adopted size for general air circulation needs.
- Small:Characterized by blade spans under 40 inches, small fans are ideal for compact spaces, hallways, or specific task areas. Their compact design allows for installation in locations where larger fans would be impractical.
- Extra Large:This specialized category includes fans with exceptionally long blade spans, primarily used in very large commercial or industrial environments like gymnasiums or aircraft hangars. These units are often HVLS fans, designed for massive air displacement.
Medium-sized fans are foundational for general use, while large and extra-large categories serve specialized environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global ceiling fans market exhibits a supply-side concentration for critical electronic components and brushless DC motors. This reliance on specific regions, particularly within China, influences manufacturing costs and product availability worldwide. Demand drivers and regulatory frameworks vary significantly across key geographies.
India
Widespread residential electrification and a tropical climate drive substantial first-time buyer demand. The Bureau of Indian Standards (BIS) certification is mandatory, influencing safety and performance benchmarks for all manufacturers. India's Bureau of Energy Efficiency (BEE) Star Labeling Program compels manufacturers to innovate toward higher star ratings. Manufacturing hubs like Gujarat and Maharashtra are rapidly adapting production lines for energy-efficient models.
United States
Consumer preferences for smart home integration and premium features shape residential demand for advanced fan models. The EPA's ENERGY STAR program incentivizes the purchase of high-efficiency ceiling fans. US Department of Energy mandates compel a transition from traditional AC motors to more efficient DC motor technology. California's stringent energy codes often lead product development for the wider North American market.
China
A large domestic market and significant manufacturing capacity for components define this region's fan supply. Strict GB standards influence both product safety and performance characteristics for local consumption. China is a primary source for critical electronic components and brushless DC motors, impacting global supply chains. Guangdong province serves as a major production base for fan components and finished goods.
Germany
Demand for energy-efficient and aesthetically integrated solutions is pronounced in new construction and renovations. The EU's Ecodesign Directive mandates minimum energy performance standards for fans sold across the European Union. This regulation drives innovation towards quieter and more efficient DC motor technology. Engineering clusters in Bavaria focus on developing advanced motor technologies for premium applications.
Ceiling Fans Market Key Industry Players
Concentration sits with established brands leveraging premium positioning and extensive distribution networks. The global ceiling fan market exhibits a tiered structure, from high-performance smart fans integrating advanced technology to traditional AC motor models. Strategic archetypes include heritage brands focused on design, regional powerhouses with strong local distribution, and technology-focused innovators specializing in energy efficiency. Companies pursue portfolio diversification, geographic expansion, and smart home ecosystem integration to secure market share.
On the premium-tier vector, Hunter Fan Company represents a heritage brand focused on residential segments in developed markets. This company primarily addresses consumers seeking high-quality, decorative, and smart fan models. India-based Havells exemplifies a regional powerhouse, leveraging extensive distribution networks in rapidly expanding economies, particularly for mass-market residential electrification. Crompton Greaves, another South Asian entity, sits within the diversified portfolio archetype, competing across a wide product range while adapting to energy efficiency mandates like BEE Star Labeling. These entities navigate evolving energy efficiency mandates and consumer preferences for smart features.
| Leading Market Players |
|---|
| Crompton Greaves |
| Havells |
| Hunter Fan Company |
| Minka Group |
| Panasonic |
| Honeywell |
| Orient Electric |
| Lithonia Lighting |
| Westinghouse |
| Others |
Cost & Logistics Intelligence
Extended lead times for brushless DC motors often translate into higher component costs, impacting the final product pricing and manufacturers' margins. This supply concentration directly influences the market's tiered pricing structure.
Pricing Analysis
India's BEE Star Labeling Program dictates the pricing tier structure for fans sold in the subcontinent. Pricing stratifies across premium, standard, and economy tiers, largely driven by energy efficiency ratings and incorporated smart features. Brand premium, such as that commanded by Hunter Fan Company, also drives price differentiation in developed markets. Pricing softness persists in the standard AC motor segment due to intense competition and raw material price volatility. The mass-market residential segment, particularly in India, exhibits the highest price sensitivity for basic models.
Supply Chain Analysis
Over-reliance on specific regions within China for critical electronic components and brushless DC motors creates a significant supply chain chokepoint. China, particularly Guangdong province, concentrates the global supply of these specialized fan components. The industry draws from copper for motor windings and electrical steel for laminations, both subject to price volatility. This component supply chain concentration poses significant geopolitical and logistical risks for global manufacturers. Distribution runs through a mix of online channels, traditional electrical distributors, and home improvement stores, with online channels gaining prominence for DIY installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the consumer preference for smart home integration and personalized comfort. New niches are emerging for specialized fan models and connected ecosystems.
For Market Incumbents: Secure component supply chains by diversifying sourcing beyond single regions, mitigating geopolitical risks. Invest in advanced DC motor R&D to counter the threat of displacement by tech-focused innovators. Strengthen distribution networks in high-growth regions like India, leveraging existing brand reputation to meet BEE Star Labeling requirements. Prioritize seamless integration into major smart home platforms to maintain premium segment leadership.
For New Entrants and Emerging Players: Specialized installation and integration services for complex smart fan systems represent a service-layer gap where incumbents under-serve. New entrants can target the rapidly expanding residential smart fan market in North America with user-friendly D2C offerings. Focus on developing fans with native support for platforms like Google Home and Amazon Alexa. A strong digital marketing strategy and efficient online logistics will enable market penetration.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven value shift play because energy efficiency mandates and smart home integration will redefine product tiers. Identify acquisition targets among vertically integrated mid-cap specialists holding strong intellectual property in brushless DC motor technology or robust smart connectivity platforms. The sustained growth of the hospitality sector also offers attractive opportunities for decorative fan manufacturers. A key signal to watch is the accelerated adoption rate of DC motor technology in the mass-market residential segment.
| Strategic Initiative | Industry Significance |
|---|---|
| DC Motor R&D Investment | Accelerates compliance with US Department of Energy mandates and captures higher margins from energy-efficient models. |
| Smart Home Platform Integration | Taps into the growing connected home market, enhancing user convenience with Amazon Alexa and Google Home. |
| Supply Chain Diversification | Mitigates geopolitical and logistical risks associated with component supply chain concentration in China. |
| BEE Star Labeling Compliance | Ensures market access and competitiveness in the rapidly expanding and regulation-driven Indian residential segment. |
| HVLS Fan Market Expansion | Addresses unmet demand in large commercial and industrial spaces not well-served by traditional fans. |
Research Approach
Desk research of industry reports, regulatory filings, and company disclosures preceded structured interviews with product managers, R&D engineers, procurement specialists, and sales directors. This approach combined primary insights with secondary validation from trade publications and government energy agencies. Bottom-up and top-down triangulation ensured data consistency across various market segments. These methods collectively informed the comprehensive market analysis.
The analytical framework employed variance decomposition to project market growth across the analysis window. Segmentation dimensions modeled included product type, technology, end user, size, and regional regulatory alignment. Compound Annual Growth Rates were derived from historical growth patterns and projected market accelerators. Key forecast inputs included residential electrification rates and energy efficiency mandate timelines.
Forecasts assume regulatory continuity in US, Indian, and EU regimes; material policy shifts would require re-modeling. The analysis reflects current market conditions and known technological trajectories. Geopolitical supply chain disruptions or rapid shifts in raw material prices represent key risk factors. Practitioners should keep alternative scenarios live as global economic and regulatory landscapes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Global Sealed DC Contactor Market