
 India Electrical Testing Services Market | 2026-2036
India Electrical Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Electrical Testing Services Market Foresight
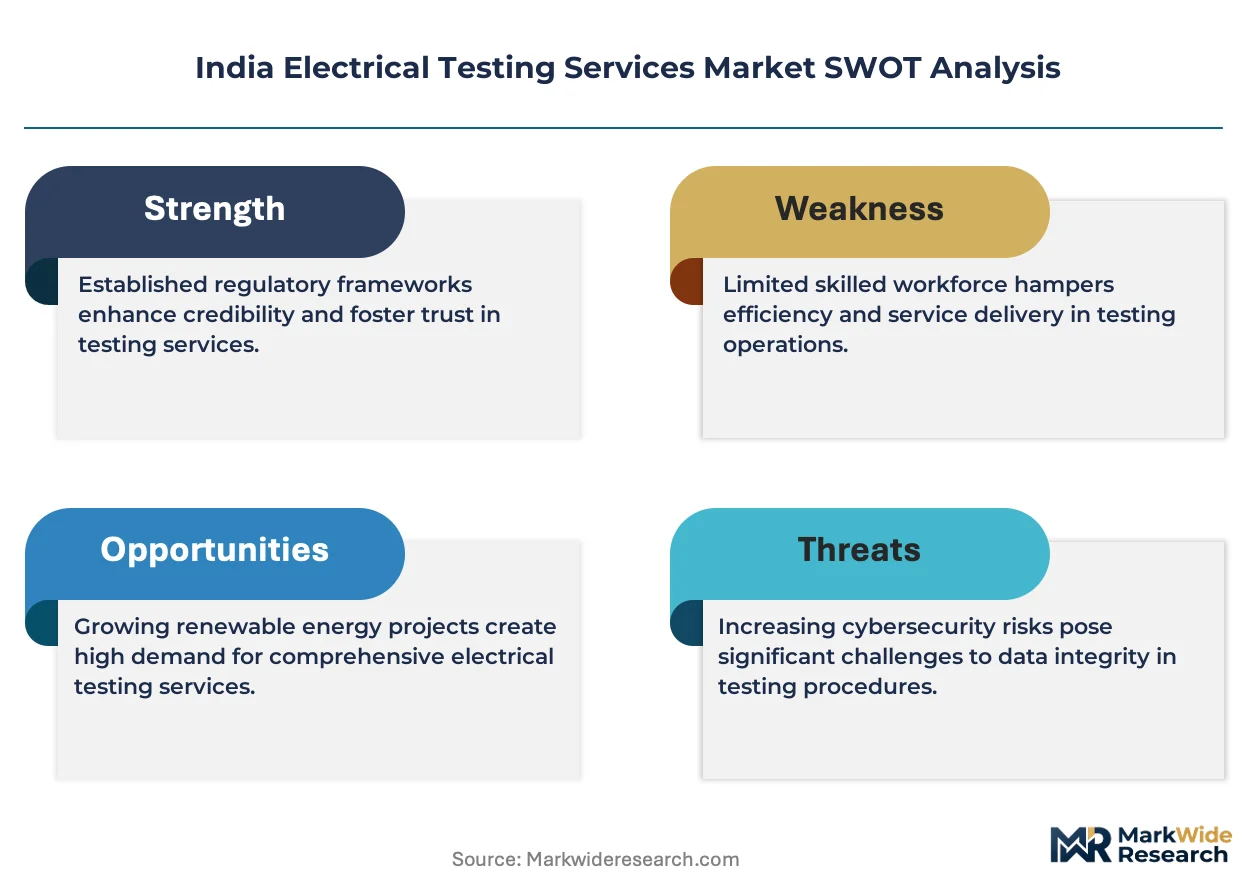
Asset-light leasing models for high-voltage test equipment is narrowing the capital barrier for mid-tier entrants. INEL Power System Engineers Pvt. Ltd. leverages its transformer testing specialization to dominate western India utility contracts. Voltech Group anchors its position through captive calibration labs that reduce third-party dependency. ITC India Private Limited competes on IEC and IS standard dual-certification breadth across manufacturing plant clients.
Electrical testing services encompass diagnostic evaluation of power apparatus through high-voltage withstand tests, insulation resistance measurement, and circuit integrity verification against rated thermal limits. These services prevent catastrophic failure in distribution networks and industrial feeders by detecting dielectric degradation before breakdown. Transformer testing commands the deepest margin pool due to aging utility infrastructure and renewable integration stress, while insulation resistance testing sustains volume leadership from its ubiquity across preventive maintenance schedules. IEC Standards and IS Standards together structure procurement requirements, with IS Standards gaining ground as domestic content rules tighten.
BIS certification requirements and CEA grid code compliance obligations compel utilities and industrial licensees to maintain documented testing cadences. The Electricity Act enforcement by state regulatory commissions amplifies penalty exposure for non-compliant operators. Stakeholders must monitor how PLI scheme disbursements for domestic equipment manufacturing reshape testing demand toward locally certified laboratories.
Market Dynamics
The India Electrical Testing Services Market pivots on CEA-mandated periodic testing protocols that force utilities and industrial licensees into documented compliance cadences. Grid modernization investments and renewable integration stress are amplifying testing frequency requirements across transmission and distribution networks.
Growth Catalysts
- CEA Grid Code Mandates:Central Electricity Authority regulations compel documented testing cadences for all transmission assets above 66 kV, creating recurring revenue pools for certified laboratories.
- PLI Scheme Disbursements:Production-linked incentive schemes for domestic power equipment manufacturing are redirecting testing demand toward BIS-certified local facilities.
- Maharashtra-Gujarat Industrial Clustering:Concentrated renewable energy parks and manufacturing zones in these states multiply transformer and switchgear testing workloads.
Market Restraints
- High-Voltage Equipment Capital Intensity:Dielectric test sets and impulse generators require substantial upfront investment, constraining mid-tier laboratory expansion.
- Skilled Technician Scarcity:Shortage of certified high-voltage test engineers limits service capacity scaling in tier-2 and tier-3 cities.
- Bureaucratic Certification Timelines:BIS laboratory accreditation processes extend 12-18 months, delaying market entry for new testing facilities.
Strategic Opportunities
- Tamil Nadu-Karnataka Renewable Corridors:Wind and solar park commissioning in southern states is generating unmet demand for inverter and transformer testing services.
- Asset-Light Equipment Leasing:Rental models for high-voltage test kits enable regional players to serve project-based demand without balance-sheet strain.
- Smart Grid Sensor Integration:Convergence of IoT monitoring with traditional high-voltage testing creates predictive maintenance service bundles.
Industry Challenges
- Multi-Standard Compliance Complexity:Laboratories must maintain simultaneous IEC and IS standard certifications, doubling quality system overhead.
- Aging Utility Workforce Transition:State electricity boards face knowledge gaps as experienced field engineers retire without structured succession protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electrical Testing Services Market |
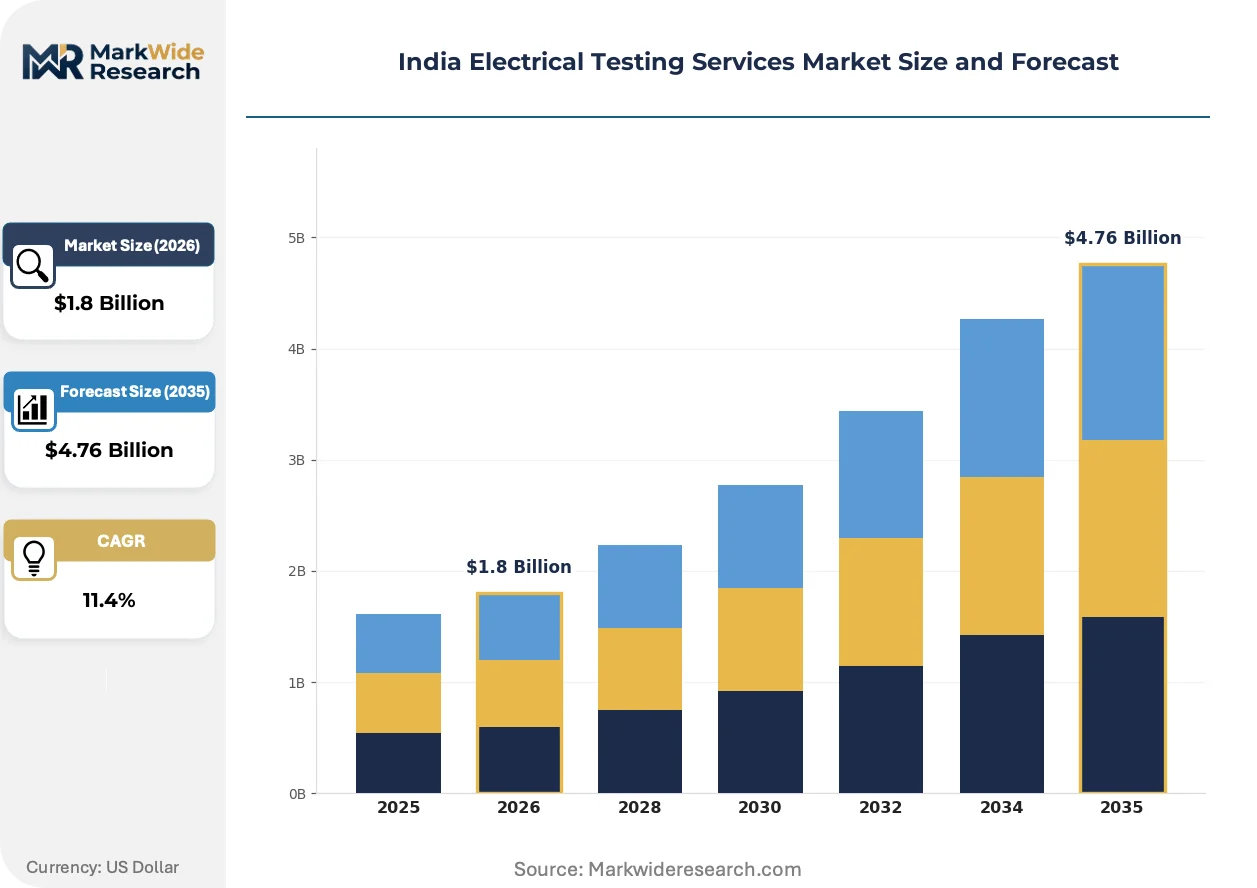
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: High Voltage Testing, Insulation Resistance Testing, Circuit Analysis, Transformer Testing End User: Manufacturing Plants, Power Generation Corporations, Construction Companies, Transportation Services Testing Standard: IEC Standards, IEEE Standards, ANSI Standards, IS Standards Application: Industrial Sector, Commercial Sector, Renewable Energy Systems, Utility Networks |
| Companies Covered | ITC India Private Limited, Ghaziabad Testing Laboratories Pvt. Ltd., INEL Power System Engineers Pvt. Ltd., Rulka Electricals Pvt. Ltd., Powertest Asia Pvt. Ltd., Technomark Engineers India Pvt. Ltd., Electrical Research and Development Association, Inser Hitech Engineers Pvt. Ltd., Voltech Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electrical Testing Services Market Shifts & Advancements
Digital diagnostic platforms are compressing testing cycle times while expanding the data capture scope for predictive maintenance. Service providers are bundling hardware sensors with analytics subscriptions to lock in recurring client relationships.
Partial discharge monitoring technology is migrating from offline laboratory conditions to online transformer monitoring. State electricity boards in Maharashtra and Gujarat are piloting continuous PD sensors on critical 220 kV units. This shift is compressing the market for scheduled offline diagnostic contracts while expanding real-time monitoring service revenues.
BIS has tightened domestic content certification requirements for power equipment under amended Quality Control Orders. Manufacturers must now demonstrate testing from BIS-recognized laboratories to qualify for government procurement tenders. Transmission equipment suppliers in western India are accelerating laboratory accreditation to maintain tender eligibility.
Power generation corporations are unbundling testing services from long-term maintenance contracts. NTPC and state gencos now issue discrete testing tenders with shorter tenures, enabling specialized regional laboratories to compete against integrated OEM service arms. This pattern is most visible in renewable energy project commissioning cycles across Rajasthan and Gujarat.
India Electrical Testing Services Market Segmentation
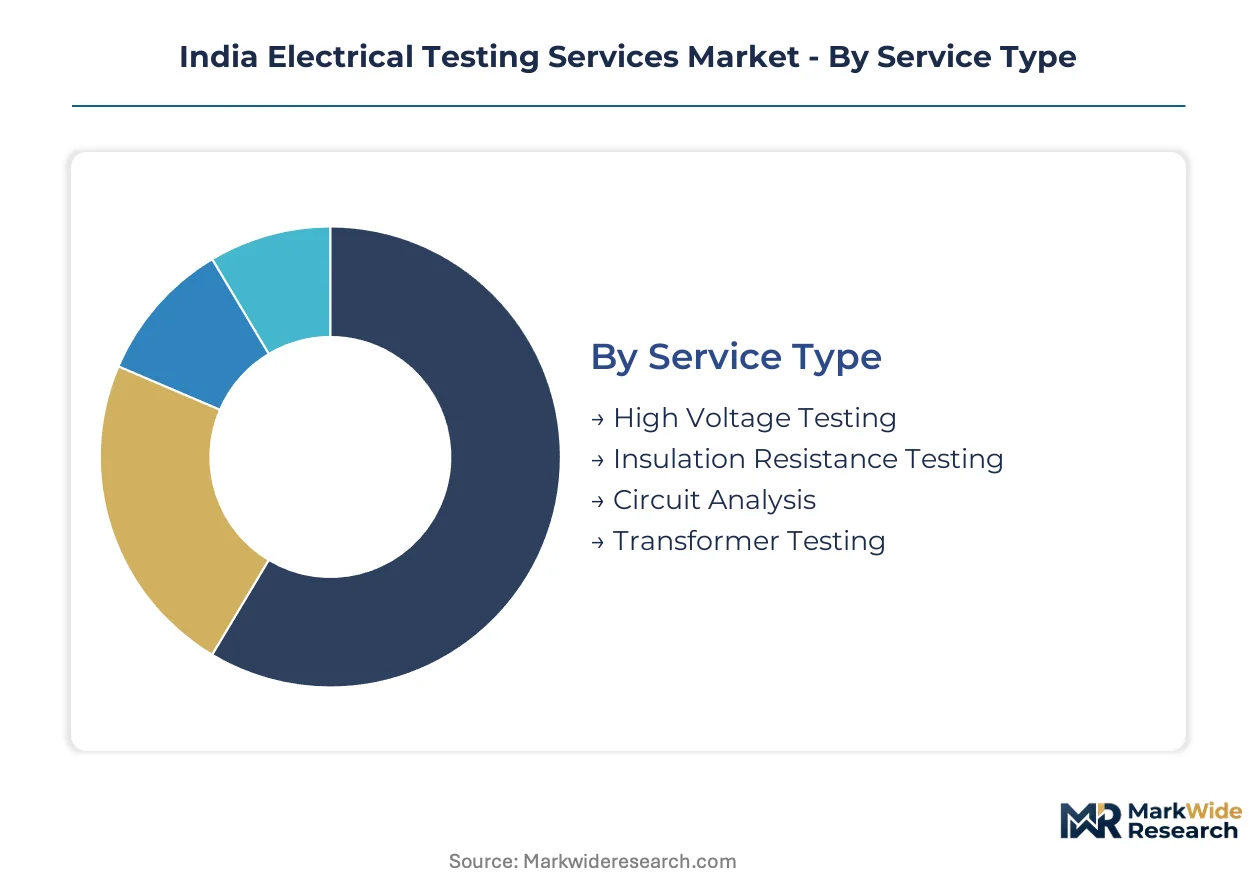
Segmentation in India's electrical testing services market reveals how regulatory mandates, equipment lifecycle demands, and standard compliance requirements fragment service procurement patterns across distinct buyer profiles and technical specifications.
Service Type:
Mature diagnostic protocols coexist with emerging predictive techniques as utilities balance scheduled maintenance against real-time monitoring investments.
- Transformer Testing:Dielectric withstand, turns ratio, and dissolved gas analysis procedures dominate utility spending due to aging distribution infrastructure and renewable integration stress. Maharashtra and Gujarat transmission licensees drive volume through mandatory CEA-mandated testing cadences for assets above 66 kV.
- Insulation Resistance Testing:Megger-based measurement of cable and winding integrity sustains the highest transaction frequency across preventive maintenance schedules. Manufacturing plants in industrial clusters execute quarterly resistance verification to satisfy BIS certification requirements and factory insurance conditions.
- High Voltage Testing:AC and DC withstand tests on switchgear and cables require specialized impulse generators and corona-free test bays.
- Circuit Analysis:Protective relay coordination and breaker timing tests verify distribution network fault clearance capability.
Transformer Testing handles the majority of throughput; Circuit Analysis is climbing the fastest as smart grid investments accelerate protection system verification demand.
End User:
Customer procurement sophistication spans from compliance-driven public sector tenders to risk-based private maintenance programs.
- Power Generation Corporations:NTPC and state gencos issue discrete testing tenders with shortened tenures, unbundling diagnostics from long-term OEM maintenance contracts. Rajasthan solar parks and Gujarat wind farms generate concentrated commissioning-phase testing demand for inverter and step-up transformer validation.
- Manufacturing Plants:Automotive and chemical facilities in Pune, Vadodara, and Mundra execute annual shutdown testing to maintain BIS equipment certification and operational continuity insurance.
- Construction Companies:Greenfield industrial and commercial projects require pre-energization testing of installed switchgear and cabling infrastructure.
- Transportation Services:Metro rail operators and airport authorities mandate specialized traction power system testing for third-rail and catenary infrastructure.
Power Generation Corporations concentrate the highest contract values; Manufacturing Plants deliver the steadiest recurring revenue base.
Testing Standard:
Dual-certification overhead shapes laboratory investment decisions as domestic content rules tighten procurement eligibility.
- IS Standards:Bureau of Indian Quality Control Orders mandate BIS-recognized laboratory testing for government procurement tender eligibility. Western India transmission equipment suppliers accelerate IS accreditation to maintain state electricity board contract access.
- IEC Standards:International Electrotechnical Commission protocols govern export-oriented manufacturing and multinational industrial facility compliance. ITC India and comparable laboratories compete on simultaneous IEC-IS dual-certification breadth to capture cross-border project demand.
- ANSI Standards:American National Standards Institute specifications apply to US-origin equipment installations and bilateral project financing conditions.
- IEEE Standards:Institute of Electrical and Electronics Engineers protocols dominate protective relay and substation automation testing specifications.
IS Standards command the deepest domestic regulatory tailwind; IEC Standards retain premium positioning for export-linked manufacturing clients.
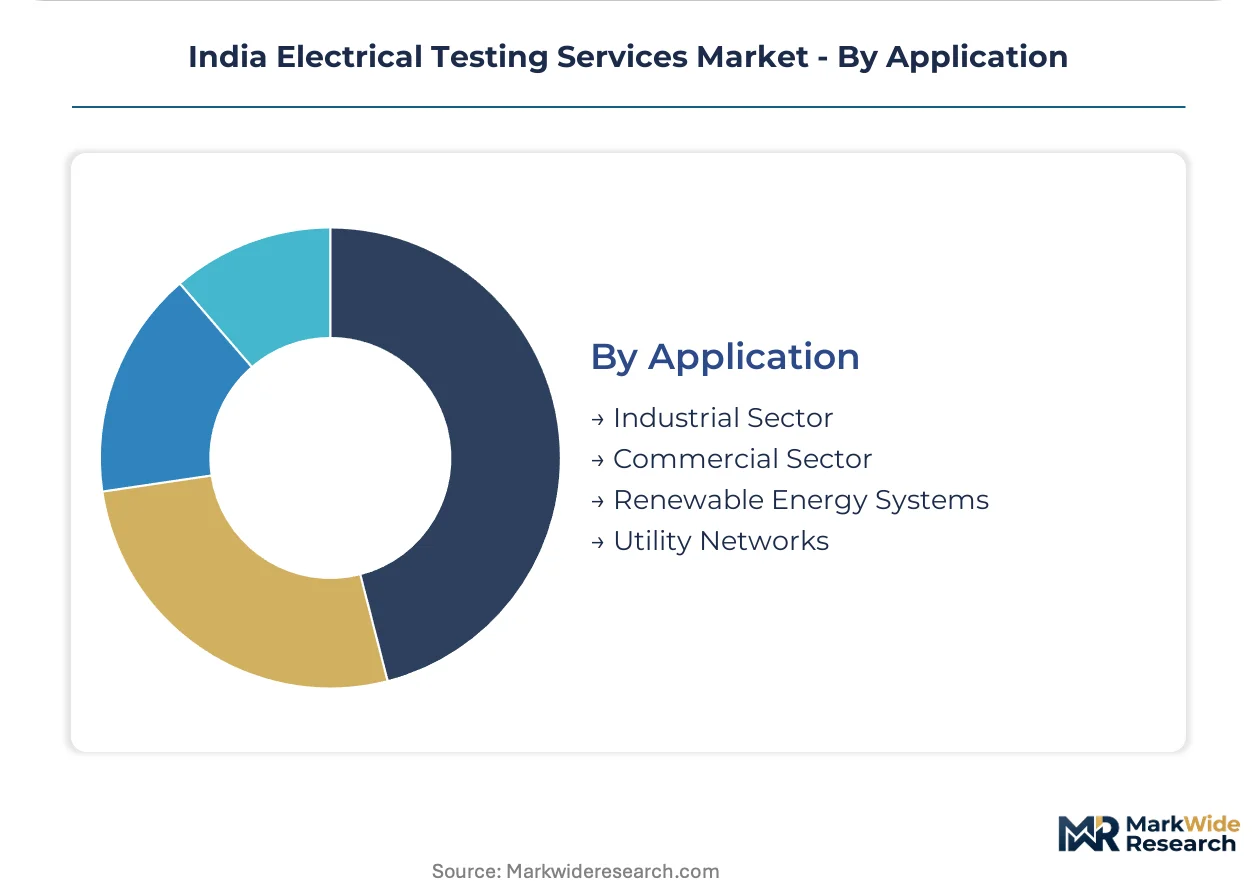
Application:
End-use demand intensity tracks electrification investment cycles and renewable capacity addition geography.
- Utility Networks:State electricity boards in Maharashtra, Gujarat, and Tamil Nadu execute the highest testing frequency due to CEA grid code enforcement and 220 kV critical asset monitoring programs. Partial discharge sensor pilots on transmission transformers are compressing scheduled offline contract volumes while expanding real-time service subscriptions.
- Renewable Energy Systems:Wind and solar park commissioning in Tamil Nadu-Karnataka corridors generates unmet inverter and collector system testing demand. Asset-light equipment leasing models enable regional laboratories to serve project-based demand without balance-sheet strain.
- Industrial Sector:Process manufacturing and heavy engineering facilities require thermal limit verification and arc flash studies for worker safety compliance.
- Commercial Sector:Data centers and hospital complexes mandate uninterrupted power supply validation and generator load bank testing.
Utility Networks absorb the largest absolute testing expenditure; Renewable Energy Systems are gaining share fastest on capacity addition momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA-mandated grid code compliance and PLI scheme disbursements for domestic equipment manufacturing are redirecting testing demand toward BIS-certified laboratories across India's industrial corridors.
Maharashtra
Maharashtra's transmission licensees execute the highest testing frequency for assets above 66 kV under CEA enforcement. State electricity boards in Mumbai and Pune pilot continuous partial discharge sensors on critical 220 kV transformers. The MIDC industrial clusters in Chakan and Talegaon generate concentrated transformer and switchgear testing workloads from automotive and chemical manufacturing plants.
Gujarat
Gujarat's renewable energy parks and port-led manufacturing zones multiply testing demand for inverter and step-up transformer validation. The state's electricity regulatory commission amplifies penalty exposure for non-compliant operators under Electricity Act enforcement. Mundra and Vadodara host transmission equipment suppliers accelerating BIS laboratory accreditation to maintain government tender eligibility.
Tamil Nadu
Tamil Nadu's wind and solar park commissioning generates unmet demand for collector system and inverter testing services. The state's renewable energy corporation issues discrete testing tenders with shortened tenures, unbundling diagnostics from long-term OEM contracts. Coimbatore and Chennai industrial belts sustain quarterly insulation resistance verification schedules for BIS-certified manufacturing facilities.
Karnataka
Karnataka's renewable corridors in Tumkur and Chitradurga drive project-based testing demand for solar park infrastructure. The state's energy department mandates pre-energization testing protocols for greenfield industrial substations. Bengaluru's data center concentration validates uninterrupted power supply systems and generator load bank performance under commercial sector compliance programs.
Delhi-NCR
Delhi-NCR's metro rail operators and airport authorities mandate specialized traction power system testing for third-rail infrastructure. The Central Electricity Authority's northern regional office enforces documented testing cadences for inter-state transmission assets. Faridabad and Gurgaon manufacturing hubs execute annual shutdown testing to maintain operational continuity insurance and factory certification requirements.
India Electrical Testing Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across certification breadth and equipment specialization vectors. The vendor base clusters around three tiers: integrated service houses with captive calibration infrastructure, regional specialists leveraging transformer testing depth, and asset-light entrants renting high-voltage equipment for project-based demand. Strategic moves concentrate on dual-certification portfolio expansion and geographic coverage extension through laboratory accreditation.
Within the western India utility contract tier, INEL Power System Engineers Pvt. Ltd. anchors specialist positioning through transformer testing concentration. Voltech Group exemplifies captive infrastructure control with calibration laboratory integration reducing third-party dependency. ITC India Private Limited occupies the dual-certification vector spanning IEC and IS standard breadth for manufacturing plant clients. These three entities represent distinct competitive archetypes: equipment specialization, vertical infrastructure control, and certification portfolio breadth.
| Leading Market Players |
|---|
| ITC India Private Limited |
| Ghaziabad Testing Laboratories Pvt. Ltd. |
| INEL Power System Engineers Pvt. Ltd. |
| Rulka Electricals Pvt. Ltd. |
| Powertest Asia Pvt. Ltd. |
| Technomark Engineers India Pvt. Ltd. |
| Electrical Research and Development Association |
| Inser Hitech Engineers Pvt. Ltd. |
| Voltech Group |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese impulse generator manufacturers compresses margin flexibility for Indian laboratories while simultaneously forcing three-tier pricing stratification across BIS-accredited, IEC-only, and uncertified service tiers.
Pricing Analysis
Certification level creates the primary spread between service tiers, with dual IEC-IS accredited laboratories commanding 40-60% premiums over single-standard competitors. Project-based pricing dominates transformer testing contracts, while preventive maintenance schedules favor annual retainer structures. Cost compression in the standard tier intensifies as asset-light entrants rent high-voltage equipment to undercut captive infrastructure players. Manufacturing plants in MIDC clusters exhibit highest price sensitivity due to insurance-mandated testing floors, whereas NTPC and state gencos prioritize certification breadth over unit cost.
Supply Chain Analysis
Export control restrictions on high-voltage impulse generators and partial discharge detection systems limit equipment flows from Germany, Japan, and Switzerland into Indian laboratories. Domestic sourcing of test bay infrastructure and calibration standards draws from local fabrication units in Pune and Bengaluru, while critical dielectric test sets remain tethered to European OEMs. Single-source vulnerability concentrates in 500 kV+ test equipment where two German suppliers control global output. Distribution runs through direct OEM relationships for capital equipment and regional distributor networks for consumables and spare components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat where BIS accreditation timelines and CEA-mandated testing protocols create entrenched switching costs for incumbent laboratories.
For Market Incumbents: Harden defensible positioning by deepening captive calibration infrastructure to eliminate third-party dependency, while accelerating dual-certification portfolio expansion before PLI scheme disbursements tighten domestic content requirements. Emerging asset-light entrants renting high-voltage test kits threaten margin compression in project-based renewable commissioning segments. Vertical control over impulse generator maintenance capacity represents the critical lever for sustaining premium positioning. For New Entrants and Emerging Players: Tamil Nadu-Karnataka renewable corridors represent the most penetrable entry point, where unmet inverter and transformer testing demand outpaces accredited laboratory capacity. Tier-2 cities in Rajasthan and Madhya Pradesh offer secondary white-space for preventive maintenance contracts as industrial clusters expand beyond western India saturation. Equipment leasing partnerships with European OEMs provide the essential go-to-market angle for overcoming capital intensity barriers without balance-sheet strain. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialists with captive infrastructure and dual-certification breadth over pure-play regional operators. Long-term viability hinges on laboratories positioned at the intersection of smart grid sensor integration and traditional high-voltage testing capabilities. Acquisition targets should demonstrate established BIS accreditation pipelines and documented utility contract relationships. The signal to watch is CEA enforcement intensity on partial discharge monitoring mandates, which would accelerate real-time service subscription models and compress scheduled offline contract volumes.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Laboratory Accreditation Acceleration | CEA grid code enforcement and PLI scheme disbursements redirect procurement toward certified local facilities. |
| Smart Grid Sensor Integration | IoT convergence with high-voltage testing creates predictive maintenance bundles that lock recurring client relationships. |
| Asset-Light Equipment Leasing | Rental models for impulse generators enable regional players to serve project demand without capital intensity. |
| Dual-Certification Portfolio Expansion | Simultaneous IEC-IS breadth captures cross-border manufacturing clients and government tender eligibility. |
| Captive Calibration Infrastructure | In-house metrology labs reduce third-party dependency and compress turnaround times for utility contracts. |
Research Methodology
The analysis maps transformer testing, insulation resistance protocols, high-voltage withstand procedures, and circuit analysis services, each validated through utility planning officers, laboratory technical directors, state electricity board procurement managers, and renewable project EPC contractors. Primary fieldwork combined structured interviews with secondary triangulation across CEA grid code filings, BIS accreditation registries, state regulatory commission orders, and PLI scheme disbursement records. Bottom-up service volume estimates and top-down market sizing were reconciled through cross-validation with equipment supplier shipment data.
Forecast assumptions held CEA enforcement intensity and PLI scheme continuation fixed while varying renewable capacity addition rates and smart grid investment trajectories across the projection horizon. Segmentation modeling incorporated service type, end-user sophistication, testing standard requirements, and application intensity dimensions. CAGRs were derived from regression analysis against historical testing frequency patterns and regulatory mandate expansion timelines, with specific inputs from transformer aging curves and renewable integration stress factors.
Stress conditions across BIS accreditation timeline extensions, high-voltage equipment import restriction tightening, and state electricity board privatization pacing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and infrastructure investment commitment. Material shifts in CEA grid code enforcement scope or PLI scheme eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Pump Testers Market
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Four-Quadrant Battery Simulator Market