
 Cable Distribution Cabinets Market | 2026-2036
Cable Distribution Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Distribution Cabinets Market Analysis
The cable distribution cabinet sector is restructuring around a sharp split between premium sealed enclosures for harsh environments and commodity indoor units where price competition intensifies. Siemens leverages its automation heritage to dominate intelligent cabinet systems with integrated monitoring. ABB anchors European utility contracts through its medium-voltage specialization. Lucy Electric competes aggressively in emerging markets with compact, modular designs that reduce installation labor.
Cable distribution cabinets are enclosed housing units that protect and organize electrical or fiber-optic terminations, typically rated for IP54-IP68 ingress protection and constructed from galvanized steel or thermoset composites to withstand temperature cycling from minus 40 to plus 70 degrees Celsius. Their primary purpose is to enable safe subscriber drops, splice access, and passive splitting in last-mile telecom and low-voltage power networks. Fiber optic cabinets lead product type demand as PON architecture displaces copper, while wall-mounted installation claims the fastest growth trajectory driven by dense urban 5G small-cell backhaul. Metal material segments retain the largest revenue pool due to durability requirements in utility and outdoor telecom applications.
EU CE marking and the F-Gas Regulation shape enclosure sealing standards and thermal management specifications for cabinets deployed across member states. The US FCC broadband equity programs and NHTSA roadside infrastructure guidelines create dual compliance pathways for manufacturers serving telecom and intelligent transportation markets. Stakeholders must monitor evolving national building codes and fiber mandate timelines to align certification investments with procurement cycles.
Market Dynamics
Fiber-to-the-home rollout mandates under the EU Green Deal are compressing deployment timelines for sealed outdoor cabinets while simultaneously fragmenting procurement across national fiber programs with divergent technical specifications.
Growth Catalysts
- EU Green Deal digital infrastructure targets:Germany's telecom operators are accelerating fiber-to-the-home deployments, creating sustained demand for IP68-rated sealed enclosures capable of withstanding temperature cycling from minus 40 to plus 70 degrees Celsius.
- Smart grid investments:China's eastern provinces are channeling capital into utility network upgrades, driving procurement of medium-voltage cable distribution cabinets with integrated monitoring capabilities for grid automation.
- PON architecture displacement:Passive optical network technology is systematically replacing copper last-mile infrastructure, elevating fiber optic cabinets above legacy copper termination units in product type demand rankings.
Market Restraints
- Galvanized steel price volatility:Metal material segments face margin compression from fluctuating raw material costs, particularly affecting outdoor telecom and utility applications where durability requirements prevent substitution with thermoset composites.
- Supply concentration in enclosure sealing:IP68 gasket and seal manufacturing clusters in select East Asian manufacturing hubs create vulnerability to regional disruption for premium harsh-environment cabinet lines.
- F-Gas Regulation thermal management constraints:EU member states' restrictions on fluorinated greenhouse gases are limiting conventional cooling options for high-density fiber cabinets, forcing redesign cycles that extend certification timelines.
Strategic Opportunities
- 5G small-cell backhaul density:Wall-mounted installation formats are capturing fastest growth trajectory as urban telecom operators deploy dense networks requiring compact, street-level fiber access points.
- US broadband equity programs:FCC infrastructure funding is unlocking rural and underserved market segments previously uneconomical for cabinet manufacturers, with procurement pathways distinct from commercial telecom contracts.
- Intelligent transportation integration:NHTSA roadside infrastructure guidelines are creating dual-use certification pathways where cabinets serving telecom backhaul can simultaneously address connected vehicle and traffic management deployments.
Industry Challenges
- Multi-jurisdiction certification complexity:Manufacturers must simultaneously maintain EU CE marking compliance, US FCC equipment authorization, and evolving national building codes across target markets, fragmenting engineering resources.
- Legacy copper infrastructure interoperability:Hybrid network environments require cabinets supporting both fiber and copper terminations, complicating product portfolio management and inventory forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Distribution Cabinets Market |
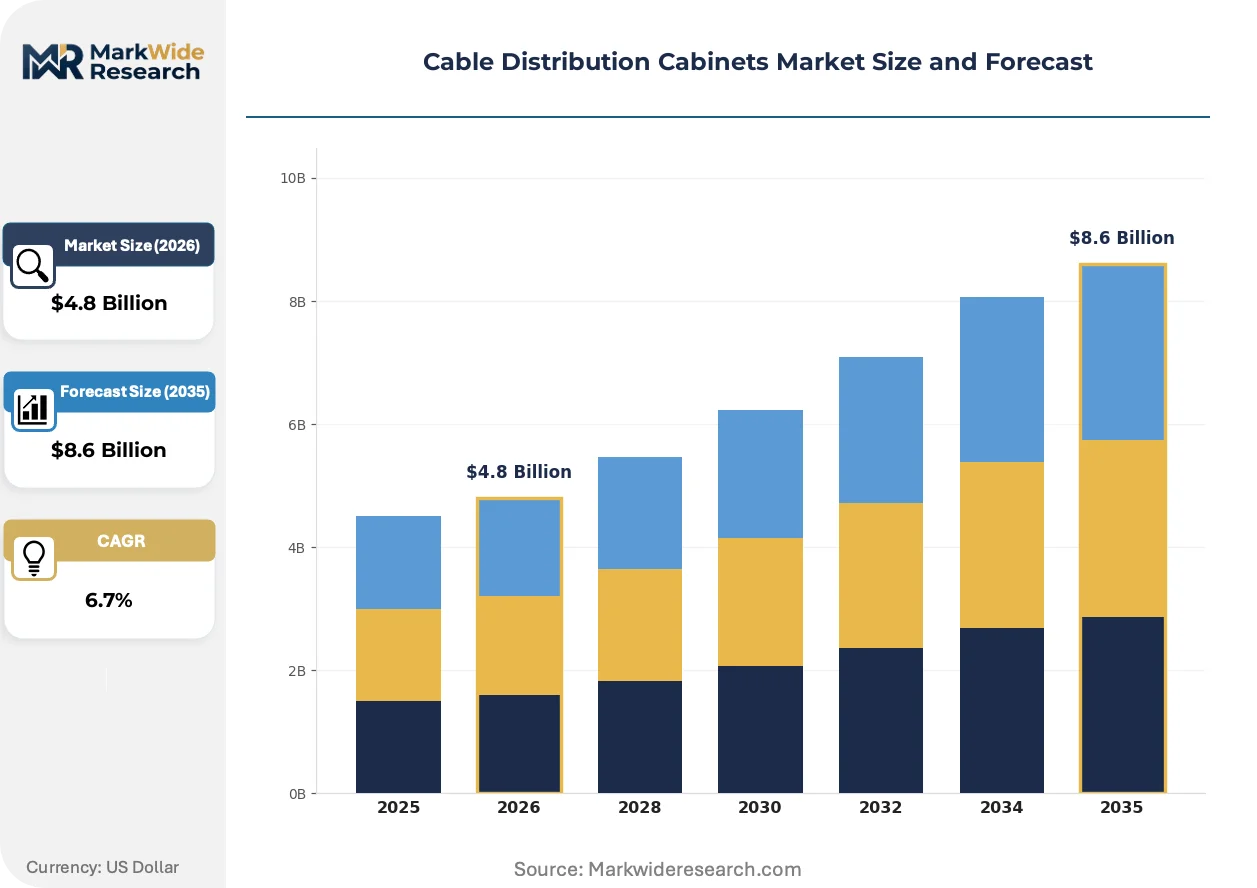
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Cabinets, Copper Cabinets, Outdoor Cabinets, Indoor Cabinets End User: Telecom Operators, Network Providers, Data Centers, Utility Companies Installation: Wall-Mounted, Floor-Standing, Freestanding, Pole-Mounted Material: Metal, Plastic, Composite, Aluminum |
| Companies Covered | Siemens, ABB, Lucy Electric, ZPAS Group, Hongfa, Krone, Sleeve Seal, C&C Power, Elba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Distribution Cabinets Market Emerging Trajectories
Thermoset composite materials are gaining ground in cabinet construction as weight reduction and corrosion resistance priorities reshape material selection criteria across outdoor telecom deployments.
Intelligent cabinet systems with integrated environmental monitoring and remote fault detection are rewriting competitive requirements for premium segments. European utilities are mandating these capabilities in medium-voltage tenders. The technology is compressing margins for basic sealed enclosures without sensor integration.
The EU F-Gas Regulation and associated CE marking updates are tightening enclosure thermal performance standards. Manufacturers serving member states must redesign sealed cabinet ventilation and passive cooling architectures. Fiber-dense urban deployments in German and French cities face the steepest compliance adaptation costs.
Telecom procurement teams are consolidating supplier relationships around full-lifecycle service agreements rather than discrete equipment purchases. Equipment-only vendors are losing access to major operator frameworks. This pattern is most pronounced in China's eastern provinces where state-owned carriers dominate infrastructure investment.
Cable Distribution Cabinets Market Segmentation
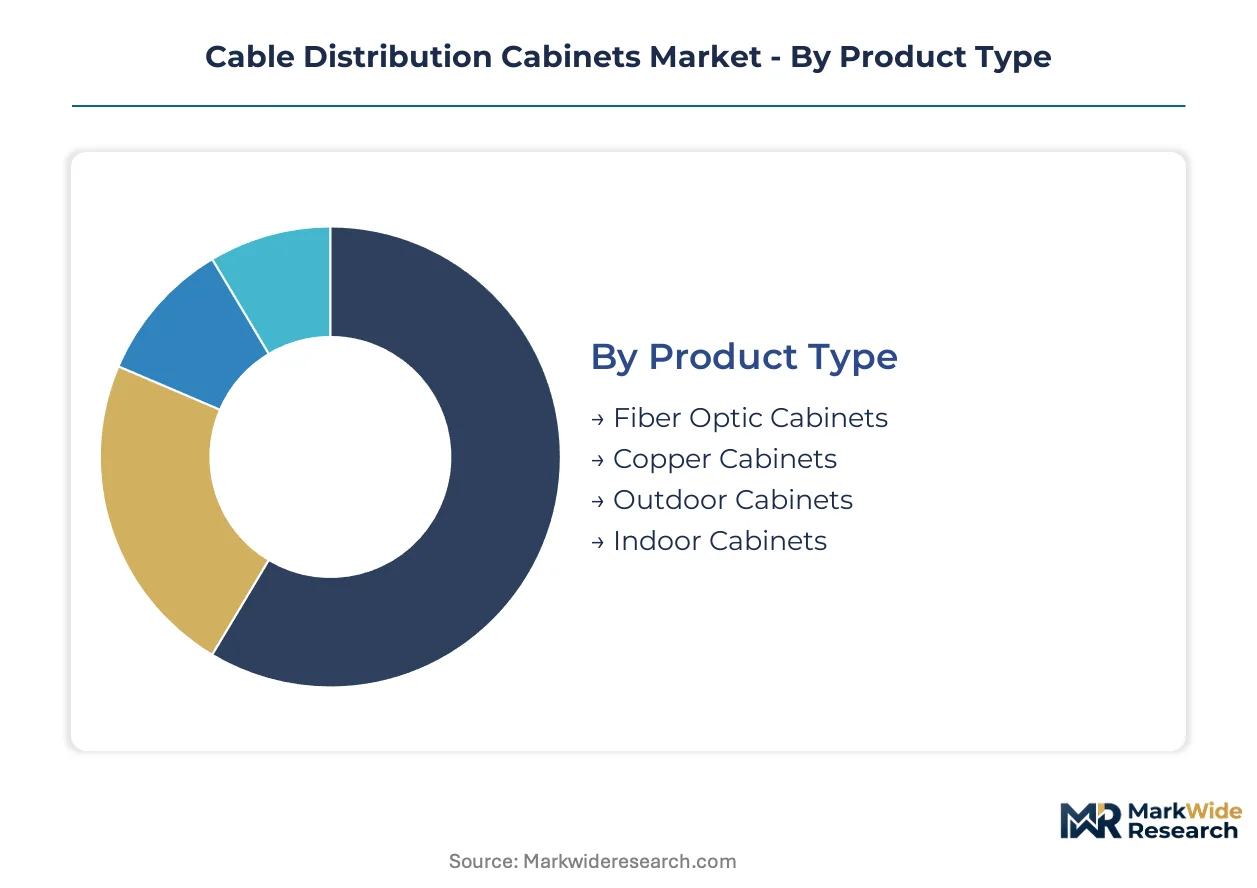
Cable distribution cabinet procurement splits sharply between standalone outdoor enclosures for harsh environments and embedded indoor systems integrated into building infrastructure. Understanding these integration patterns reveals where manufacturers must engineer for modularity versus where sealed durability commands premium positioning.
Product Type:
Integration depth varies dramatically across this category, with some segments functioning as independent network nodes while others embed within larger infrastructure systems.
- Fiber Optic Cabinets:These units house passive optical splitters and splice trays in IP54-IP68 rated enclosures, engineered for temperature cycling from minus 40 to plus 70 degrees Celsius. Demand concentrates in Germany's fiber-to-the-home deployments under EU Green Deal targets, where sealed outdoor variants withstand street-level exposure without building integration.
- Outdoor Cabinets:Standalone sealed enclosures designed for pole or ground mounting with integrated environmental protection. China's eastern provinces drive procurement for utility network upgrades, where smart grid investments require medium-voltage cabinets capable of autonomous operation in uncontrolled climates.
- Copper Cabinets:Legacy termination units for DSL and copper last-mile networks, typically deployed as embedded building infrastructure rather than standalone street furniture.
- Indoor Cabinets:Rack-mounted or wall-integrated units prioritizing space efficiency over environmental sealing, common in data center and building basement installations.
Fiber optic cabinets lead volumes today; outdoor cabinets are gaining share fastest.
End User:
Cost tier differentiation separates capital-intensive utility procurement from price-sensitive telecom volume contracts.
- Telecom Operators:State-owned carriers in China's eastern provinces dominate infrastructure investment, consolidating supplier relationships around full-lifecycle service agreements rather than discrete equipment purchases.
- Utility Companies:European utilities mandate intelligent cabinet systems with integrated environmental monitoring and remote fault detection in medium-voltage tenders, compressing margins for basic sealed enclosures without sensor integration.
- Network Providers:Competitive local exchange carriers and wholesale fiber operators purchasing standardized cabinets for metropolitan ring networks.
- Data Centers:Hyperscale and colocation facilities procuring indoor cabinets for interconnection and cross-connect infrastructure.
Telecom operators lead volumes today; utility companies are expanding procurement most quickly.
Installation:
Application context determines whether cabinets serve dense urban backhaul or rural distribution networks.
- Wall-Mounted:Compact enclosures designed for building exterior mounting, capturing the steepest expansion trajectory as urban 5G small-cell backhaul demands street-level fiber access points with minimal footprint.
- Pole-Mounted:Cylindrical or rectangular cabinets strapped to utility poles for aerial cable distribution, prevalent in US rural broadband equity program deployments where underground construction proves uneconomical.
- Floor-Standing:Large-capacity cabinets for central office and headend applications requiring technician workspace and equipment rack integration.
- Freestanding:Pad-mounted enclosures for greenfield residential developments and campus environments.
Wall-mounted installations are climbing the fastest; pole-mounted formats retain the largest installed base.
Material:
Supply concentration in metal processing creates cost structure divergence from emerging composite alternatives.
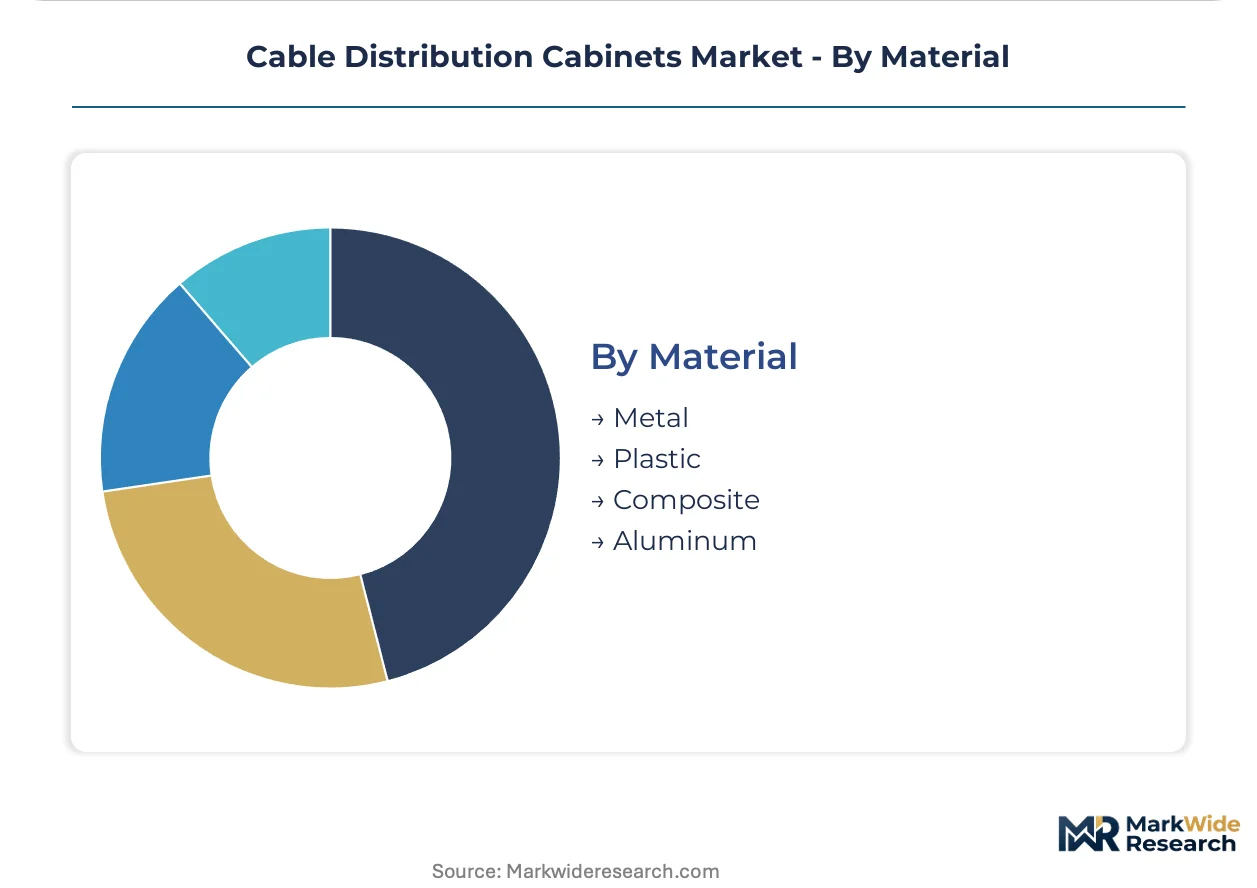
- Metal:Galvanized steel enclosures retain the largest revenue pool due to durability requirements in utility and outdoor telecom applications, though margin compression from raw material price volatility limits substitution flexibility.
- Composite:Thermoset polymer formulations gaining ground through weight reduction and corrosion resistance priorities, particularly valued in coastal and chemically aggressive environments where steel degradation accelerates.
- Aluminum:Lightweight metal alternatives for pole-mounted applications where structural load limits constrain steel deployment.
- Plastic:Injection-molded enclosures for indoor and protected outdoor applications with minimal mechanical stress requirements.
Metal leads volumes today; composite materials are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's telecom operators are accelerating fiber-to-the-home deployments faster than China's eastern provinces, where smart grid investments now dominate utility procurement patterns.
United States
Rural broadband equity programs under FCC infrastructure funding are unlocking pole-mounted cabinet deployments across underserved markets. NHTSA roadside infrastructure guidelines create dual-use certification pathways for connected vehicle and traffic management cabinets. Texas and California clusters concentrate manufacturing capacity for sealed outdoor enclosures.
Germany
Telecom operators are compressing deployment timelines for IP68-rated sealed cabinets under EU Green Deal digital infrastructure targets. CE marking and F-Gas Regulation compliance requirements tighten thermal management specifications for fiber-dense urban deployments. Bavaria and North Rhine-Westphalia industrial zones anchor enclosure manufacturing and systems integration.
China
State-owned carriers in eastern provinces are consolidating supplier relationships around full-lifecycle service agreements rather than discrete equipment purchases. MIIT standards and dual carbon goals shape smart grid investment priorities for medium-voltage utility networks. Yangtze River Delta manufacturing hubs concentrate IP68 gasket and seal production.
India
Utility network modernization under CEA grid automation directives is driving procurement of intelligent cabinet systems with integrated monitoring. TRAI fiber mandates are compressing last-mile deployment timelines for sealed outdoor enclosures. Maharashtra and Gujarat industrial corridors concentrate metal fabrication capacity for galvanized steel cabinets.
United Kingdom
Network providers are procuring wall-mounted cabinets for dense urban 5G small-cell backhaul deployments. Building code updates and national fiber mandate timelines are reshaping certification investment cycles. Midlands manufacturing clusters specialize in thermoset composite enclosures for corrosion-resistant applications.
Cable Distribution Cabinets Market Vendor Landscape
Top-tier vendors anchor premium intelligent systems, while mid-tier fabricators compete on modularity and emerging-market price positioning. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with automation heritage, specialized electrical equipment manufacturers with medium-voltage expertise, and compact modular specialists targeting labor-cost-sensitive installations. Dominant competitive moves include backward integration into enclosure sealing components and geographic expansion through national fiber program certifications.
Among diversified industrial conglomerates, Siemens AG and ABB Ltd exemplify the intelligent systems archetype through their automation and power technology foundations. Lucy Electric occupies a position within the specialized electrical equipment tier, representing compact modular design capabilities. These three anchors demonstrate how competitive positioning splits between premium integrated monitoring and emerging-market installation efficiency.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Lucy Electric |
| ZPAS Group |
| Hongfa |
| Krone |
| Sleeve Seal |
| C&C Power |
| Elba |
| Others |
Supply Flow & Price Mechanics
State-owned carriers in China's eastern provinces consolidate procurement around full-lifecycle service agreements, forcing equipment-only vendors toward bundled pricing models that embed installation and maintenance. This buyer concentration compresses margins for standalone cabinet sales while elevating premium capture for integrated monitoring systems.
Pricing Analysis
Bundled service agreements now dominate telecom procurement while unbundled equipment transactions persist in utility segments. Three-tier pricing structure across premium intelligent cabinets, standard sealed enclosures, and economy indoor units separates Siemens and ABB's automation-integrated offerings from commodity fabricators. Cost compression in the standard tier intensifies because galvanized steel price volatility prevents material substitution in outdoor applications. Telecom operators in Germany exhibit the least price sensitivity due to EU Green Deal deployment mandates, whereas competitive local exchange carriers in the US broadband equity programs drive the steepest discount pressure.
Supply Chain Analysis
Single-source vulnerability sits with IP68 gasket and seal manufacturing clusters concentrated in China's Yangtze River Delta. Galvanized steel sheet production draws from mills in India and Germany, while thermoset composite resins hinge on petrochemical feedstocks from South Korea and Japan. Tariff exposure on Chinese-manufactured sealing components threatens premium harsh-environment cabinet lines. Distribution runs through national fiber program certification pathways rather than open channel markets, with Siemens and ABB maintaining direct relationships to state-owned carriers and European utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on thermoset composite substitution reducing raw material cost exposure and intelligent cabinet premiums capturing utility automation budgets. The shift from commodity enclosures to sensor-integrated systems rewards backward integration into environmental monitoring components.
For Market Incumbents: Anchor premium positioning through captive production of IP68 sealing components and integrated monitoring modules. Siemens and ABB dominate intelligent systems by controlling sensor supply chains; mid-tier competitors must defend against this vertical integration by securing exclusive gasket supplier relationships in China's Yangtze River Delta. Certification investments in US FCC equipment authorization and EU CE marking updates represent the critical lever for maintaining national fiber program access.
For New Entrants and Emerging Players: US FCC broadband equity programs in rural and underserved markets open a window for pole-mounted cabinet specialists without incumbent service infrastructure. India's TRAI fiber mandates and CEA grid automation directives create the most penetrable regulatory environment for compact modular designs. Target municipal smart city procurement with wall-mounted formats for 5G small-cell backhaul, bypassing carrier consolidation that locks out equipment-only vendors.
For Investors and Strategic Acquirers: Industrial conglomerates with automation heritage are the most active acquirer in this space, seeking intelligent cabinet capabilities to complement power technology portfolios. Target mid-tier fabricators with established CE marking and proprietary thermoset composite formulations. The signal to watch is EU F-Gas Regulation enforcement tightening thermal management specifications, which will force redesign cycles favoring acquirers with in-house engineering capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Components | Captive IP68 gasket production insulates margin from Yangtze River Delta supply disruption. |
| Intelligent Cabinet System Launch | Integrated environmental monitoring meets European utility tender requirements for grid automation. |
| Thermoset Composite Manufacturing Transition | Weight reduction and corrosion resistance unlock coastal telecom and chemically aggressive utility deployments. |
| National Fiber Program Certification | US FCC equipment authorization and EU CE marking unlock procurement pathways closed to uncertified competitors. |
| Full-Lifecycle Service Agreement | Recurring revenue streams align with China's state-owned carrier consolidation around integrated suppliers. |
Methodological Framework
Multiple input streams — executive interviews with telecom infrastructure procurement directors, utility grid automation engineers, and enclosure manufacturing plant managers; secondary validation through SEC filings of Siemens and ABB, EU CE marking databases, and MIIT smart grid investment disclosures; plus customs records for galvanized steel and thermoset resin trade flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment data from enclosure manufacturers was cross-referenced against panel input from national fiber program administrators. The analytical framework modeled demand across product type, installation format, material composition, and end-user vertical throughout the forecast period. CAGRs were derived from installation volume trajectories in Germany's fiber-to-the-home deployments and China's eastern province smart grid investments, with temperature cycling specifications and IP rating requirements serving as industry-specific demand modifiers.
Revisions become necessary when EU F-Gas Regulation enforcement accelerates thermal management redesign cycles, when galvanized steel price volatility triggers material substitution toward thermoset composites, or when national fiber program timelines shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Europe Electrical Bushing Market