
 North America MV Switchgear Market | 2026-2036
North America MV Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
North America MV Switchgear Market Analysis
Texas is reshaping competitive dynamics in North American medium-voltage switchgear through expanded manufacturing footprints serving ERCOT grid expansion. Schneider Electric SE leverages its Austin operations to anchor regional service capabilities for utility-scale deployments. Powell Industries dominates specialized outdoor enclosures for petrochemical and offshore applications along the Gulf Coast.
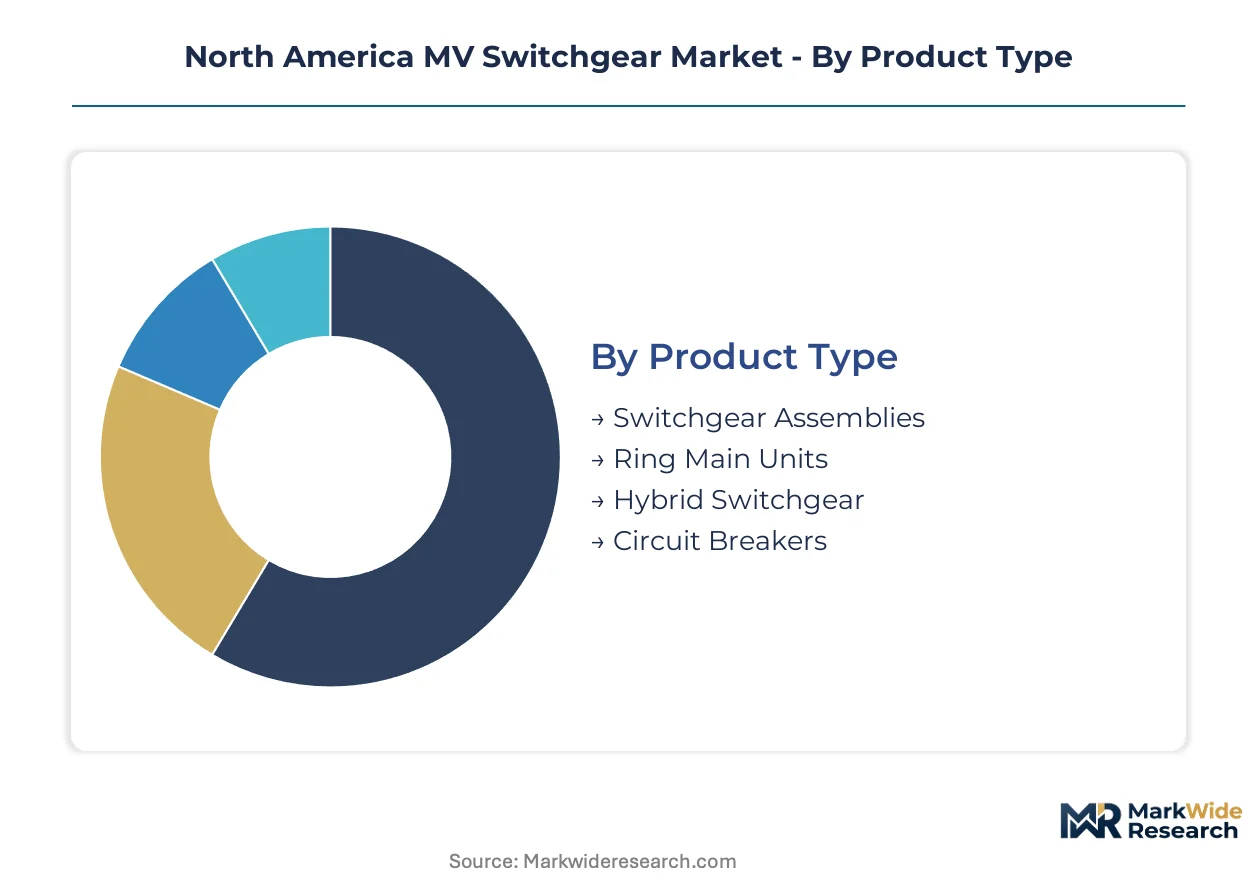
Medium-voltage switchgear encompasses electrical protection, control, and isolation equipment rated between 1 kV and 52 kV, employing vacuum interrupters or SF6 insulation to interrupt fault currents and safeguard distribution networks. The equipment serves critical functions in substations, industrial facilities, and renewable generation interconnection points where arc-flash containment and operational reliability prove essential. Circuit breakers command the largest product share as utilities prioritize fault-clearing speed for grid stability, while ring main units represent the fastest-growing segment driven by underground distribution densification in urban Canadian and US markets. Renewable energy end-users generate disproportionate margin pools due to customized interconnection specifications and stringent power-quality requirements.
NHTSA and EPA standards indirectly shape switchgear procurement through electric-vehicle charging infrastructure mandates that cascade into utility distribution upgrades, while IEEE C37 and CSA C22.2 product standards govern dielectric withstand, short-circuit ratings, and seismic qualification across US and Canadian jurisdictions. FERC Order 2023 interconnection queue reforms will accelerate substation buildouts requiring compliant MV equipment. Stakeholders must monitor state-level clean-energy mandates and utility integrated resource plans to anticipate procurement cycles and specification shifts.
Market Dynamics
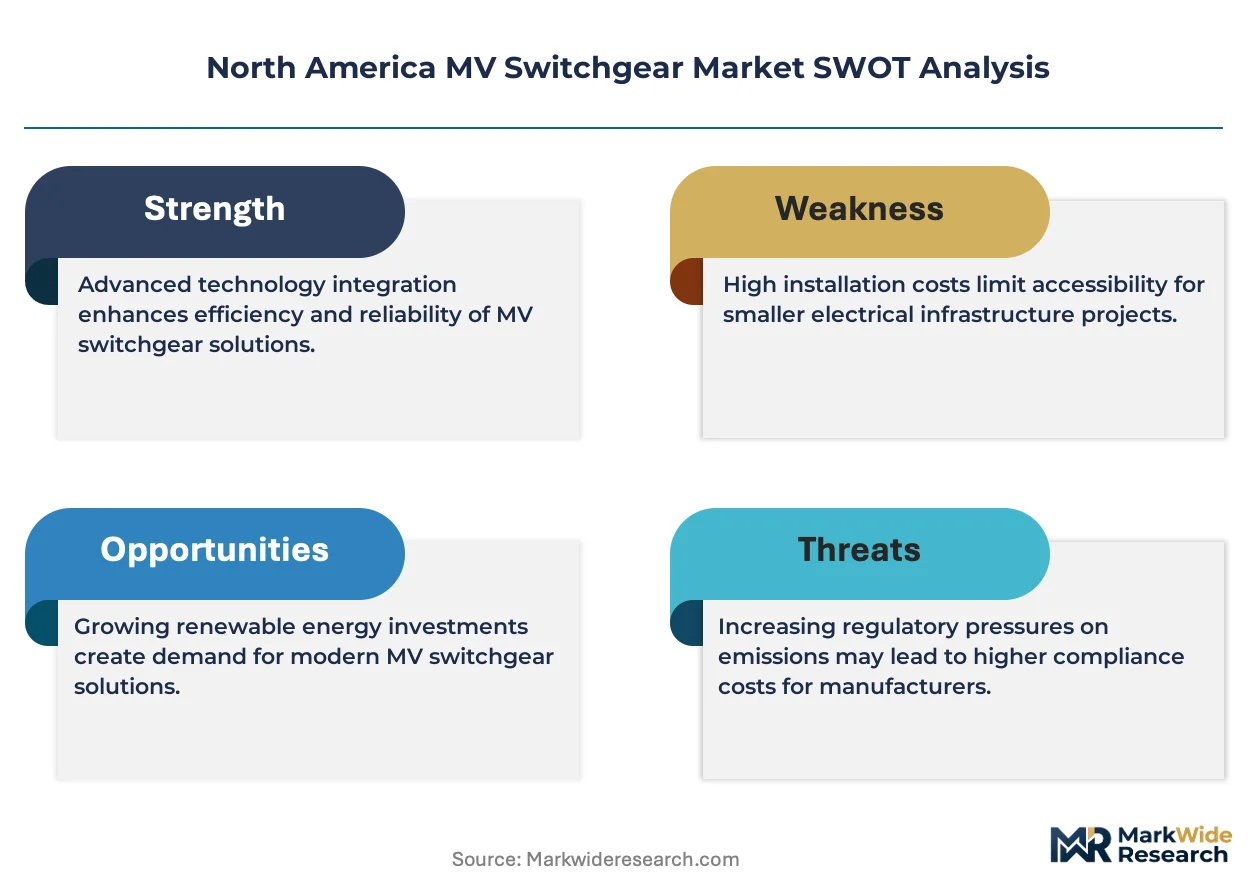
EPA sulfur hexafluoride emissions restrictions are forcing wholesale insulation technology transitions across North American utility procurement. The regulatory pressure eliminates incumbent SF6-based equipment from new substation deployments and triggers accelerated replacement cycles in aging infrastructure.
Growth Catalysts
- Grid Modernization Mandates:FERC Order 2023 interconnection queue reforms compel utilities to expand substation capacity. ERCOT and CAISO backlogs drive equipment procurement for renewable integration.
- Texas Manufacturing Expansion:Gulf Coast industrial clusters anchor domestic production capacity for utility-scale deployments. Regional fabrication reduces lead times for petrochemical and offshore applications.
- SF6-Free Technology Maturation:Vacuum interrupter and dry-air insulation alternatives achieve dielectric performance parity. Utilities now specify alternative technologies for new construction without operational compromise.
Market Restraints
- Copper and Steel Input Volatility:Raw material price swings compress fabrication margins for enclosure and busbar components. Foundry capacity constraints in Mexico and Canada amplify procurement uncertainty.
- Specialized Engineering Talent Scarcity:Arc-flash containment design and seismic qualification expertise concentrates among aging utility engineering cohorts. Knowledge transfer gaps threaten project execution timelines.
- Extended Certification Cycles:IEEE C37.20.2 and CSA C22.2.31 testing protocols demand 18-24 month validation periods for new product introductions. Regulatory friction delays technology commercialization.
Strategic Opportunities
- Canadian Underground Distribution Densification:Toronto and Vancouver municipal electrification programs expand ring main unit deployment. Urban infrastructure renewal outpaces overhead system replacement economics.
- EV Charging Infrastructure Cascade:NHTSA and EPA vehicle electrification mandates force distribution utility upgrades. Secondary substation equipment demand multiplies across California and Northeast corridor states.
- Digital Twin Integration:Sensor-embedded switchgear converges with predictive maintenance platforms. Asset performance data monetization creates recurring revenue streams for OEM service divisions.
Industry Challenges
- Legacy Substation Integration Complexity:New SF6-free equipment must interface with 30-40 year-old protection relay schemes. Retrofit engineering consumes disproportionate project engineering hours.
- Seismic Qualification Bottlenecks:IEEE 693 high-level certification requires specialized shake-table testing facilities. Limited North American laboratory capacity queues validation programs.
- Supply Chain Reconfiguration Friction:Domestic content requirements in utility procurement specifications disrupt established Asian component sourcing. Alternative supplier qualification extends material lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America MV Switchgear Market |
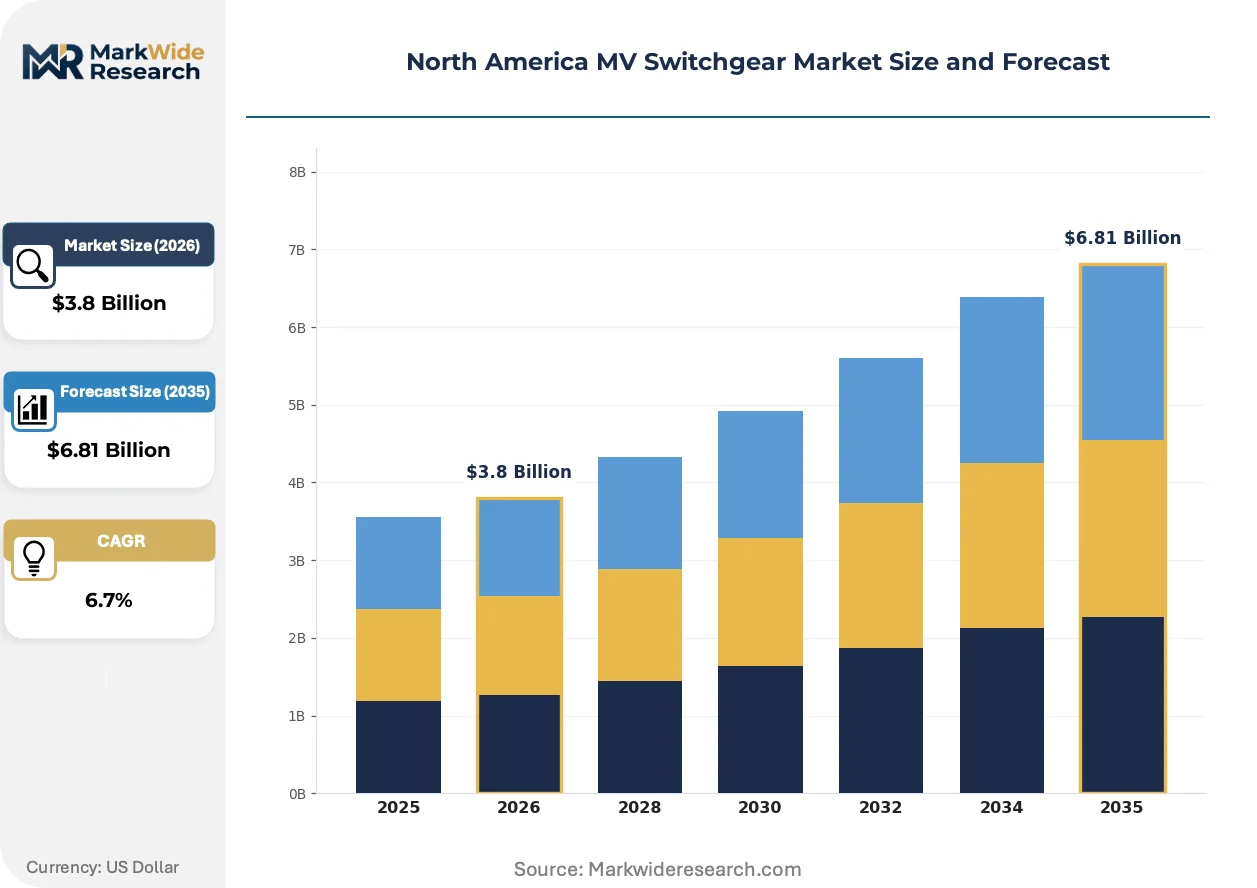
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switchgear Assemblies, Ring Main Units, Hybrid Switchgear, Circuit Breakers End User: Utilities, Manufacturing, Commercial Buildings, Renewable Energy Installation Type: Indoor, Outdoor, Compact, Modular Service Type: Maintenance, Upgradation, Installation, Consultation |
| Companies Covered | Schneider Electric SE, Powell Industries, ABB Ltd, Toshiba Corporation, Mitsubishi Electric Corporation, Eaton Corporation plc, General Electric, LS Electric Co., Ltd., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America MV Switchgear Market Emerging Trajectories
Insulation technology substitution dominates equipment specification evolution across North American utility engineering departments. Three concurrent developments reshape competitive positioning and procurement criteria.
Dry-air insulated switchgear is rendering obsolete SF6-dependent designs in new utility substation construction. Pacific Gas and Electric and Southern California Edison now mandate alternative insulation for all greenfield 15-38 kV installations. The technology transition compresses margins for incumbents with stranded SF6 manufacturing assets while elevating vacuum interrupter specialists.
EPA's tightened sulfur hexafluoride emissions reporting rules impose equipment-level tracking and leak detection mandates. Utilities must install monitoring systems and report annual leakage rates above one percent thresholds. The regulatory burden accelerates SF6 phase-out timelines in California, New York, and Massachusetts where state environmental agencies enforce supplemental restrictions.
Integrated resource planning procurement cycles now compress traditional equipment specification windows. Duke Energy and Xcel Energy consolidate medium-voltage switchgear purchasing into multi-year framework agreements with performance guarantees. The buying-pattern shift disadvantages project-based distributors and elevates OEMs with captive installation and maintenance capabilities across Texas, Florida, and Illinois territories.
North America MV Switchgear Market Segmentation
Segmentation in the North America MV Switchgear Market reveals divergent service intensity profiles across product categories. Equipment complexity and regulatory compliance burdens create aftermarket revenue opportunities that vary substantially by segment.
Product Type:
After-sales service intensity escalates with arc-flash containment requirements and interrupter technology sophistication across product categories.
- Circuit Breakers:Vacuum interrupter assemblies rated 15-38 kV require periodic contact wear inspection and dielectric testing. Demand concentrates in Texas and California where ERCOT and CAISO interconnection backlogs drive utility procurement for renewable integration projects. SF6-free alternatives now dominate new specifications.
- Ring Main Units:Compact sealed-for-life designs minimize maintenance but demand specialized fault-passage indicator calibration. Underground distribution densification in Toronto and Vancouver municipal programs accelerates deployment. These units expand most quickly among product categories.
- Switchgear Assemblies:Customized busbar configurations and protection relay integration command extended commissioning support.
- Hybrid Switchgear:Mixed-technology designs combining gas-insulated and air-insulated elements require cross-trained service technicians.
Circuit breakers hold the largest share; momentum sits with ring main units.
End User:
Customer procurement sophistication spans from framework-agreement purchasing to project-specific engineering, reshaping vendor engagement models.
- Utilities:Integrated resource planning consolidates multi-year procurement with performance guarantees. Duke Energy and Xcel Energy specify IEEE C37.20.2 compliance and seismic qualification upfront. FERC Order 2023 interconnection reforms compress specification windows.
- Renewable Energy:Customized interconnection specifications and stringent power-quality requirements generate disproportionate margin pools. Wind and solar developers in Texas and California face procurement urgency from queue backlogs. This segment climbs the fastest.
- Manufacturing:Petrochemical and offshore Gulf Coast applications demand specialized outdoor enclosures with corrosion resistance.
- Commercial Buildings:Urban electrification programs in Northeast corridor states drive secondary substation equipment demand.
Utilities command the largest procurement volume; renewable energy shows the steepest expansion trajectory.
Installation Type:
Physical configuration dictates enclosure engineering standards and site logistics complexity across deployment scenarios.
- Outdoor:Powell Industries dominates specialized enclosures for petrochemical and offshore applications along the Gulf Coast. NEMA 3R and 4X ratings withstand salt spray and chemical exposure. Hurricane-prone regions specify enhanced structural integrity.
- Indoor:Arc-flash containment and ventilation requirements dominate specification sheets for substation control buildings. Seismic qualification per IEEE 693 adds engineering overhead.
- Compact:Space-constrained urban substations in Canadian and US dense markets favor reduced-footprint designs.
- Modular:Factory-integrated skids reduce field assembly time for accelerated renewable interconnection timelines.
Outdoor installations retain the largest installed base; compact configurations gain share fastest.
Service Type:
Recurring revenue potential concentrates in predictive maintenance platforms as sensor-embedded switchgear converges with digital twin integration.
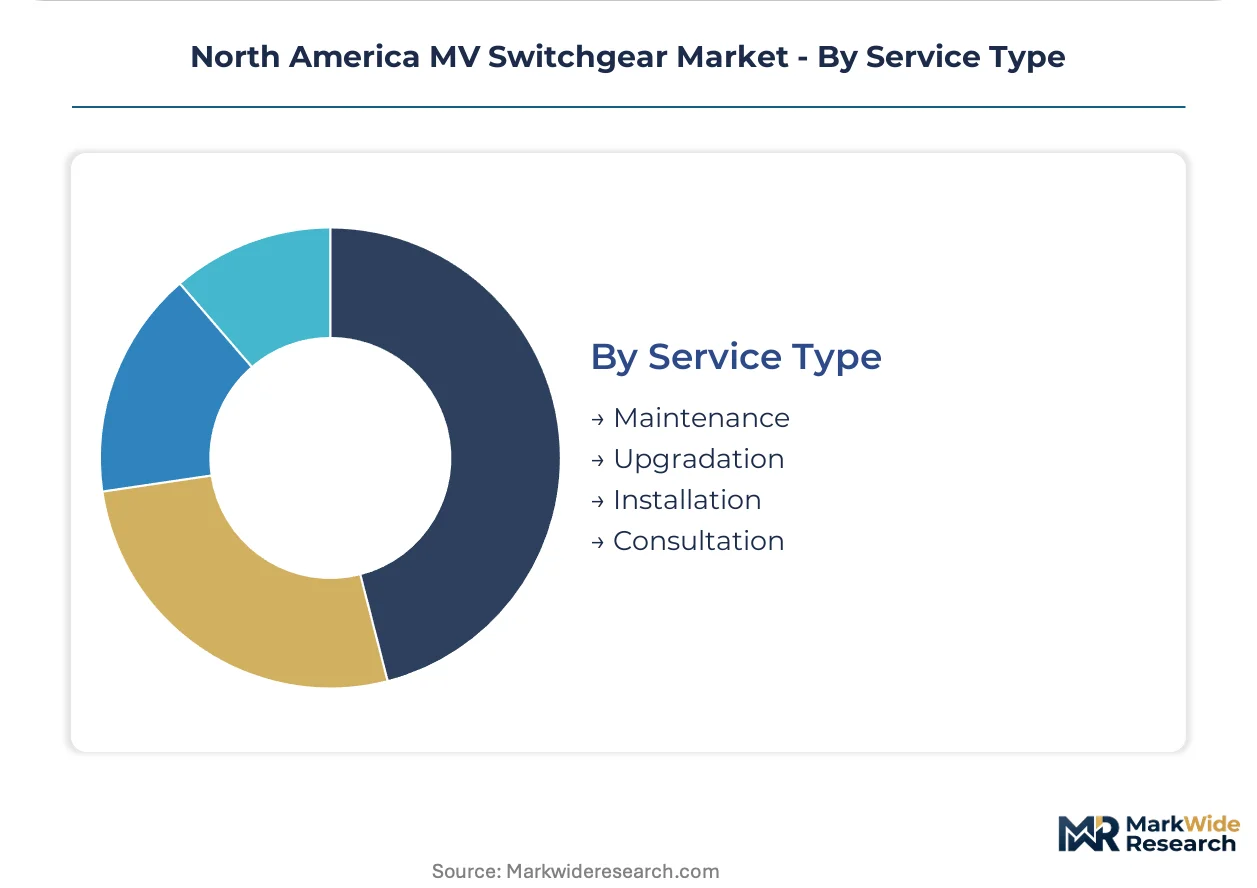
- Maintenance:EPA sulfur hexafluoride emissions tracking mandates annual leak detection reporting above one percent thresholds. California, New York, and Massachusetts enforce supplemental state restrictions. Monitoring system installation creates ongoing service attachment.
- Upgradation:Legacy substation integration complexity consumes disproportionate engineering hours as SF6-free equipment interfaces with 30-40 year-old protection relay schemes.
- Installation:Schneider Electric leverages Austin operations to anchor regional service capabilities for utility-scale deployments.
- Consultation:Seismic qualification bottlenecks and extended IEEE C37.20.2 certification cycles drive engineering advisory demand.
Maintenance generates the most recurring revenue; upgradation services expand most quickly as EPA regulations accelerate replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic fabrication capacity clusters along the Gulf Coast and Great Lakes corridors, with specialized enclosure engineering concentrating in Houston and Chicago industrial zones. Component sourcing extends into Ontario and Quebec for busbar and relay assemblies. Mexico's northern border states anchor copper foundry operations serving cross-border utility procurement.
United States
ERCOT interconnection queue reforms and CAISO renewable backlogs drive substation buildouts across Texas and California. EPA sulfur hexafluoride emissions rules mandate equipment-level tracking and accelerate SF6-free procurement specifications. Gulf Coast petrochemical clusters in Houston and Beaumont anchor Powell Industries' specialized outdoor enclosure production for offshore applications.
Canada
Toronto and Vancouver municipal electrification programs expand underground distribution densification. Provincial utilities in Ontario and British Columbia specify CSA C22.2.31 compliance for seismic qualification. Montreal-area engineering firms concentrate arc-flash containment design expertise for harsh-climate installations.
Mexico
Northern border states host copper foundry capacity supplying busbar components to US utility fabricators. CFE grid modernization investments in Baja California and Sonora drive procurement for renewable interconnection infrastructure. Monterrey industrial clusters specialize in steel enclosure fabrication for NEMA-rated outdoor applications.
North America MV Switchgear Market Vendor Landscape
Integrated multinational electrical equipment conglomerates and specialized regional fabricators split the market across distinct capability tiers. Consolidation pressure intensifies as utilities consolidate procurement into multi-year framework agreements demanding captive installation and maintenance capabilities. Two strategic archetypes dominate: full-service OEMs with end-to-end project execution capabilities, and niche specialists concentrating on severe-environment enclosures or seismic-qualified designs. Competitive moves center on geographic expansion into Texas manufacturing zones and technology licensing for SF6-free insulation alternatives.
Within the full-service OEM tier, Schneider Electric SE and ABB Ltd exemplify integrated providers with captive regional service networks. Schneider leverages its Austin operations to anchor utility-scale deployment capabilities across ERCOT territories. Powell Industries occupies a specialist position in severe-environment outdoor enclosures for Gulf Coast petrochemical and offshore applications. These three entities represent divergent strategic postures: multinational scale versus regional fabrication depth versus application-specific engineering.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Powell Industries |
| ABB Ltd |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Eaton Corporation plc |
| General Electric |
| LS Electric Co., Ltd. |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
The I-35 freight corridor connecting Mexican copper foundries to Texas fabrication centers feeds directly into supply concentration and downstream price stratification across medium-voltage switchgear procurement. Logistics cost dynamics from Monterrey to Houston amplify margin compression for standard-tier equipment while insulating premium seismic-qualified products from commodity pricing pressure.
Pricing Analysis
EPA sulfur hexafluoride emissions reporting mandates dictate the pricing tier structure across North American utility procurement. Three-tier pricing structure across premium, standard, and economy levels separates IEEE 693 seismic-certified equipment from standard IEEE C37.20.2-compliant units and basic commercial-grade assemblies. Cost compression in the standard tier is intensifying because Mexican copper foundry capacity constraints extend raw material lead times. Renewable energy developers exhibit the highest price sensitivity due to interconnection queue urgency, while petrochemical operators in Gulf Coast markets show the least sensitivity given corrosion-resistance specifications.
Supply Chain Analysis
Copper foundry operations in Mexico, relay assembly facilities in Ontario, and steel enclosure fabricators in Illinois hold concentrated contract-manufacturing capacity for North American switchgear production. The supply chain draws from Chilean copper concentrate, domestic steel coil, and vacuum interrupter assemblies sourced from Japan and South Korea. Single-source vulnerability around IEEE 693 shake-table testing facilities in California and Massachusetts creates qualification bottlenecks that extend new product introduction timelines. Distribution runs through utility-direct procurement frameworks and specialized electrical distributors serving industrial and commercial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive maintenance platforms and EPA-mandated emissions monitoring systems is expanding faster than hardware sales across North American MV switchgear markets. Digital twin integration and sensor-embedded asset performance data monetization now command recurring revenue multiples that hardware transactions cannot replicate.
For Market Incumbents: Pre-empt SF6-free technology displacement by accelerating vacuum interrupter R&D investment and captive installation capability expansion across ERCOT and CAISO territories. Consolidate framework agreement positioning through multi-year performance guarantees that lock out project-based distributors. Defend against specialized regional fabricators by acquiring seismic qualification engineering expertise concentrated in aging utility cohorts.
For New Entrants and Emerging Players: Build out ring main unit specialization targeting Toronto and Vancouver underground distribution densification programs where incumbent coverage remains thin. Canadian municipal electrification mandates create immediate procurement windows without entrenched supplier relationships. Establish engineering advisory services around legacy substation integration complexity to bypass capital-intensive manufacturing entry barriers.
For Investors and Strategic Acquirers: Seismic-qualified design specialists with IEEE 693 certification track records represent the most defensible acquisition targets in a market where testing facility scarcity creates persistent bottlenecks. Long-term viability over the next decade hinges on successful SF6-free technology transition completion and digital service platform integration. Watch for FERC Order 2023 implementation acceleration as the inflection signal indicating substation buildout procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Technology Licensing | EPA emissions rules force insulation technology substitution across utility specifications. |
| Seismic Qualification Investment | IEEE 693 certification scarcity creates persistent competitive moats for qualified suppliers. |
| Predictive Maintenance Platform Integration | Sensor-embedded switchgear converges with digital twin monetization for recurring revenue. |
| Gulf Coast Manufacturing Footprint Expansion | Regional fabrication reduces lead times for petrochemical and offshore enclosure demand. |
| Utility Framework Agreement Consolidation | Duke Energy and Xcel Energy multi-year procurement shifts favor integrated OEM service capabilities. |
Methodological Framework
Cross-validation between utility procurement officer interviews and FERC interconnection queue data anchors the qualitative findings in documented infrastructure investment patterns. Primary engagement with substation engineering directors, OEM aftermarket service heads, EPC contractor project managers, and electrical distributor account executives combined with secondary validation through IEEE standards documentation, EPA regulatory filings, EIA grid investment databases, and utility integrated resource plan disclosures. Bottom-up equipment shipment analysis and top-down grid modernization budget triangulation establish volume and value estimates.
Calibration against historical utility capital expenditure cycles and renewable interconnection completion rates ensures forecast robustness across the projection horizon. Segmentation modeling incorporates product type complexity, end-user procurement sophistication, installation configuration requirements, and service intensity profiles. CAGRs derive from equipment replacement cycle analysis, regulatory phase-out timeline acceleration, and infrastructure investment elasticity to interconnection queue reform. Forecast inputs include copper price volatility scenarios and domestic content requirement implementation trajectories.
Stress conditions across raw material input costs, regulatory enforcement intensity, and engineering talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology transition pace and utility procurement consolidation trends. Specific risk factors including prolonged IEEE C37.20.2 certification delays or accelerated state-level SF6 restrictions could materially revise trajectory. Cross-checking against EIA Annual Energy Outlook infrastructure investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Hazardous Location Limit Switches Market
Switches
Fusible Switches Market
Switches
Oil Level Switches Market
Switches
Smart Pole-Mounted Switch Market
Switches
Micro Switch Market
Switches
North America Switchgear Market
Switches
Asia Pacific Safety Switches Market
Switches
5G Solid State Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
United States X by Wire Systems Market
Switches
Pad-Mounted Switchgear Market
Switches
Reed Switches Sensors Market
Switches
Power Load Switches Market
Switches
India Reed Sensors Switches Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Asia-Pacific High Voltage Switchgear Market