
 Saudi Arabia Industrial Electrical Components Market | 2026-2036
Saudi Arabia Industrial Electrical Components Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Industrial Electrical Components Market Analytics
Aftermarket service revenue for switchgear and transformer maintenance is rewriting profit allocation across the value chain. Alfanar Company leverages its integrated manufacturing and service footprint to capture recurring revenue streams. Saudi Power Transformer Company anchors its position through high-voltage coil production capabilities. Electrical Industries Company (EIC) competes on rapid turnaround for utility refurbishment contracts.
Saudi Arabia industrial electrical components encompass power distribution and control apparatus—including vacuum-interrupter switchgear, oil-immersed distribution transformers, and microprocessor-based protective relays—engineered to operate at ambient temperatures up to 55°C and voltages spanning 0.4 kV through 400 kV. These components regulate, protect, and transform electrical energy for continuous industrial processes. Switchgear dominates capital expenditure across petrochemical complexes due to arc-flash containment requirements. Smart technology adoption in transformer monitoring is expanding fastest among utilities seeking predictive maintenance capabilities. Conventional analog relays remain entrenched in legacy oilfield infrastructure where digital retrofit costs deter replacement.
SFDA mandates IEC-equivalent electrical safety certification for all industrial components deployed in hazardous process environments. SASO's technical regulations for low-voltage equipment restrict market access to products bearing approved conformity marks. The Saudi Electricity Company (SEC) procurement standards increasingly require local content verification for transformer and switchgear awards. Stakeholders must monitor how Vision 2030 localization quotas reshape supplier qualification criteria and domestic joint-venture requirements.
Market Dynamics
SFDA electrical safety mandates and Saudi Vision 2030 localization targets are compressing supplier qualification timelines while redirecting procurement toward domestic manufacturing joint ventures. This regulatory-industrial convergence is restructuring competitive entry barriers across transformer and switchgear categories.
Growth Catalysts
- Downstream oil and gas modernization:Petrochemical operators in Jubail and Ras Al-Khair are replacing aging switchgear with arc-flash-rated vacuum interrupters to meet process safety requirements.
- SASO technical regulations:Mandatory conformity marks for low-voltage equipment are filtering out uncertified imports and consolidating demand around approved suppliers.
- SEC local content verification:Procurement standards now require documented domestic value-add for high-voltage transformer awards, incentivizing foreign manufacturers to establish coil-winding and assembly facilities within the Kingdom.
Market Restraints
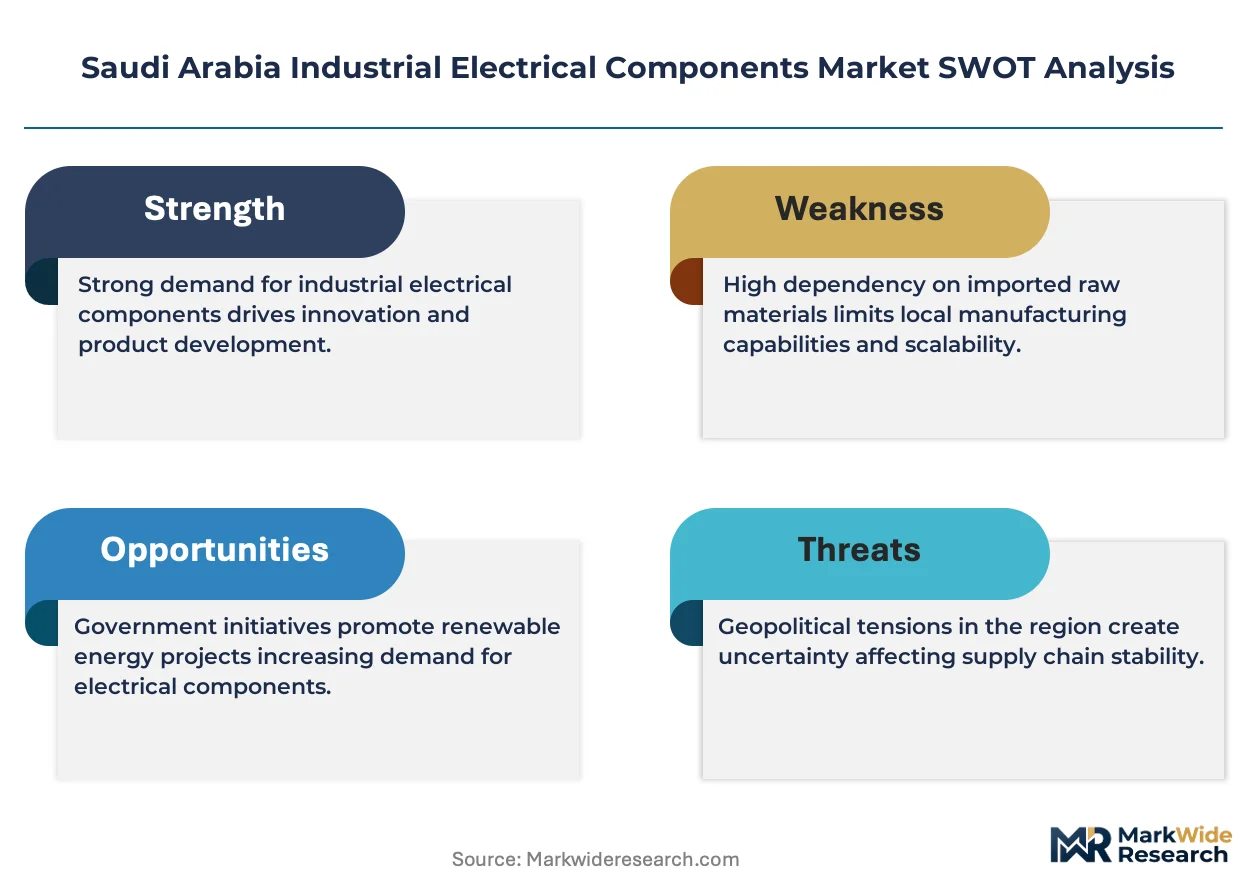
- Copper and grain-oriented electrical steel volatility:Transformer core material costs fluctuate with global commodity indices, compressing margin predictability for domestic manufacturers dependent on imported inputs.
- High-voltage coil production concentration:Advanced winding capabilities for 132 kV and above remain concentrated among a limited set of certified facilities in the Eastern Province.
- IEC 61850 retrofit inertia:Legacy oilfield infrastructure retains analog protective relays due to digital communication protocol upgrade costs and downtime penalties.
Strategic Opportunities
- Tabuk and Jazan industrial zone expansion:Greenfield smelter and mining projects in underpenetrated western regions require complete power distribution infrastructure buildouts.
- Smart transformer monitoring convergence:Integration of dissolved gas analysis sensors with edge computing platforms enables predictive maintenance contracts for Saudi Electricity Company distribution networks.
- Service revenue unbundling:Switchgear maintenance contracts are separating from equipment sales, creating recurring revenue streams for technicians with arc-flash certification and thermal imaging capabilities.
Industry Challenges
- Arc-flash engineering talent scarcity:Qualified protection engineers with IEC 60909 short-circuit calculation expertise remain concentrated among SEC and major EPC contractors.
- SFDA certification timeline compression:Hazardous area equipment approvals for Zone 1 and Zone 2 environments require extended third-party testing cycles that delay project commissioning.
- Legacy analog-digital integration complexity:Microprocessor relay retrofits into 1980s-era oilfield substations demand custom protocol gateways and staged cutover planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Industrial Electrical Components Market |
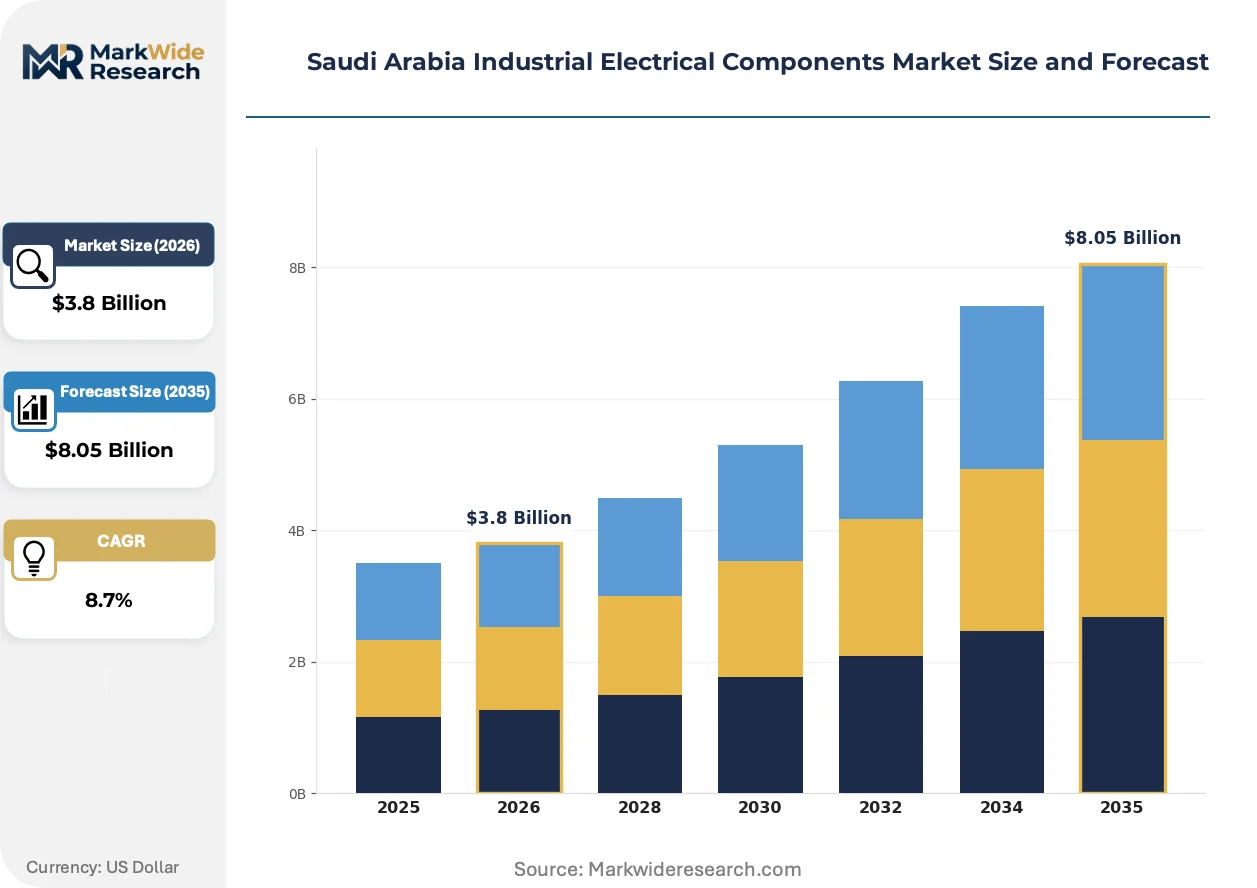
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switchgear, Circuit Breakers, Transformers, Relays Application: Manufacturing, Power Generation, Construction, Oil & Gas End User: Utilities, Industrial, Commercial, Residential Technology: Digital, Analog, Smart, Conventional |
| Companies Covered | Saudi Power Transformer Company, Electrical Industries Company (EIC), Al-Abdulkarim Holding (AKH) Co., Bahra Advanced Cable Manufacture Company Limited, Alfanar Company, GEDAC Electric Company, TIEPCO, Advanced Technical Solutions Company for Industry, Saudi Electric Supply Company Limited (SESCO), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Industrial Electrical Components Market Evolving Landscape
Digitization of asset health monitoring is converging with localization mandates to reshape how industrial electrical components are specified, procured, and maintained across Saudi processing facilities.
Dry-type cast resin transformers are hybridizing with built-in fiber-optic temperature monitoring systems to eliminate oil containment risks in petrochemical environments. Aramco and SABIC affiliates are specifying these units for indoor substations at new cracker complexes. The technology is hybridizing procurement criteria by merging fire safety compliance with predictive maintenance capability in single capital decisions.
SFDA mandates now require IEC-equivalent electrical safety certification for all components deployed in hazardous process environments. Industrial buyers must document conformity assessment body approvals before site acceptance testing. Switchgear suppliers serving Jubail petrochemical clusters are responding by pre-certifying entire product families through SASO-notified bodies to compress delivery schedules.
Aftermarket service contracts are unbundling from original equipment sales as utilities and industrial operators seek specialized maintenance providers. Saudi Electricity Company distribution divisions now tender transformer condition monitoring separately from capital procurement. This pattern is most visible in the Eastern Province, where Alfanar and EIC technicians compete on thermal imaging turnaround times and dissolved gas analysis interpretation accuracy.
Saudi Arabia Industrial Electrical Components Market Segmentation
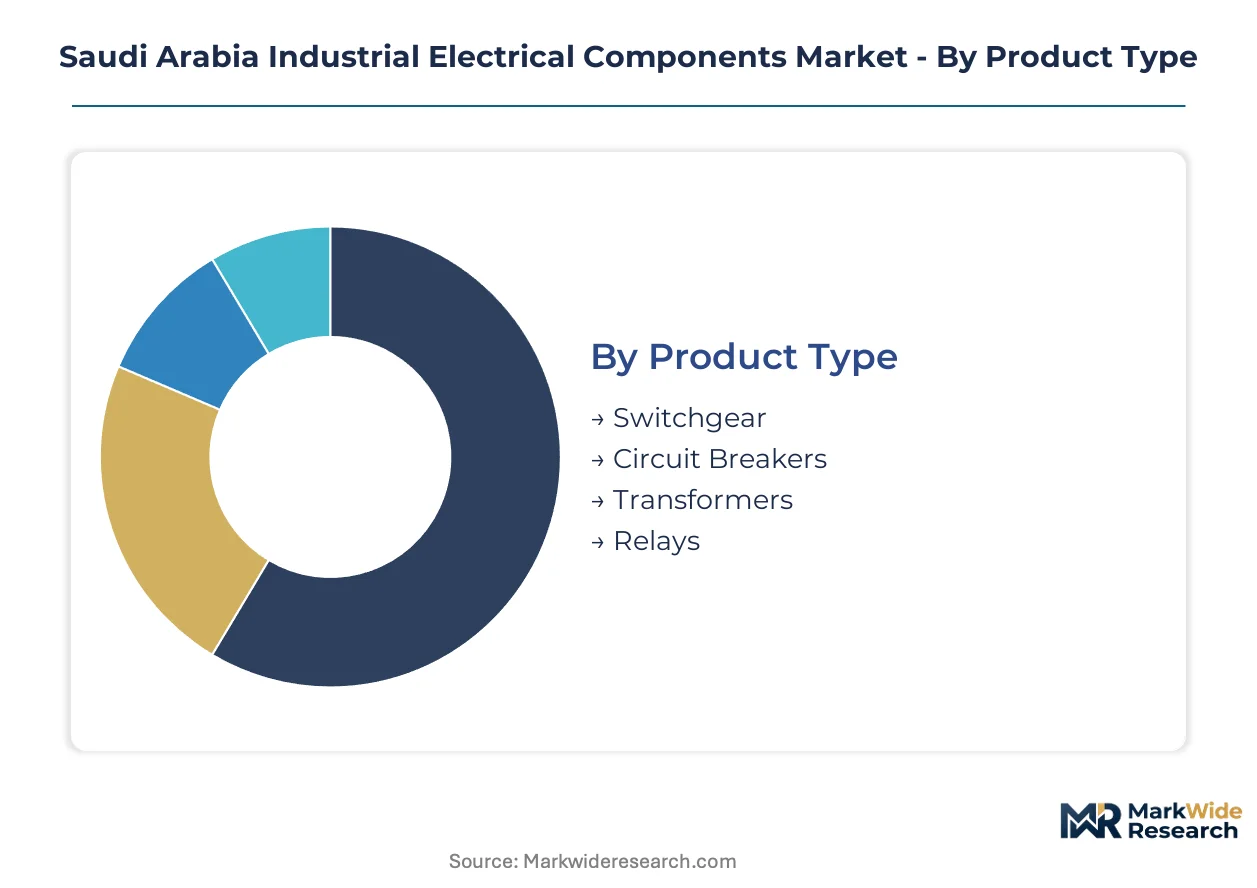
Segmentation in the Saudi Arabia Industrial Electrical Components Market determines how after-sales service intensity varies across equipment categories. Switchgear and transformer segments generate recurring maintenance revenue streams that now rival original equipment margins. Understanding these segment-specific service economics guides procurement strategy for operators in Jubail and Ras Al-Khair industrial clusters.
Product Type:
After-sales service intensity varies dramatically by product type, with switchgear and transformers commanding multi-year maintenance contracts while relays and circuit breakers follow replacement cycles.
- Switchgear:Vacuum-interrupter and gas-insulated switchgear assemblies rated 11 kV through 132 kV incorporate arc-flash containment systems mandatory for petrochemical process safety. Demand concentrates in Jubail and Ras Al-Khair complexes where SABIC and Aramco affiliates modernize aging oil-immersed switchyards to meet SFDA hazardous area mandates.
- Transformers:Oil-immersed distribution units and dry-type cast resin designs span 0.4 kV to 400 kV ratings with ambient temperature tolerance to 55°C. Procurement clusters around Saudi Electricity Company high-voltage substation upgrades and new smelter projects in Tabuk and Jazan where coil-winding localization quotas apply.
- Circuit Breakers:Air and vacuum interruption mechanisms protect feeder circuits across industrial substations.
- Relays:Electromechanical and microprocessor-based protective devices coordinate fault clearance in utility and oilfield networks.
By volume, Transformers leads. By growth pace, Switchgear is ahead.
Application:
Application segmentation tracks how capital deployment priorities differ between process industries with continuous operations and infrastructure sectors with intermittent construction cycles.
- Oil & Gas:Downstream processing facilities in the Eastern Province require arc-flash-rated switchgear and smart transformer monitoring to replace 1980s-era analog infrastructure. SFDA mandates for Zone 1 and Zone 2 hazardous area certification compress supplier qualification timelines for equipment destined for Ras Al-Khair cracking complexes.
- Power Generation:Combined-cycle and solar photovoltaic integration projects demand high-voltage switchgear and protective relay systems with IEC 61850 communication protocols. Saudi Electricity Company procurement standards now require documented local content for transformer awards, redirecting sourcing toward domestic joint-venture facilities.
- Manufacturing:Steel, aluminum, and cement plants require robust power distribution architectures.
- Construction:Temporary and permanent electrification for commercial and industrial building projects.
By installed base, Oil & Gas dominates. By expansion velocity, Power Generation is climbing the fastest.
End User:
End user categories reveal divergent procurement behaviors between regulated utilities with centralized tendering and industrial operators with decentralized technical specifications.
- Utilities:Saudi Electricity Company distribution and transmission divisions tender transformer condition monitoring separately from capital procurement, unbundling service revenue from equipment sales. Eastern Province divisions prioritize thermal imaging turnaround and dissolved gas analysis interpretation accuracy in vendor selection.
- Industrial:Petrochemical, mining, and smelter operators specify dry-type cast resin transformers with fiber-optic temperature monitoring for indoor substations at new cracker complexes, merging fire safety compliance with predictive maintenance in single capital decisions.
- Commercial:Office complexes and retail centers specify standard distribution transformers and low-voltage switchgear.
- Residential:Housing developments and district cooling plants utilize conventional pad-mounted transformers.
By contract value, Utilities leads. By specification sophistication, Industrial is gaining share fastest.
Technology:
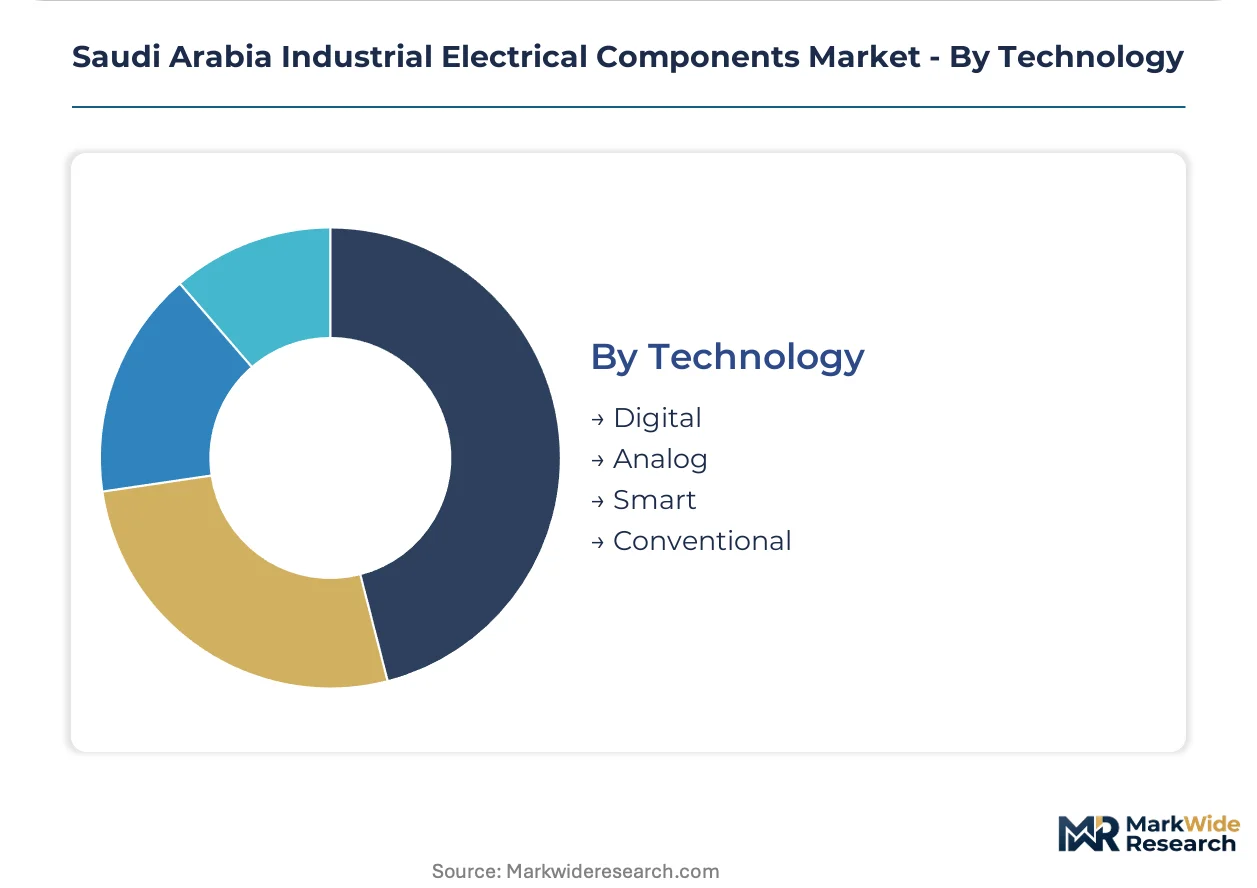
Technology segmentation captures the tension between legacy analog infrastructure with low retrofit appetite and digital systems with predictive maintenance capabilities.
- Smart:Transformer monitoring platforms integrate dissolved gas analysis sensors with edge computing for predictive maintenance contracts. Saudi Electricity Company distribution networks in the Eastern Province pilot these systems to reduce unplanned outage duration.
- Digital:Microprocessor-based protective relays with IEC 61850 communication enable centralized substation automation. Adoption concentrates in greenfield Tabuk and Jazan industrial zones where protocol upgrade costs do not burden legacy infrastructure.
- Analog:Electromechanical relays and conventional transformer monitoring persist in oilfield infrastructure.
- Conventional:Standard switchgear and transformer designs without integrated monitoring capabilities.
By deployment base, Conventional leads. By specification momentum, Smart is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Saudi Arabia's industrial electrical components landscape diverge sharply between the oil-dominated Eastern Province and the emerging mining corridors of the west. Utilities prioritize transformer refurbishment cycles while petrochemical operators emphasize arc-flash containment in new switchgear specifications.
Eastern Province
Jubail and Ras Al-Khair industrial cities concentrate demand for 132 kV vacuum-interrupter switchgear as SABIC and Aramco affiliates modernize cracking complexes. SFDA mandates for Zone 1 hazardous area certification compress supplier qualification timelines for equipment destined for these facilities. High-voltage coil production capabilities remain anchored here, with SEC procurement standards requiring documented local content verification for transformer awards.
Riyadh
The central region drives demand for smart transformer monitoring platforms as Saudi Electricity Company distribution divisions pilot predictive maintenance systems. SASO technical regulations for low-voltage equipment filter procurement toward conformity-marked suppliers serving the capital's expanding data center and logistics hub construction. Industrial zones on the city's periphery specify dry-type cast resin transformers with fiber-optic temperature monitoring for fire-sensitive indoor installations.
Western Region
Tabuk and Jazan industrial zones require complete power distribution infrastructure buildouts for greenfield smelter and mining projects. Vision 2030 localization quotas redirect transformer sourcing toward domestic joint-venture facilities with coil-winding capabilities. The region's underpenetrated status creates first-mover opportunities for suppliers establishing arc-flash-certified maintenance technician networks.
NEOM Northwest
The giga-project zone specifies IEC 61850-compliant protective relay systems for its planned renewable energy integration backbone. Procurement patterns here favor digital-native suppliers capable of edge-computing convergence for substation automation. The absence of legacy analog infrastructure eliminates retrofit cost barriers that constrain smart technology adoption elsewhere.
Saudi Arabia Industrial Electrical Components Market Competitive Landscape
Capability concentration sits with specialized coil-winding and arc-flash engineering tiers; scale advantage sits with integrated manufacturing-and-service footprints. Domestic joint ventures capture SEC procurement preference through local content verification, while foreign manufacturers defend position through technology licensing arrangements. Two archetypes dominate: integrated electrical equipment conglomerates with captive maintenance networks, and specialized high-voltage component fabricators with certified hazardous area expertise. Competitive moves center on unbundling service revenue from equipment sales and establishing coil-winding joint ventures to meet localization mandates.
Within the integrated conglomerate tier, Alfanar Company and Electrical Industries Company exemplify the manufacturing-and-service model capturing recurring maintenance contracts. Saudi Power Transformer Company anchors the high-voltage specialization vector through its coil production capabilities. These three entities collectively represent how domestic qualification requirements and SEC procurement standards reshape competitive positioning across switchgear and transformer categories.
| Leading Market Players |
|---|
| Saudi Power Transformer Company |
| Electrical Industries Company (EIC) |
| Al-Abdulkarim Holding (AKH) Co. |
| Bahra Advanced Cable Manufacture Company Limited |
| Alfanar Company |
| GEDAC Electric Company |
| TIEPCO |
| Advanced Technical Solutions Company for Industry |
| Saudi Electric Supply Company Limited (SESCO) |
| Others |
Value Network & Pricing Analysis
Copper and grain-oriented electrical steel volatility determines both pricing tier spreads and supply chain shape across Saudi Arabia's industrial electrical components landscape. Global commodity index swings compress margin predictability for domestic manufacturers while forcing procurement teams to layer long-term offtake contracts atop spot-market exposure.
Pricing Analysis
Long-term offtake agreements dominate transformer procurement as Saudi Electricity Company distribution divisions seek cost predictability across multi-year refurbishment cycles. Pricing stratifies across premium, standard, and economy tiers based on IEC certification grade and after-sales service bundling. Cost compression in standard-grade switchgear is intensifying because Jubail petrochemical operators are consolidating supplier panels around pre-certified product families. Industrial end-users show highest price sensitivity due to capital budget cyclicality, while utilities absorb premium pricing for localized coil-winding capabilities that satisfy Vision 2030 content verification.
Supply Chain Analysis
Export-control regimes restricting advanced winding machinery flows from Germany and Japan constrain high-voltage coil production scaling in the Eastern Province. Saudi manufacturers draw from Chinese and South Korean sources for copper conductor and core steel, with European specialists feeding protective relay component streams. Single-source vulnerability concentrates in 132 kV and above winding equipment where certified facility count remains limited. Distribution runs through Saudi Electricity Company tendering platforms for utility-scale awards, while direct EPC channel relationships govern petrochemical complex procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's industrial electrical components market sits in early-cycle expansion as downstream oil and gas modernization accelerates switchgear replacement cadence. Smart transformer monitoring adoption creates parallel service revenue streams that reshape vendor economics.
For Market Incumbents: Harden arc-flash engineering capabilities against talent scarcity by embedding IEC 60909 calculation expertise within captive technician networks. Deepen upstream control over coil-winding operations to defend margin position as Vision 2030 localization quotas tighten. Pre-certify entire switchgear product families through SASO-notified bodies before Jubail and Ras Al-Khair tender releases compress qualification windows.
For New Entrants and Emerging Players: Build out arc-flash-certified maintenance technician networks in Tabuk and Jazan where greenfield smelter projects lack established service infrastructure. Target dissolved gas analysis interpretation contracts that Saudi Electricity Company now tenders separately from capital equipment procurement. Lead with thermal imaging turnaround speed as the go-to-market wedge against integrated conglomerates with slower response protocols.
For Investors and Strategic Acquirers: Vision 2030 localization quota enforcement reshapes the acquisition landscape toward joint-venture structures with documented coil-winding capabilities. The five-to-ten year viability window favors targets combining hazardous area certification expertise with recurring maintenance contract books. Watch SEC procurement standard revisions as the signal for when domestic content verification thresholds will trigger supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Coil-Winding Joint Venture Formation | Vision 2030 localization quotas redirect transformer awards toward verified domestic value-add facilities. |
| Arc-Flash Certification Pre-Investment | SFDA hazardous area mandates compress supplier qualification timelines for Zone 1 equipment destined for Jubail complexes. |
| Smart Monitoring Platform Integration | Dissolved gas analysis sensors with edge computing enable predictive maintenance contracts for SEC distribution networks. |
| Service Revenue Unbundling | Separate tendering for transformer condition monitoring creates recurring revenue streams independent of capital sales cycles. |
| Western Region Technician Network Buildout | Tabuk and Jazan industrial zones lack established maintenance infrastructure for greenfield smelter electrification projects. |
Research Methodology
A standing panel of utility procurement officers, petrochemical maintenance directors, EPC project managers, and arc-flash protection engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC tender documentation, SASO technical regulation filings, customs import records for electrical steel and copper conductor, and IEC certification body disclosure databases. Bottom-up equipment shipment tracking and top-down utility capital expenditure analysis were triangulated to anchor volume estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning product type, application sector, end-user category, and technology tier. CAGRs were derived from installation base depreciation curves and replacement cycle acceleration factors specific to SFDA mandate compliance deadlines. Forecast inputs incorporated commodity price sensitivity bands for grain-oriented electrical steel and copper, plus localization quota phase-in assumptions.
Stress conditions across copper price volatility, coil-winding equipment import licensing delays, and SEC procurement standard revision timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about mandate enforcement intensity and joint-venture formation velocity. Material shifts in Vision 2030 localization quota thresholds or SFDA certification timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Slip Ring Market
Electrical Equipment
Insulator Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Laminated Busbar Market