
 Asia-Pacific Vacuum Circuit Breakers Market | 2026-2036
Asia-Pacific Vacuum Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vacuum Circuit Breakers Market Outlook
Skilled vacuum interrupter technician availability is collapsing across Southeast Asian manufacturing hubs, forcing OEMs to restructure assembly footprints. Mitsubishi Electric Corporation sustains captive production of ceramic vacuum envelopes at its Japanese facilities, insulating it from regional labor shortages. Fuji Electric Co., Ltd. dominates medium-voltage indoor breaker supply to Tokyo Electric Power and affiliated Japanese utilities. Siemens AG anchors engineering centers in India to train local talent pools for digital-hybrid breaker commissioning.
Asia-Pacific vacuum circuit breakers are sealed pressure-switching devices utilizing vacuum arcs between copper-chrome contacts to interrupt fault currents up to 40.5 kV, primarily protecting transformers, generators, and cable networks from overload damage. Indoor installations command the largest product type share due to dense urban substation constraints across Japanese and South Korean metropolitan grids. Digital technology breakers represent the fastest-expanding segment as utilities in Australia and Taiwan integrate remote monitoring and predictive diagnostics into existing electromechanical infrastructure. Hybrid architectures blending mechanical reliability with digital sensing are capturing margin pools in premium utility tenders.
Japan's METI enforces JIS C 4603 standards for vacuum interrupter endurance testing, while India's CEA mandates localized content thresholds under its Make in India power equipment directives. Australia's TGA-equivalent electrical safety frameworks and China's GB 1984 national standards collectively shape product certification requirements and market access timelines across the region. Stakeholders must weigh backward integration into vacuum interrupter production against technology licensing partnerships as tariff and local-content rules tighten.
Market Dynamics
India's transmission utilities are retiring electromechanical switchgear fleets at scale, forcing vacuum circuit breaker OEMs to restructure supply chains around localized manufacturing mandates and ceramic vacuum interrupter sourcing.
Growth Catalysts
- India's PLI scheme for power equipment:Localized production incentives are pulling assembly capacity into Gujarat and Tamil Nadu manufacturing corridors.
- China's dual carbon goals:Grid modernization mandates are accelerating medium-voltage infrastructure replacement across provincial utilities.
- Renewable absorption requirements:Southeast Asian state grids are expanding switching capacity to manage intermittent solar and wind injection.
Market Restraints
- Ceramic vacuum envelope concentration:Japanese captive production controls critical interrupter component supply, exposing regional OEMs to input bottlenecks.
- CEA localization thresholds:India's Make in India directives impose content rules that extend certification timelines for foreign suppliers.
- SF6 alternative limitations:Dry air and fluoronitrile mixtures face dielectric performance constraints in high-altitude Himalayan substations.
Strategic Opportunities
- Vietnam's transmission buildout:State utility EVN is tendering 24 kV and 36 kV indoor breaker contracts for urban substation densification.
- Digital-mechanical hybrid architectures:Remote monitoring integration with copper-chrome contact systems is opening premium tender categories.
- Australia's predictive diagnostics mandate:Network operators are specifying condition-monitoring protocols that favor retrofit-ready breaker platforms.
Industry Challenges
- Vacuum interrupter technician scarcity:Southeast Asian manufacturing hubs lack trained specialists for ceramic envelope sealing and contact assembly.
- JIS C 4603 endurance testing timelines:Japanese METI certification protocols extend product validation cycles for regional market entry.
- Legacy electromechanical integration:Taiwanese and Australian utilities face commissioning complexity when grafting digital sensing onto installed mechanical breaker fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vacuum Circuit Breakers Market |
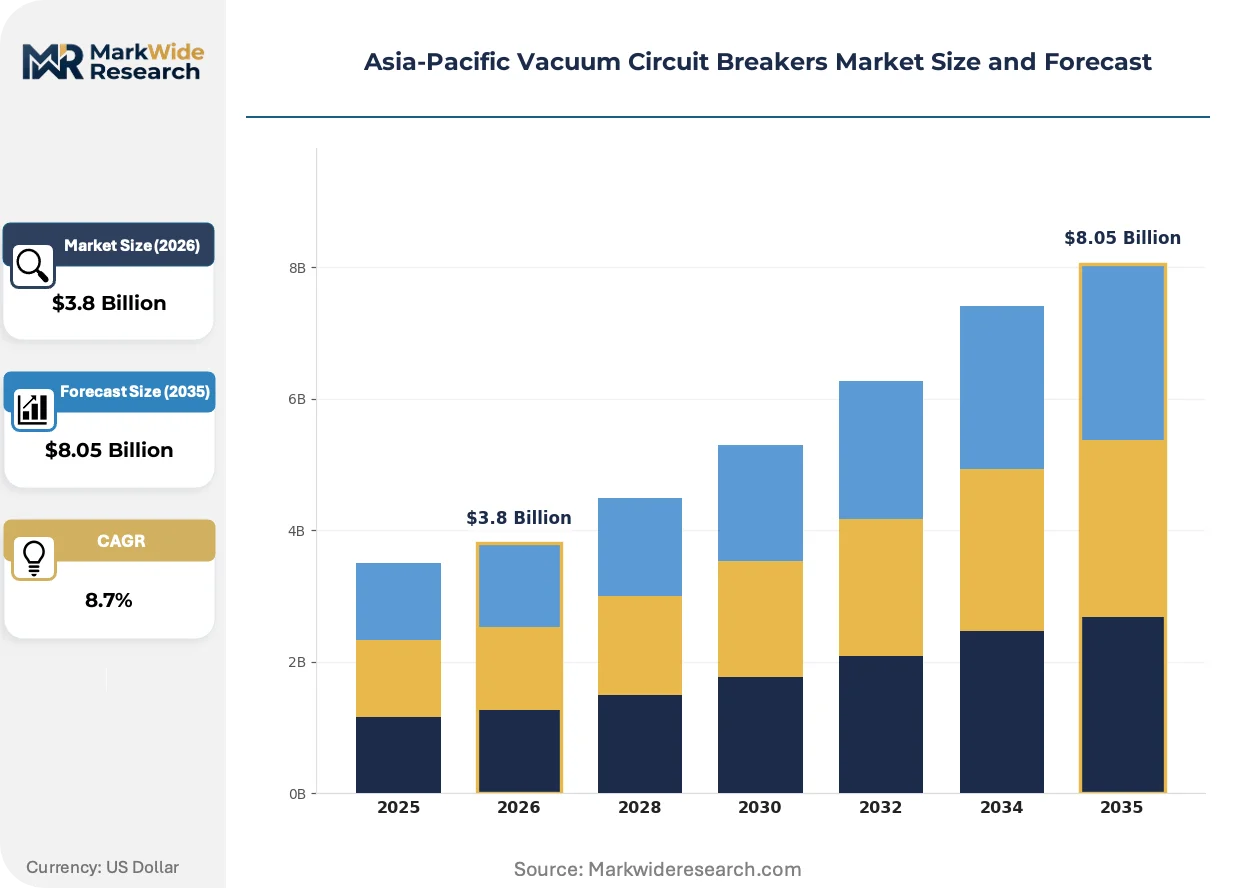
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor, Outdoor, Portable, Fixed Application: Power Distribution, Industrial Automation, Renewable Energy, Transportation End User: Utilities, Manufacturing, Commercial, Residential Technology: Mechanical, Digital, Hybrid, Electromechanical |
| Companies Covered | Schneider Electric SE, Mitsubishi Electric Corporation, Hitachi Ltd, Eaton Corporation PLC, Siemens AG, ABB Ltd, Toshiba Corporation, Fuji Electric Co., Ltd., Huayi Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vacuum Circuit Breakers Market Strategic Shifts
Digital sensing layers are grafting onto vacuum interrupter hardware, fragmenting traditional product categories and forcing OEMs to restructure engineering teams around software-integrated commissioning protocols.
Copper-chrome contact metallurgy is fragmenting across three competing formulations: standard CrCu 50/50 blends for cost-sensitive tenders, high-density CrCu 75/25 for high-interruption duty cycles, and nano-doped variants for ultra-fast switching in renewable collector substations. Indian state transmission utilities are piloting the high-density formulations in Rajasthan solar zones. The metallurgical divergence is fragmenting supplier qualification protocols and forcing breaker OEMs to maintain parallel contact sourcing strategies.
Japan's METI revised JIS C 4603 endurance testing protocols in 2023, mandating 10,000 electrical operation cycles for 24 kV rated breakers. The standard compresses product development timelines for regional suppliers seeking Japanese utility qualification. Korean manufacturers are responding by consolidating ceramic vacuum envelope testing at dedicated KERI-affiliated laboratories.
After-sales service unbundling is separating breaker hardware procurement from commissioning and predictive maintenance contracts. Australian network operators are tendering these functions independently, compressing OEM margin pools on initial equipment sales while expanding recurring revenue opportunities for diagnostics specialists. The shift is most visible in New South Wales and Victoria distribution network tenders.
Asia-Pacific Vacuum Circuit Breakers Market Segmentation
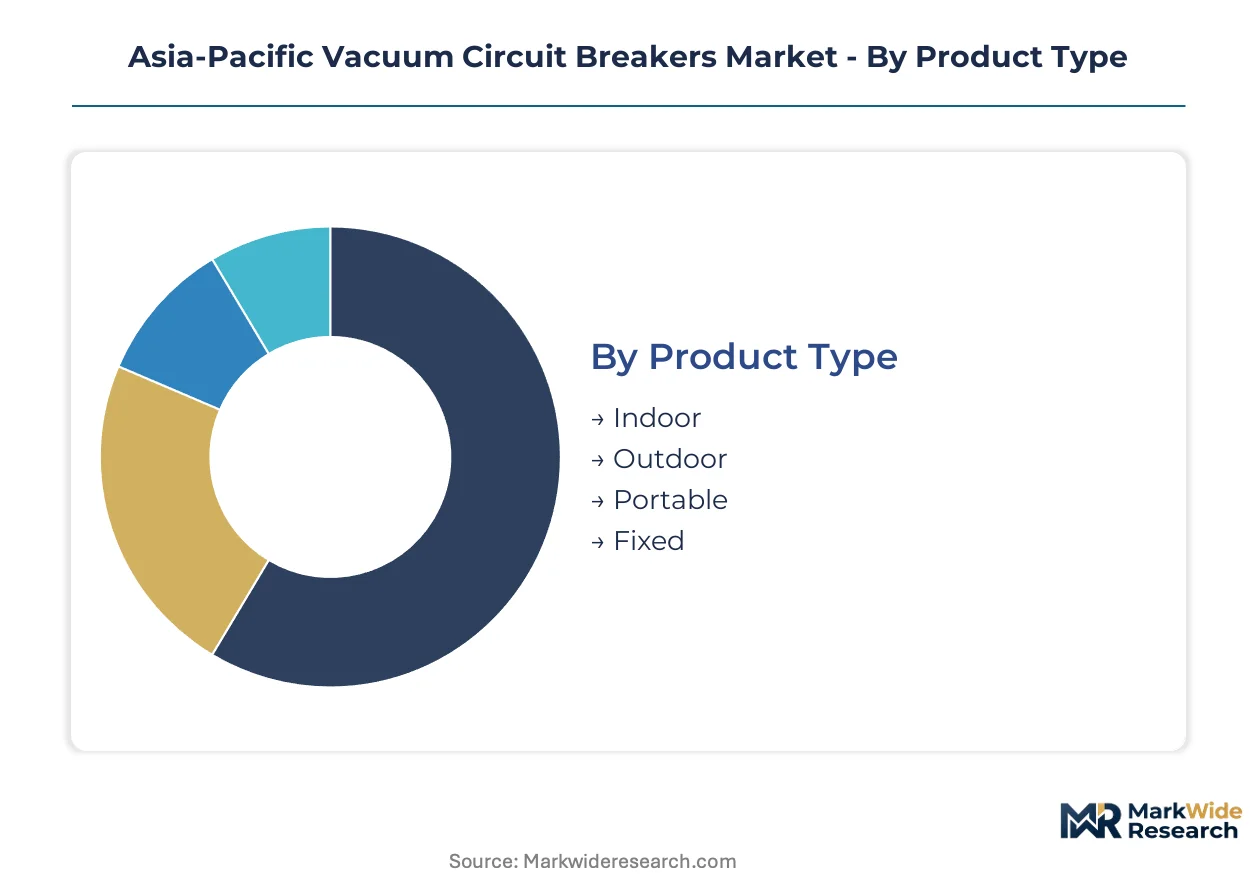
Vacuum circuit breaker procurement across Asia-Pacific fragments across four dimensions that determine specification requirements, certification pathways, and margin structures. Each segmentation axis carries distinct competitive dynamics shaped by utility modernization mandates, renewable integration pressures, and localized manufacturing incentives.
Product Type:
Outdoor and portable configurations face intensifying substitution pressure from gas-insulated alternatives in high-altitude Himalayan substations where vacuum dielectric performance degrades.
- Indoor:Sealed vacuum interrupter assemblies housed in metal-clad switchgear enclosures rated for 12-40.5 kV distribution networks. Demand concentrates in Japanese and South Korean metropolitan substations where space constraints and seismic codes favor compact, floor-mounted installations.
- Outdoor:Pole-mounted or freestanding breaker units with weather-resistant porcelain or composite housings. State grids in India and Vietnam are expanding procurement for rural distribution feeders and solar collector substations exposed to monsoon conditions.
- Portable:Mobile breaker units on skid or trailer platforms for emergency restoration and temporary grid reinforcement. Mining operations in Western Australia and Queensland specify these for remote site electrification.
- Fixed:Permanently installed breaker modules integrated into gas-insulated switchgear line-ups. Chinese provincial utilities favor fixed configurations for urban underground substation densification projects.
Indoor configurations anchor the volume base while hybrid indoor-digital variants gain share at the steepest rate.
Application:
Cost-tier stratification separates premium-specification breakers for nuclear and data center applications from standard-duty units for commercial distribution.
- Power Distribution:Medium-voltage feeder protection and bus sectionalizing in 11-33 kV utility networks. India's state transmission utilities dominate procurement volumes under CEA-mandated modernization programs.
- Industrial Automation:Motor protection and arc-flash mitigation in steel, cement, and petrochemical process plants. Japanese automotive manufacturing clusters specify JIS C 4603-certified breakers with extended mechanical endurance.
- Renewable Energy:Collector substation switching for solar and wind farm interconnection. Rajasthan and Gujarat solar zones in India are piloting high-interruption-duty copper-chrome contact formulations.
- Transportation:Traction power supply protection for metro rail and electrified railway networks. Vietnam's urban metro expansions in Hanoi and Ho Chi Minh City are tendering 24 kV indoor breakers for substation infrastructure.
Power distribution commands the installed base while renewable energy applications expand most quickly as intermittent generation penetration rises.
End User:
Customer-type concentration determines pricing leverage, with utilities consolidating procurement through framework agreements while commercial buyers fragment across project-specific tenders.
- Utilities:State-owned transmission and distribution companies operating under regulatory rate-base mechanisms. Procurement concentrates in India's Power Grid Corporation and state DISCOMs modernizing aging electromechanical fleets.
- Manufacturing:Heavy industrial facilities requiring reliable medium-voltage protection for continuous process operations. South Korean shipbuilding and semiconductor fabrication plants specify premium endurance ratings.
- Commercial:Data centers, hospitals, and large retail complexes demanding high-availability power distribution. Singapore and Sydney financial district developments are specifying digital-hybrid breakers with remote monitoring.
- Residential:Apartment complex substations and gated community distribution networks. Procurement volumes remain limited except in high-density Japanese and Chinese urban housing developments.
Utilities dominate procurement volume while commercial end users drive the steepest specification upgrades toward predictive diagnostics integration.
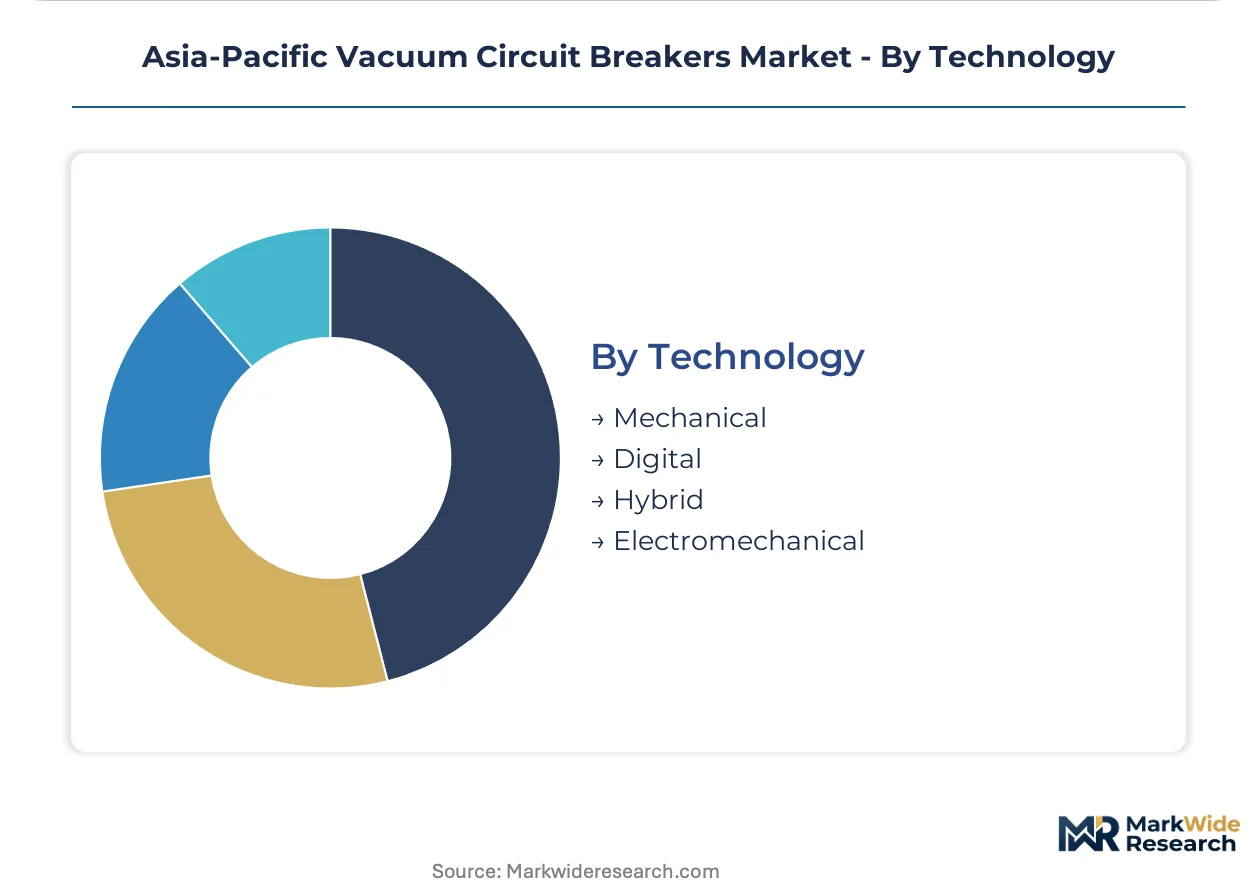
Technology:
Supply concentration in ceramic vacuum interrupter production favors established mechanical and electromechanical suppliers over digital-native entrants lacking backward integration.
- Mechanical:Spring-operated stored-energy mechanisms with manual or motor-charged closing. Japanese utilities maintain substantial installed bases requiring spare parts and lifecycle extension services.
- Digital:Microprocessor-controlled protection relays with IEC 61850 communication protocols. Taiwan's Taipower and Australia's network operators are retrofitting existing switchgear with digital sensing layers.
- Hybrid:Mechanical vacuum interrupters grafted with digital monitoring and predictive diagnostics. Premium tenders in New South Wales and Victoria specify these for condition-based maintenance programs.
- Electromechanical:Conventional solenoid or motor-operated mechanisms without embedded intelligence. India's aging state grid infrastructure retains significant electromechanical populations targeted for phased replacement.
Mechanical technology retains the largest installed base while hybrid architectures capture the steepest share gains in premium utility segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA anchors the regulatory framework driving vacuum circuit breaker procurement across the Asia-Pacific, with localized content mandates reshaping supply chain configurations for foreign and domestic suppliers alike.
India
State transmission utilities in Rajasthan and Gujarat are retiring electromechanical switchgear fleets at scale under CEA-mandated modernization programs. The PLI scheme for power equipment pulls assembly capacity into Tamil Nadu and Gujarat manufacturing corridors. High-density copper-chrome contact formulations are piloting in Rajasthan solar zones to manage high-interruption duty cycles.
China
Provincial utilities are accelerating medium-voltage infrastructure replacement to meet dual carbon goals. GB 1984 national standards govern product certification timelines and market access requirements. Urban underground substation densification projects in the Yangtze River Delta favor fixed breaker configurations integrated into gas-insulated switchgear line-ups.
Japan
METI enforces JIS C 4603 standards mandating 10,000 electrical operation cycles for 24 kV rated breakers, compressing product development timelines for regional suppliers. Tokyo Electric Power and affiliated utilities source medium-voltage indoor breakers from domestic suppliers. KERI-affiliated laboratories handle ceramic vacuum envelope testing for Korean manufacturers seeking qualification.
Australia
Network operators in New South Wales and Victoria are specifying condition-monitoring protocols that favor retrofit-ready hybrid breaker platforms. TGA-equivalent electrical safety frameworks shape product certification requirements. Mining operations in Western Australia and Queensland procure portable breaker units for remote site electrification.
Vietnam
State utility EVN is tendering 24 kV and 36 kV indoor breaker contracts for urban substation densification in Hanoi and Ho Chi Minh City. Urban metro expansions in both cities are driving traction power supply protection demand. Rural distribution feeders and solar collector substations exposed to monsoon conditions require weather-resistant outdoor configurations.
Asia-Pacific Vacuum Circuit Breakers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive vacuum interrupter production and digital-hybrid engineering capabilities separating premium-positioned suppliers from assembly-dependent competitors. The market structure concentrates around Japanese and European conglomerates with backward integration into ceramic envelope manufacturing, while Indian and Chinese fabricators compete on localized assembly cost positions. Two strategic archetypes dominate: vertically integrated interrupter producers and digital-native system integrators. Competitive moves center on technology licensing partnerships for SF6 alternatives and capacity relocation to satisfy CEA localization thresholds.
Among the integrated tier, Mitsubishi Electric Corporation exemplifies captive production advantages through Japanese-based ceramic vacuum envelope manufacturing. Siemens AG anchors engineering capabilities in India to develop local talent pools for digital-hybrid breaker commissioning. Fuji Electric Co., Ltd. occupies a position within the domestic Japanese utility supply chain, reflecting the concentration of premium-tier demand around METI-certified suppliers.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Hitachi Ltd |
| Eaton Corporation PLC |
| Siemens AG |
| ABB Ltd |
| Toshiba Corporation |
| Fuji Electric Co., Ltd. |
| Huayi Electric |
| Others |
Value Chain & Pricing Dynamics
Long-term framework agreements between Japanese ceramic vacuum envelope producers and regional breaker OEMs lock in supply access while anchoring price visibility across multi-year procurement cycles. These arrangements insulate captive producers from spot-market volatility but expose assembly-dependent competitors to input cost uncertainty when localization mandates force supply chain restructuring.
Pricing Analysis
Japanese-manufactured vacuum interrupters command substantial premiums over Indian and Chinese equivalents, reflecting JIS C 4603 certification overhead and ceramic envelope quality differentials. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified suppliers from regional assemblers and localized fabricators. Cost compression in the standard tier is intensifying because CEA localization thresholds are pulling assembly capacity into Gujarat and Tamil Nadu corridors. State transmission utilities in India exhibit the highest price sensitivity, while Australian network operators prioritizing predictive diagnostics integration show the least.
Supply Chain Analysis
Port congestion along the Shanghai-Nagoya trade lane elevates inbound logistics costs for ceramic vacuum envelope shipments destined for Southeast Asian assembly plants. Supply concentrates in Japan for critical interrupter components, in India for localized breaker assembly, and in China for copper-chrome contact metallurgy. Manufacturing rests on alumina ceramic substrates, oxygen-free copper, and chrome powder feedstocks. Single-source vulnerability around Japanese captive envelope production exposes regional OEMs to allocation constraints during demand surges. Distribution runs through utility framework agreements and EPC contractor specifications rather than merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific vacuum circuit breaker market is entering a cyclical recovery phase as India's transmission utility modernization programs and China's dual carbon infrastructure replacement create sustained equipment demand.
For Market Incumbents: Consolidate backward integration into ceramic vacuum envelope production to defend margin pools against CEA localization mandates and Japanese supply bottlenecks. Expand captive testing capacity at KERI-affiliated laboratories to compress JIS C 4603 certification timelines for regional market entry. Lock in long-term offtake agreements with Rajasthan and Gujarat solar zone developers before high-density copper-chrome contact formulations commoditize.
For New Entrants and Emerging Players: Lead with digital-hybrid breaker architectures targeting Australia's predictive diagnostics mandate in New South Wales and Victoria distribution networks. Vietnam's EVN tendering pipeline for 24 kV and 36 kV indoor breakers offers the most penetrable geographic entry point. Partner with established Japanese component suppliers for ceramic envelope sourcing rather than attempting greenfield interrupter production.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive vacuum interrupter production and established utility qualification pathways. The five-to-ten year viability window favors suppliers with backward integration into ceramic envelope manufacturing over pure-play assemblers. Watch for inflection signals in Indian PLI scheme capacity utilization rates as a demand-acceleration indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Vacuum Envelope Capacity Expansion | Captive production insulates Mitsubishi Electric from regional technician shortages and supply bottlenecks. |
| Digital-Hybrid Platform Development | Remote monitoring integration opens premium tender categories with Australian network operators. |
| CEA Localization Compliance Investment | Gujarat and Tamil Nadu assembly corridors satisfy India's Make in India power equipment directives. |
| Copper-Chrome Contact Metallurgy Licensing | High-density CrCu 75/25 formulations differentiate suppliers in Rajasthan solar zone tenders. |
| Predictive Diagnostics Service Unbundling | After-sales contracts expand recurring revenue beyond initial breaker hardware sales in Australia. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, vacuum interrupter production engineers, EPC contractor procurement leads, and aftermarket service heads. Secondary validation drew from CEA modernization program disclosures, METI JIS C 4603 standard documentation, Indian PLI scheme administrative records, and utility tender databases. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Across the projection horizon, the analytical framework modeled product type, application, end user, and technology segmentation dimensions with geographic disaggregation at country level. CAGRs were derived from fitted growth curves anchored to disclosed utility capital expenditure plans and renewable interconnection queue data. Forecast inputs incorporated copper-chrome contact metallurgy adoption rates and digital-hybrid breaker penetration assumptions by regulatory jurisdiction.
Forecasts assume regulatory continuity in India's CEA localization regime and Japan's METI certification protocols; material policy shifts would require re-modeling. Supply chain disruption scenarios and technician availability constraints represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
North America Thermal Protector Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Europe Electrical Bushing Market