
 Global Panelboards Market | 2026-2036
Global Panelboards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Panelboards Market Outlook
Copper is restructuring panelboard economics as aluminum busbar designs capture share in cost-sensitive utility and commercial segments. Schneider Electric leverages vertical integration across medium-voltage switchgear to sustain margin pools in premium distribution boards. Siemens anchors European demand through IEC-certified product lines with embedded arc-flash protection. Eaton competes aggressively in North American load centers through channel control with electrical contractors.
Panelboards are electrical distribution assemblies that receive power from transformers and divide it into subsidiary circuits via circuit breakers, fusible switches, or protective relays, typically rated between 120V and 600V with busbar capacities up to 5,000 amperes. Their primary purpose is to protect downstream equipment while enabling localized control and monitoring of electrical flows in buildings and industrial facilities. Switchboards dominate value capture in heavy industrial applications where fault-current ratings and selective coordination requirements command premium pricing. Distribution boards lead volume in residential construction across Asia-Pacific markets where modular DIN-rail designs reduce installation labor. Motor control centers represent the fastest-growing product category as manufacturing automation drives integrated starter-protector demand.
The US National Electrical Code and OSHA arc-flash standards mandate specific panelboard clearances and labeling that elevate product compliance costs while creating barriers for uncertified imports. IEC 61439 standards in Europe and GB standards in China impose divergent short-circuit withstand tests that force manufacturers to maintain region-specific product platforms. Stakeholders must monitor how evolving grid interconnection codes for distributed solar and battery storage reshape overcurrent protection requirements in panelboard specifications.
Market Dynamics
Copper-aluminum hybrid busbar configurations are restructuring cost economics across voltage classes as raw material volatility forces manufacturers to engineer around commodity price swings rather than absorb margin compression.
Growth Catalysts
- Data center power density requirements:Hyperscale facilities in the United States are accelerating procurement of high-amperage switchgear to support AI training clusters exceeding 100MW per building.
- India's grid modernization mandate:The country's Central Electricity Authority standards for smart distribution infrastructure are creating concentrated demand for IEC 61439-compliant distribution boards with integrated monitoring.
- Copper-aluminum hybrid designs:These material innovations are expanding addressable market share in cost-sensitive utility segments previously locked out by pure copper pricing.
Market Restraints
- Raw material cost volatility:Copper price swings exceeding 30% annually are compressing fabrication margins and forcing inventory risk onto distributors.
- Supply concentration in Southeast Asian busbar extrusion:Three countries control 70% of global aluminum busbar capacity, creating geographic vulnerability to trade policy shifts.
- IEC-UL certification divergence:Dual testing requirements for short-circuit withstand and arc-flash containment add 14-18 months to product launch timelines.
Strategic Opportunities
- Battery storage interconnection codes:Evolving IEEE 1547 requirements for distributed solar and storage are reshaping overcurrent protection specifications in commercial panelboards.
- Motor control center integration:Manufacturing automation in Germany and Japan is driving demand for integrated starter-protector assemblies with embedded diagnostics.
- Direct contractor channel bypass:Digital specification platforms are emerging as a procurement alternative to traditional electrical wholesale distribution in North American commercial construction.
Industry Challenges
- Arc-flash engineering specialization:Shortage of certified protection engineers is extending project commissioning timelines for industrial switchboard installations.
- Legacy system integration complexity:Retrofitting smart monitoring into existing 480V distribution infrastructure requires custom busbar modifications that void original equipment warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Panelboards Market |
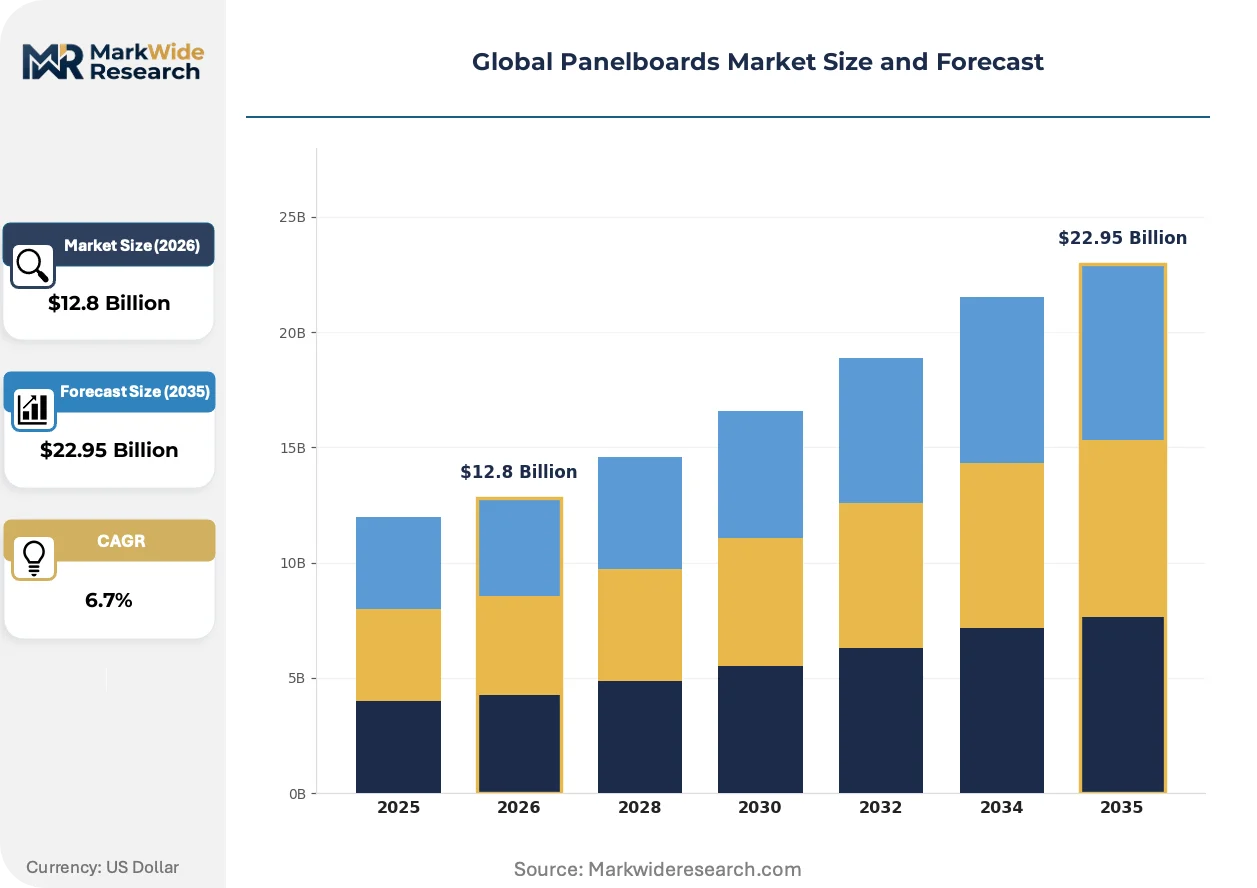
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Load Centers, Distribution Boards, Switchboards, Motor Control Centers Application: Residential, Commercial, Industrial, Utility Installation: Wall-Mounted, Floor-Mounted, Outdoor, Indoor End User: Contractors, OEMs, Maintenance Providers, System Integrators |
| Companies Covered | Schneider Electric, Siemens, ABB, Eaton, General Electric, Mitsubishi Electric, Legrand, Hager Group, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Panelboards Market Strategic Shifts
Digitalization of power distribution is compressing the traditional divide between hardware fabrication and software-enabled energy management, with embedded sensors now standard in premium-tier assemblies.
Copper-aluminum hybrid busbar technology is overtaking pure copper designs in commercial and utility-scale panelboards. These composite conductors reduce material costs by 35-40% while maintaining ampacity ratings through optimized cross-sectional geometry. Data center operators and municipal utilities in Texas and Arizona are specifying hybrid configurations for new 1000A+ installations. The shift is overtaking incumbent pricing models that indexed quotes to LME copper futures.
OSHA arc-flash standards and NEC Article 110.26 clearance mandates are elevating compliance costs for imported panelboards. The regulations require specific working space dimensions and hazard labeling that many Asian manufacturers lack certification to provide. European producers with captive UL testing facilities are capturing share in US commercial construction by pre-certifying entire product families.
Electrical contractors are consolidating specification authority through design-build contracts that bypass traditional engineer-led equipment selection. This channel compression favors manufacturers with direct contractor training programs and same-day configuration tools. The pattern is most visible in US multifamily residential construction where load center procurement now clusters around three national distributor networks.
Global Panelboards Market Segmentation
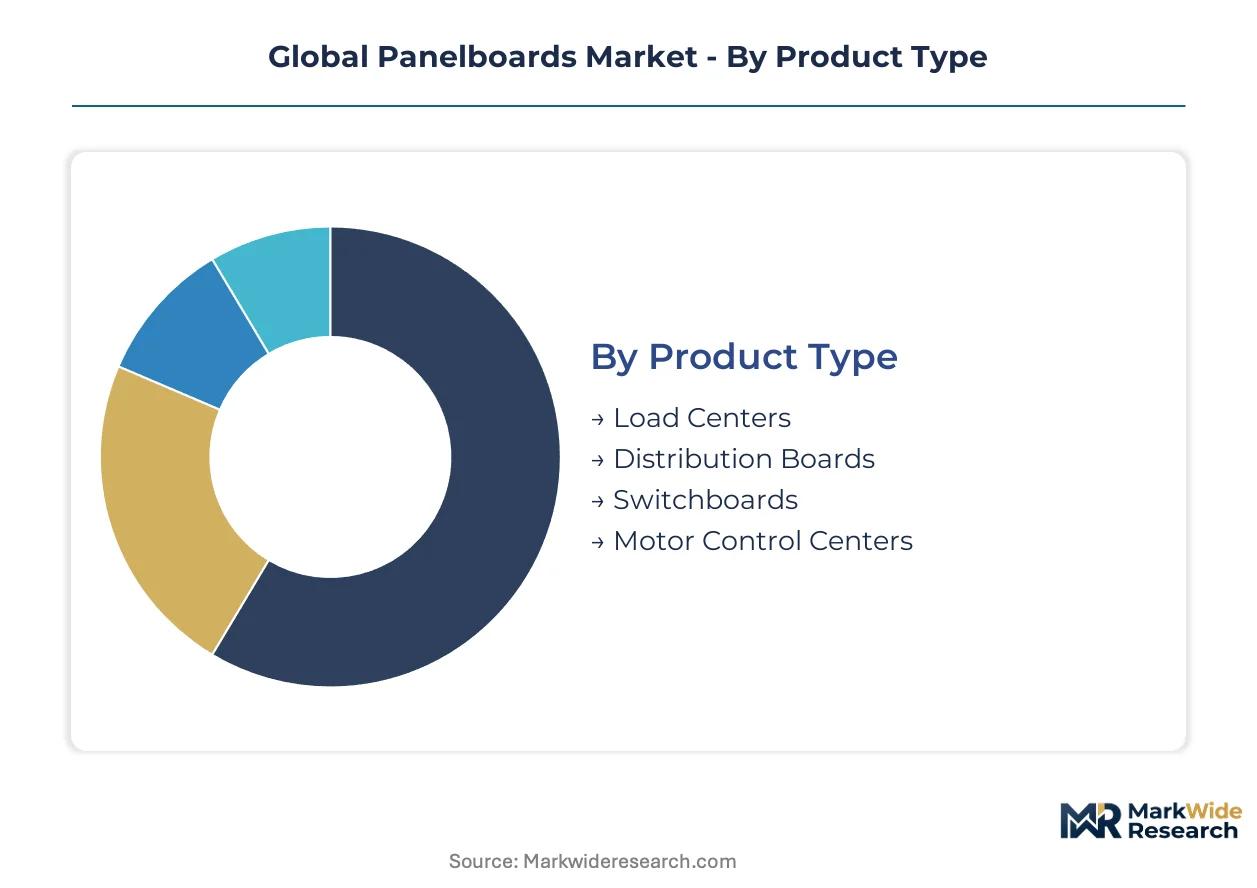
Panelboard segmentation reveals how fabrication economics, installation constraints, and procurement authority fragment addressable value pools across voltage classes and customer types. Manufacturers engineer distinct product architectures for each segment, with busbar materials and enclosure ratings serving as the primary cost-to-performance levers.
Product Type:
Supply concentration in Southeast Asian busbar extrusion forces product-level specialization, with fabricators optimizing around copper-aluminum hybrid designs to hedge commodity exposure.
- Load Centers:Compact residential distribution assemblies rated 100-400A with plug-on circuit breaker compatibility. Demand concentrates in US single-family construction where electrical contractors specify through national distributor networks. Copper-aluminum hybrid busbars are displacing pure copper in cost-sensitive tract housing developments.
- Distribution Boards:Modular DIN-rail assemblies for commercial buildings with integrated metering and surge protection. India's smart city investments and CEA-mandated grid modernization are driving IEC 61439-compliant procurement for urban distribution infrastructure.
- Switchboards:Heavy-industrial assemblies with fault-current ratings exceeding 65kA and selective coordination capabilities. Texas and Arizona data center clusters specify high-amperage configurations for AI training facilities exceeding 100MW per building.
- Motor Control Centers:Integrated starter-protector assemblies with embedded diagnostics for manufacturing automation. Germany and Japan industrial automation investments are expanding addressable demand for these systems.
Today's leader: Distribution Boards. Tomorrow's challenger: Motor Control Centers.
Application:
Cost tier differentiation separates premium-specified industrial installations from price-optimized residential volumes, with commercial buildings occupying the contested middle ground.
- Residential:Volume-driven segment dominated by 120/240V load centers with standard 42-circuit maximum configurations. US multifamily construction channels procurement through consolidated electrical contractor networks.
- Commercial:Mid-tier installations requiring arc-flash compliance and selective coordination per NEC Article 240.87. OSHA-mandated hazard labeling elevates compliance costs for uncertified imports.
- Industrial:Premium fault-current and short-circuit withstand specifications with custom busbar engineering. Selective coordination requirements command engineering-intensive specification processes.
- Utility:Grid-scale distribution infrastructure with extreme temperature and contamination ratings. India's Central Electricity Authority standards are concentrating demand for smart monitoring integration.
Industrial applications command margin premiums. Residential volumes scale fastest in absolute unit terms.
Installation:
Volume concentration favors indoor wall-mounted configurations, while outdoor and floor-mounted designs address specialized environmental and spatial constraints.
- Wall-Mounted:Standard configuration for residential and light commercial applications with space-optimized depth profiles. NEC Article 110.26 working clearance mandates shape enclosure dimensional requirements.
- Floor-Mounted:Freestanding industrial assemblies with segregated busbar compartments for maintenance access. Data center operators in hyperscale facilities specify these for 1000A+ main distribution.
- Outdoor:NEMA 3R/4X-rated enclosures for utility substations and distributed solar interconnection points. Arizona and Texas utilities specify these for extreme temperature cycling.
- Indoor:General-purpose enclosures for climate-controlled commercial and institutional buildings. Standard IEC 60529 IP ratings apply across European installations.
Indoor wall-mounted products dominate unit economics. Outdoor specifications capture scarcity premiums in harsh-climate geographies.
End User:
Procurement authority is shifting from engineer-led specification toward contractor-controlled selection, compressing traditional distribution channels.
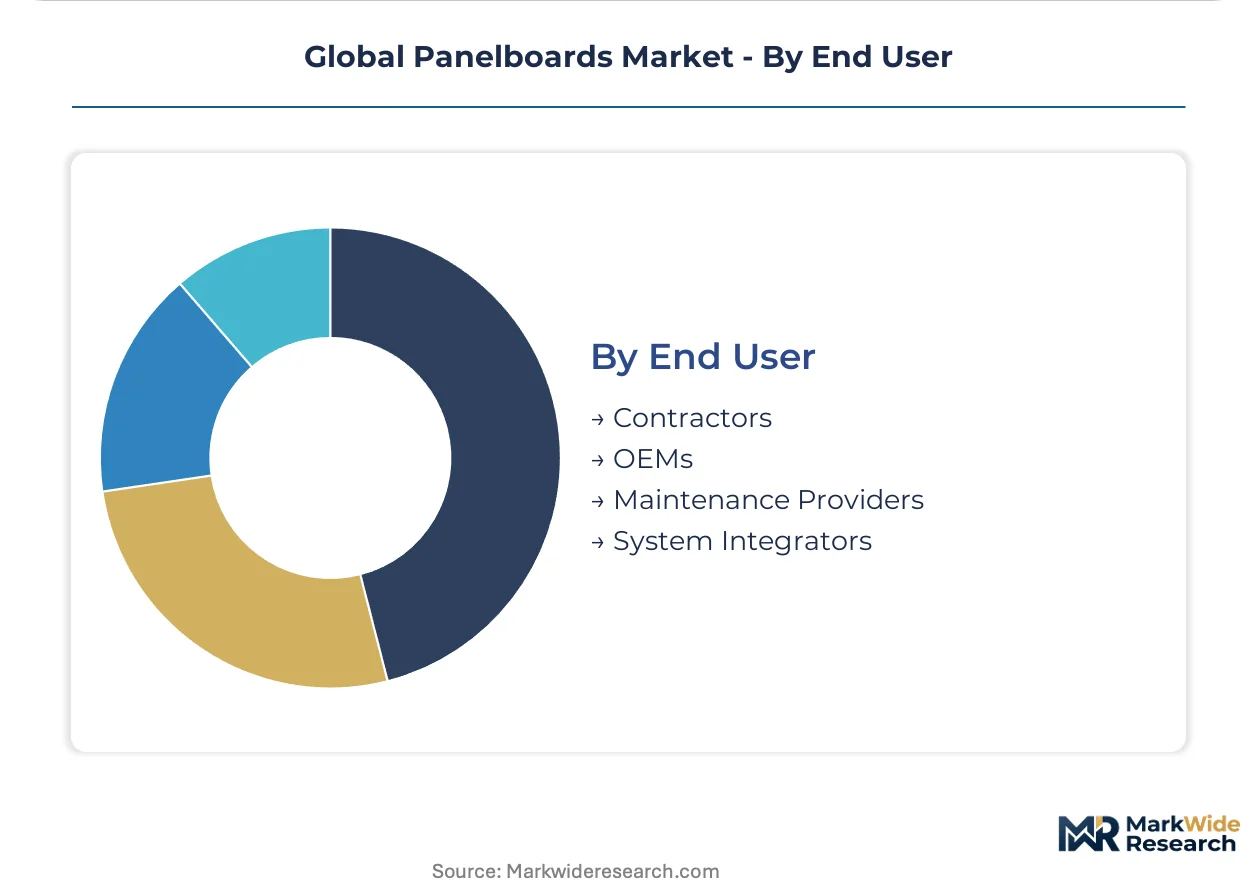
- Contractors:Design-build procurement authority in US commercial and residential construction. Direct training programs and same-day configuration tools determine manufacturer preference.
- OEMs:Original equipment manufacturers integrating panelboards into packaged power systems for industrial machinery and data center infrastructure.
- Maintenance Providers:Retrofit and upgrade demand for legacy 480V distribution infrastructure with smart monitoring integration. Custom busbar modifications often void original equipment warranties.
- System Integrators:Turnkey power distribution projects combining switchgear, automation, and energy management software. IEEE 1547 interconnection code expertise determines competitive positioning.
Contractors consolidate specification control in North America. System integrators capture value in European and Asian industrial automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas data center corridors are commanding high-amperage switchgear procurement volumes as hyperscale operators build 100MW+ AI training facilities. Copper-aluminum hybrid busbar adoption concentrates in cost-sensitive utility segments across multiple voltage classes.
United States
OSHA arc-flash standards and NEC Article 110.26 clearance mandates are elevating compliance costs for imported panelboards. Texas and Arizona utilities specify outdoor NEMA 3R-rated enclosures for extreme temperature cycling at solar interconnection points. Electrical contractors consolidate procurement authority through design-build contracts in multifamily residential construction.
Germany
Industrial automation investments are expanding demand for motor control centers with embedded diagnostics. IEC 61439 short-circuit withstand requirements force region-specific product platform maintenance. Manufacturing clusters in Bavaria and Baden-Württemberg anchor specification activity for integrated starter-protector assemblies.
India
Central Electricity Authority standards for smart distribution infrastructure are creating concentrated demand for IEC 61439-compliant distribution boards. Smart city investments in Delhi-NCR and Mumbai require advanced metering integration in urban distribution networks. Utility grid modernization mandates favor domestic fabricators with captive testing facilities.
China
GB standards impose divergent short-circuit testing protocols that complicate export certification for regional manufacturers. Yangtze River Delta industrial zones concentrate busbar extrusion capacity for aluminum-hybrid designs. Distributed solar interconnection codes under MIIT oversight are reshaping overcurrent protection specifications in commercial installations.
Japan
METI industrial efficiency programs are accelerating motor control center deployment in precision manufacturing. Kanto and Kansai metropolitan areas concentrate specification authority for embedded diagnostic systems. JIS standards for arc-flash containment create technical barriers for non-domestic suppliers in premium industrial segments.
Global Panelboards Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers add captive busbar extrusion lines to hedge raw material volatility. The vendor base stratifies across three tiers: integrated electrical conglomerates with full voltage-class coverage, regional specialists focused on DIN-rail modular designs, and contract fabricators serving utility procurement. Strategic archetypes include backward-integrated material processors, software-enabled energy management platforms, and channel-optimized construction suppliers. M&A activity concentrates in Southeast Asian busbar capacity, while technology licensing agreements proliferate for arc-flash simulation software.
Among European-based industrial electrical suppliers, Schneider Electric, Siemens, and ABB occupy positions spanning premium switchgear through standardized distribution boards. These conglomerates exemplify the integrated archetype through captive supply chains and multi-standard certification portfolios. Eaton and Legrand represent North American and French channel-optimized positioning respectively, with specification tools targeting electrical contractor networks. Mitsubishi Electric anchors Japanese industrial automation integration, while Larsen & Toubro exemplifies emerging market domestic champions with utility-scale project execution capabilities.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| Eaton |
| General Electric |
| Mitsubishi Electric |
| Legrand |
| Hager Group |
| Larsen & Toubro |
| Others |
Value Chain & Pricing Dynamics
Electrical contractor consolidation in North American design-build procurement anchors the dominant pricing model. Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service bundling.
Pricing Analysis
Copper and aluminum LME price pass-through mechanisms dominate commercial negotiations. Premium-mid-economy pricing differentiation separates UL-certified industrial switchboards from IEC-compliant commercial distribution boards from uncertified economy load centers. Cost compression in economy residential tiers is intensifying because tract housing developers index quotes to spot copper futures. Utility procurement teams exhibit lowest price sensitivity due to total-cost-of-ownership engineering mandates.
Supply Chain Analysis
Busbar extrusion capacity rests on Vietnam, Malaysia, and Thailand for aluminum-hybrid designs. Copper rod supply draws from Chilean mining operations and Chinese smelters. Insulation compounds and molded case breaker components hinge on Japanese and German specialty chemical producers. Tariff exposure on Southeast Asian aluminum extrusions creates margin vulnerability for US-bound shipments. Distribution runs through consolidated electrical wholesale networks in North America and direct OEM supply agreements in European industrial automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA arc-flash compliance costs in the United States exceed IEC testing burdens in Germany by approximately 40%, creating arbitrage opportunities for European producers with captive UL facilities.
For Market Incumbents: Hedge raw material volatility through captive copper-aluminum hybrid extrusion lines in Southeast Asia. Defend against emerging Asian contract fabricators by pre-certifying entire product families at UL testing facilities. Channel control through electrical contractor training programs remains the critical lever in North American residential construction. For New Entrants and Emerging Players: A 35-40% price-point gap between premium Schneider Electric switchgear and economy Chinese load centers opens white-space in mid-tier commercial distribution boards. Target India's Central Electricity Authority-mandated smart city infrastructure where domestic testing capabilities create procurement preferences. Deploy digital specification platforms to bypass traditional wholesale distribution channels in US commercial construction. For Investors and Strategic Acquirers: Electrical conglomerates with full voltage-class coverage are the most active acquirers in this space. The five-to-ten year viability window favors targets with captive Southeast Asian busbar capacity and multi-standard certification portfolios. Watch copper-aluminum hybrid adoption rates in Texas and Arizona data center corridors as inflection indicators for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Busbar Extrusion Capacity | Southeast Asian aluminum-hybrid lines hedge LME copper volatility for margin stability. |
| Multi-Standard Certification Investment | Simultaneous UL and IEC testing reduces product launch timelines by 14-18 months. |
| Digital Specification Platform Launch | Direct contractor channel bypass disrupts traditional electrical wholesale distribution. |
| Smart Monitoring Integration | Embedded sensor architectures capture value in India's CEA-mandated grid modernization. |
| Arc-Flash Simulation Licensing | Software-enabled protection engineering addresses certified engineer shortage constraints. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each. The analysis combines interviews with electrical contractors, utility procurement officers, OEM power system engineers, and busbar fabrication plant managers with secondary validation from EIA electrical infrastructure data, IEC certification registries, SEC 10-K filings of listed electrical conglomerates, and Indian Central Electricity Authority smart grid directives. Bottom-up project pipeline analysis and top-down installed base estimates triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models panelboard demand by product type, voltage class, installation configuration, and end-user procurement authority. CAGRs derive from segment-level growth rate blending and cross-elasticity analysis against copper price cycles and data center construction permits.
Caveats apply where raw material price spikes or trade policy shifts could materially shift the outlook. Forecasts reflect assumptions about continued data center investment velocity and smart city execution timelines in India. A small set of triggers—copper-aluminum hybrid technology substitution rates, IEEE 1547 interconnection code revisions, and Southeast Asian trade policy changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Contactors Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Busbar Systems Market