
 North America Commercial Lighting Control Market | 2026-2036
North America Commercial Lighting Control Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Lighting Control Market Insights
Healthcare facility retrofit demand is hardening as hospitals prioritize circadian lighting protocols and infection-control-compatible automation. Leviton Manufacturing Co Inc leverages its extensive electrical wiring device portfolio to anchor retrofit projects across aging medical infrastructure. Signify Holding competes through its Interact platform, which sustains deep integration with building management systems. Lutron Electronics Co Inc dominates the premium specification channel through proprietary wireless protocols and commissioning services.
Commercial lighting control encompasses networked and standalone systems that modulate artificial illumination intensity, timing, and spectral output based on occupancy patterns, daylight availability, or programmed schedules. DALI-enabled architectures support individual addressability across luminaire groups down to single-fixture granularity, while Bluetooth mesh deployments reduce infrastructure dependency through self-healing node topologies. Smart lighting solutions are capturing the fastest expansion trajectory as software-defined functionality displaces hardware-centric legacy architectures. Wi-Fi-based technology segments retain substantial installed base volume but face margin compression from chipset commoditization.
The US Department of Energy enforces federal minimum efficiency standards through its Appliance and Equipment Standards Program, while California's Title 24 Building Energy Efficiency Standards mandate automatic daylight dimming and occupancy-based shutoff in commercial construction. Canada's Natural Resources Office administers the Energy Efficiency Regulations that align provincial adoption with federal performance benchmarks. Stakeholders must monitor evolving interoperability certification requirements between wireless protocols as procurement specifications increasingly demand open-system compatibility rather than proprietary lock-in.
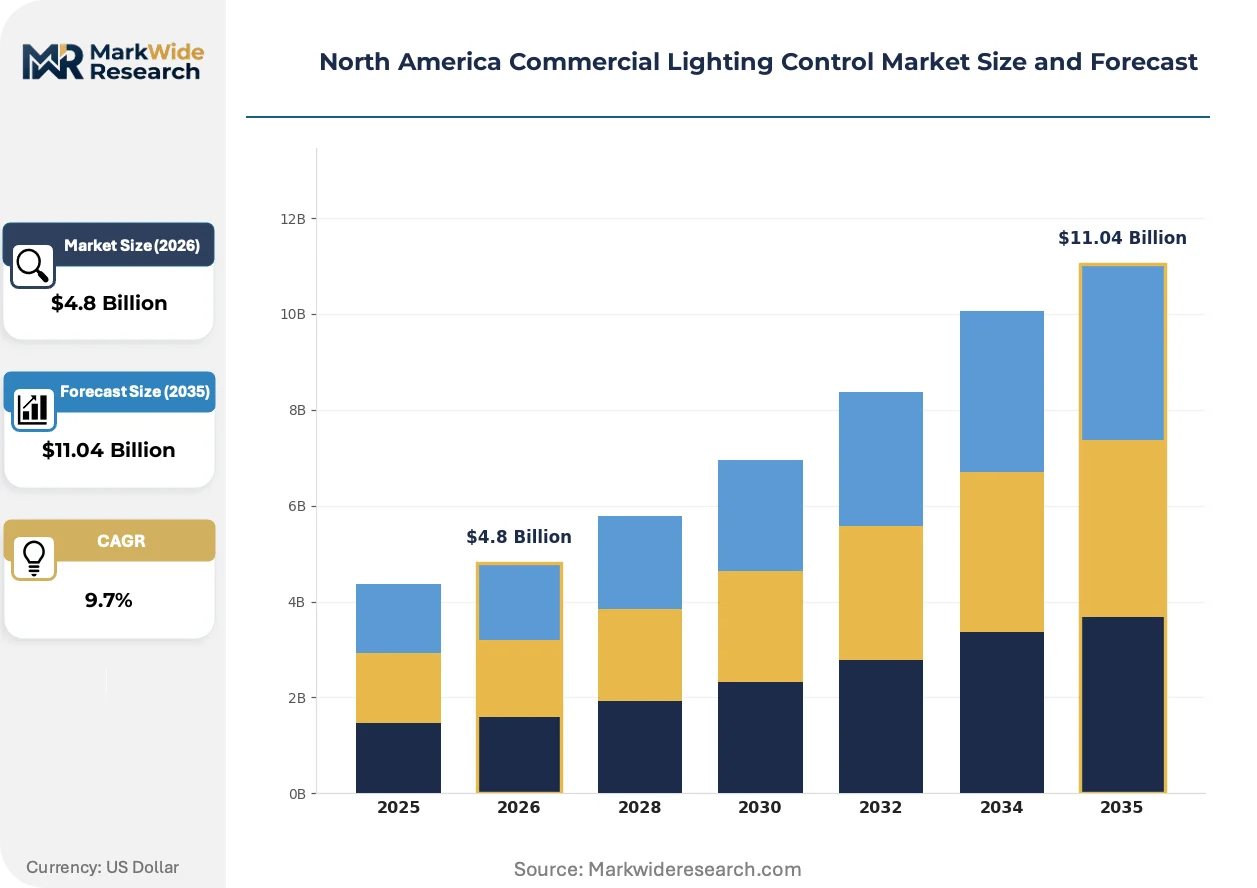
Market Dynamics
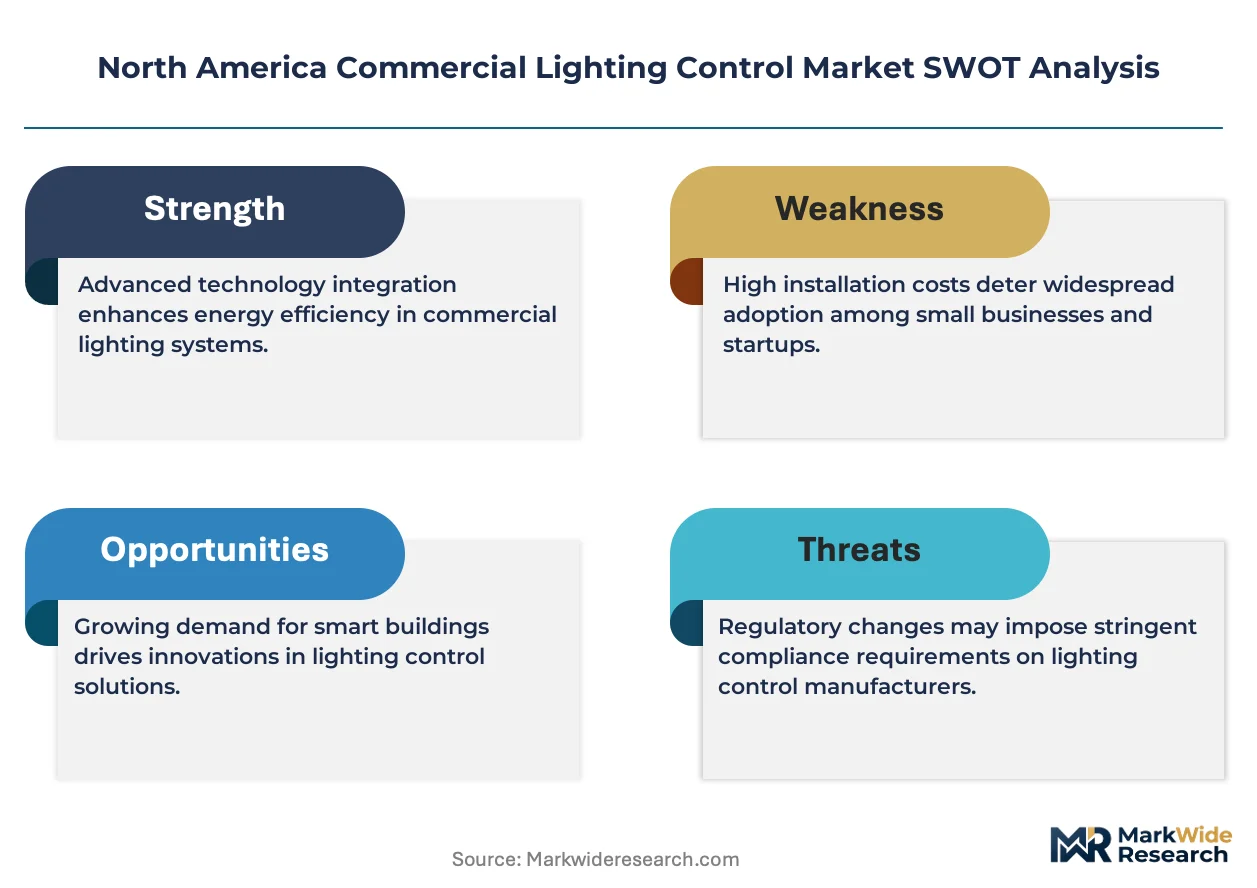
Software-defined lighting architectures are compressing hardware margins while forcing incumbent suppliers to rebuild revenue models around recurring platform fees and data services. This structural shift is redistributing value capture from fixture manufacturers toward control system integrators and building analytics providers.
Growth Catalysts
- California Title 24 mandates:Automatic daylight dimming and occupancy shutoff requirements in commercial construction are creating baseline demand for networked control systems across new build and major renovation projects.
- Healthcare circadian protocols:Hospital systems are retrofitting patient rooms and clinical corridors with tunable white systems to support staff alertness and patient recovery metrics tied to reimbursement quality scores.
- Bluetooth mesh topologies:Self-healing wireless node architectures are reducing infrastructure dependency in historic buildings and fast-track tenant improvement projects where conduit runs face logistical constraints.
Market Restraints
- Silicon supply concentration:Dependence on Taiwanese and South Korean semiconductor foundries for wireless chipsets creates vulnerability to geopolitical disruption and allocation constraints during demand spikes.
- Copper and aluminum input volatility:Luminaire housing and conductor materials face commodity price swings that compress gross margins when long-dated construction contracts lock in fixed pricing.
- Legacy DALI incompatibility:Existing two-wire installations lack power-over-data capability, forcing expensive rewiring or gateway devices that fragment network management and degrade reliability.
Strategic Opportunities
- Texas metropolitan corridor:Dallas-Fort Worth and Houston commercial construction pipelines are outpacing national averages, creating concentrated demand for specification-grade control systems in Class A office and mixed-use developments.
- Utility demand response integration:Aggregated lighting load curtailment programs in Ontario and several US ISO territories offer recurring revenue streams for networked system operators with grid-interactive capabilities.
- Power-over-Ethernet convergence:IT infrastructure convergence with low-voltage lighting distribution is opening specification channels through data center contractors and structured cabling specialists previously outside traditional electrical channels.
Industry Challenges
- Commissioning technician scarcity:Qualified professionals capable of programming networked sequences and tuning daylight harvesting algorithms command wage premiums that extend project timelines and inflate soft costs.
- Interoperability certification delays:Multi-protocol verification against DALI-2, Zigbee, and Matter specifications stretches product release cycles and fragments R&D investment across competing standardization tracks.
- Existing building automation integration:BACnet and Modbus protocol translation introduces latency and failure points when lighting networks must coordinate with legacy HVAC and security systems in institutional retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Lighting Control Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimmer Switches, Occupancy Sensors, Photocells, Smart Lighting Technology: Wi-Fi, Zigbee, Bluetooth, DALI Application: Office Spaces, Retail Outlets, Hospitality, Warehouses End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Others |
| Companies Covered | Leviton Manufacturing Co Inc, ams-Osram International GmbH, Signify Holding, Hubbell Incorporated, Schneider Electric, Acuity Brands Inc., Eaton Corporation, Cree Lighting, Lutron Electronics Co Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Lighting Control Market Trends and Innovations
Spectral tunability and embedded sensing are converging to transform lighting networks into distributed building intelligence platforms. This evolution is compressing the traditional separation between illumination infrastructure and operational technology systems.
Li-Fi optical wireless communication is integrating infrared and visible light spectrum for high-bandwidth data transmission in electromagnetic-sensitive environments. Defense contractors and healthcare imaging facilities are piloting installations where radio-frequency restrictions prevent Wi-Fi deployment. The technology is integrating building communications backbone functions into existing luminaire density, displacing parallel infrastructure investment.
The US Department of Energy Appliance and Equipment Standards Program is tightening federal minimums for commercial luminaire control efficacy. Manufacturers must redesign driver architectures to meet standby power limits while maintaining dimming performance across full output ranges. The regulation is compressing SKU proliferation as engineering resources concentrate on compliant platform designs rather than regional variant optimization.
Facility managers are unbundling after-sales service contracts from initial equipment procurement, selecting third-party commissioning and maintenance providers based on software platform expertise rather than hardware brand loyalty. This behavior is fragmenting specification influence and elevating independent system integrators in multi-vendor environments. The shift is most visible in California and New York where complex Title 24 and Local Law 97 compliance requirements favor specialized service relationships over traditional manufacturer-direct support models.
North America Commercial Lighting Control Market Segmentation
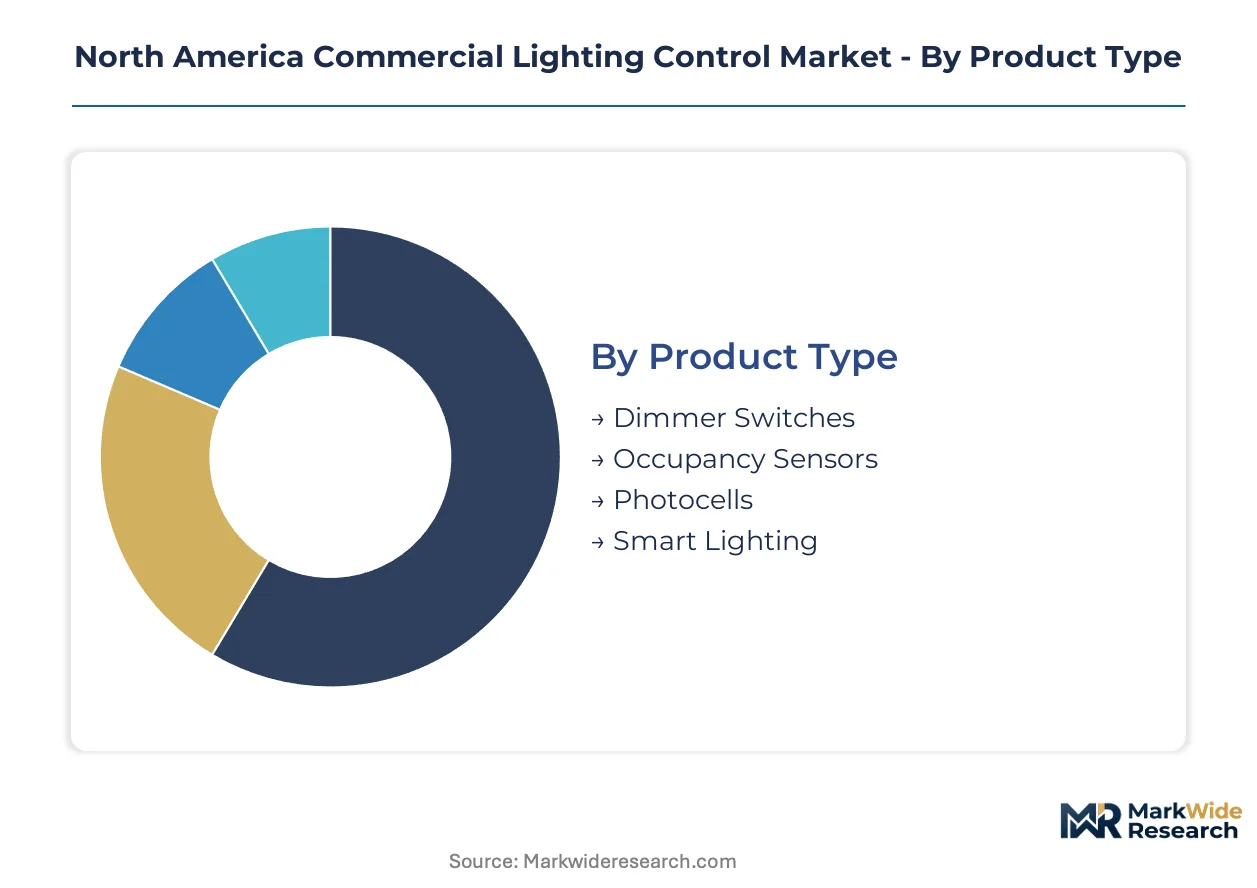
Segmentation in commercial lighting controls reveals how procurement specifications fragment across regulatory jurisdictions, building vintages, and integration complexity. Understanding these divides exposes where specification influence concentrates and which technology transitions command premium positioning.
Product Type:
Customization intensity varies from commodity wall-box devices to fully programmable networked systems requiring commissioning services.
- Dimmer Switches:Wall-mounted phase-cut or 0-10V controllers provide manual or preset intensity adjustment. Demand concentrates in California Title 24 retrofits where automatic daylight dimming mandates drive replacement cycles in aging commercial stock.
- Occupancy Sensors:Passive infrared, ultrasonic, and dual-technology detectors trigger automatic shutoff based on motion detection. Texas metropolitan corridor construction pipelines absorb specification-grade units with integrated daylight harvesting for Class A office developments.
- Photocells:Ambient light sensors enable open-loop and closed-loop daylight harvesting algorithms.
- Smart Lighting:Networked luminaire-level controllers with embedded processing and wireless backhaul.
Leading the category by volume: Dimmer Switches. Expanding most quickly: Smart Lighting.
Technology:
Margin profiles diverge sharply between proprietary wireless stacks and standardized wired protocols with certification overhead.
- Wi-Fi:IP-native connectivity leveraging existing enterprise infrastructure for lighting control backhaul. Chipset commoditization compresses hardware margins while IT channel convergence opens specification pathways through data center contractors.
- Bluetooth:Mesh topologies with self-healing node architectures reduce infrastructure dependency. Historic building retrofits and fast-track tenant improvements favor deployments where conduit runs face logistical constraints.
- Zigbee:Low-power IEEE 802.15.4 mesh networking with established building automation interoperability.
- DALI:Two-wire digital addressable lighting interface enabling individual fixture control and status feedback.
Dominant by installed base: DALI. Gaining share fastest: Bluetooth.
Application:
Building type determines code compliance burden and integration depth with parallel building systems.
- Office Spaces:Open-plan and private office configurations requiring occupancy-based shutoff and daylight harvesting. California and New York jurisdictions drive specification-grade networked systems where Local Law 97 and Title 24 carbon compliance intensify automation requirements.
- Retail Outlets:Merchandise display and circulation lighting with extended operating hours. National retail chains prioritize standardized commissioning protocols across portfolio rollouts to reduce technician dependency.
- Hospitality:Guest room and public space controls balancing aesthetic flexibility with operational efficiency.
- Warehouses:High-bay industrial facilities with intermittent occupancy patterns and minimal daylight access.
Highest specification intensity: Office Spaces. Steepest retrofit activity: Hospitality.
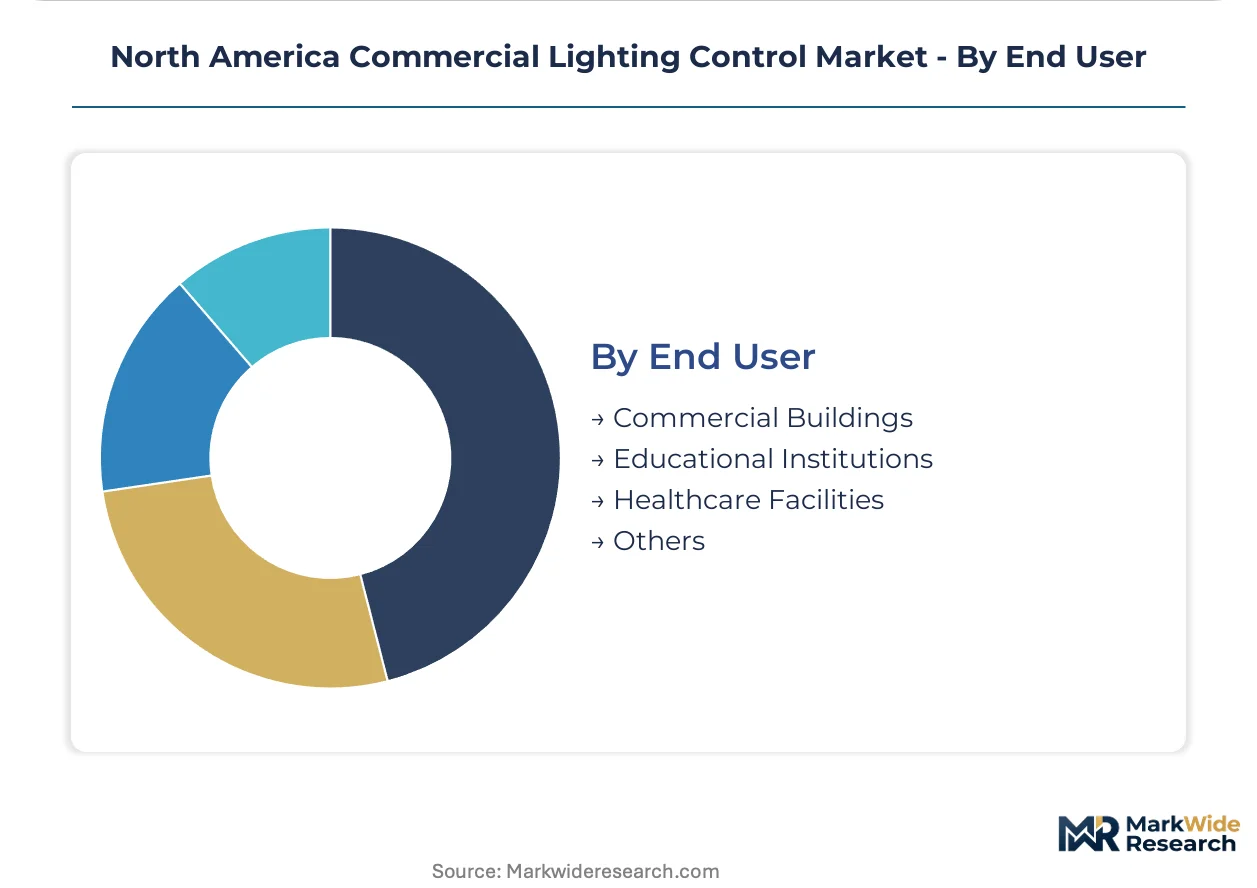
End User:
Procurement authority and technical sophistication vary from institutional facilities managers to decentralized educational purchasing.
- Commercial Buildings:Class A office, mixed-use, and corporate campus developments with professional facilities management. Utility demand response program enrollment in Ontario and select US ISO territories creates recurring revenue opportunities for grid-interactive system operators.
- Healthcare Facilities:Hospitals and outpatient clinics requiring circadian lighting protocols and infection-control-compatible automation. Patient room retrofits concentrate specification demand for tunable white systems tied to reimbursement quality metrics.
- Educational Institutions:K-12 and university campuses with constrained capital budgets and extended equipment lifecycles.
- Others:Government, religious, and cultural facilities with specialized preservation or security requirements.
Largest absolute spend: Commercial Buildings. Fastest protocol adoption: Healthcare Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Title 24 incentive zones concentrate specification-grade demand across the Western United States, while Texas metropolitan expansion and Canadian provincial efficiency programs create complementary growth corridors.
United States
California's Title 24 Building Energy Efficiency Standards mandate automatic daylight dimming and occupancy-based shutoff in commercial construction, driving baseline demand for networked control systems. The US Department of Energy enforces federal minimum efficiency standards through its Appliance and Equipment Standards Program. Dallas-Fort Worth and Houston commercial construction pipelines absorb specification-grade occupancy sensors with integrated daylight harvesting for Class A office developments.
Canada
Ontario's utility demand response programs create recurring revenue opportunities for networked system operators with grid-interactive capabilities. Natural Resources Canada administers the Energy Efficiency Regulations that align provincial adoption with federal performance benchmarks. Toronto and Vancouver commercial retrofits concentrate procurement for tunable white systems in healthcare facilities.
California
Healthcare facility retrofit demand hardens as hospitals prioritize circadian lighting protocols and infection-control-compatible automation. The California Energy Commission enforces Title 24 standards that exceed federal minimums. Los Angeles and San Francisco Bay Area jurisdictions drive specification-grade networked systems where carbon compliance intensifies automation requirements.
Texas
Fast-track tenant improvement projects favor Bluetooth mesh deployments where conduit runs face logistical constraints. The Public Utility Commission of Texas oversees demand response program frameworks. Houston and Austin metropolitan corridors absorb high volumes of smart lighting controllers in mixed-use developments.
New York
Local Law 97 carbon compliance requirements favor specialized service relationships over traditional manufacturer-direct support models. The New York State Energy Research and Development Authority administers efficiency incentive programs. New York City commercial buildings drive specification intensity for office space controls with extended operating hours.
North America Commercial Lighting Control Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with electrical infrastructure incumbents commanding retrofit channels and software-defined platforms capturing new construction specifications. Market structure tilts toward consolidation among diversified industrial conglomerates with captive distribution networks. Three archetypes dominate: wiring device specialists with retrofit anchoring capability, premium specification houses with proprietary wireless protocols, and diversified electrical conglomerates with building automation integration. Competitive moves center on platform licensing agreements and vertical integration into commissioning services.
Among diversified electrical conglomerates, Schneider Electric, Eaton Corporation, and Acuity Brands Inc. occupy positions that exemplify the building automation integration archetype. These entities represent the scale-driven end of competitive positioning, leveraging existing electrical distribution relationships to bundle lighting controls with broader power management portfolios. Their market presence anchors specification influence across multi-trade construction projects where single-source accountability reduces procurement complexity.
| Leading Market Players |
|---|
| Leviton Manufacturing Co Inc |
| ams-Osram International GmbH |
| Signify Holding |
| Hubbell Incorporated |
| Schneider Electric |
| Acuity Brands Inc. |
| Eaton Corporation |
| Cree Lighting |
| Lutron Electronics Co Inc |
| Others |
Pricing and Supply Chain Analysis
Commissioning technician scarcity in California and Texas metropolitan corridors drives labor-cost differentials that widen pricing-tier spreads between specification-grade networked systems and commodity wall-box devices.
Pricing Analysis
Short lead-time premiums separate emergency replacement orders from standard project scheduling, with California Title 24 compliance deadlines compressing procurement windows. Three-tier pricing structure across premium specification-grade, standard networked, and economy standalone levels reflects certification grade and after-sales service bundling. Pricing pressure stems from silicon chipset commoditization in Wi-Fi segments. Educational institutions exhibit highest price sensitivity due to constrained capital budgets, while healthcare facilities prioritize infection-control compatibility over unit cost.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Los Angeles anchor hub-and-spoke patterns serving Texas metropolitan corridor and California Title 24 jurisdictions. Taiwan and South Korean semiconductor foundries supply wireless chipsets, while Chinese and Mexican facilities produce luminaire housings. Copper and aluminum conductor materials draw from Chilean and Australian mining operations. Single-source vulnerability concentrates in Taiwanese foundry capacity for Bluetooth mesh controllers. Distribution runs through electrical wholesale channels and emerging IT infrastructure contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where control over commissioning services and software platform licensing determines long-term margin capture.
For Market Incumbents: Acquire commissioning service capabilities to anchor retrofit project influence against independent system integrators fragmenting specification authority. Build captive supply of DALI-2 certified drivers to reduce exposure to semiconductor allocation constraints from Taiwanese foundries. Consolidate backward integration into sensor manufacturing to defend margin position against silicon commoditization.
For New Entrants and Emerging Players: Begin with Bluetooth mesh deployments in historic building retrofits where conduit constraints exclude incumbent wired protocols. Target fast-track tenant improvement projects in Houston and Austin where infrastructure-light wireless topologies reduce installation barriers. Partner with structured cabling specialists to access data center contractor channels outside traditional electrical distribution.
For Investors and Strategic Acquirers: Re-rating potential sits with software-defined platform specialists given utility demand response integration creating recurring revenue streams. Long-term viability favors operators with grid-interactive capabilities and open-protocol interoperability certification. Acquisition target archetype: commissioning services firms with California Title 24 expertise. Signal to watch: utility program enrollment rates in Ontario and Texas ISO territories as inflection indicator for platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Interact platform integration with BACnet building management systems captures specification influence in institutional retrofits. |
| Acquisition of Specialist Firm | Commissioning services acquisitions consolidate project control against independent integrators fragmenting manufacturer-direct relationships. |
| Strategic Partnership | Utility demand response partnerships in Ontario and Texas ISO territories establish recurring revenue streams for grid-interactive operators. |
| Geographic Expansion | Dallas-Fort Worth and Houston corridor expansion captures specification-grade demand outpacing national construction averages. |
| Product Launch | Tunable white system launches target healthcare circadian lighting protocols tied to reimbursement quality metrics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with lighting controls specification engineers, electrical contractor procurement leads, healthcare facilities managers, and utility demand response program officers provided qualitative validation. Secondary sources included US Department of Energy Appliance Standards Program documentation, California Energy Commission Title 24 compliance databases, Natural Resources Canada efficiency regulations, and electrical distribution channel shipment records. Bottom-up and top-down triangulation cross-validated segment-level estimates against aggregate market construction.
Granularity-level modeling addressed product type, technology protocol, application building category, and end-user procurement authority across the analysis window. Segmentation dimensions included networked versus standalone architecture, DALI-2 versus Bluetooth mesh versus Wi-Fi connectivity, office versus healthcare versus retail deployment, and institutional versus commercial building ownership. CAGRs derived from trend extrapolation of regulatory mandate adoption curves and construction pipeline data. Forecast inputs incorporated semiconductor allocation constraints and copper price volatility assumptions.
Underlying measurement precision varies by segment; California and Texas metropolitan corridor estimates carry tighter precision than Canadian provincial breakdowns due to regulatory filing density. Forecasts reflect documented assumptions regarding Title 24 enforcement continuity and utility program enrollment trajectories. Geopolitical disruption to Taiwanese foundry capacity represents specific risk factor warranting scenario sensitivity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
North America Thermal Protector Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Electrical Enclosures Market