
 Electric Motors for Conveyor System Market | 2026-2036
Electric Motors for Conveyor System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motors for Conveyor System Market Foresight
E-commerce fulfillment is realigning procurement priorities across the electric motor supply chain for conveyor systems. ABB Group leverages its integrated drive-motor portfolio to capture retrofit opportunities in automated distribution centers. Siemens AG anchors European demand through its SIMOTICS platform optimized for continuous-duty conveyor applications. Bonfiglioli Riduttori S.p.A specializes in compact gearmotor configurations that dominate intralogistics installations with space constraints.
Electric motors for conveyor systems are electromechanical devices that convert electrical energy into mechanical rotation, typically specified by continuous duty cycles, IP55 or higher enclosure ratings, and torque profiles matched to belt loading conditions. These motors power material handling equipment across manufacturing floors, distribution hubs, and processing facilities where reliable speed control determines throughput consistency. AC motors retain the largest installed base due to their durability and compatibility with variable frequency drive control methods, while servo motors are gaining share in high-precision sortation and indexing applications where exact positioning determines system efficiency. The food processing end user segment commands premium pricing for stainless steel and washdown-rated configurations that satisfy sanitary design requirements.
The US Department of Energy enforces minimum energy performance standards that disqualify lower-efficiency motor classes from new conveyor installations, while the EU Ecodesign Directive and CE marking requirements under the Machinery Directive shape product architecture for equipment sold into European markets. China's GB standards through SAMR establish efficiency tiers that influence sourcing decisions for motors deployed in domestic logistics infrastructure expansion. Stakeholders must monitor how evolving efficiency regulations interact with total cost of ownership calculations as motor replacement cycles accelerate in energy-intensive conveyor operations.
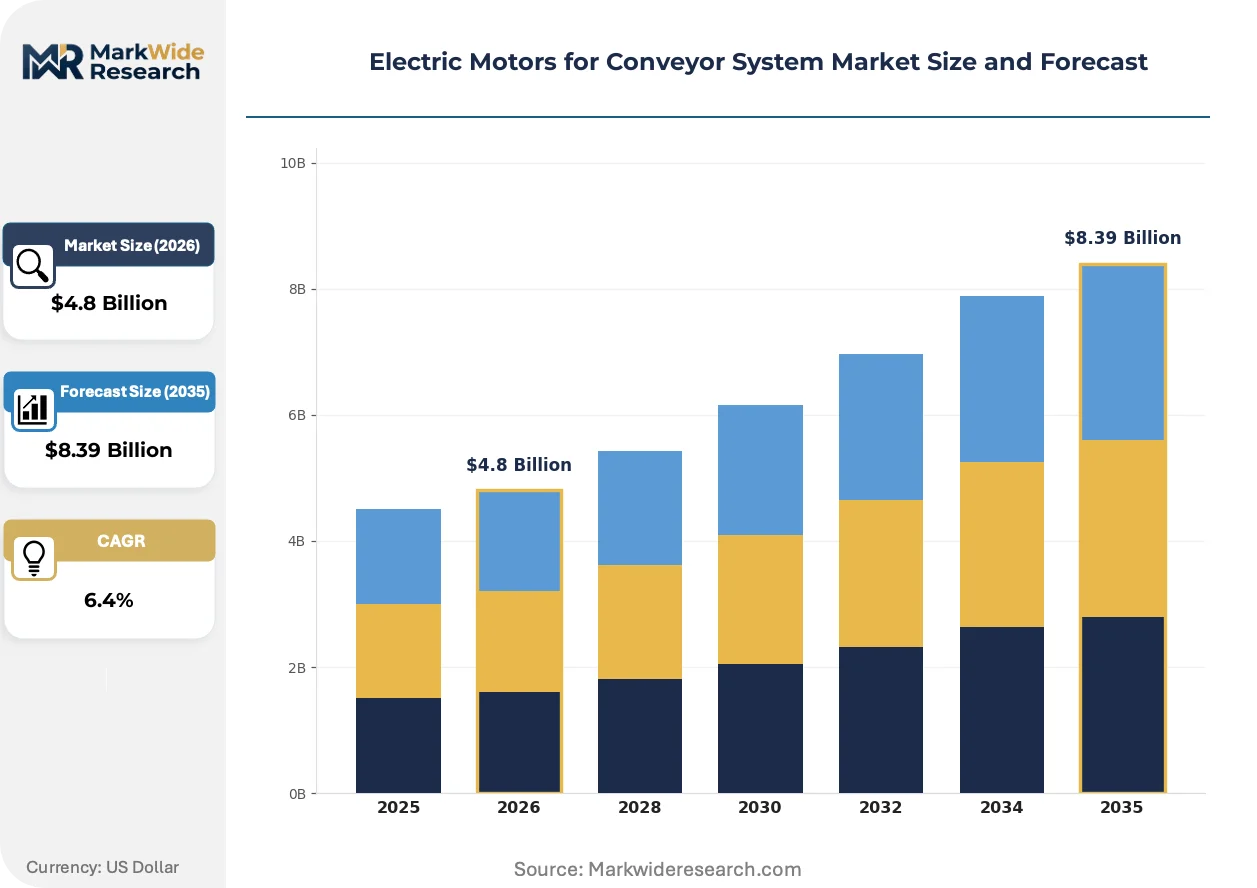
Market Dynamics
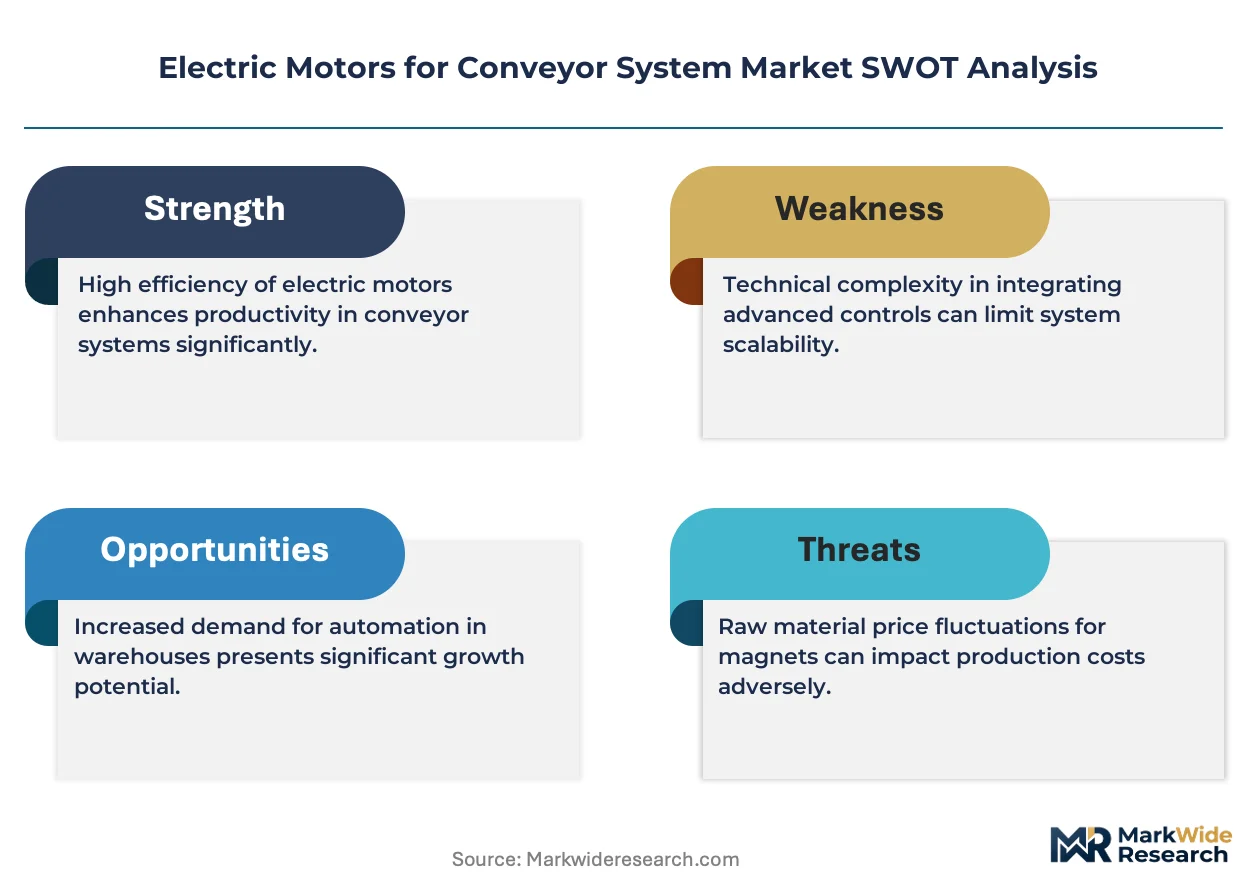
Energy efficiency mandates from the US Department of Energy and the EU Ecodesign Directive are forcing accelerated replacement cycles across installed conveyor motor bases, compressing payback calculations and favoring premium-efficiency platforms over standard-duty alternatives.
Growth Catalysts
- E-commerce fulfillment expansion:Automated sortation systems in distribution centers are pulling continuous-duty motor procurement toward higher torque-density specifications. Demand concentrates in facilities processing parcel volumes exceeding one million units daily.
- EU Ecodesign Directive:The regulation's tiered efficiency requirements are disqualifying IE2 and lower motor classes from new installations across European material handling infrastructure.
- Food processing sanitation standards:Washdown-rated stainless steel motor configurations are commanding premium positioning as FDA and USDA sanitary design requirements tighten in protein processing and dairy operations.
Market Restraints
- Copper and rare earth price volatility:Permanent magnet motor production faces input cost pressure from neodymium supply concentration in Chinese processing facilities.
- IE4 and IE5 efficiency premium:The capital cost differential between premium-efficiency and standard-efficiency platforms extends payback periods beyond acceptable thresholds for small and mid-sized conveyor operators.
- AC induction motor installed base inertia:Decades of durable legacy equipment deployment creates replacement resistance despite variable frequency drive compatibility advantages in newer platforms.
Strategic Opportunities
- India logistics infrastructure buildout:The country's warehouse automation penetration remains below comparable Asian economies, creating white space for gearmotor suppliers targeting cold chain and pharmaceutical distribution.
- Servo-conveyor convergence:Precision indexing applications in pharmaceutical packaging and electronics assembly are drawing servo motor architectures into conveyor zones previously served by AC induction platforms.
- US Inflation Reduction Act efficiency incentives:Tax credits for industrial equipment upgrades are accelerating retrofit timelines in energy-intensive bulk material handling operations.
Industry Challenges
- Variable frequency drive commissioning expertise:The gap between motor supply and qualified field service capacity is extending startup timelines and degrading efficiency realization in complex multi-zone conveyor systems.
- Cross-jurisdictional certification burden:CE marking under the EU Machinery Directive, UL listing for North American deployment, and CCC compliance for Chinese installations create parallel testing requirements that compress margin structures for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motors for Conveyor System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Motors, DC Motors, Servo Motors, Stepper Motors Power Rating: Low Power, Medium Power, High Power, Custom Power Control Method: Variable Frequency Drive, Direct On-Line, Soft Starter, Open Loop End User: Manufacturing, Warehousing, Food Processing, Pharmaceutical |
| Companies Covered | Bodine Electric Company, Bonfiglioli Riduttori S.p.A, ABB Group, Power Electric, Altra Industrial Motion, Siemens AG, Oriental Motor U.S.A. Corp, Regal Rexnord Corporation, Nord Gear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motors for Conveyor System Market Shifts & Advancements
Digitalization of motor control architectures and predictive maintenance integration are reshaping how conveyor operators specify and procure electromechanical powertrains, shifting value capture toward software-enabled service models.
Permanent magnet synchronous motors are expanding into high-duty-cycle conveyor applications previously dominated by AC induction architectures. Cold storage and refrigerated distribution facilities are adopting these platforms for their superior partial-load efficiency. The technology is expanding into retrofit markets as operators face compressed energy payback requirements under utility demand-response programs.
The EU Ecodesign Directive's 2023 efficiency tier updates are mandating IE4 minimums for motors in the 75-200 kW range deployed across European manufacturing and logistics infrastructure. Industrial buyers are responding by consolidating procurement around integrated motor-drive packages that guarantee system-level efficiency certification. Food processing and pharmaceutical handling operations face the steepest compliance timelines due to their reliance on continuous-duty washdown-rated equipment.
Buying organizations are unbundling motor procurement from conveyor OEM supply agreements, establishing direct relationships with ABB, Siemens, and specialized gearmotor suppliers for lifecycle cost optimization. Large e-commerce fulfillment operators are leading this disintermediation, leveraging volume concentration to negotiate extended warranty and predictive maintenance provisions. Germany and the United States host the most advanced examples of this procurement model evolution.
Electric Motors for Conveyor System Market Segmentation
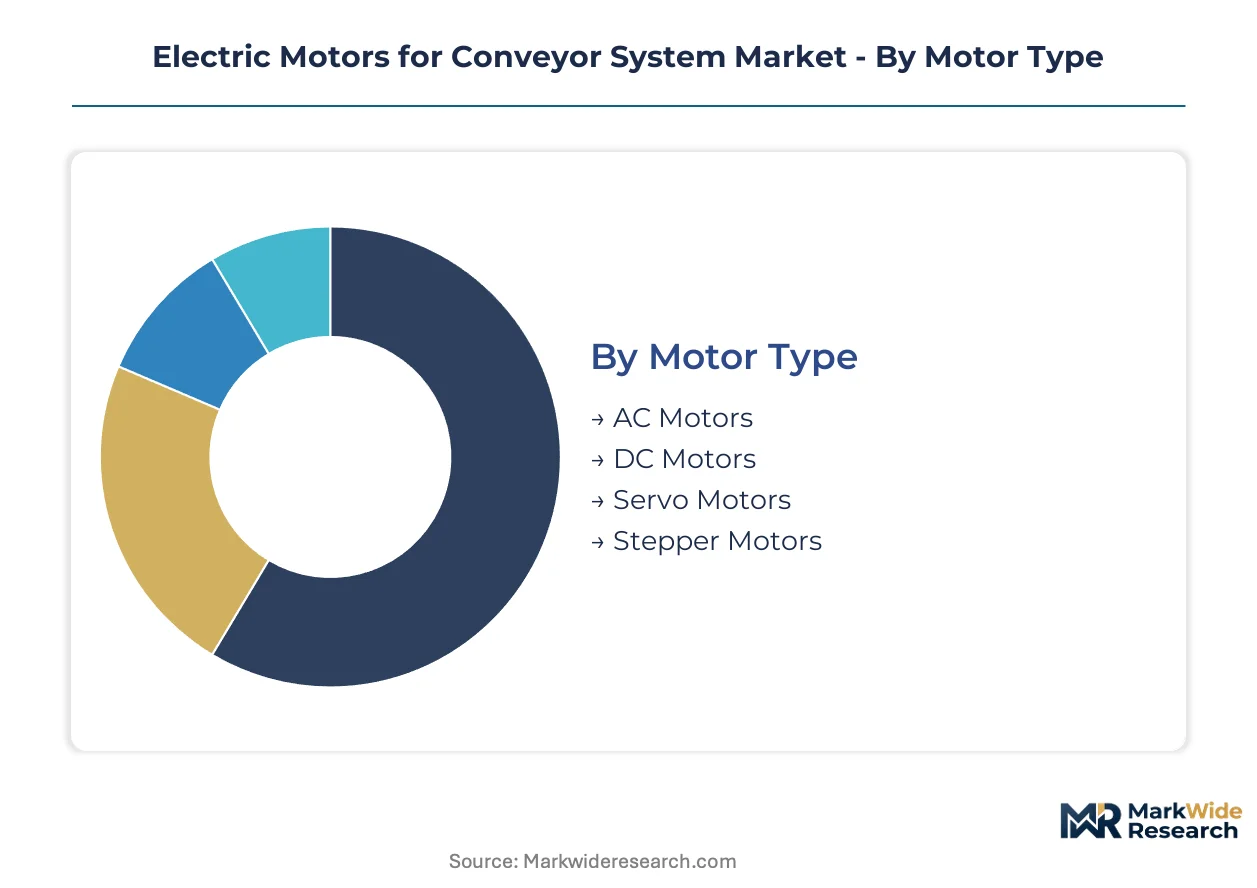
Electric motor procurement for conveyor systems follows distinct technical and economic logics across motor architectures, power classes, control philosophies, and end-use environments. Buyers weigh efficiency certification tiers against duty cycle requirements while navigating jurisdictional regulatory mandates that disqualify lower-efficiency platforms from new installations.
Motor Type:
Equipment buyers prioritize efficiency tier compliance and torque density when specifying motor architectures for continuous-duty material handling operations.
- AC Motors:Induction architectures dominate installed bases across manufacturing floors and distribution hubs due to rugged construction and variable frequency drive compatibility. Demand concentrates in Germany and the United States where energy efficiency regulations under the EU Ecodesign Directive and US Department of Energy standards accelerate replacement cycles toward premium-efficiency IE4 platforms.
- Servo Motors:Permanent magnet synchronous designs deliver precise positioning for high-speed sortation and indexing applications in pharmaceutical packaging and electronics assembly lines. Demand clusters in automated fulfillment centers processing parcel volumes exceeding one million units daily, where exact positioning determines system throughput.
- DC Motors:Brushed and brushless configurations persist in legacy material handling equipment and battery-powered mobile conveyor systems requiring simple speed control without inverter infrastructure.
- Stepper Motors:Open-loop positioning architectures serve low-torque indexing applications in laboratory automation and small-scale packaging machinery where cost minimization outweighs dynamic performance requirements.
Volume sits with AC Motors; growth tilts toward Servo Motors.
Power Rating:
Capital expenditure thresholds and operating cost structures divide procurement patterns across conveyor system scale classes.
- Medium Power:Motors in the 5-50 kW range power bulk material handling conveyors and automated sortation systems across e-commerce fulfillment infrastructure. Procurement concentrates in China and Germany where warehouse automation buildouts demand continuous-duty platforms with IE4 efficiency certification.
- Low Power:Fractional horsepower units drive light-duty package handling and modular conveyor sections in pharmaceutical and electronics assembly environments. Food processing washdown-rated configurations command premium positioning under FDA sanitary design requirements.
- High Power:Heavy-duty mining, aggregate, and port material handling applications require robust enclosures and extended bearing life for severe-duty cycles.
- Custom Power:Engineered-to-order specifications address non-standard belt widths, extreme ambient temperatures, and explosive atmosphere certifications for chemical and petrochemical handling facilities.
Medium Power carries the heaviest procurement volume; Custom Power expands most quickly in specialized industrial applications.
Control Method:
Energy management strategies and startup torque requirements determine controller selection across conveyor system architectures.
- Variable Frequency Drive:VFD control dominates new installations by enabling precise speed modulation, regenerative braking, and demand-responsive energy consumption. Adoption accelerates under US Inflation Reduction Act efficiency incentives and EU Ecodesign Directive compliance timelines.
- Direct On-Line:Simple across-the-line starting persists in cost-sensitive applications with low starting frequency and minimal speed variation requirements.
- Soft Starter:Reduced-voltage starting protects mechanical components in high-inertia bulk handling conveyors while limiting electrical disturbance on distribution networks.
- Open Loop:Basic voltage-frequency control serves fixed-speed applications where precise torque control provides no operational benefit.
Variable Frequency Drive commands the largest share of new specification; Soft Starter retains position in retrofit-heavy mining and aggregate sectors.
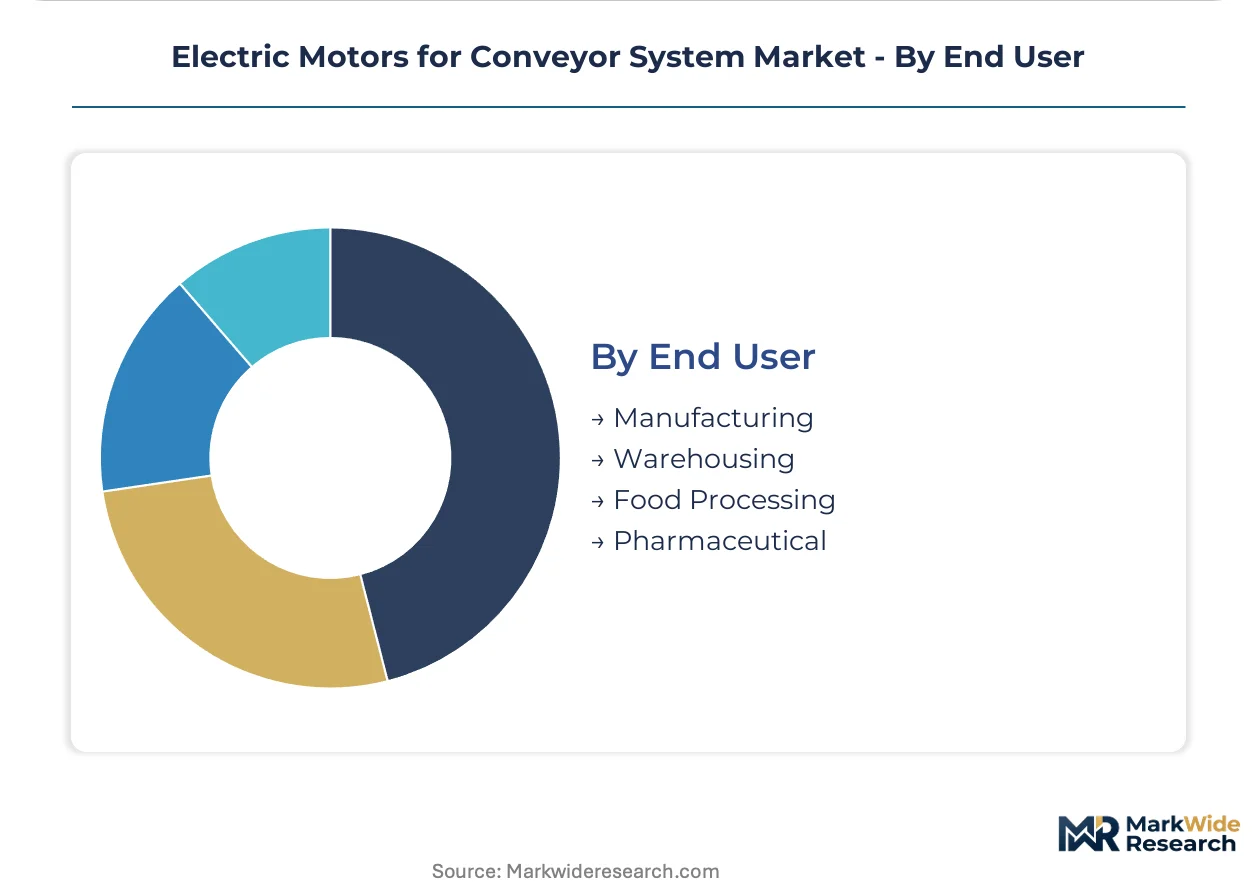
End User:
Regulatory compliance burdens and operating environment severity create divergent procurement specifications across vertical markets.
- Manufacturing:Assembly line and work-in-progress conveyor systems demand reliable continuous-duty motors with IP55 minimum enclosure ratings. Procurement concentrates in automotive and electronics production clusters across Germany, China, and the United States.
- Food Processing:Stainless steel washdown-rated motors with smooth surfaces and sealed bearings satisfy FDA and USDA sanitary design requirements in protein processing and dairy operations. Premium pricing reflects corrosion resistance and cleanability certification.
- Warehousing:Automated storage and retrieval systems plus parcel sortation infrastructure pull high-torque-density motors toward 24/7 operational profiles in e-commerce fulfillment centers.
- Pharmaceutical:Cleanroom-compatible motors with low particle generation and precise indexing capability serve packaging and serialization lines under strict contamination control protocols.
Manufacturing holds the broadest installed base; Food Processing generates the steepest pricing premiums per kilowatt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and Germany's industrial corridors concentrate conveyor motor procurement for automated logistics infrastructure. These designated zones accelerate depreciation schedules and import duty exemptions for efficiency-certified equipment.
United States
E-commerce fulfillment centers in the Inland Empire and Dallas-Fort Worth metroplex drive continuous-duty motor procurement for automated sortation systems. The US Inflation Reduction Act extends tax credits for industrial equipment upgrades exceeding specified efficiency thresholds. Chicago and Atlanta distribution hubs are retrofitting legacy conveyor infrastructure with premium-efficiency platforms under accelerated depreciation schedules.
Germany
Automotive manufacturing clusters in Bavaria and Baden-Württemberg sustain demand for precision conveyor motors in assembly line applications. The EU Ecodesign Directive's IE4 minimum efficiency requirements for motors above 75 kW compress replacement cycles across industrial installations. The Ruhr Valley logistics corridor is consolidating procurement around integrated motor-drive packages to guarantee system-level compliance certification.
China
Domestic logistics infrastructure expansion in the Pearl River Delta and Yangtze River Delta pulls high-torque-density motor procurement toward 24/7 operational profiles. SAMR-administered GB standards establish efficiency tiers that influence sourcing decisions for warehouse automation buildouts. Shenzhen and Shanghai fulfillment centers are deploying servo motor architectures for high-speed parcel sortation exceeding one million units daily.
India
Cold chain and pharmaceutical distribution networks in Maharashtra and Gujarat create white space for gearmotor suppliers targeting warehouse automation penetration below comparable Asian economies. The PLI scheme for manufacturing incentives supports domestic motor production capacity expansion. Mumbai-Pune industrial corridor facilities are adopting stainless steel washdown-rated configurations for food processing sanitation compliance.
Electric Motors for Conveyor System Market Competitive Landscape
Top-tier vendors anchor premium-efficiency platforms, while mid-tier specialists capture retrofit opportunities through application-specific configurations. The supplier base organizes around three strategic archetypes: integrated drive-motor portfolio providers, compact gearmotor specialists, and fractional horsepower precision motor fabricators. Consolidation pressures favor vendors with captive VFD commissioning expertise and multi-jurisdictional certification capabilities. Dominant competitive moves include backward integration into permanent magnet supply chains and predictive maintenance service model expansion.
Within the integrated systems tier, ABB Group and Siemens AG exemplify vendors consolidating procurement relationships through lifecycle cost optimization provisions. Bonfiglioli Riduttori S.p.A occupies a specialized position among compact gearmotor suppliers targeting space-constrained intralogistics installations. These three entities represent distinct competitive vectors: scale-driven platform breadth, European regulatory anchoring, and application-specific torque density leadership.
| Leading Market Players |
|---|
| Bodine Electric Company |
| Bonfiglioli Riduttori S.p.A |
| ABB Group |
| Power Electric |
| Altra Industrial Motion |
| Siemens AG |
| Oriental Motor U.S.A. Corp |
| Regal Rexnord Corporation |
| Nord Gear Corporation |
| Others |
Supply & Pricing Matrix
Permanent magnet synchronous motor adoption is compressing cost economics for high-efficiency platforms while concentrating supply leverage among vendors with captive rare earth sourcing. This technology transition simultaneously elevates working capital requirements for motor assemblers and tightens procurement timelines for buyers seeking IE4 and IE5 efficiency tiers.
Pricing Analysis
Short lead-time premiums now structure procurement negotiations, with buyers paying 15-25% markups for motors deliverable inside eight weeks versus standard twelve-week cycles. Three-tier pricing structure across premium, standard, and economy levels separates IE5 permanent magnet platforms from IE4 induction alternatives and legacy IE3 inventory. Pricing pressure stems from copper and neodymium volatility transmitted through Chinese processing concentration. Small and mid-sized conveyor operators exhibit acute price sensitivity, while e-commerce fulfillment giants absorb premiums for predictive maintenance bundling.
Supply Chain Analysis
Warehouse-distribution layers organize around regional distribution centers in Germany, China, and the United States that buffer OEMs against demand spikes. Motor manufacturing draws from concentrated rare earth processing in China, copper cathode supply from Chile and Peru, and electrical steel from Japan and South Korea. Single-source vulnerability in neodymium supply creates exposure to export restriction risk. Distribution runs through authorized distributor networks with technical commissioning capabilities, bypassing traditional conveyor OEM channels for large fulfillment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in rare earth magnet supply are propping pricing power for integrated motor-drive vendors with upstream material security. Capacity bottlenecks in qualified VFD commissioning expertise extend delivery timelines and inflate service premiums.
For Market Incumbents: To counter disintermediation by e-commerce fulfillment operators building direct supplier relationships, anchor procurement consolidation through extended warranty and predictive maintenance service contracts. Deepen backward integration into permanent magnet supply chains to insulate margin structures from Chinese rare earth volatility. Prioritize captive VFD commissioning capacity to capture installation-phase value that distributors cannot replicate. For New Entrants and Emerging Players: Begin with India's underpenetrated warehouse automation infrastructure, where cold chain and pharmaceutical distribution networks lack qualified gearmotor suppliers. Target stainless steel washdown-rated configurations for food processing applications in Maharashtra and Gujarat industrial corridors. Lead with application engineering support that incumbent distributors underserve in mid-market dairy and protein processing operations. For Investors and Strategic Acquirers: Re-rating potential sits with compact gearmotor specialists possessing multi-jurisdictional certification capabilities given accelerating EU Ecodesign Directive compliance timelines. Long-term viability favors vendors with integrated motor-drive portfolios and predictive maintenance software attach rates. Monitor VFD commissioning technician availability as the inflection indicator for vendor pricing power versus distributor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Supply | Captive neodymium sourcing insulates margin structures from Chinese export restriction risk. |
| Predictive Maintenance Service Expansion | Software-enabled condition monitoring shifts value capture from hardware to recurring revenue streams. |
| Multi-Jurisdictional Certification Investment | Parallel CE, UL, and CCC compliance accelerates cross-border deployment without retesting delays. |
| Regional Distribution Center Expansion | Local inventory buffers in Germany, China, and the United States compress lead times for fulfillment operators. |
| Servo Motor Architecture Development | Precision indexing capability penetrates pharmaceutical packaging and electronics assembly conveyor zones. |
Research Methodology
Document review covered regulatory filings from the US Department of Energy and EU Ecodesign Directive documentation, complemented by interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at conveyor-integrated manufacturing and logistics facilities. Secondary validation drew from customs trade data, SEC 10-K filings, and efficiency certification databases. Bottom-up motor shipment estimates triangulated against top-down conveyor system investment flows.
Historical efficiency regulation adoption curves were cross-referenced against panel input from industry stakeholders to model replacement cycle acceleration. Segmentation across motor architecture, power rating, control method, and end-use environment structured volume and value outputs across the analysis window. CAGRs were derived from regression analysis of procurement intensity versus e-commerce fulfillment infrastructure buildout rates and energy efficiency payback threshold evolution.
Underlying measurement precision varies by segment; AC motor volumes carry tighter precision than emerging servo motor categories where specification standards remain fluid. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and rare earth supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Current Clamps Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Electric Enclosure Market