
 Electric Control Panel Market | 2026-2036
Electric Control Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Control Panel Market Analysis
Multi-source procurement for electromechanical assemblies is restructuring supply relationships across the Electric Control Panel Market. ABB Ltd. leverages captive semiconductor sourcing to protect delivery schedules for medium voltage panel lines. Schneider Electric anchors its position through deep channel partnerships with European system integrators. Siemens AG competes on engineering density, staffing regional application centers with power systems specialists.
An electric control panel is an enclosed assembly of circuit breakers, contactors, relays, busbars, and instrumentation devices rated for specific voltage classes, designed to distribute, control, and protect electrical power flows in industrial and commercial installations. Low voltage panels dominate unit volumes due to ubiquity across manufacturing floors and commercial buildings, while PLC-based systems capture the fastest expansion as facilities retrofit manual controls with programmable logic for process visibility. Motor control centers retain mature, replacement-driven demand patterns with margin pools concentrated in aftermarket services and spare parts logistics.
NFPA 70 (National Electrical Code) in the United States, IEC 61439 across European markets, and OSHA electrical safety directives collectively shape enclosure ratings, short-circuit withstand requirements, and arc flash mitigation features that panel builders must certify before installation. These standards raise engineering costs for smaller fabricators while creating specification advantages for manufacturers with in-house testing laboratories and pre-approved design platforms. Stakeholders must monitor how evolving grid interconnection rules for distributed solar and battery storage redefine panel architectures and protection coordination schemes.
Market Dynamics
The Electric Control Panel Market faces structural pressure from IEC 61439-2 compliance deadlines, which mandate enhanced arc fault containment and busbar segregation. Panel fabricators must redesign enclosure architectures while maintaining cost positions against commodity Asian imports.
Growth Catalysts
- Automotive Electrification:Battery gigafactories in Germany and the United States require medium-voltage motor control centers with integrated safety instrumentation. OEMs specify IEC-compliant panels for cell formation and electrode coating lines.
- NFPA 70E Arc Flash Mandates:U.S. industrial facilities must retrofit legacy switchgear with arc-resistant enclosures and remote racking systems. Compliance audits drive replacement cycles in petrochemical and metals processing plants.
- Silicon Carbide Power Semiconductors:Wide-bandgap devices enable compact, high-frequency drives that reduce panel footprint by 40%. Food and beverage packagers adopt these integrated motor-drive assemblies for cleanroom compatibility.
Market Restraints
- Copper and Cold-Rolled Steel Volatility:Busbar and enclosure raw material costs swing 15-25% quarterly. Small fabricators in Italy and Poland lack hedging programs to absorb input spikes.
- Semiconductor Supply Concentration:IGBT modules and protection relays source predominantly from East Asian foundries. Lead times for medium-voltage breakers stretch 26-34 weeks, freezing project schedules.
- Skilled Electrician Scarcity:Germany's Chamber of Industry and Commerce reports 12,000 unfilled electrical technician positions. Panel commissioning and startup delays extend 30-60 days at industrial sites.
Strategic Opportunities
- India Manufacturing Incentives:The Production Linked Incentive scheme for electrical equipment offers 4-6% output-linked benefits. Multinational panel builders localize assembly in Gujarat and Tamil Nadu to serve Southeast Asian project demand.
- Digital Twin Integration:Siemens and ABB embed asset performance management software into panel deliveries. Predictive maintenance contracts generate recurring revenue streams from pharmaceutical and data center operators.
- EU Green Deal Electrification:The REPowerEU plan mandates industrial heat pump deployment. Control panel demand from district heating substations and thermal storage systems will accelerate through 2030.
Industry Challenges
- IEC 61439 Type-Tested Assembly Certification:Third-party laboratory validation costs €15,000-40,000 per panel series. Smaller fabricators defer new product introductions, ceding specification battles to tested-platform incumbents.
- Legacy System Integration:Brownfield manufacturing sites operate 1980s-era relay logic and pneumatic controls. PLC migration projects require custom I/O mapping and operator retraining, inflating commissioning budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Control Panel Market |
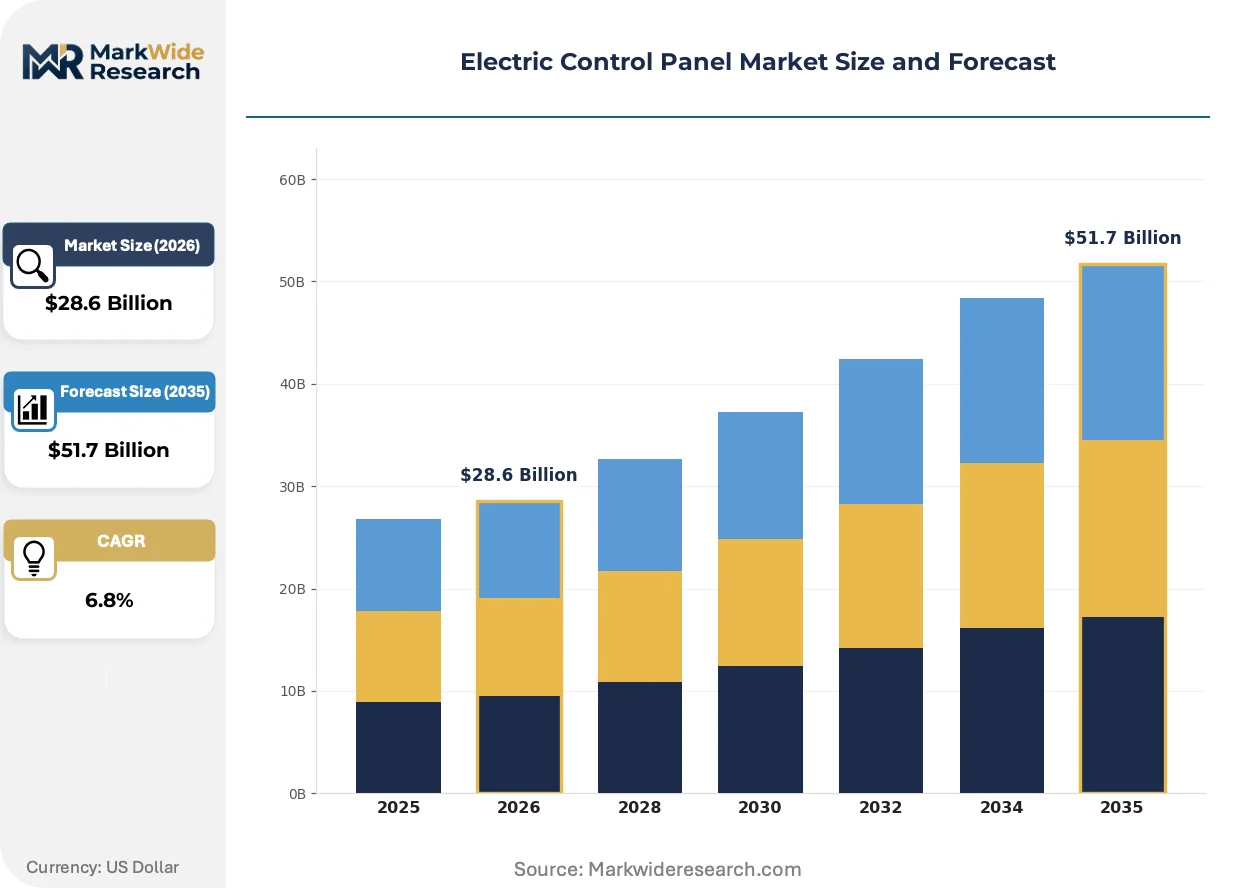
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage Panels, Medium Voltage Panels, Power Distribution Panels, Motor Control Centers Technology: Smart Grid, PLC-Based Systems, Manual Control, Remote Monitoring Application: Industrial Automation, Building Management, Renewable Energy Systems, Power Generation End User: Manufacturing, Oil & Gas, Utilities, Transportation |
| Companies Covered | ABB Ltd., Schneider Electric, Siemens AG, Eaton, Rockwell Automation, nVent, Mitsubishi Electric, Power Industrial Controls, Bay Power Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Control Panel Market Emerging Trajectories
Digitalization of power distribution is compressing the traditional separation between hardware fabrication and software-enabled services. Panel builders now compete on data architecture integration, not merely enclosure engineering.
Intelligent motor control centers with embedded Ethernet-IP and Profinet connectivity are expanding into process industries previously served by hardwired I/O. Chemical producers in the Rhine-Ruhr cluster deploy these systems for real-time energy monitoring and predictive bearing analysis. The technology is expanding into aftermarket service contracts that displace traditional break-fix maintenance models.
The EU F-Gas Regulation's phasedown of SF6 insulating gas is forcing medium-voltage panel redesigns toward vacuum interrupters and dry air insulation. German switchgear manufacturers accelerate R&D spending to maintain export competitiveness. French nuclear maintenance providers now specify SF6-free panels for safety-critical balance-of-plant upgrades.
Consolidated procurement by engineering-procurement-construction firms is compressing vendor lists to pre-qualified platform suppliers. Oil and gas megaprojects in the United States Gulf Coast now specify sole-source panel packages spanning low-voltage through medium-voltage classes. This concentration favors fabricators with in-house metalworking, powder coating, and cable harness capabilities.
Electric Control Panel Market Segmentation
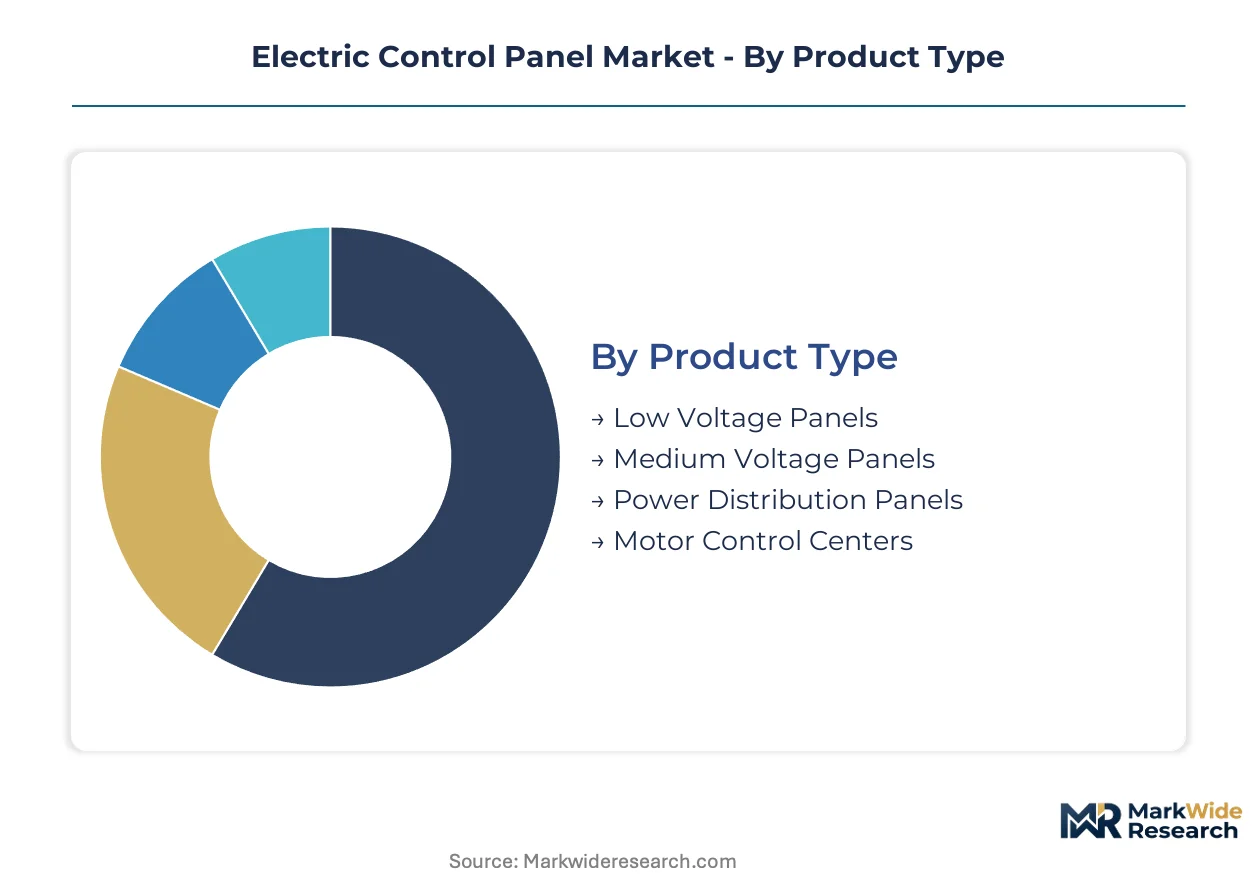
Segmentation in the Electric Control Panel Market reveals how voltage class, control architecture, and end-use environment dictate specification requirements, compliance pathways, and supplier selection criteria across industrial and commercial installations.
Product Type:
Buyers differentiate primarily by voltage class and fault current handling requirements, with installation scale and safety criticality driving enclosure ratings and busbar configurations.
- Low Voltage Panels:Rated up to 1,000V AC, these assemblies dominate manufacturing floor installations with molded-case circuit breakers and DIN-rail mounted components. Demand concentrates in Germany's automotive stamping plants and food processing facilities across Bavaria, driven by IEC 61439-2 compliance deadlines forcing enclosure upgrades.
- Medium Voltage Panels:Operating at 1kV-52kV with metal-clad switchgear and vacuum interrupters, these systems protect transformer substations and heavy motor loads. Battery gigafactories in the United States and Germany specify these for electrode coating lines, where arc flash containment and busbar segregation are non-negotiable.
- Power Distribution Panels:Main-tie-main configurations with draw-out breakers serve commercial campuses and data centers requiring selective coordination.
- Motor Control Centers:Bucket-style assemblies with combination starters support conveyor systems and pump stations in mature replacement cycles.
Volume sits with Low Voltage Panels; growth tilts toward Medium Voltage Panels.
Technology:
The control architecture spectrum spans hardwired electromechanical logic to software-defined automation, with connectivity requirements and operator skill levels determining technology selection.
- Smart Grid:IEC 61850-compliant panels with embedded sensors and edge computing enable real-time power quality monitoring and demand response. German distribution utilities deploy these for grid modernization, while French nuclear maintenance providers specify them for safety-critical balance-of-plant upgrades.
- PLC-Based Systems:Programmable logic controllers with Ethernet-IP and Profinet connectivity replace relay logic for process visibility and remote diagnostics. Chemical producers in Germany's Rhine-Ruhr cluster lead adoption, using predictive bearing analysis to displace break-fix maintenance contracts.
- Manual Control:Pushbutton and selector switch interfaces persist in hazardous environments where cybersecurity isolation trumps connectivity.
- Remote Monitoring:Cloud-connected panels with asset performance management software generate recurring revenue from pharmaceutical and data center operators.
Manual Control retains installed base dominance; PLC-Based Systems are climbing the fastest as brownfield retrofits accelerate.
Application:
Application context determines environmental protection ratings, arc flash mitigation requirements, and integration complexity with existing building or process infrastructure.
- Industrial Automation:Harsh-duty enclosures with NEMA 4X or IP65 ratings protect against coolant spray and metal dust in machining centers. U.S. automotive battery plants and German chemical facilities drive specification volume, with NFPA 70E arc flash mandates forcing enclosure replacements.
- Building Management:Compact panelboards with integrated energy meters serve commercial office and healthcare facilities where space constraints and aesthetics matter.
- Renewable Energy Systems:DC-rated busbars and rapid shutdown compliance dominate solar inverter skids and battery energy storage enclosures.
- Power Generation:Custom engineered switchgear with synchrophasor monitoring protects turbine generators and grid interconnection points.
Industrial Automation commands current revenue concentration; Renewable Energy Systems show the steepest expansion trajectory through grid interconnection buildouts.
End User:
End-user industry dictates safety integrity levels, hazardous area classifications, and lifecycle service expectations that separate specification-grade suppliers from commodity fabricators.
- Manufacturing:Discrete and process automation panels with high-density I/O and cleanroom-compatible finishes serve semiconductor fabs and food packagers. India's Production Linked Incentive scheme for electrical equipment is drawing multinational assembly localization to serve Southeast Asian manufacturing demand.
- Oil & Gas:Explosion-proof enclosures and SIL-rated safety instrumented systems protect offshore platforms and LNG terminals. U.S. Gulf Coast megaprojects now specify sole-source panel packages spanning low-voltage through medium-voltage classes.
- Utilities:Pole-mounted reclosers and pad-mounted switchgear prioritize reliability and remote operation for distribution network resilience.
- Transportation:Traction power substations and tunnel ventilation controls require seismic qualification and fire-resistant cabling.
Manufacturing absorbs the highest unit volumes; Oil & Gas maintains premium pricing through hazardous location certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive stamping belt and chemical corridor anchor European copper busbar consumption. China's Yangtze River Delta clusters supply enclosure-grade cold-rolled steel to fabricators worldwide. India's PLI scheme for electrical equipment is redirecting multinational assembly capacity toward Gujarat and Tamil Nadu.
United States
Automotive battery gigafactories in Michigan and Tennessee require medium-voltage motor control centers with integrated safety instrumentation. OSHA electrical safety directives and NFPA 70E arc flash mandates force enclosure replacements across petrochemical facilities. The Gulf Coast engineering-procurement-construction corridor now specifies sole-source panel packages for oil and gas megaprojects.
Germany
Bavarian automotive producers and Rhine-Ruhr chemical facilities drive specification volume for IEC 61439-2 compliant low-voltage panels. The EU F-Gas Regulation's SF6 phasedown accelerates vacuum interrupter adoption in medium-voltage switchgear. Stuttgart's industrial automation cluster deploys PLC-based systems with predictive bearing analysis to displace break-fix maintenance contracts.
China
Yangtze River Delta fabricators supply enclosure-grade steel and copper busbar assemblies to domestic and export markets. The country's dual carbon goals accelerate grid modernization investments requiring smart grid-compliant panels. Shenzhen's electronics manufacturing corridor demands compact, high-frequency motor-drive assemblies for cleanroom-compatible production lines.
India
The Production Linked Incentive scheme for electrical equipment offers output-linked benefits drawing multinational panel builders to Gujarat and Tamil Nadu. Central Electricity Authority regulations shape distribution network resilience requirements for utilities. Maharashtra's manufacturing belt generates concentrated demand from discrete automation and food processing facilities upgrading legacy relay logic.
Japan
Chubu region automotive suppliers and Kanto electronics manufacturers specify high-density I/O panels with cleanroom-compatible finishes. METI industrial efficiency standards drive predictive maintenance adoption in semiconductor fabrication facilities. Osaka-Kobe's chemical processing cluster maintains mature replacement cycles for motor control centers with aftermarket service contracts.
Electric Control Panel Market Vendor Landscape
Global majors compete with regional champions across certification depth and channel reach. The vendor base stratifies into three tiers: tested-platform incumbents with in-house laboratories, regional fabricators with metalworking and powder coating capabilities, and commodity assemblers dependent on outsourced component sourcing. Strategic moves concentrate on pre-qualification for engineering-procurement-construction vendor lists and geographic localization to capture India PLI incentives.
Among European-based diversified industrials, ABB Ltd. and Schneider Electric occupy positions anchored by captive semiconductor sourcing and deep channel partnerships respectively. Siemens AG exemplifies the engineering-density archetype through regional application centers staffed with power systems specialists. These three represent distinct competitive vectors: supply security, distribution integration, and technical service intensity.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric |
| Siemens AG |
| Eaton |
| Rockwell Automation |
| nVent |
| Mitsubishi Electric |
| Power Industrial Controls |
| Bay Power Inc. |
| Others |
Supply Flow & Price Mechanics
Oil and gas megaproject procurement offices in the United States Gulf Coast and battery gigafactory engineering teams in Germany command sole-source panel packages that compress vendor lists to pre-qualified platform suppliers. This buyer concentration tilts pricing power toward fabricators with in-house testing laboratories and captive semiconductor sourcing, while commodity assemblers face margin erosion from raw material volatility and compliance certification costs.
Pricing Analysis
Warranty and aftermarket service bundling separates specification-grade suppliers from transactional fabricators, with predictive maintenance contracts now standard for pharmaceutical and data center operators. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with IEC 61439 type-tested assemblies commanding 15-25% premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because small Italian and Polish fabricators lack hedging programs to absorb copper and cold-rolled steel swings. Project-based buyers in renewable energy show highest price sensitivity, while nuclear maintenance providers and automotive OEMs prioritize compliance over unit cost.
Supply Chain Analysis
IGBT module and protection relay supply rests on East Asian foundries in China, South Korea, and Japan, with vacuum interrupter sourcing concentrating in Germany and Switzerland. Copper busbar draws from Chilean mining operations and Chinese Yangtze River Delta smelters, while enclosure-grade cold-rolled steel feeds from Chinese and Indian mills. Single-source vulnerability in medium-voltage breaker semiconductors creates 26-34 week lead time exposure that freezes project schedules. Distribution runs through engineering-procurement-construction firms and European system integrators with deep channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from IEC 61439-2 compliance deadlines and third-party laboratory validation costs is forcing smaller fabricators to defer new product introductions, ceding specification battles to tested-platform incumbents with in-house capabilities.
For Market Incumbents: Deploy captive semiconductor sourcing to protect delivery schedules for medium-voltage panel lines against East Asian foundry concentration risk. Deepen backward integration into powder coating and cable harness capabilities to defend sole-source package positions for Gulf Coast oil and gas megaprojects. Channel control through regional application centers staffed with power systems specialists anchors specification influence in Germany's automotive stamping belt. For New Entrants and Emerging Players: The 15-25% price gap between premium IEC-certified platforms and commodity Asian imports opens white-space in India's PLI scheme localizations for Southeast Asian project demand. Target aftermarket service contracts for motor control centers in Japan's Osaka-Kobe chemical processing cluster, where mature replacement cycles favor predictive maintenance over break-fix models. Go-to-market through European system integrator partnerships accelerates specification access without direct certification investment. For Investors and Strategic Acquirers: The window for entry favors regional fabricators with metalworking capabilities and pre-qualified EPC vendor list positions. Long-term viability hinges on digital twin integration and asset performance management software recurring revenue streams. Watch Siemens and ABB predictive maintenance contract penetration in pharmaceutical and data center verticals as inflection indicator for service-margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive IGBT supply protects ABB's medium-voltage panel delivery schedules against East Asian foundry lead times. |
| Digital Twin Platform Integration | Siemens embeds asset performance management software to generate recurring revenue from data center operators. |
| IEC 61439 Certification Investment | Third-party laboratory validation creates specification barriers that cede market share to tested-platform incumbents. |
| India PLI Localization | Multinational assembly in Gujarat and Tamil Nadu captures 4-6% output-linked benefits for Southeast Asian demand. |
| SF6-Free Switchgear R&D | German manufacturers accelerate vacuum interrupter development to maintain export competitiveness under EU F-Gas phasedown. |
Methodological Framework
Trade association filings from NEMA and ZVEI, customs databases tracking copper busbar and cold-rolled steel flows, and SEC 10-K disclosures from listed electrical equipment manufacturers formed the secondary backbone. Primary interviews with plant engineers at German automotive stamping facilities, procurement leads at U.S. battery gigafactories, EPC contractors in the Gulf Coast corridor, and aftermarket service heads at Japanese chemical processors validated demand patterns. Bottom-up unit economics and top-down macroeconomic triangulation anchored market sizing across voltage classes and control architectures.
Historical trendline analysis of industrial automation capital expenditure and electrical safety mandate compliance cycles informed projection frameworks. Segmentation modeling spanned voltage class, control architecture, end-use environment, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves and substitution dynamics between PLC-based and hardwired systems. Forecast inputs incorporated silicon carbide semiconductor adoption curves and EU Green Deal electrification targets.
Inputs from NEMA shipment data and ZVEI order intake statistics were available through the study window; gaps in small fabricator financial disclosures introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding IEC 61439-2 compliance deadline adherence and semiconductor supply normalization trajectories. Regulatory acceleration in arc flash mitigation, raw material cost spikes, and skilled electrician scarcity in Germany warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Insulator Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
North America Thermal Protector Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market