
 Vacuum Chambers Market | 2026-2036
Vacuum Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Chambers Market Intelligence
Specialist fabricators in Germany and Japan are pivoting toward higher-margin, custom chamber production for research applications. Pfeiffer Vacuum Technology AG leverages its extensive engineering capabilities to serve complex R&D projects. Kurt J. Lesker Company differentiates through a comprehensive component catalog and global logistics. MKS Instruments, Inc. competes by offering integrated vacuum solutions that bundle chambers with its proprietary instrumentation.
A vacuum chamber is a rigid enclosure from which air and other gases are removed by a vacuum pump. These vessels, typically constructed from stainless steel or aluminum, must withstand significant external pressure to maintain an internal low-pressure environment. Custom chambers designed for research and development applications command the highest margins. Rigid chambers for industrial processes constitute a high-volume segment where competition is based on manufacturing scale and material sourcing.
Material and construction integrity is governed by ISO standards, alongside specific national frameworks like Japan's JIS standards for industrial equipment. For life sciences and food packaging, compliance with regulations from the US FDA and the European Medicines Agency is mandatory for market access. Navigating the interplay between material science advancements and evolving end-user cleanliness specifications will define competitive advantage for manufacturers.
Market Dynamics
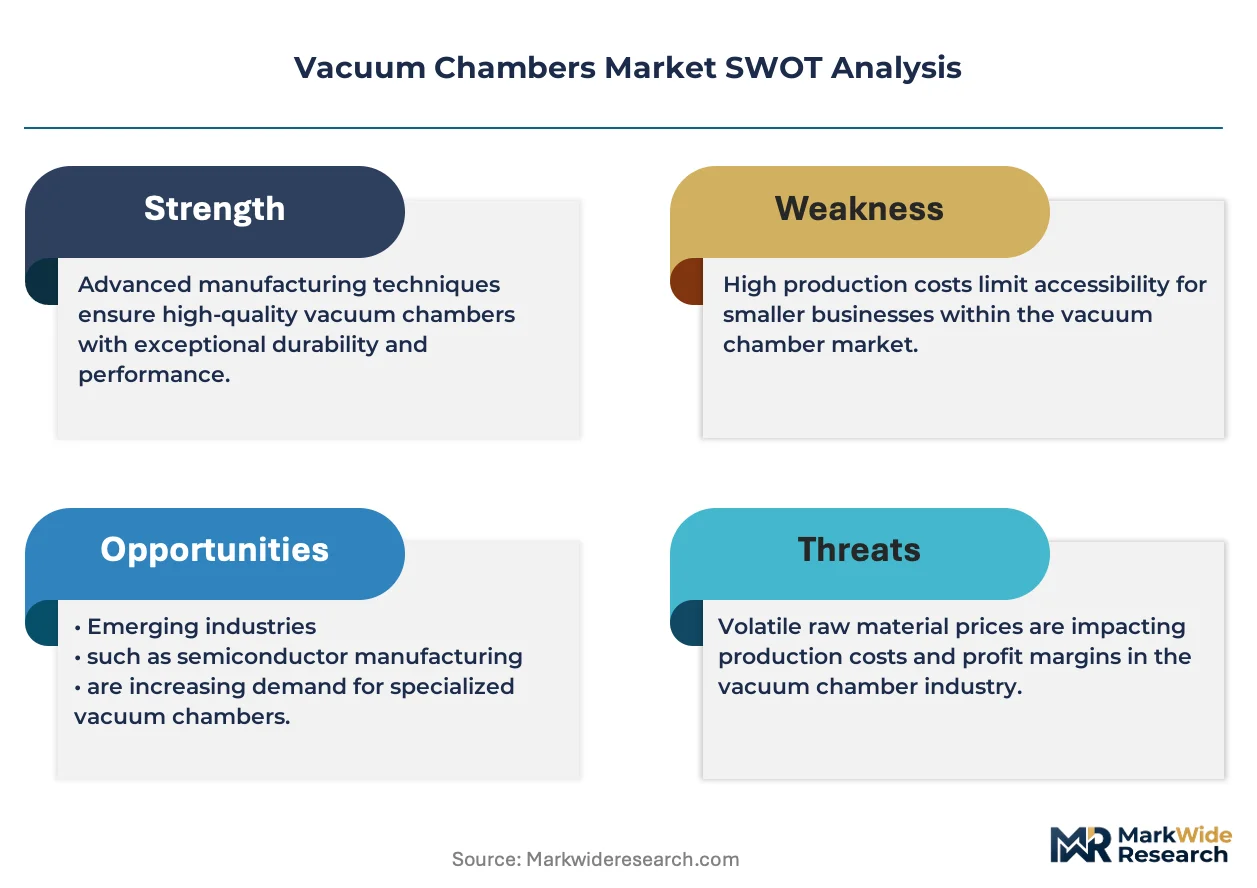
The vacuum chamber market is defined by a fundamental divergence between industrial-scale production and specialized, high-margin fabrication. This split forces manufacturers to choose between competing on cost and volume for process applications or on engineering depth for custom R&D projects.
Growth Catalysts
- Semiconductor Advancement:The transition to sub-5-nanometer nodes in semiconductor fabrication demands exceptionally clean and stable vacuum environments, driving investment in advanced chamber technologies to minimize particulate contamination and ensure process uniformity.
- Pharmaceutical Processing:Demand for lyophilization (freeze-drying) in sterile drug manufacturing and biologics preservation creates a need for vacuum chambers that comply with stringent cGMP, US FDA, and EMA cleanliness and material standards.
- National R&D Initiatives:Government-funded projects in fields like fusion energy in the UK and quantum computing research in Germany require ultra-high vacuum (UHV) systems, creating dedicated demand for highly customized, performance-critical chambers.
Market Restraints
- Material Cost Volatility:The price and availability of specialized, low-outgassing materials like vacuum-grade 316LN stainless steel and forged aluminum alloys are subject to fluctuations in global commodity markets, impacting production costs and margin stability.
- Technical Performance Limits:Achieving and maintaining ultra-high vacuum (UHV) conditions is constrained by the physical phenomenon of outgassing from chamber walls, which can introduce impurities and limit the ultimate pressure achievable in sensitive experiments.
- Specialized Labor Scarcity:A limited global pool of certified welders and engineers with expertise in UHV fabrication techniques, particularly in established manufacturing hubs like Germany and Japan, creates production bottlenecks and inflates labor costs.
Strategic Opportunities
- Space Sector Expansion:The proliferation of private satellite constellations and space exploration missions creates new demand for large thermal vacuum (TVAC) chambers to test spacecraft components and systems under simulated space conditions.
- Integrated Smart Chambers:Embedding sensors for pressure, temperature, and residual gas analysis directly into chamber walls offers an opportunity to provide customers with intelligent, data-rich subsystems that enable real-time process monitoring and predictive maintenance.
- Food Packaging Modernization:The adoption of modified atmosphere packaging (MAP) and vacuum skin packaging (VSP) in emerging economies across Southeast Asia and Latin America provides a volume market for industrial-grade stainless steel chambers.
Industry Challenges
- UHV Fabrication Skill Gap:A persistent shortage of technicians skilled in cleanroom assembly protocols and specialized welding techniques, such as tungsten inert gas (TIG) welding for vacuum-tight seams, hinders the production of high-specification chambers.
- Dual-Certification Complexity:Navigating the separate and often lengthy certification processes for life science applications under both US FDA and European EMA regulations adds significant time and cost to product development and market entry.
- Capital-Intensive Manufacturing:The high upfront investment required for precision equipment like electron beam welders and large-scale, five-axis CNC machines for monolithic chamber production presents a significant barrier to entry for new fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Chambers Market |
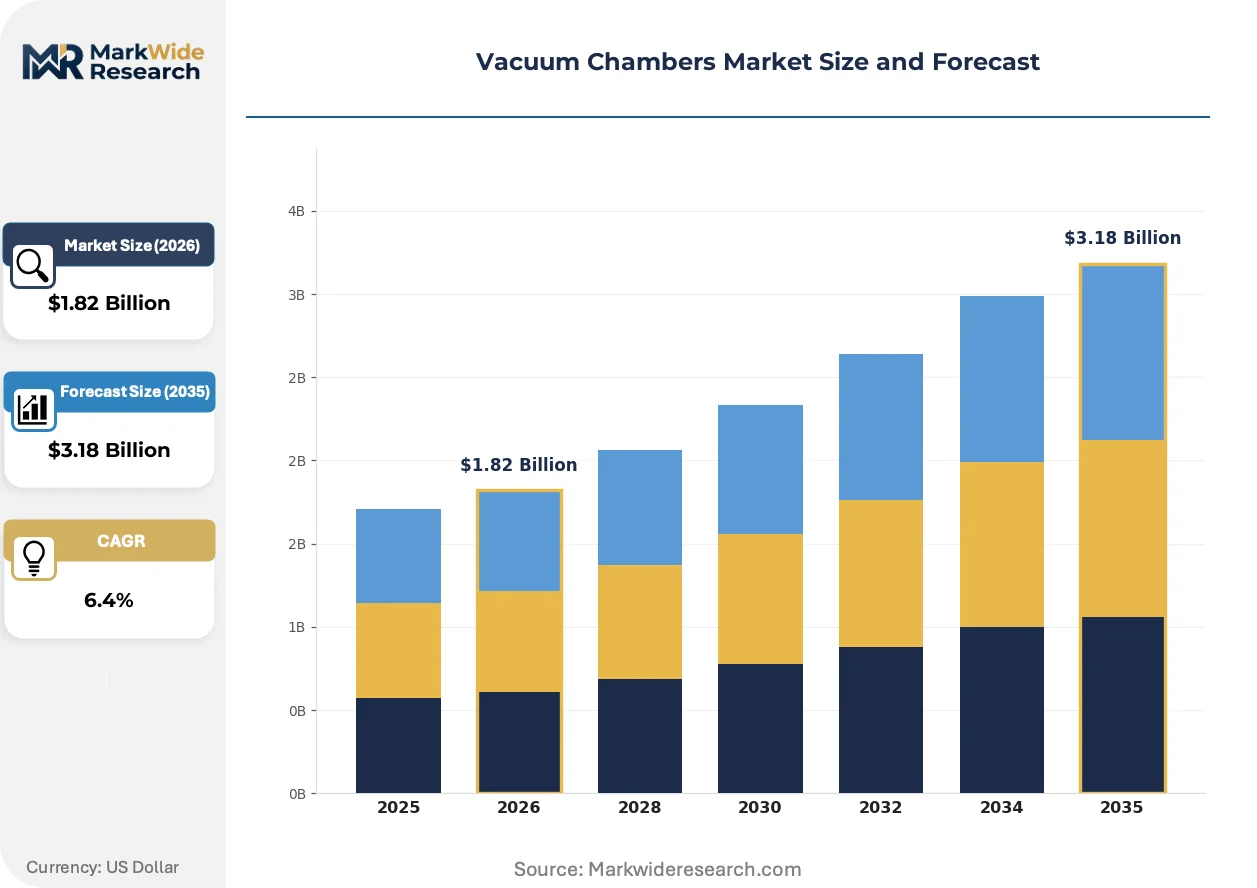
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Chambers, Flexible Chambers, Custom Chambers, Lab Chambers Application: Industrial Processes, Research & Development, Electronics Manufacturing, Food Packaging End User: Manufacturers, Research Institutions, Laboratories, Hospitals Technology: Mechanical Pumps, Diffusion Pumps, Turbo Pumps, Ion Pumps |
| Companies Covered | ULVAC, Inc., Keller Technology Corporation, Pfeiffer Vacuum Technology AG, GNB Corporation, Terra Universal, Kurt J. Lesker Company, Leybold GmbH, LACO Technologies, MKS Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Chambers Market Strategic Shifts & Innovations
Increasingly, the market is shifting from treating chambers as passive containers to designing them as active, intelligent components within larger process systems. This evolution prioritizes integrated monitoring, advanced materials, and compliance with lifecycle-focused regulations to enhance performance and traceability.
Additive manufacturing using specialized metal powders is enabling the creation of chambers with complex internal features. Research labs and aerospace firms are early adopters, using 3D printing to build chambers with integrated cooling channels or unique geometries that are difficult or impossible to machine traditionally. The technology is automating the production workflow for bespoke, high-performance components, reducing lead times for designs that previously required significant manual fabrication and assembly.
European regulatory frameworks are forcing manufacturers to adopt a lifecycle approach to material management. Mandates like the Corporate Sustainability Reporting Directive (CSRD) require comprehensive documentation of a chamber's material origins, energy consumption in production, and end-of-life recyclability. This affects suppliers to the EU's semiconductor and medical device sectors most acutely, as they must now provide detailed material passports to maintain market access.
Buyers are progressively moving from sourcing standalone components to procuring fully integrated and pre-validated vacuum subsystems. This trend disrupts the traditional sales model where customers purchased chambers, pumps, and gauges from different vendors. The shift is most visible within the semiconductor equipment sector, where OEMs favor single-supplier solutions to simplify supply chain logistics and accelerate their time-to-market.
Vacuum Chambers Market Segmentation
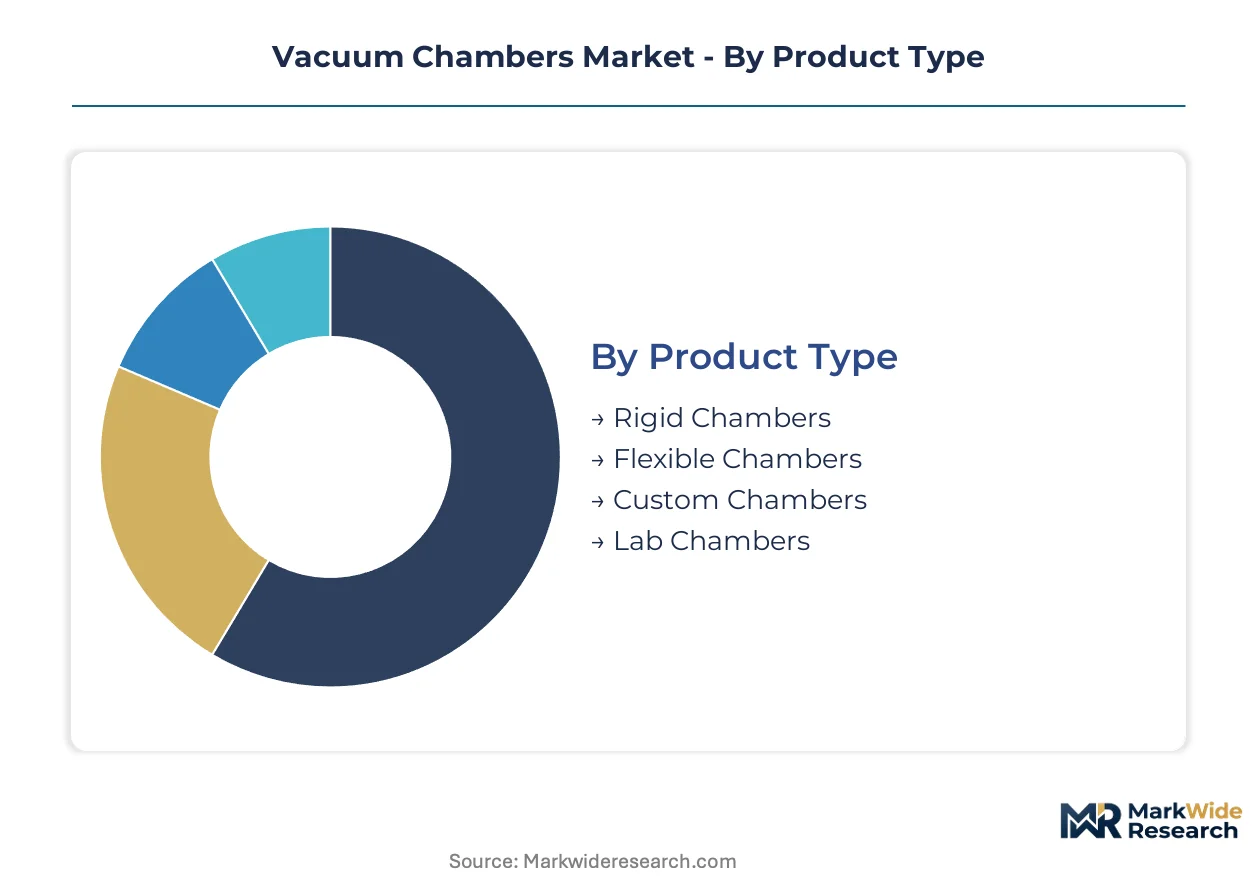
The vacuum chambers market segments reflect the diverse requirements of various industries, ranging from high-volume industrial production to highly specialized scientific research. Understanding these distinctions is crucial for manufacturers to tailor product offerings and strategic investments. Segmentation highlights the interplay between material science, engineering precision, and specific end-user demands for vacuum integrity.
Product Type:
The product type category delineates the market based on the degree of customization and physical characteristics, spanning from highly standardized vessels to bespoke engineering solutions.
- Rigid Chambers:These are robust, fixed-shape enclosures, typically made from stainless steel or aluminum, designed to withstand significant external pressure for industrial processes. Demand concentrates within high-volume electronics manufacturing, driven by the need for stable environments in semiconductor fabrication.
- Flexible Chambers:Constructed from pliable materials like plastic films, these chambers offer adaptability for packaging and some lower-grade vacuum applications. They provide cost-effective solutions for food packaging, particularly in emerging economies modernizing their preservation techniques.
- Custom Chambers:Engineered to specific client requirements, these chambers feature unique geometries, material compositions, and integrated functionalities for specialized research and development projects. These solutions command higher margins within national R&D initiatives, such as fusion energy research.
- Lab Chambers:Smaller, standardized vacuum enclosures used in educational and general laboratory settings for basic research and material science experiments.
Most installed capacity flows through Rigid Chambers. Expansion is steepest in Custom Chambers.
Application:
This segmentation highlights the primary end-use sectors driving demand, ranging from large-scale manufacturing to precision scientific endeavors.
The application segment distinguishes between high-volume, cost-sensitive industrial uses and specialized, performance-critical scientific deployments.
- Industrial Processes:This segment includes applications like heat treatment, coating, and material processing where vacuum environments enhance product quality and efficiency. Germany's advanced manufacturing hubs drive demand for these robust, high-throughput systems.
- Research & Development:Encompasses highly specialized uses in fields such as particle physics, material science, and quantum computing, requiring ultra-high vacuum conditions and custom chamber designs. Government-funded projects in countries like the UK and Germany specifically demand these performance-critical systems.
- Electronics Manufacturing:Critical for semiconductor fabrication, thin-film deposition, and display production, requiring extremely clean and stable vacuum environments to prevent contamination. South Korea's electronics clusters represent a significant demand center for these specialized chambers.
- Food Packaging:Utilizes vacuum technology for modified atmosphere packaging (MAP) and vacuum skin packaging (VSP) to extend shelf life and preserve food quality.
The primary demand driver for this category is the escalating need for precise atmospheric control across diverse industrial and scientific processes.
End User:
The end-user segment reflects the institutional and commercial entities that procure vacuum chambers, each with distinct purchasing criteria and operational needs.
This category differentiates based on the primary customer type, from large-scale production facilities to academic and healthcare institutions.
- Manufacturers:Industrial entities that integrate vacuum chambers into their production lines for processes like semiconductor fabrication, industrial coatings, and specialized material treatments. These users prioritize reliability and throughput.
- Research Institutions:Universities, national laboratories, and private R&D centers requiring advanced vacuum systems for scientific discovery and technological innovation. Their demand often focuses on custom, high-performance solutions.
- Laboratories:Smaller-scale research and testing facilities, including academic and commercial labs, that utilize vacuum chambers for material analysis, sample preparation, and controlled environment experiments. They often seek versatile, user-friendly equipment.
- Hospitals:Primarily use vacuum chambers for sterilization processes, medical device manufacturing, and some pharmaceutical applications, adhering to strict health and safety regulations.
Growth in this category is strongly correlated with investments in advanced manufacturing and scientific discovery.
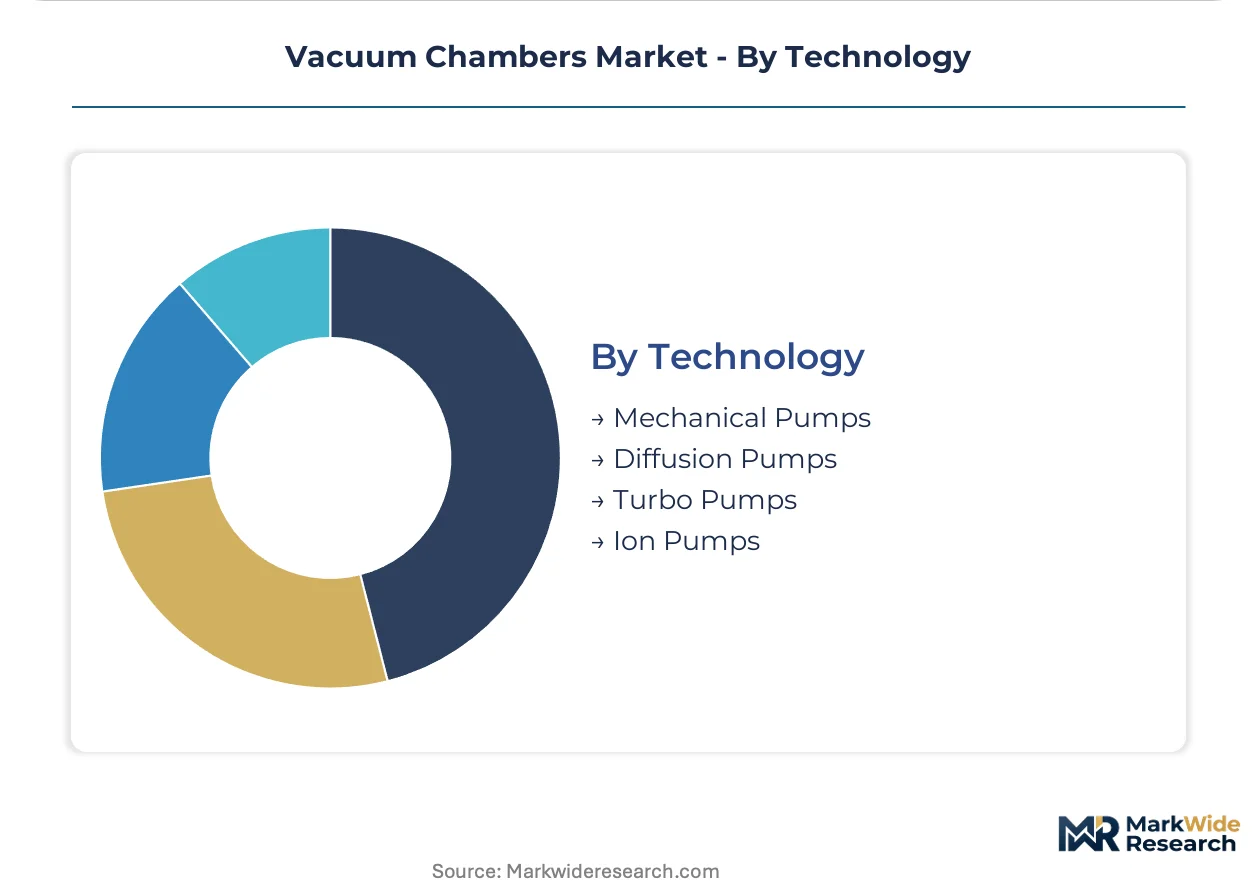
Technology:
The technology segment categorizes vacuum chambers based on the type of vacuum pump employed, directly influencing achievable vacuum levels and operational characteristics.
This category highlights the different pumping mechanisms used to achieve and maintain low-pressure environments, impacting performance and application suitability.
- Mechanical Pumps:These primary pumps, including rotary vane and scroll pumps, are used for rough and medium vacuum applications, often serving as backing pumps for high vacuum systems. They are essential for initial gas removal in many industrial processes.
- Diffusion Pumps:Employing a jet of high-speed vapor to entrain gas molecules, these pumps achieve high vacuum levels, particularly in older or less sensitive high-vacuum systems. They are commonly found in metallurgical applications.
- Turbo Pumps:Utilizing high-speed rotating blades, turbomolecular pumps create high and ultra-high vacuum conditions by imparting momentum to gas molecules. These pumps are critical for semiconductor manufacturing due to their cleanliness and high pumping speeds.
- Ion Pumps:These pumps achieve ultra-high vacuum by ionizing gas molecules and trapping them on active surfaces, offering extremely clean and vibration-free operation. They are indispensable for sensitive research applications like quantum computing.
The evolution of this category directly supports the pursuit of increasingly lower pressure environments for sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering expertise drives custom chamber demand, contrasting with South Korea's focus on high-volume electronics manufacturing. This divergence highlights distinct regional priorities and technological specializations within the global vacuum chambers market. Each geography contributes uniquely to market dynamics through specific industrial concentrations and regulatory frameworks.
Germany
German engineering expertise drives custom chamber demand for advanced manufacturing and R&D initiatives, particularly in fusion energy. The EU Green Deal mandates sustainable production practices, influencing material sourcing and energy consumption. The Stuttgart region concentrates on high-precision vacuum systems, serving industrial automation and specialized research. This area benefits from significant investment in next-generation industrial processes.
South Korea
South Korea's electronics clusters drive demand for high-volume vacuum chambers in semiconductor fabrication and display production. The MFDS guides standards for life science applications, indirectly influencing cleanliness and material specifications across advanced manufacturing. Gyeonggi Province houses major electronics manufacturing facilities, consistently requiring specialized, high-throughput systems. This concentration supports the nation's leadership in global electronics.
Japan
Japan's specialist fabricators focus on high-margin custom chamber production for advanced material science research and development. JIS standards govern industrial equipment, ensuring stringent quality and performance for these complex systems. The Tokyo region features a concentration of high-end research institutions and manufacturing facilities. These entities consistently demand bespoke solutions for cutting-edge applications.
United States
United States demand stems from sub-5-nanometer semiconductor node development and expanding space exploration missions. Federal R&D initiatives provide substantial funding for ultra-high vacuum systems critical to quantum computing research. Silicon Valley and Phoenix areas concentrate semiconductor manufacturing and aerospace testing facilities. These regions represent a significant market for both standard and highly customized vacuum solutions.
Vacuum Chambers Market Key Industry Players
German producers anchor one tier; Japanese specialists hold another in the vacuum chambers market. The market shows a fundamental divergence between industrial-scale production and specialized, high-margin custom fabrication. This split creates distinct competitive arenas. Large-scale industrial suppliers, specialized R&D fabricators, and integrated solution providers represent key strategic archetypes. Companies pursue technology licensing and strategic partnerships to expand their solution offerings and market reach.
Specialists in high-performance vacuum systems include Pfeiffer Vacuum Technology AG. Pfeiffer Vacuum Technology AG, a German AG, exemplifies engineering depth for complex R&D projects, leveraging extensive capabilities. Kurt J. Lesker Company, an American firm, represents comprehensive component catalogs and global logistics, differentiating through broad availability. MKS Instruments, Inc., another US-based corporation, anchors the integrated solutions segment by bundling chambers with proprietary instrumentation. These entities collectively demonstrate the market's segmentation by capability and customer service model, catering to diverse end-user requirements across various industries.
| Leading Market Players |
|---|
| ULVAC, Inc. |
| Keller Technology Corporation |
| Pfeiffer Vacuum Technology AG |
| GNB Corporation |
| Terra Universal |
| Kurt J. Lesker Company |
| Leybold GmbH |
| LACO Technologies |
| MKS Instruments, Inc. |
| Others |
Cost & Logistics Intelligence
Stringent cleanliness specifications from semiconductor manufacturers are forcing vacuum chamber suppliers to invest heavily in advanced material processing, directly influencing pricing for specialized solutions. This investment creates a bifurcated market where high-volume industrial chambers compete on cost, while custom R&D chambers command premium pricing due to engineering depth.
Pricing Analysis
Direct-to-OEM discounts characterize the high-volume rigid chamber segment, reflecting manufacturing scale efficiencies. Project-based pricing dominates custom chamber sales, driven by unique geometries and integrated functionalities. Price differentiation stems from the customization level and the specific vacuum-grade material used, such as 316LN stainless steel. Pricing pressure affects industrial-grade chambers due to manufacturing scale competition. Buyers in industrial processes exhibit the highest price sensitivity, while research institutions prioritize performance over cost for bespoke systems.
Supply Chain Analysis
Regional distribution centers facilitate the movement of standard vacuum components, while custom chambers often ship directly from specialized fabricators. Geographic supply concentration for advanced materials like forged aluminum alloys centers in Germany and Japan. Key raw material dependencies include vacuum-grade 316LN stainless steel and specialized seals. Material cost volatility presents a significant supply chain risk, impacting production expenses. Distribution runs through a hybrid model, combining direct sales for integrated solutions with a network of specialized distributors for components and standard chambers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vacuum chambers market is a stable compounder, driven by the continuous advancement in semiconductor technology and specialized R&D initiatives globally.
For Market Incumbents: Cement market leadership through continuous investment in UHV fabrication expertise and advanced material science. Focus on integrated solutions to counter component suppliers and simplify customer procurement. Invest in dual-certification processes (US FDA, EMA) to secure life sciences market access against stringent regulatory shifts. Expand capacity in Germany and Japan to leverage specialized labor pools.
For New Entrants and Emerging Players: Additive manufacturing capabilities offer a technology-first wedge for new entrants, enabling complex internal geometries for bespoke chambers. Target the research and development segment, particularly aerospace firms requiring unique thermal vacuum chambers. Offer rapid prototyping and specialized material options as a go-to-market angle, focusing on niche, high-performance applications. Prioritize cleanroom assembly protocols.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fabricators possessing unique UHV welding and cleanroom assembly skills. The market offers long-term viability, supported by sustained demand from semiconductor and advanced research sectors over the next decade. Target mid-sized companies with proprietary material science or integrated monitoring IP. The signal to watch is the increasing adoption of smart, sensor-embedded chambers for real-time process control.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Germany | Increases production capability for high-precision custom vacuum chambers, serving advanced R&D. |
| Green Manufacturing Transition | Ensures compliance with EU Green Deal mandates, enhancing market access for European clients. |
| Product Launch: Integrated Smart Chambers | Offers customers real-time process monitoring and predictive maintenance, adding significant value. |
| Strategic Partnership with Instrumentation Providers | Simplifies supply chains for OEMs seeking fully integrated vacuum subsystems. |
| Certification Investment for Life Sciences | Secures market access for pharmaceutical and medical device applications under US FDA and EMA regulations. |
Research Approach
Multiple input streams — primary interviews, secondary research, and industry databases — were reconciled to construct a comprehensive market view. Engagement with R&D directors, procurement managers in electronics, and regulatory affairs specialists provided qualitative insights. Secondary data from government reports, scientific journals, company filings, and ISO standards documentation validated quantitative findings through bottom-up and top-down triangulation.
Data stream reconciliation involved modeling market segments by product type, application, end-user, and technology, including vacuum level, across the analysis window. Demand for custom chambers in fusion energy and semiconductor fabrication provided key inputs for CAGR derivation. Volume and value projections were refined using historical data and industry-specific growth catalysts, such as sub-5-nanometer node transitions and R&D funding allocations.
The model holds under current geopolitical stability and material supply conditions; deviation in global trade policies or raw material availability would shift projections. Forecasts reflect documented assumptions regarding technological adoption and regulatory compliance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Vacuum Coating Equipment Market