
 Utility Trucks Market | 2026-2036
Utility Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Trucks Market Intelligence
The rising importance of the telecommunications sector for 5G infrastructure deployment is rebalancing demand away from traditional construction applications. Ford Motor Company leverages its dominance in light and medium-duty platforms for service truck configurations. Daimler Truck AG specializes in heavy-duty vocational chassis for complex utility tasks. Meanwhile, General Motors competes across multiple size classes with its extensive commercial vehicle portfolio.
Utility trucks are commercial vehicles configured with specialized bodies and equipment for vocational work. These configurations, such as aerial lifts or service bodies, are mounted on chassis with specific gross vehicle weight ratings to support their intended function. While diesel-powered service trucks constitute a large portion of the market, electric models are the fastest-growing sub-segment by fuel type. Medium-duty trucks show significant demand from public works and landscaping end users who require a balance of payload and maneuverability.
Emissions regulations from the US Environmental Protection Agency and directives within the EU Green Deal directly influence powertrain development. Concurrently, standards from China's MEE and worker safety rules from bodies like OSHA in the United States govern vehicle manufacturing and operational safety. Fleet operators now face a critical decision regarding the optimal timing for capital investment in electric powertrains versus maintaining existing diesel assets.
Market Dynamics
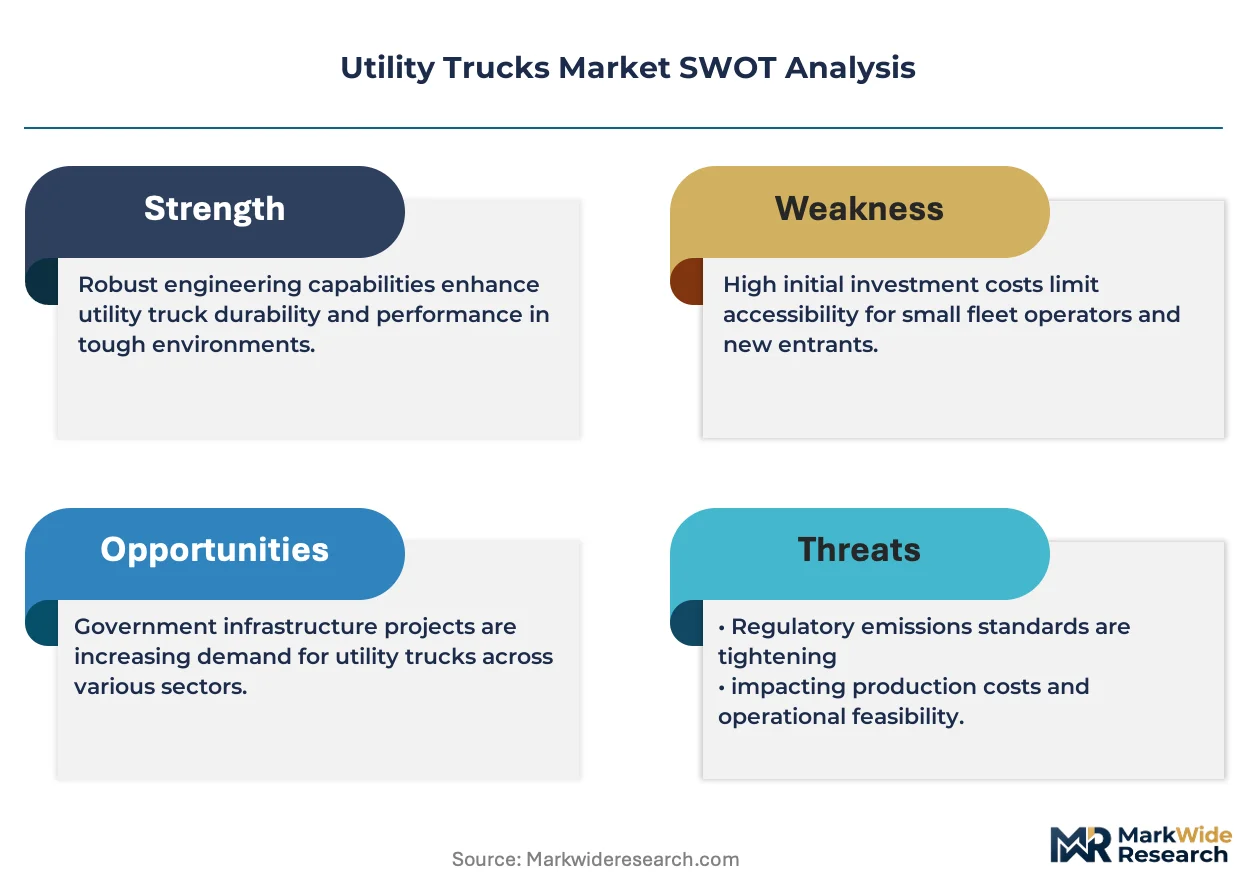
The utility truck market's evolution is governed by the concurrent expansion of telecommunications infrastructure and the regulatory push for powertrain electrification. This dual pressure forces fleet operators to balance immediate operational needs against long-term capital investment and compliance strategies.
Growth Catalysts
- Regulatory Mandates:Directives within the EU Green Deal and similar policies in the United States are accelerating the replacement of aging diesel fleets with electric models, particularly within municipal public works departments.
- 5G Network Deployment:The global build-out of 5G infrastructure requires extensive use of aerial lift and service trucks for installing and maintaining cellular equipment, creating sustained demand from the telecommunications sector.
- Battery Technology Advancement:Improvements in lithium-ion battery energy density and the expansion of fast-charging networks are increasing the operational viability of electric utility trucks for demanding, full-day duty cycles.
Market Restraints
- High Capital Outlay:The initial acquisition cost for electric utility trucks remains significantly higher than for their diesel-powered equivalents, presenting a substantial barrier for budget-constrained municipalities and small contractors.
- Charging Infrastructure Gaps:The lack of robust and accessible high-capacity charging stations in rural and remote service territories limits the practical deployment of battery-electric models for many utility operators.
- Specialized Component Scarcity:Supply chain bottlenecks for critical components like high-voltage battery packs and power management modules for commercial vehicles constrain manufacturers' production capacity for new electric models.
Strategic Opportunities
- Vehicle-to-Grid (V2G) Applications:Developing electric utility trucks with bidirectional charging capabilities creates a new value proposition, allowing fleets to serve as mobile power sources during grid outages or for peak shaving.
- Infrastructure Renewal in Developing Economies:Large-scale public works and grid modernization projects in countries across South America and Southeast Asia represent a significant, underpenetrated market for new utility vehicle sales.
- Integrated Safety Systems:The convergence of telematics with advanced driver-assistance systems (ADAS) offers an opportunity to create premium vehicle packages that enhance compliance with worker safety rules from bodies like OSHA.
Industry Challenges
- Technician Skill Gaps:A widespread shortage of mechanics and technicians trained to diagnose and service the high-voltage electric powertrains and complex software systems of modern utility trucks creates maintenance backlogs.
- Upfit Integration Complexity:Ensuring seamless mechanical and software integration between new electric chassis and the diverse array of specialized third-party bodies, such as aerial lifts and cranes, is a major engineering hurdle.
- Navigating Divergent Standards:Vehicle manufacturers face significant design and compliance costs in developing platforms that can meet disparate emissions and safety regulations from the US EPA, the EU, and China's MEE.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Trucks Market |
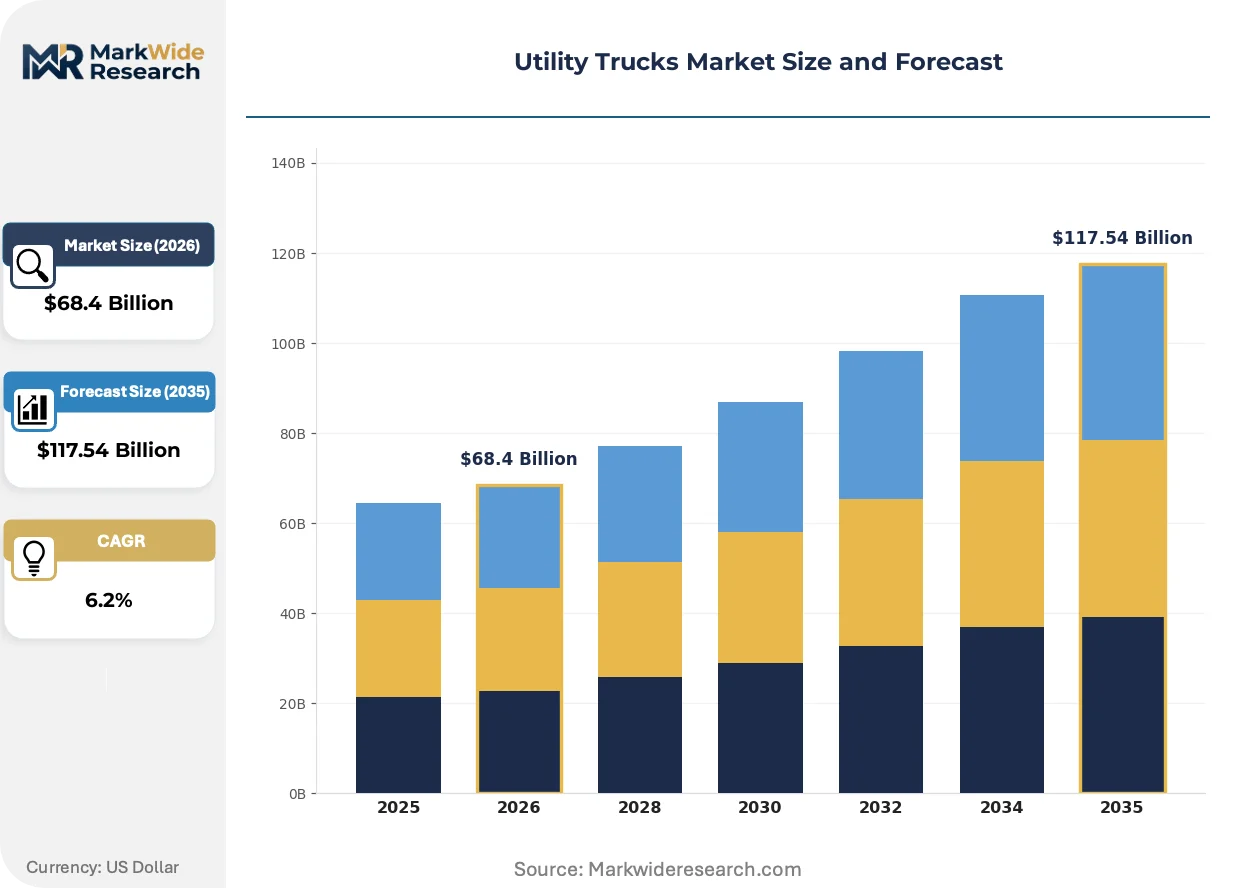
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Type: Box Truck, Dump Truck, Flatbed Truck, Service Truck Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Construction, Public Works, Landscaping, Telecommunications Size: Light Duty, Medium Duty, Heavy Duty, Super Heavy Duty |
| Companies Covered | Daimler Truck AG, Ford Motor Company, General Motors, FCA US LLC, TOYOTA MOTOR CORPORATION, ISUZU MOTORS LIMITED, NISSAN USA, Mack Trucks, NAVISTAR, INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Trucks Market Strategic Shifts & Innovations
The convergence of advanced telematics with powertrain electrification is transforming the functional role of utility trucks. These vehicles are evolving from single-purpose tools into connected, data-generating assets that are integral to modernizing grid management and telecommunications infrastructure.
Vehicle-to-Grid (V2G) technology enables electric utility trucks to function as mobile batteries, feeding power back to the grid or a specific site. Utility companies and municipal fleet operators are the earliest adopters, valuing the potential for emergency power response and grid stabilization services. This capability is electrifying the fundamental purpose of a work truck, converting it from a pure energy consumer into a distributed energy resource.
Emissions regulations, including standards from the US Environmental Protection Agency and China's MEE, are compelling a fundamental redesign of commercial vehicle powertrains. This shift directly impacts engine and aftertreatment system development, forcing investment away from traditional diesel and toward battery-electric and hydrogen fuel cell alternatives. The medium-duty truck segment is most affected, as it sits at the intersection of urban operational requirements and stringent clean-air mandates.
A notable behavioral shift involves fleet managers prioritizing Total Cost of Ownership (TCO) over initial sticker price in their acquisition strategies. This favors vehicles with lower fuel and maintenance costs, even if the upfront capital expenditure is higher, disrupting traditional procurement patterns centered on lowest-bid wins. This TCO-focused approach is most visible among large public utility and telecommunications fleets in North America and Europe.
Utility Trucks Market Segmentation
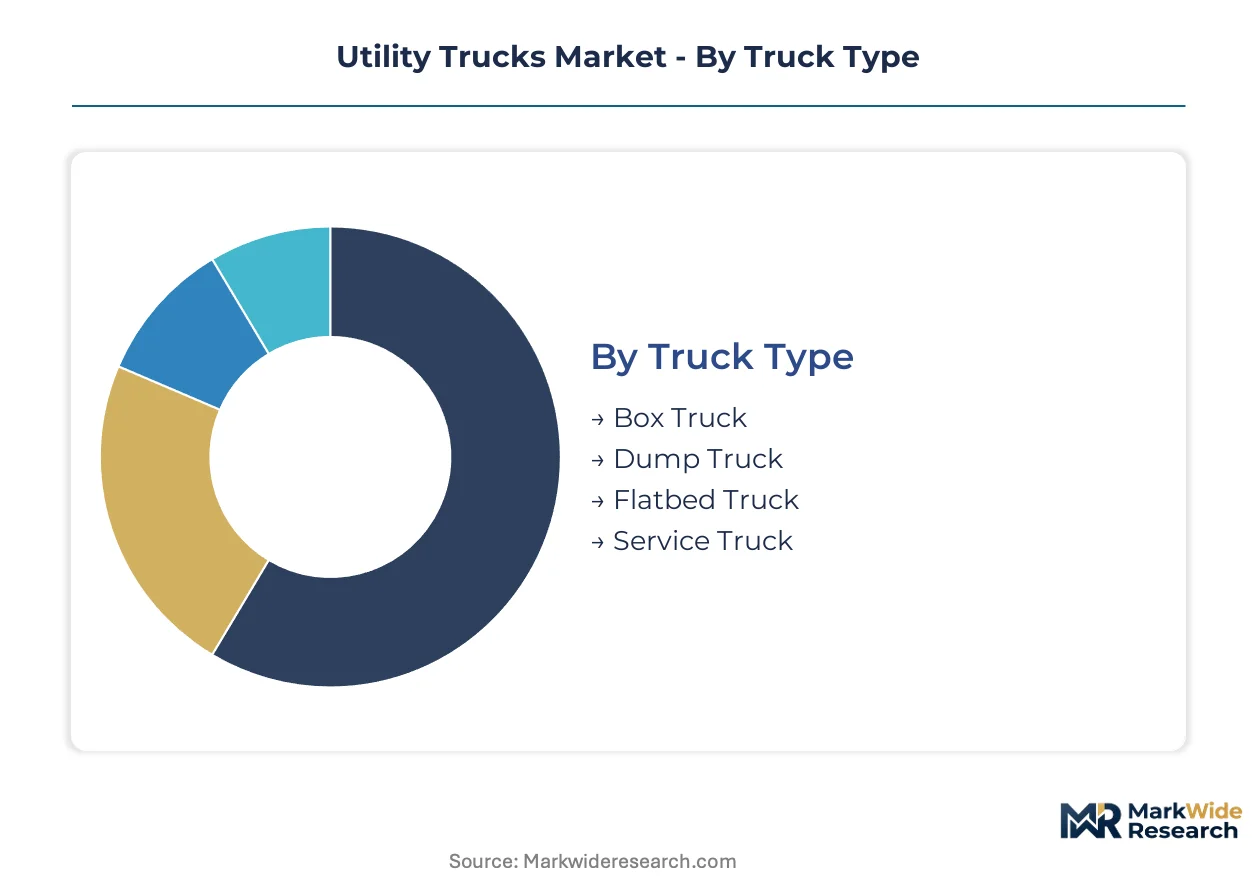
The utility trucks market segmentation clarifies how diverse vehicle configurations and powertrain technologies address specific operational needs across various industries. Understanding these distinctions is crucial for manufacturers to align product development with end-user requirements and for fleet operators to optimize procurement strategies.
Truck Type:
The truck type classification highlights the specialized configurations tailored for distinct operational requirements.
- Service Truck:These vehicles feature enclosed bodies with external compartments and often include cranes or aerial lifts for field maintenance. Demand concentrates in telecommunications and municipal public works for infrastructure upkeep.
- Dump Truck:Designed for bulk material transport, these trucks feature an open-box bed with hydraulic hoists for unloading aggregates or debris. Public works departments and construction companies widely deploy them for site preparation and waste removal.
- Box Truck:Enclosed cargo areas protect equipment and tools, commonly used by delivery services and mobile workshops.
- Flatbed Truck:An open, flat cargo area facilitates the transport of oversized or irregularly shaped equipment for construction and utility projects.
Dump Truck leads on scale; Service Truck leads on momentum.
Fuel Type:
The fuel type segmentation reflects the market's response to evolving environmental standards and operational efficiency demands.
- Electric:These powertrains utilize battery-electric systems, offering zero tailpipe emissions and reduced operational noise. Demand is accelerating in urban public works fleets and for last-mile utility operations due to stringent emissions regulations from the US EPA and EU Green Deal.
- Diesel:Traditional internal combustion engines power these trucks, known for their high torque and long-range capabilities, particularly in heavy-duty applications. Construction and long-haul utility services continue to rely on diesel for demanding duty cycles.
- Gasoline:These engines are common in lighter duty utility vehicles, providing lower upfront costs for smaller fleet operators.
- Hybrid:Combining an internal combustion engine with an electric motor, these trucks offer improved fuel efficiency for specific duty cycles.
Diesel powertrains account for the largest volume; electric models are expanding most quickly.
End User:
The end-user classification highlights the specific operational demands driving utility truck configurations and equipment choices.
- Telecommunications:This sector deploys utility trucks for installing, maintaining, and repairing communication infrastructure, including fiber optics and 5G networks. Extensive 5G build-out across the United States and Europe drives significant demand for aerial lift trucks.
- Public Works:Municipal and government entities utilize these vehicles for maintaining public infrastructure, including roads, water systems, and electrical grids. Upgrades to aging infrastructure within US municipalities significantly influence procurement patterns.
- Construction:This segment employs utility trucks for material transport, site preparation, and equipment delivery on various building projects.
- Landscaping:Utility trucks support landscaping operations with equipment hauling, debris removal, and tree care services.
Public Works holds a substantial market share; Telecommunications is gaining share fastest.
Size:
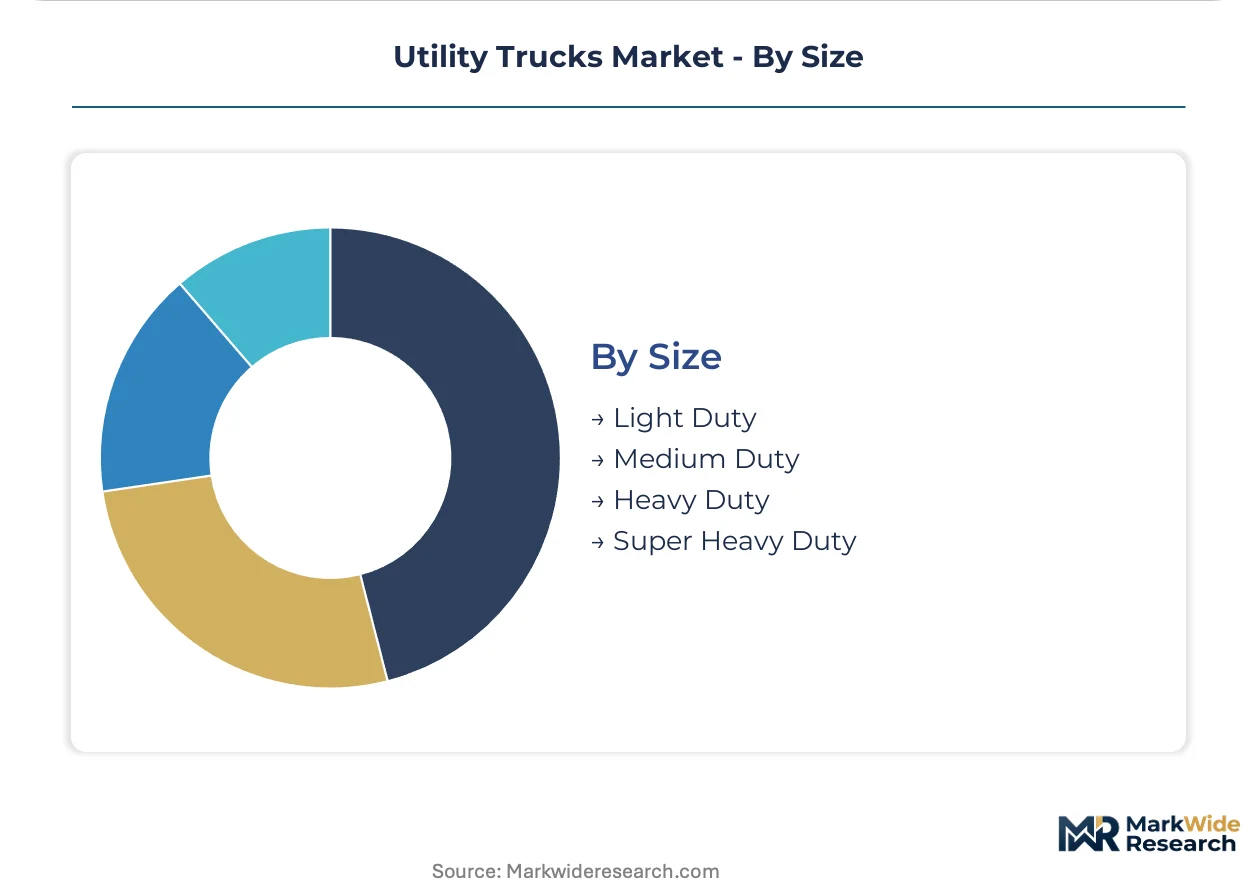
The size segmentation categorizes utility trucks based on their Gross Vehicle Weight Rating (GVWR) and intended payload capacity.
- Medium Duty:These trucks balance payload capacity with maneuverability, making them suitable for urban utility work and public works applications. Public works and landscaping end users exhibit significant demand for this versatile size class.
- Heavy Duty:Designed for substantial payloads and complex vocational tasks, these chassis often support large cranes or specialized aerial devices. Daimler Truck AG specializes in these configurations for demanding utility operations.
- Light Duty:These vehicles are typically used for smaller service tasks and material transport, offering agility for urban environments.
- Super Heavy Duty:Employed for extreme payloads and specialized industrial applications, these trucks represent the upper echelon of utility vehicle capacity.
Medium Duty trucks offer superior operational flexibility; Heavy Duty trucks provide maximum vocational capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global utility trucks market exhibits a dynamic where production and deployment strategies are increasingly influenced by a regulatory-arbitrage angle. Manufacturers and fleet operators navigate diverse emissions standards and electrification mandates across key regions. This creates a complex environment for capital investment and market penetration.
United States
Demand for utility trucks in the United States is driven by municipal public works upgrades and extensive 5G network build-out. The US Environmental Protection Agency's stringent emissions standards accelerate the transition to electric models, particularly for urban fleets. Major telecommunications and infrastructure projects in states like California and Texas require a significant influx of specialized service vehicles.
China
China's infrastructure development and rapid urbanization fuel substantial demand for dump trucks and service vehicles. The Ministry of Ecology and Environment (MEE) regulations push for cleaner commercial vehicle powertrains, impacting local manufacturers. Industrial clusters in the Yangtze River Delta are seeing increased production and deployment of electric utility truck prototypes for municipal services.
Germany
Germany's robust industrial base and focus on renewable energy infrastructure create strong demand for heavy-duty utility trucks. The EU Green Deal directives encourage the adoption of zero-emission vehicles, influencing public sector procurement. Major automotive manufacturing hubs in Bavaria and Baden-Württemberg are centers for innovation in electric and hydrogen fuel cell truck development.
India
Infrastructure renewal projects and the expansion of telecommunications networks across India are significant demand drivers. The country's vehicle emission standards, aligned with Bharat Stage norms, are gradually pushing fleet operators towards more efficient models. Urban centers like Mumbai and Delhi are experiencing a surge in demand for medium-duty trucks for utility maintenance and construction.
Brazil
Brazil's extensive agricultural sector and ongoing public works projects generate consistent demand for various utility truck types. National environmental policies, though less stringent than in Europe, still promote the use of more fuel-efficient and lower-emission vehicles. The industrial heartland around São Paulo is witnessing increased investment in local production capabilities for specialized vocational chassis.
Utility Trucks Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers broaden their offerings to capture demand across various utility truck segments. The market structure exhibits a tiered consolidation, with a few global giants competing across multiple size classes. Strategic archetypes include full-line commercial vehicle producers, specialized vocational chassis builders, and new entrants focused solely on electric powertrains. Capacity expansion in electric vehicle production and strategic partnerships for battery supply chains are key competitive moves.
Companies like Daimler Truck AG exemplify the specialized vocational chassis builder archetype, focusing on heavy-duty applications requiring robust platforms for complex utility tasks. Ford Motor Company, with its extensive commercial vehicle portfolio, represents the full-line producer, leveraging its dominance in light and medium-duty platforms for service truck configurations across various end-user segments. General Motors also occupies a significant position across multiple size classes, offering a broad range of commercial vehicles to meet diverse utility needs, from municipal public works to telecommunications infrastructure deployment.
| Leading Market Players |
|---|
| Daimler Truck AG |
| Ford Motor Company |
| General Motors |
| FCA US LLC |
| TOYOTA MOTOR CORPORATION |
| ISUZU MOTORS LIMITED |
| NISSAN USA |
| Mack Trucks |
| NAVISTAR, INC. |
Cost & Logistics Intelligence
Municipal public works departments and large telecommunications fleets increasingly prioritize total cost of ownership over initial sticker price, driving a shift towards value-based pricing for utility trucks. This procurement change influences manufacturers' product development and service bundling strategies.
Pricing Analysis
Distributor margins for utility trucks are influenced by specialized upfits and regional service requirements. The dominant pricing model involves per-unit transactional sales for standard diesel models, evolving towards value-based contracts for electric variants that bundle charging and maintenance. Price differentiation stems from the customization level for vocational tasks and the comprehensiveness of after-sales service packages. Pricing pressure for diesel models reflects competition, while the high capital outlay for electric trucks creates a barrier for budget-constrained buyers; small contractors are most price-sensitive, while large public utility fleets are least sensitive.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of utility trucks, particularly for specialized components. Geographic supply concentration includes China for battery packs and power management modules, and Germany for heavy-duty vocational chassis. The industry draws from inputs like high-voltage battery packs and advanced power management modules; supply chain bottlenecks for these components present a structural risk. Distribution runs through direct sales channels for large public utility fleets and extensive dealer networks for smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The utility trucks market presents a margin-expansion opportunity, driven by the premiumization of electric powertrains and value-added service bundles. This shift allows manufacturers to capture higher value beyond traditional vehicle sales.
For Market Incumbents: Anchor existing market share by accelerating investment in electric powertrain R&D and expanding charging infrastructure partnerships. Incumbents should also acquire specialized upfitters to ensure seamless integration of electric chassis with vocational bodies, mitigating the threat from new electric vehicle entrants. Deepening vertical integration into critical component supply chains, such as power management modules, can also safeguard production capacity. Channel control through established dealer networks remains a key lever against emerging competition.
For New Entrants and Emerging Players: Online configurators and direct-to-fleet sales models offer new entrants a path to market penetration, bypassing traditional dealer networks. Target the medium-duty electric truck segment for urban public works in the United States, where emissions regulations create a strong demand pull. Focus on offering integrated solutions that bundle electric vehicles with charging infrastructure and telematics. Value propositions centered on Vehicle-to-Grid (V2G) capabilities can differentiate offerings in this underpenetrated segment.
For Investors and Strategic Acquirers: Automotive OEMs and diversified industrial conglomerates are the most active acquirers in this space, seeking to expand their electric commercial vehicle portfolios. Long-term viability is strong, as decarbonization mandates ensure sustained demand for electric utility trucks over the next decade. Acquisition targets should include specialized electric chassis manufacturers or advanced battery technology developers. The signal to watch is the expansion of fast-charging networks and the standardization of upfit integration protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Battery Technology R&D | Accelerating energy density and charging speeds makes electric utility trucks more viable for full-day duty cycles. |
| Develop V2G-Enabled Truck Platforms | Bidirectional charging capabilities create new revenue streams for fleet operators through grid stabilization services. |
| Partner with Telecommunications Infrastructure Providers | Securing long-term contracts with 5G network builders ensures sustained demand for specialized aerial lift trucks. |
| Acquire Specialized Upfitting Companies | Seamless integration of electric chassis with vocational bodies addresses a key engineering challenge for manufacturers. |
| Expand Fast-Charging Network Collaborations | Robust charging infrastructure supports the widespread deployment of battery-electric utility trucks in rural and urban areas. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with fleet managers, public works directors, and commercial vehicle engineers were validated against secondary research. Secondary sources included government emissions reports from the US EPA and China's MEE, commercial vehicle production databases, and industry association publications. This approach ensured comprehensive data triangulation and robust market sizing.
The input-output matrix framing utilized a multi-variable regression model to project market dynamics across the analysis window. Segmentation dimensions modeled included truck type, fuel type, end user, size, and regional deployment patterns. Compound annual growth rates were derived from historical trends and projected future demand. Key industry-specific forecast inputs included 5G network build-out schedules and electric vehicle charging infrastructure development.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell trucks would alter the outlook. Forecasts reflect current assumptions regarding geopolitical stability and regulatory environments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Hydrogen Trucks Market