
 Asia Pacific Garbage Truck Bodies Market | 2026-2036
Asia Pacific Garbage Truck Bodies Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Garbage Truck Bodies Market Insights
China's manufacturing corridor is rewriting capacity dynamics for garbage truck body fabrication across the Asia Pacific. Fulongma leverages its domestic supply chain density to dominate rear-loader assembly lines for municipal tenders. BYD Motors anchors its position through electric chassis integration with proprietary body designs. Shinmaywa Industries competes on alloy-intensive compaction mechanisms that reduce tare weight for Japanese operator specifications.
Garbage truck bodies constitute hydraulically actuated enclosures mounted on commercial chassis, engineered with high-tensile steel or aluminum alloys to withstand cyclic compression loads exceeding twenty tons per operating shift. Their primary purpose centers on mechanized collection, temporary containment, and in-transit compaction of municipal solid waste to maximize payload density per route. Rear loader configurations command the largest installed base across Asia Pacific municipal fleets due to compatibility with manual bin tipping and automated arm interfaces. Aluminum material adoption is accelerating fastest among operators prioritizing fuel economy and electric range extension, though steel retains margin dominance in price-sensitive bulk procurement channels. Composite-reinforced panels occupy a niche premium tier serving coastal municipalities with corrosive atmospheric exposure.
India's BIS structural standards, Japan's JIS automotive regulations, and China's GB vehicle safety codes collectively dictate welding protocols, hydraulic pressure ratings, and crashworthiness testing for body-chassis integration. These frameworks elevate capital requirements for new entrants while rewarding incumbents with certified in-house testing facilities. Stakeholders must monitor divergence between national electrification timelines and chassis availability to align body production capacity with zero-emission fleet transitions.
Market Dynamics
Electrification mandates across Asia Pacific municipal fleets are compressing body-chassis integration timelines and forcing fabricators to retool welding lines for aluminum-intensive designs compatible with electric range constraints.
Growth Catalysts
- India's Smart Cities Mission:Urban local bodies in 100 designated cities are tendering mechanized waste collection fleets, creating dedicated demand for rear-loader configurations with automated arm interfaces.
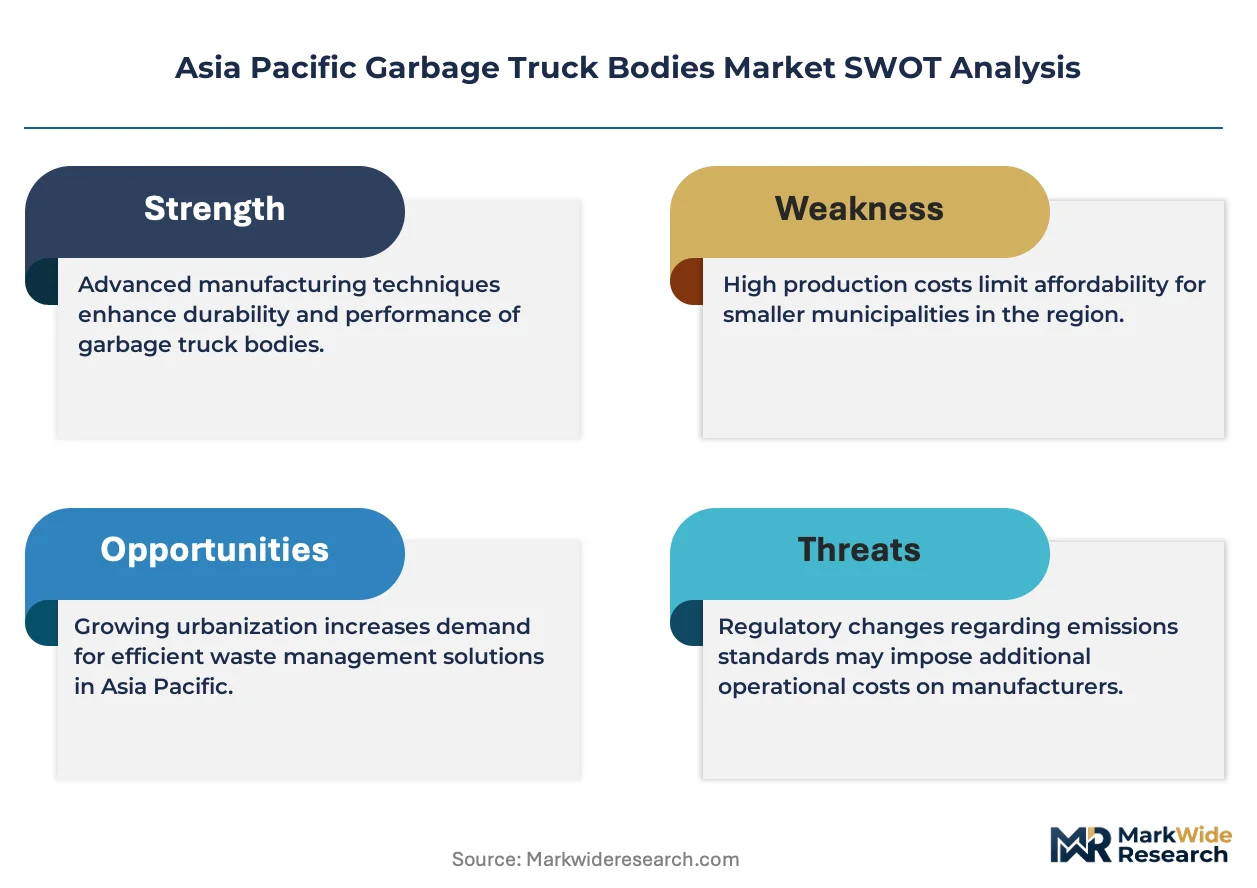
- BIS structural certification:Mandatory crashworthiness testing for body-chassis integration is filtering out uncertified suppliers and consolidating procurement toward accredited fabricators.
- Aluminum alloy substitution:High-tensile aluminum panels are displacing steel in premium municipal tenders where fuel economy and payload optimization drive total cost of ownership calculations.
Market Restraints
- Steel price volatility:Hot-rolled coil input costs fluctuate with regional scrap metal flows, compressing margin buffers for fabricators locked into fixed-price municipal contracts.
- Chassis supply concentration:Commercial electric chassis availability remains concentrated among three domestic suppliers, creating bottleneck risk for body builders awaiting platform deliveries.
- Hydraulic system import dependency:High-pressure compaction cylinders and valve assemblies rely on Japanese and German component sources, exposing assemblers to currency and lead-time volatility.
Strategic Opportunities
- Vietnam's secondary cities:Provincial capitals outside Hanoi and Ho Chi Minh City lack mechanized collection coverage, presenting first-mover expansion potential for rear-loader suppliers.
- Composite-reinforced coastal variants:Fiberglass-skinned aluminum honeycomb panels address corrosion exposure in Philippine and Indonesian port cities, commanding 40-60% price premiums over standard steel.
- Japan's carbon-neutral port initiatives:METI-funded fleet electrification at Yokohama and Kobe is creating demand for lightweight bodies optimized for BYD and Hino electric chassis.
Industry Challenges
- Certification timeline compression:BIS crash testing and JIS weld qualification cycles now overlap with tender deadlines, forcing fabricators to maintain parallel prototype pipelines.
- Aluminum welding skill scarcity:TIG and friction-stir welding expertise for thin-gauge structural alloys remains concentrated among Japanese and Korean technician pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Garbage Truck Bodies Market |
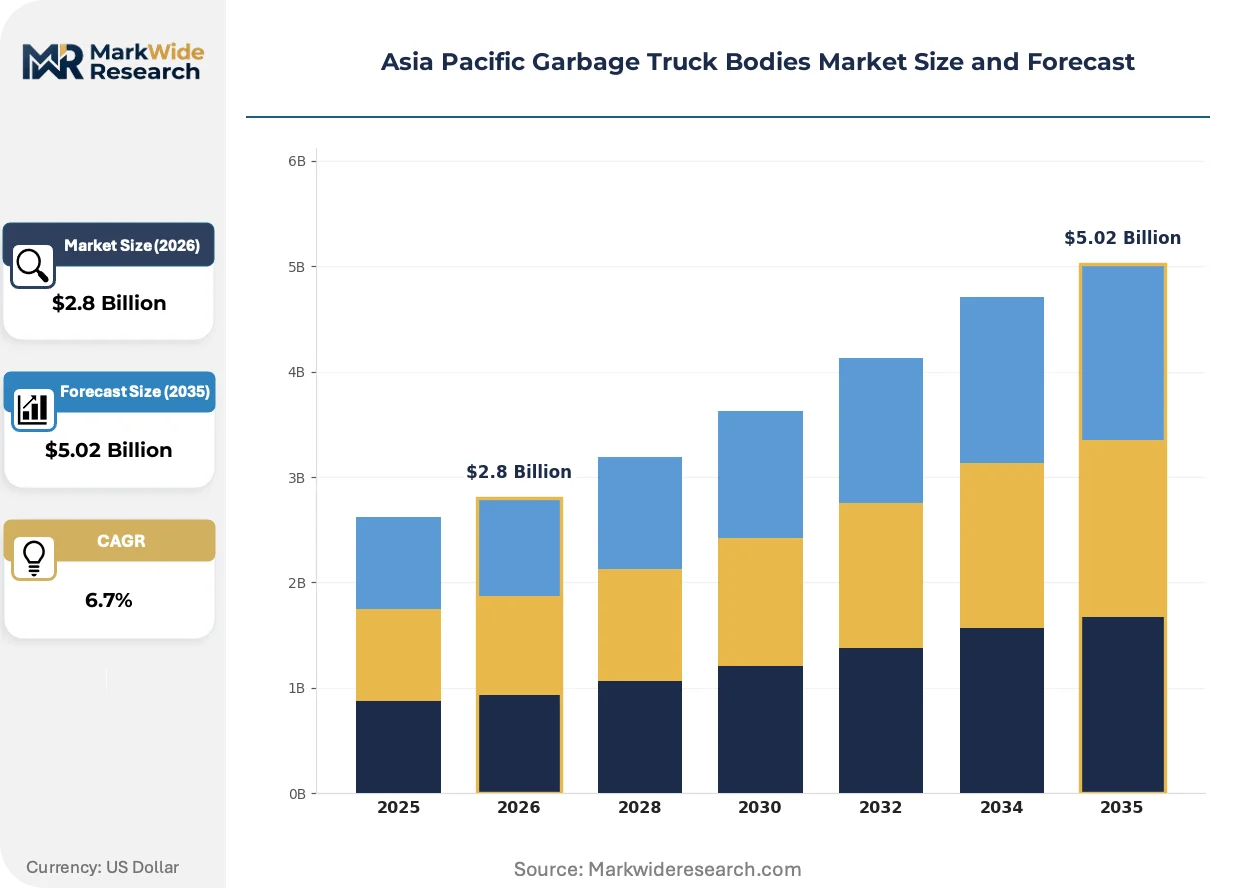
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear Loader, Side Loader, Front Loader, Compactor Material: Steel, Aluminum, Composite, Fiberglass Capacity: 5-10 Cubic Yards, 11-15 Cubic Yards, 16-20 Cubic Yards, Above 20 Cubic Yards Application: Municipal Use, Commercial Use, Construction Waste, Industrial Waste |
| Companies Covered | Fulongma, BYD Motors, Shinmaywa Industries, Mitsubishi Fuso Truck and Bus Corporation, Dongfeng Motor Corporation, Ashok Leyland, Volvo, Isuzu Motors, TATA Motors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Garbage Truck Bodies Market Trends and Innovations
Telematics integration and predictive maintenance systems are rewriting fleet operator expectations for garbage truck body performance monitoring and route optimization across Asia Pacific municipal contracts.
Sensor-embedded compaction mechanisms are digitizing payload monitoring and hydraulic health diagnostics. Municipal fleet managers in Singapore and Sydney are mandating real-time fill-level transmission for dynamic route dispatch. This connectivity layer is digitizing traditional body specifications into data-service bundles that favor suppliers with software development capabilities.
China's GB standards for commercial vehicle electrification are accelerating aluminum body adoption to offset battery weight penalties. Provincial environmental regulators in Guangdong and Jiangsu now require electric chassis compatibility in municipal tender technical specifications. Fabricators without certified aluminum welding protocols are losing eligibility for tier-one urban contracts.
Lifecycle service contracting is displacing upfront equipment procurement in Australian and Japanese municipal markets. Operators in Melbourne and Osaka are unbundling body maintenance from chassis warranties, creating aftermarket revenue pools for specialist fabricators with regional service networks. This shift is most visible where total cost of ownership modeling dominates tender evaluation criteria.
Asia Pacific Garbage Truck Bodies Market Segmentation
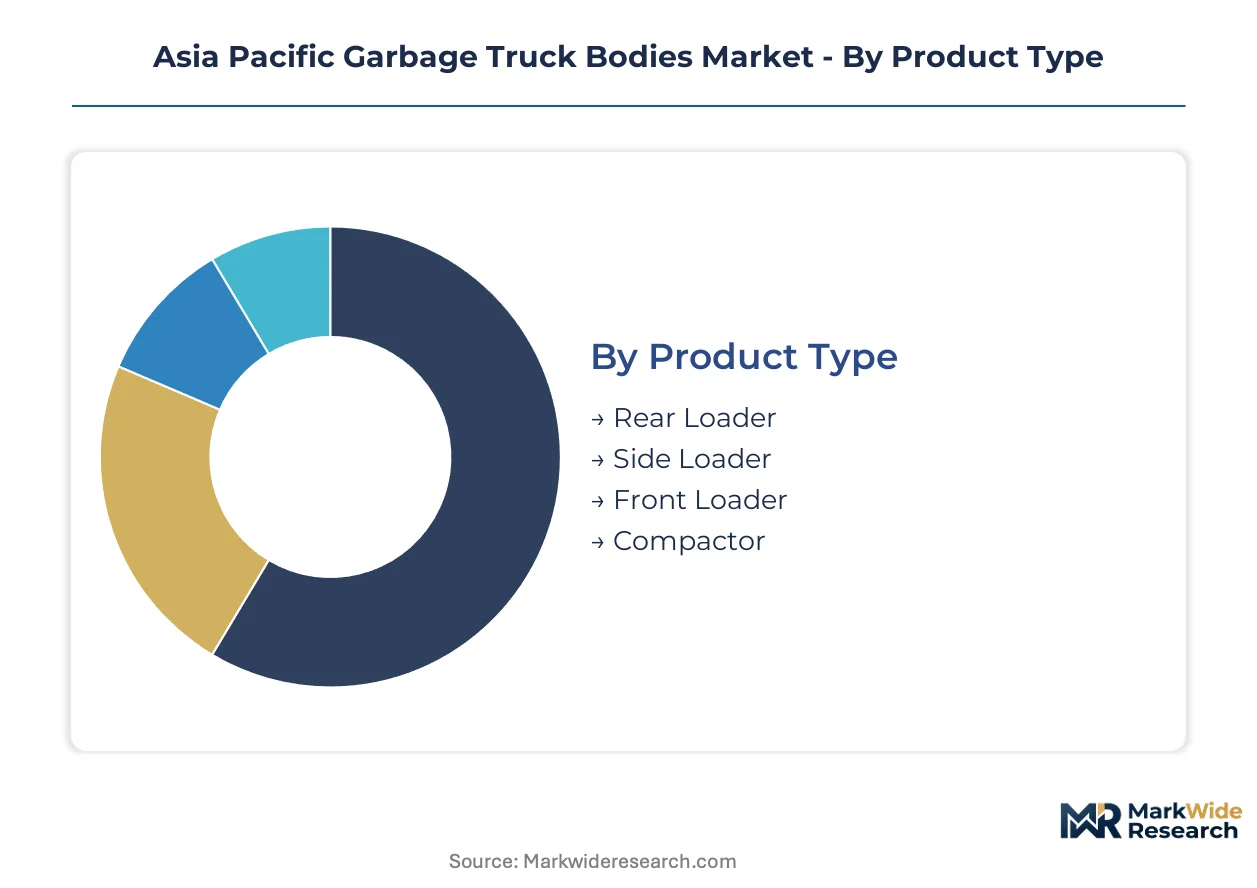
Garbage truck body specifications diverge sharply across Asia Pacific operating environments, from dense urban corridors requiring compact maneuverability to sprawling industrial zones demanding maximum payload volume. Procurement patterns in this market track municipal budget cycles, electrification mandates, and corrosion exposure levels that reshape material preferences by geography.
Product Type:
Rear loaders anchor municipal fleet specifications across Southeast Asian smart city tenders, while front loaders capture commercial and industrial contracts with standardized container systems.
- Rear Loader:Hydraulically actuated tailgate mechanisms with automated arm interfaces dominate urban waste collection in Indian municipal corporations and Vietnamese provincial capitals. Demand concentrates where manual bin tipping remains prevalent and labor costs favor semi-automated loading over fully automated alternatives.
- Side Loader:Curbside automated collection systems with single-operator capability are gaining traction in Australian and Japanese municipalities facing driver shortage pressures. Sydney and Melbourne fleet operators specify these configurations for residential route density optimization.
- Front Loader:Heavy-duty container lift systems serve commercial waste streams and construction debris in Chinese industrial zones.
- Compactor:Stationary and self-contained compaction units address high-volume retail and hospitality waste in Philippine shopping mall districts.
The dominant share belongs to Rear Loader configurations, while Side Loader specifications are closing the gap fastest in premium municipal tenders.
Material:
Material selection hinges on the trade-off between acquisition cost and lifecycle operating economics, with electrification timelines accelerating lightweight adoption.
- Steel:Hot-rolled high-tensile carbon steel panels withstand impact damage and abrasive waste streams in price-sensitive Indian and Indonesian bulk procurement. Margins compress when scrap metal volatility coincides with fixed-price municipal contracts.
- Aluminum:Thin-gauge structural alloys reduce tare weight by 30-40% compared to steel equivalents, extending electric chassis range in Guangdong and Jiangsu provincial tenders. Welding protocol certification under China's GB standards filters out uncertified fabricators.
- Composite:Fiberglass-reinforced honeycomb panels command premium pricing in coastal Indonesian and Philippine port cities.
- Fiberglass:Gel-coated corrosion barriers serve niche applications in chemical processing waste and marine atmospheric exposure.
Steel retains volume leadership in aggregate fleet procurement, though Aluminum is expanding most quickly in electrification-mandated urban contracts.
Capacity:
Route density and chassis payload ratings dictate cubic yard specifications, with electric range constraints favoring smaller, more frequent collection cycles.
- 5-10 Cubic Yards:Compact rear loaders navigate narrow lanes in historic districts of Kyoto, Hoi An, and Penang heritage zones. Japanese operators specify these dimensions for residential alleyway access where turning radius limits apply.
- 11-15 Cubic Yards:Mid-range configurations balance payload efficiency with maneuverability in secondary Chinese cities and Thai provincial capitals.
- 16-20 Cubic Yards:High-volume compaction chambers serve commercial districts and industrial parks in Bangalore and Ho Chi Minh City.
- Above 20 Cubic Yards:Maximum-density designs address construction demolition waste and bulk commercial streams in Australian mining towns and Chinese special economic zones.
The 11-15 cubic yard bracket holds the largest installed base, while 5-10 cubic yard specifications are climbing the fastest under zero-emission fleet transitions.
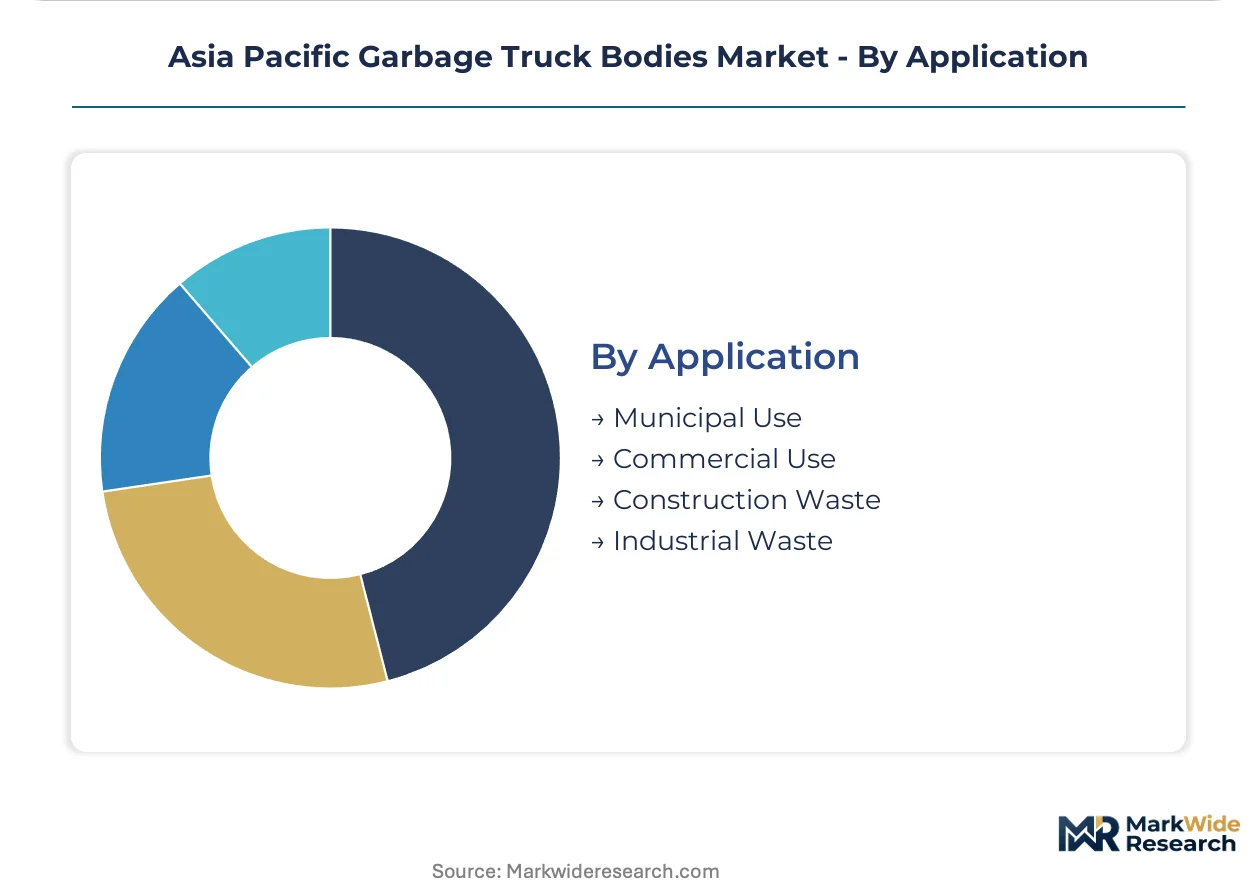
Application:
End-use segmentation tracks funding source divergence between tax-supported municipal operations and contract-driven commercial services.
- Municipal Use:Tax-funded fleet procurement under India's Smart Cities Mission and Indonesia's national solid waste management program drives standardized rear-loader specifications. Tender evaluation prioritizes total cost of ownership over upfront capital expenditure.
- Commercial Use:Private waste haulers in Australian and Japanese metropolitan markets demand lifecycle service contracting with unbundled maintenance warranties. Melbourne and Osaka operators separate body upkeep from chassis coverage.
- Construction Waste:Heavy-duty reinforced bodies with abrasion-resistant liners serve demolition debris in Chinese urban renewal zones.
- Industrial Waste:Specialized containment systems address hazardous and chemical processing byproducts in Korean and Taiwanese manufacturing clusters.
Municipal Use commands the dominant procurement volume, while Commercial Use is gaining share fastest through outcome-based service contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing corridor hosts the densest concentration of garbage truck body fabrication capacity across Asia Pacific, with provincial industrial parks in Guangdong and Jiangsu anchoring aluminum-intensive production lines for electric chassis integration.
China
Guangdong and Jiangsu provincial tenders now mandate electric chassis compatibility in municipal waste collection contracts, compressing body-chassis integration timelines for fabricators. GB standards for commercial vehicle electrification dictate aluminum welding protocol certification, filtering uncertified suppliers from tier-one urban procurement. Fulongma leverages domestic supply chain density in Fujian to dominate rear-loader assembly lines for municipal tenders across the Yangtze River Delta.
India
Urban local bodies in 100 Smart Cities Mission designated cities are tendering mechanized waste collection fleets with standardized rear-loader specifications. BIS structural certification mandates crashworthiness testing for body-chassis integration, consolidating procurement toward accredited fabricators. Ashok Leyland and TATA Motors anchor fabrication capacity in Tamil Nadu and Maharashtra to serve municipal corporations in Bangalore and Delhi-NCR.
Japan
METI-funded carbon-neutral port initiatives at Yokohama and Kobe are creating demand for lightweight bodies optimized for electric chassis. JIS automotive regulations dictate welding protocols and hydraulic pressure ratings for body-chassis integration, elevating capital requirements for certification. Shinmaywa Industries competes from its Kansai base on alloy-intensive compaction mechanisms that reduce tare weight for domestic operator specifications.
Vietnam
Provincial capitals outside Hanoi and Ho Chi Minh City lack mechanized collection coverage, presenting first-mover expansion potential for rear-loader suppliers. The national solid waste management program is channeling infrastructure investment toward secondary urban centers. Dongfeng Motor Corporation and regional fabricators are positioning assembly partnerships in the Red River Delta to capture emerging municipal demand.
Australia
Melbourne and Sydney fleet operators are mandating real-time fill-level transmission for dynamic route dispatch, digitizing traditional body specifications into data-service bundles. Lifecycle service contracting is displacing upfront equipment procurement, unbundling body maintenance from chassis warranties. Volvo and Isuzu Motors anchor positions in Victoria and New South Wales through aftermarket service network density.
Asia Pacific Garbage Truck Bodies Market Competitive Landscape
Integrated chassis-body manufacturers and specialized body fabricators split the market along electrification capability lines. Tier-one municipal tenders concentrate among certified aluminum welders with in-house testing facilities, while price-sensitive bulk procurement channels retain steel-dominant suppliers. Two strategic archetypes dominate: domestic supply chain orchestrators leveraging provincial industrial density, and alloy-specialist technicians with certified friction-stir welding protocols. Competitive moves center on parallel prototype pipelines for overlapping certification cycles and captive hydraulic component sourcing to offset currency volatility.
Among Chinese integrated manufacturers, Fulongma and BYD Motors exemplify the domestic supply chain archetype, with the former representing rear-loader specialization and the latter anchoring electric chassis-body integration. Shinmaywa Industries occupies a position within the Japanese alloy-specialist tier, reflecting technician-pool concentration for thin-gauge structural welding. These three named entities illustrate how certification density and material expertise stratify competitive positioning across Asia Pacific municipal procurement channels.
| Leading Market Players |
|---|
| Fulongma |
| BYD Motors |
| Shinmaywa Industries |
| Mitsubishi Fuso Truck and Bus Corporation |
| Dongfeng Motor Corporation |
| Ashok Leyland |
| Volvo |
| Isuzu Motors |
| TATA Motors |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's containerized logistics costs shape procurement economics for garbage truck body fabricators, amplifying price differentiation between certified aluminum welders and steel-dominant suppliers while compressing margins for uncertified entrants locked out of tier-one municipal tenders.
Pricing Analysis
India's BIS structural certification dictates the pricing tier structure across Asia Pacific municipal procurement, separating crash-tested aluminum body integrators from uncertified steel fabricators. Three-tier pricing structure across premium, standard, and economy levels tracks welding protocol certification, after-sales service bundling, and electric chassis compatibility. Pricing pressure stems from hot-rolled coil volatility in fixed-price Indian municipal contracts. Steel-dependent bulk procurement channels exhibit highest price sensitivity, while Japanese electric fleet operators show lowest sensitivity due to lifecycle cost optimization.
Supply Chain Analysis
Extended payment terms from Guangdong provincial fleet operators and supply-chain finance facilities anchored in Fujian industrial parks concentrate fabrication capacity in China's manufacturing corridor. Component sourcing draws from Japanese hydraulic cylinder specialists, German valve assembly manufacturers, and domestic Chinese aluminum smelters. Single-source vulnerability runs through high-pressure compaction cylinder imports from Osaka-based suppliers. Distribution runs through municipal tender procurement channels and lifecycle service contracting networks in Australian and Japanese metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific garbage truck bodies sit in early-cycle expansion, with Vietnam's provincial capitals and Indonesia's national solid waste program driving mechanized collection penetration below 30 percent in secondary urban centers.
For Market Incumbents: Build certification moats around parallel BIS and JIS prototype pipelines to compress qualification timelines and lock out uncertified competitors. Accelerate captive hydraulic component sourcing to offset yen-euro currency volatility threatening margin buffers. Aluminum welding technician apprenticeship programs in Tamil Nadu and Guangdong defend against Korean and Japanese skill scarcity.
For New Entrants and Emerging Players: Vietnam's secondary cities outside Hanoi and Ho Chi Minh City offer first-mover positioning where mechanized collection coverage remains underdeveloped. Philippine and Indonesian coastal municipalities present premium composite-reinforced body opportunities with 40-60 percent pricing premiums over standard steel. Partner with Dongfeng Motor Corporation or Ashok Leyland for chassis-body integration credibility in municipal tender channels.
For Investors and Strategic Acquirers: Alloy-specialist fabricators with certified friction-stir welding protocols and in-house GB standards testing facilities represent the most defensible acquisition archetype. Long-term viability hinges on electrification mandate alignment across Guangdong, Jiangsu, and Indian Smart Cities jurisdictions. Monitor divergence between national zero-emission fleet timelines and commercial electric chassis delivery schedules as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Welding Protocol Certification | GB standards compliance unlocks tier-one procurement in Guangdong and Jiangsu provincial tenders. |
| Captive Hydraulic Component Sourcing | In-house cylinder production insulates margins from yen-denominated import volatility. |
| Telematics-Enabled Service Contracting | Real-time fill-level transmission meets Sydney and Melbourne fleet operator mandates. |
| Composite-Reinforced Coastal Variants | Fiberglass-skinned honeycomb panels capture premium pricing in Philippine and Indonesian port cities. |
| Secondary City Distribution Partnerships | Assembly alliances in Vietnam's Red River Delta position for national solid waste program funding. |
Research Methodology
Desk research of customs trade data, municipal tender databases, and GB-BIS-JIS regulatory filings preceded structured interviews with fleet procurement managers at Indian municipal corporations, aluminum welding technicians at Fujian fabricators, hydraulic component sourcing directors, and aftermarket service heads at Australian waste management operators. Bottom-up volume estimates from chassis delivery schedules and body assembly line capacity triangulated against top-down municipal budget allocation data across Smart Cities Mission jurisdictions.
Assumptions held fixed include China's dual carbon goals timeline, India's BIS certification enforcement trajectory, and Japanese METI port electrification funding levels, while aluminum alloy substitution rates and electric chassis availability varied across sensitivity scenarios. Segmentation modeling spanned product configuration, material grade, cubic yard capacity bracket, and application type. CAGRs derived from fitted trend extrapolation validated against historical procurement cycle patterns and fleet replacement schedules.
Practitioners should monitor chassis delivery bottlenecks, scrap metal price volatility, and certification timeline compression for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Tipper Truck Market