
 Utility Vehicle Market | 2026-2036
Utility Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Vehicle Market Outlook
The US EPA Tier 4 Final emissions standards is shifting procurement criteria across North American utility vehicle fleets. Polaris Inc. anchors the recreational side-by-side segment with extensive dealer network coverage. Deere & Company dominates agricultural utility vehicle sales through its captive financing arm and equipment integration. KUBOTA Corporation specializes in compact diesel platforms for Asian and Latin American farm operators.
Utility vehicles span wheeled motorized platforms engineered for cargo transport, passenger movement, and task-specific mobility across unpaved or restricted terrain, typically featuring four-wheel-drive capability, payload ratings exceeding 500 kg, and ground clearance above 200 mm. Their primary commercial purpose centers on replacing manual labor and light trucks in environments where road infrastructure is limited or absent. Compact SUVs and pick-up trucks command the largest revenue pools as fleet buyers prioritize versatility over single-purpose configurations. Electric fuel type variants are capturing disproportionate R&D allocation as battery energy density improvements enable viable range for rural and remote applications.
The US EPA, China's MIIT, and the EU's F-Gas Regulation collectively shape engine certification, electrification timelines, and refrigerant specifications across major production bases. Japan's METI adds pressure through fuel efficiency benchmarks that influence export-oriented manufacturers. Stakeholders must track divergence between US and Chinese electrification standards to avoid stranded platform investments.
Market Dynamics
The US EPA Tier 4 Final emissions standards is forcing a platform-level redesign across diesel-powered utility vehicle architectures. Agricultural and construction fleet operators now face procurement decisions that lock in powertrain configurations for decade-long replacement cycles.
Growth Catalysts
- Rural infrastructure investment:China's inland provinces are deploying utility vehicles for road maintenance and agricultural logistics. Provincial procurement budgets prioritize four-wheel-drive platforms with standardized service networks.
- MIIT electrification timelines:China's dual carbon goals are compressing development schedules for battery-electric utility platforms. Domestic manufacturers accelerate R&D to meet 2035 phase-out benchmarks for combustion engines in designated zones.
- Precision agriculture integration:Autosteer and variable-rate application systems require utility vehicles with dedicated hydraulic circuits and CAN bus architecture. Farm operators replace aging fleets to enable implement compatibility.
Market Restraints
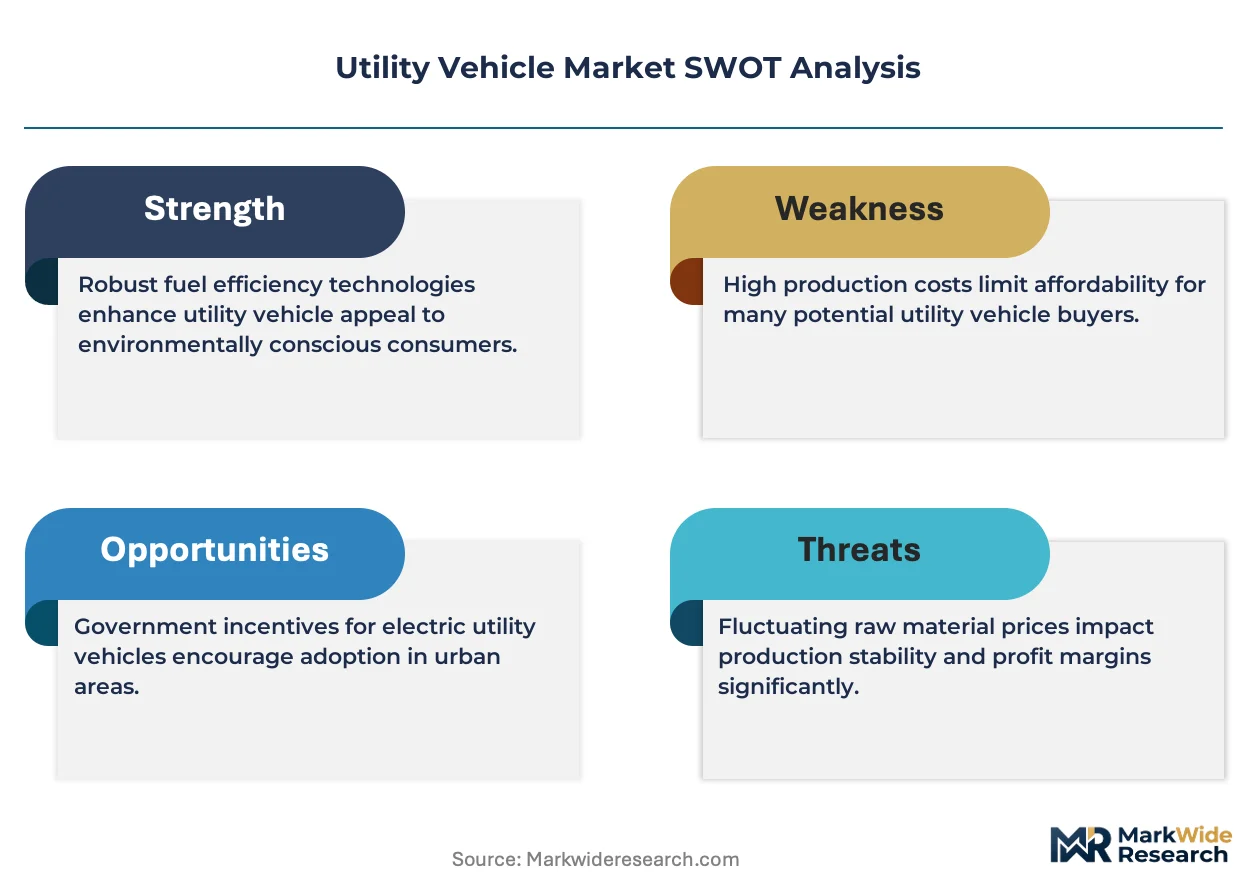
- Diesel aftertreatment complexity:Selective catalytic reduction and diesel particulate filter systems add cost and maintenance burden. Small fleet operators defer replacement purchases to avoid technician retraining and DEF supply logistics.
- Battery supply concentration:Cell production for commercial vehicle scales concentrates in East Asian manufacturing corridors. OEMs face allocation constraints and long lead times for pack integration.
- Steel and aluminum input volatility:Chassis and cargo bed fabrication depends on commodity metals exposed to tariff and energy cost fluctuations. Margin pressure limits pricing flexibility for mid-tier configurations.
Strategic Opportunities
- India's agricultural mechanization gap:Sub-50 horsepower utility vehicles serve smallholder farms with limited tractor access. Local assembly partnerships circumvent import duty structures while building service density.
- Telematics and usage-based financing:Hour-meter data and geofencing enable equipment lenders to underwrite risk by actual utilization rather than collateral value. Captive finance arms capture customer lifetime value through subscription structures.
- EU F-Gas Regulation refrigerant transition:Air-conditioned cab variants must migrate to low-GWP alternatives. Early compliance creates specification advantages for export-oriented manufacturers targeting European rental fleets.
Industry Challenges
- Powertrain software integration:Engine control modules, transmission logic, and implement electronics require cross-vendor calibration. Fleet operators report diagnostic complexity and proprietary tool lock-in.
- Homologation timeline compression:Parallel certification tracks for EPA, EU Stage V, and emerging market standards strain engineering bandwidth. Platform divergence multiplies validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Vehicle Market |
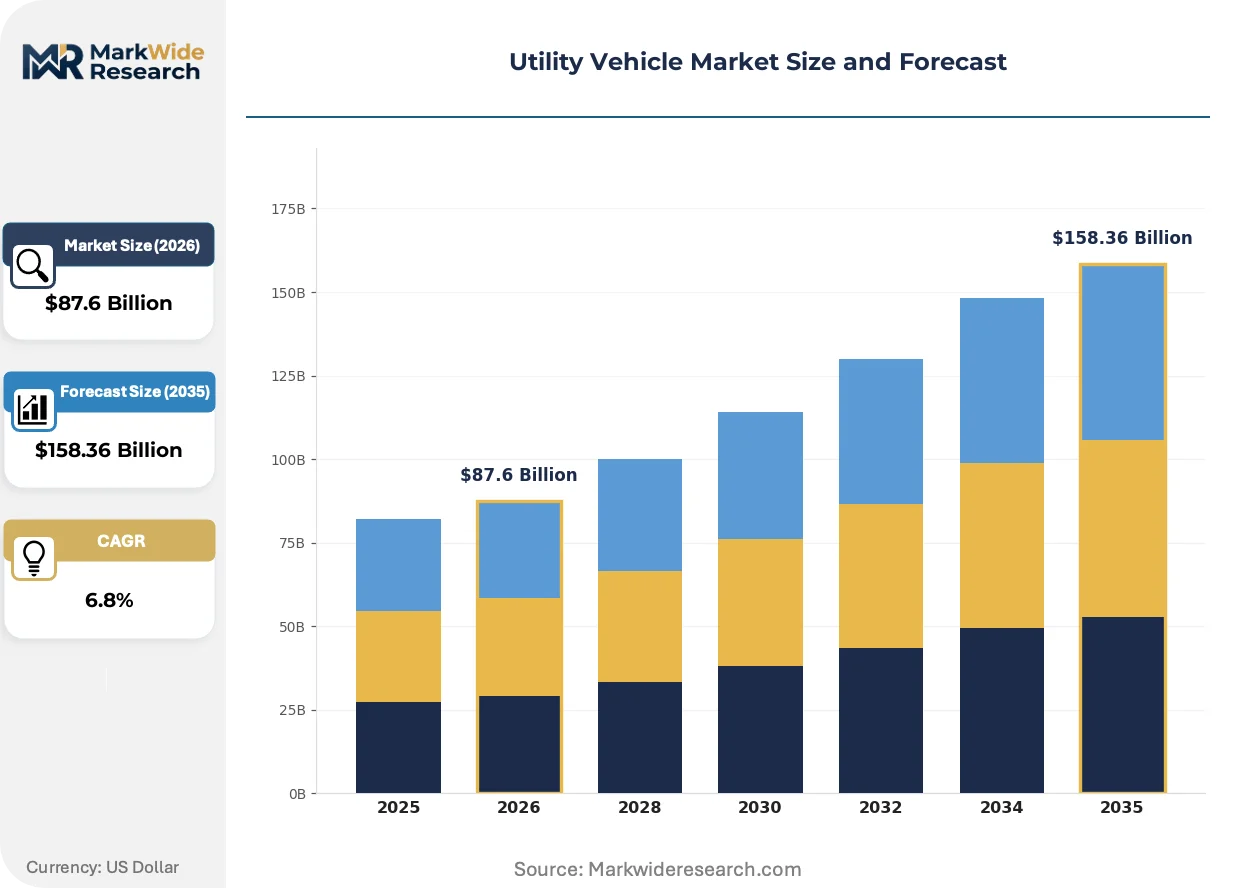
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact SUVs, Full-Size SUVs, Pick-Up Trucks, Minivans End User: Agriculture, Construction, Emergency Services, Recreational Users Fuel Type: Gasoline, Diesel, Electric, Hybrid Vehicle Size: Subcompact, Compact, Mid-Size, Full-Size |
| Companies Covered | Polaris Inc., BRP Inc., Deere & Company, Honda Motor Co., Ltd., Textron Inc., Kawasaki Heavy Industries, Ltd., KUBOTA Corporation, CFMOTO, Yamaha Motor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Vehicle Market Strategic Shifts
Powertrain electrification is absorbing the majority of engineering resources across utility vehicle development programs. Battery chemistry advances and thermal management systems now determine competitive positioning more than mechanical durability alone.
Solid-state battery prototyping is absorbing venture funding and pilot line investment from tier-one suppliers. Agricultural OEMs in Japan and Germany are field-testing packs with silicon-anode architectures for extended duty cycles. The technology is absorbing range anxiety barriers that previously limited electric utility vehicle deployment to closed-campus applications.
The EU's F-Gas Regulation mandates refrigerant phase-down schedules that cascade into cab climate system redesigns. Compressor and heat pump suppliers must recertify components for CO2 or HFO alternatives. European rental fleet specifications now exclude legacy refrigerant systems, compressing availability windows for non-compliant inventory.
Equipment-as-a-service contracting is displacing traditional loan and lease structures among North American construction fleets. Operators prefer fixed hourly rates covering maintenance and telematics over capital ownership. This shift concentrates purchasing authority with national rental networks rather than dispersed contractors.
Utility Vehicle Market Segmentation
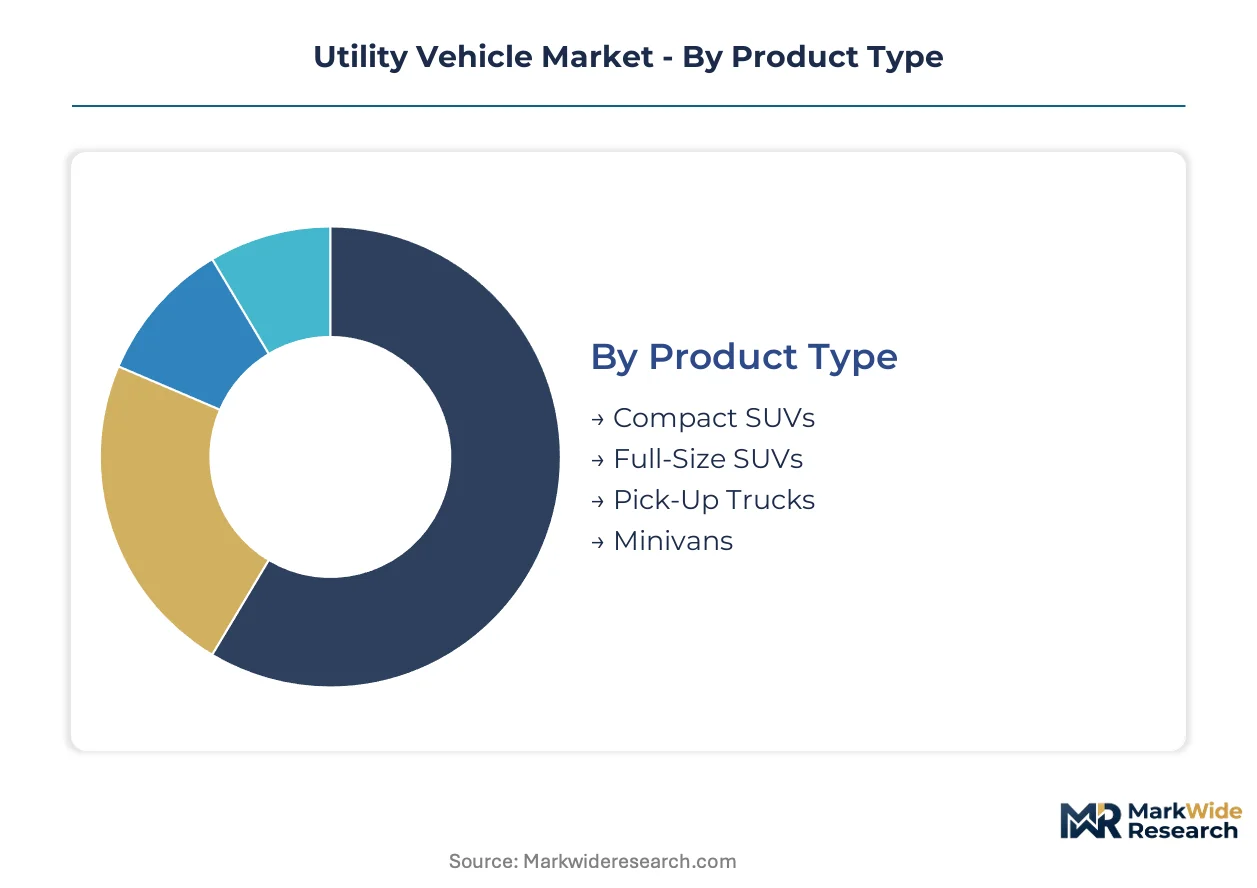
Utility vehicle procurement patterns diverge sharply between fleet operators seeking standardized platforms and specialized users demanding task-optimized configurations. Segmentation reveals how powertrain choices, payload requirements, and duty cycles reshape competitive positioning across agricultural, construction, and recreational buyer pools.
Product Type:
Standalone vehicle architectures dominate revenue capture, while chassis-cab derivatives serve embedded equipment integration needs across vocational fleets.
- Compact SUVs:Unibody construction with 1,500-2,500 kg towing capacity serves rural municipal fleets and smallholder cooperatives in China's Henan and Sichuan provinces. Provincial procurement standardization favors four-wheel-drive variants with unified service protocols.
- Pick-Up Trucks:Body-on-frame platforms with open cargo beds accommodate aftermarket implement mounting for construction and agricultural contractors. Fleet buyers in Brazil's Mato Grosso grain belt prioritize diesel powertrains for fuel availability and torque characteristics.
- Full-Size SUVs:Three-row seating configurations with enclosed cargo security serve emergency response coordinators and remote site supervisors.
- Minivans:Low-floor access and modular interior tracks support last-mile logistics in urban-peripheral zones with restricted loading infrastructure.
Pick-up trucks lead volumes today; electric powertrain variants are gaining share fastest in closed-campus and municipal procurement.
End User:
Commercial operators drive replacement cycles through equipment integration requirements, while recreational demand fluctuates with discretionary income patterns.
- Agriculture:Autosteer-ready hydraulic circuits and ISOBUS compatibility command premium positioning. Brazilian soybean operators in Goiás and Mato Grosso do Sul replace fleets to enable precision planting implement control.
- Construction:Reinforced suspension packages and differential lock systems withstand aggregate hauling and site grading duty cycles. Rental fleet operators specify telematics-ready CAN bus architecture for hour-meter verification.
- Emergency Services:Upfitter-friendly electrical systems and heavy-duty alternator options support mobile command and medical transport configurations.
- Recreational Users:Trail-rated suspension and aftermarket accessory compatibility dominate purchase criteria in US desert Southwest and Australian Outback markets.
Agriculture leads volumes today; construction telematics integration is climbing the fastest among fleet segments.
Fuel Type:
Regulatory pressure on combustion architectures accelerates platform divergence between EPA Tier 4 Final compliance zones and electrification-leading jurisdictions.
- Diesel:Compression-ignition platforms with SCR and DPF aftertreatment retain dominance in high-torque agricultural and construction applications. US Tier 4 Final certification costs push small manufacturers toward engine supplier consolidation.
- Electric:Battery-electric architectures with 150-300 km range enable vineyard, orchard, and campus maintenance operations with predictable duty cycles. China's MIIT dual carbon timeline compresses domestic OEM development schedules for designated low-emission zones.
- Gasoline:Spark-ignition powertrains serve recreational and light-duty commercial segments where refueling infrastructure constraints diesel adoption.
- Hybrid:Parallel electric assist systems bridge range anxiety gaps in remote construction and rural emergency response deployments.
Diesel leads volumes today; electric variants show the steepest expansion trajectory in state-directed procurement programs.
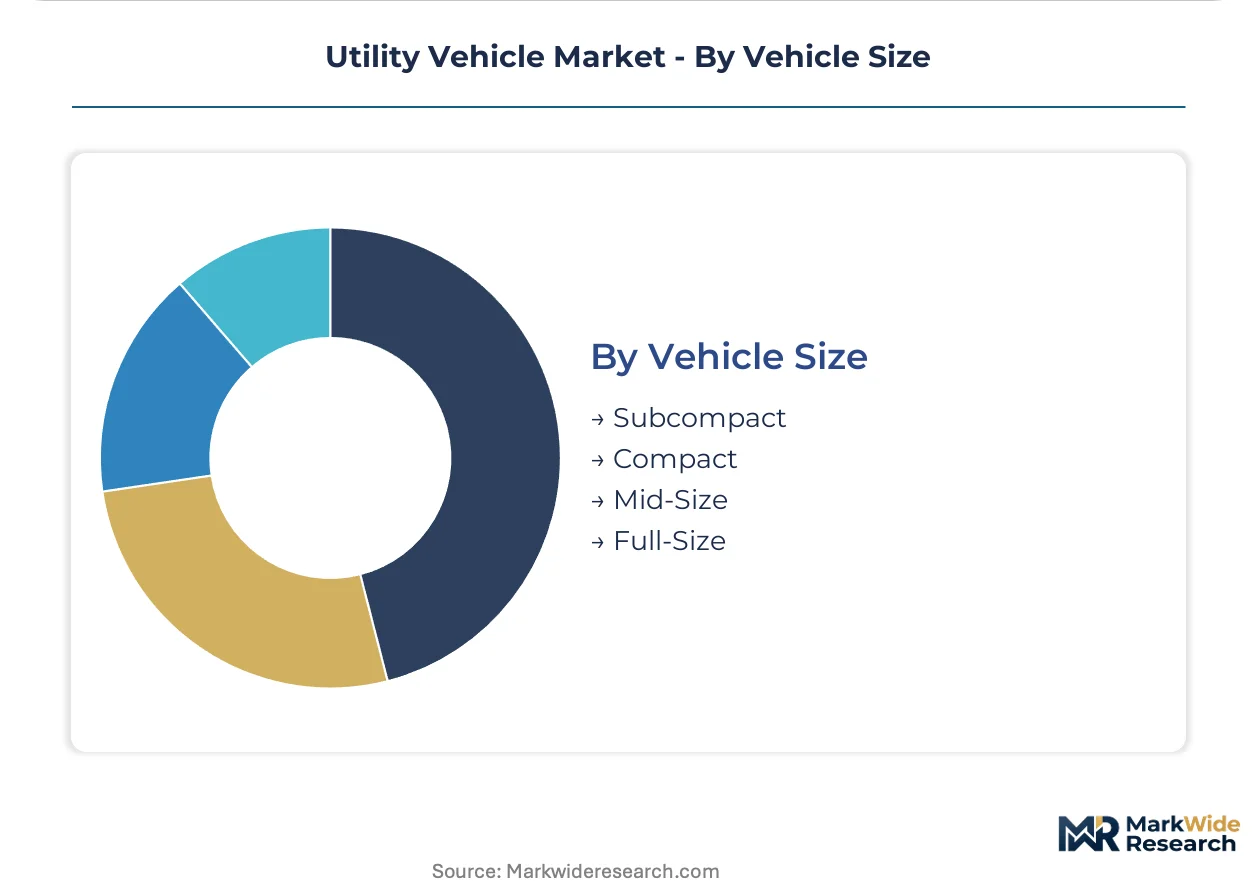
Vehicle Size:
Dimensional classification determines homologation pathways, import duty tiers, and operator licensing requirements across national regulatory frameworks.
- Full-Size:Platforms exceeding 5.3 meters in length with 3,500+ kg towing capacity anchor North American fleet procurement. US EPA emissions certification applies uniform standards regardless of vehicle mass.
- Compact:Sub-4.7 meter lengths with 1,000-1,500 kg payload ratings penetrate India's agricultural mechanization gap where smallholder farm scale limits tractor access. Local assembly partnerships circumvent import duty structures.
- Subcompact:Narrow-track designs with sub-1,800 mm width navigate vineyard rows and urban maintenance corridors with restricted access.
- Mid-Size:Intermediate dimensional envelope balances cab comfort with maneuverability in European forest management and alpine rescue applications.
Full-size configurations lead volumes today; compact platforms are expanding most quickly in emerging market smallholder mechanization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The utility vehicle industry traces its commercial origins to post-war agricultural mechanization in the United States, where manufacturers first standardized four-wheel-drive platforms for farm and ranch operations. That American foundation diffused into specialized regional variants across Brazil, China, Germany, and Australia as local terrain and regulatory conditions reshaped platform requirements.
United States
Recreational side-by-side demand concentrates in Arizona, Utah, and Nevada desert corridors where trail-rated suspension commands premium positioning. EPA Tier 4 Final emissions standards force diesel platform redesigns across agricultural and construction fleets. Polaris Inc. anchors production and distribution networks from Minnesota and Iowa manufacturing bases.
Brazil
Soybean operators in Mato Grosso and Goiás replace aging fleets to enable precision planting implement control through ISOBUS-compatible hydraulic circuits. ANVISA equipment certification runs parallel to agricultural ministry inspections for rural mechanization subsidies. Local assembly partnerships in São Paulo state circumvent import duty structures while building service density for sub-50 horsepower segments.
China
Provincial procurement in Henan and Sichuan prioritizes four-wheel-drive platforms with standardized service protocols for road maintenance and agricultural logistics. MIIT dual carbon goals compress development schedules for battery-electric utility platforms targeting 2035 combustion phase-out benchmarks in designated zones. Yangtze River Delta manufacturers accelerate solid-state battery prototyping for extended duty cycle applications.
Germany
EU Stage V emissions standards and F-Gas Regulation refrigerant mandates cascade into cab climate system redesigns for European rental fleet specifications. Bavaria and Baden-Württemberg host precision agriculture equipment integration clusters where autosteer-ready CAN bus architecture commands premium positioning. Forest management and alpine rescue applications in southern regions favor mid-size dimensional envelopes balancing cab comfort with restricted access maneuverability.
Australia
Outback recreational demand fluctuates with discretionary income patterns across Western Australia and Northern Territory mining corridor communities. TGA equipment registration requirements intersect with state-level agricultural safety inspections for farm fleet compliance. Queensland sugar cane and cattle operations drive replacement cycles through dedicated hydraulic circuit requirements for implement compatibility.
Utility Vehicle Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the utility vehicle landscape, with integrated manufacturers maintaining captive engine foundries while specialized assemblers source powertrains from tier-one suppliers. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive financing arms, recreational specialists with extensive dealer networks, and regional fabricators serving agricultural mechanization gaps. Competitive positioning hinges on M&A activity consolidating engine supplier relationships and strategic partnerships securing battery cell allocation from East Asian manufacturing corridors.
Among North American recreational specialists, Polaris Inc. and BRP Inc. exemplify the dealer-network-dependent archetype, while Deere & Company represents the diversified industrial conglomerate model with integrated agricultural equipment ecosystems. KUBOTA Corporation anchors the compact diesel specialist position serving Asian and Latin American farm operators. These three named entities illustrate the structural divergence between recreational, agricultural, and regional-mechanization competitive vectors without exhaustively mapping the full competitive set.
| Leading Market Players |
|---|
| Polaris Inc. |
| BRP Inc. |
| Deere & Company |
| Honda Motor Co., Ltd. |
| Textron Inc. |
| Kawasaki Heavy Industries, Ltd. |
| KUBOTA Corporation |
| CFMOTO |
| Yamaha Motor Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive engine foundries at diversified industrial conglomerates anchor both supply security and pricing power across diesel utility vehicle architectures. This vertical integration pattern insulates Tier 1 OEMs from tier-one supplier allocation constraints while compressing margin capture for asset-light assemblers sourcing powertrains externally.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts for agricultural and construction fleets. Price differentiation rests on EPA Tier 4 Final certification status and captive financing availability through equipment manufacturers' in-house lending arms. Cost compression in the economy tier is intensifying because small fleet operators defer replacement purchases to avoid diesel aftertreatment maintenance burdens. Municipal buyers exhibit lowest price sensitivity due to standardized procurement protocols, while independent contractors in Brazil's Mato Grosso grain belt demonstrate highest sensitivity to fuel cost differentials.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet demand from national rental networks and provincial procurement authorities in China's inland provinces. Cell production for battery-electric platforms concentrates in China, South Korea, and Japan, with chassis fabrication drawing from steel and aluminum suppliers exposed to tariff volatility. Single-source vulnerability around selective catalytic reduction module suppliers creates bottleneck risk for EPA-compliant diesel architectures. Distribution runs through captive dealer networks for agricultural equipment and independent distributors for recreational side-by-side segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 4 Final emissions standards force platform-level redesigns that concentrate procurement authority with integrated manufacturers possessing captive certification resources.
For Market Incumbents: Anticipate margin compression from battery supply allocation constraints by securing long-term cell offtake agreements with Yangtze River Delta manufacturers. Consolidate engine supplier relationships to amortize Tier 4 Final validation costs across higher production volumes, while expanding captive financing subscription structures to capture customer lifetime value from telematics-enabled usage data. For New Entrants and Emerging Players: MIIT dual carbon goals in China open a window for battery-electric utility platform specialists targeting designated low-emission zones with 2035 combustion phase-out benchmarks. India's agricultural mechanization gap presents the most penetrable geography, where sub-50 horsepower compact platforms serve smallholder farms with limited tractor access. Partner with local assembly operations in São Paulo state to circumvent import duty structures while building service density. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators serving agricultural mechanization gaps because fragmented local service networks create customer lock-in through proximity maintenance. Target compact diesel specialists with established Latin American distribution and ISOBUS-compatible hydraulic circuit expertise. Watch solid-state battery prototyping milestones from Japanese and German agricultural OEMs as inflection indicators for extended duty cycle electric platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake from East Asian corridors secures allocation for electric platform scaling. |
| Platform Standardization | Unified CAN bus architecture reduces homologation costs across EPA, EU Stage V, and emerging market standards. |
| Captive Financing Expansion | Subscription-based equipment contracting displaces traditional loans among North American construction fleets. |
| Telematics Integration | Hour-meter data and geofencing enable usage-based underwriting for agricultural and rental fleet customers. |
| Local Assembly Partnership | Regional fabrication in São Paulo state circumvents Brazilian import duties for sub-50 horsepower segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with agricultural fleet operators, construction rental network procurement directors, OEM platform engineers, and captive finance executives with secondary validation. Regulatory filings from EPA, China's MIIT, and EU F-Gas Regulation databases anchored emissions and electrification timeline assumptions. Trade data from customs authorities, agricultural equipment registration databases, and SEC 10-K disclosures from diversified industrial conglomerates provided production and revenue benchmarks. Bottom-up fleet replacement modeling and top-down market sizing triangulated volume estimates.
Historical reference periods spanning pre-Tier 4 Final implementation through current electrification transition phases anchored the forecast window. Segmentation modeling covered product type, end-use application, fuel architecture, and vehicle size dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from replacement cycle analysis and provincial procurement budget trajectories. Battery energy density improvement curves and solid-state prototyping timelines informed electric platform penetration assumptions across the projection horizon.
Revisions become necessary when battery supply allocation constraints intensify, steel and aluminum input volatility disrupts chassis fabrication economics, or divergence between US and Chinese electrification standards strand platform investments. Forecasts reflect assumptions about MIIT dual carbon timeline adherence and EPA enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Peru Commercial Vehicle Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Japan Commercial Vehicles Market