
 Garbage Collection Trucks Market | 2026-2036
Garbage Collection Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Garbage Collection Trucks Market Analysis
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified OEMs and secondary assemblers. Oshkosh Corporation leverages its defense-contracting manufacturing discipline to anchor municipal fleet contracts across North America. Heil Environmental specializes in automated arm technologies that differentiate its side-loader configurations from commodity chassis suppliers. Scania Group dominates European refuse truck powertrain integration, particularly in CNG and emerging electric platforms.
Garbage collection trucks are purpose-built vocational vehicles combining reinforced steel hopper bodies with hydraulic compaction systems achieving typical payload densities of 400-600 kg per cubic meter, designed for repetitive urban stop-and-go cycles with automated lifting mechanisms reducing crew requirements. Rear loader configurations retain the largest installed base but electric fuel type segments capture the fastest expansion as battery energy density improvements and overnight depot charging infrastructure mature. Multi-compartment vehicle types command premium positioning where municipalities enforce source-separated organic and recyclable collection streams.
EPA greenhouse gas Phase 3 standards and EU Green Deal emissions benchmarks compel powertrain transitions across major manufacturing jurisdictions, while China's MIIT new energy vehicle mandates accelerate domestic electric chassis development. The California Air Resources Board operates the most stringent state-level fleet conversion timeline in the United States. Stakeholders must weigh total cost of ownership against capital expenditure premiums as electrification infrastructure requirements reshape procurement evaluation frameworks.
Market Dynamics
Powertrain electrification is decomposing the established diesel-centric supply chain, forcing chassis manufacturers to reconfigure procurement relationships around battery pack integrators and electric drivetrain specialists.
Growth Catalysts
- EPA greenhouse gas Phase 3 standards:Fleet operators in the United States face binding emissions reductions that accelerate electric and CNG chassis procurement timelines.
- Automated side-loader mechanisms:Single-operator collection vehicles reduce labor costs by eliminating manual lifting requirements in high-density urban routes.
- China's MIIT new energy vehicle mandates:Domestic OEMs receive production quotas that expand electric refuse truck availability across municipal procurement channels.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cobalt and nickel compress margin structures for electric chassis assemblers.
- Depot charging infrastructure capex:Municipal fleet operators must fund grid upgrades and overnight charging installations before electric vehicle deployment.
- Technical payload density limitations:Current battery energy density restricts hopper compaction ratios compared to diesel equivalents on extended rural routes.
Strategic Opportunities
- India's Smart Cities Mission:Urban local bodies receive central funding for mechanized waste collection systems in tier-2 and tier-3 municipalities.
- Biomethane-compatible CNG powertrains:Organic waste stream operators seek closed-loop fuel sourcing from anaerobic digestion facilities.
- Route optimization telematics convergence:Real-time compaction monitoring combined with predictive maintenance algorithms creates subscription revenue streams for OEMs.
Industry Challenges
- High-voltage technician certification gaps:Fleet maintenance departments lack trained personnel for battery management system diagnostics and repair.
- ISO 9001 compliance timelines:Secondary assemblers face extended audit cycles that delay qualification for municipal tender participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garbage Collection Trucks Market |
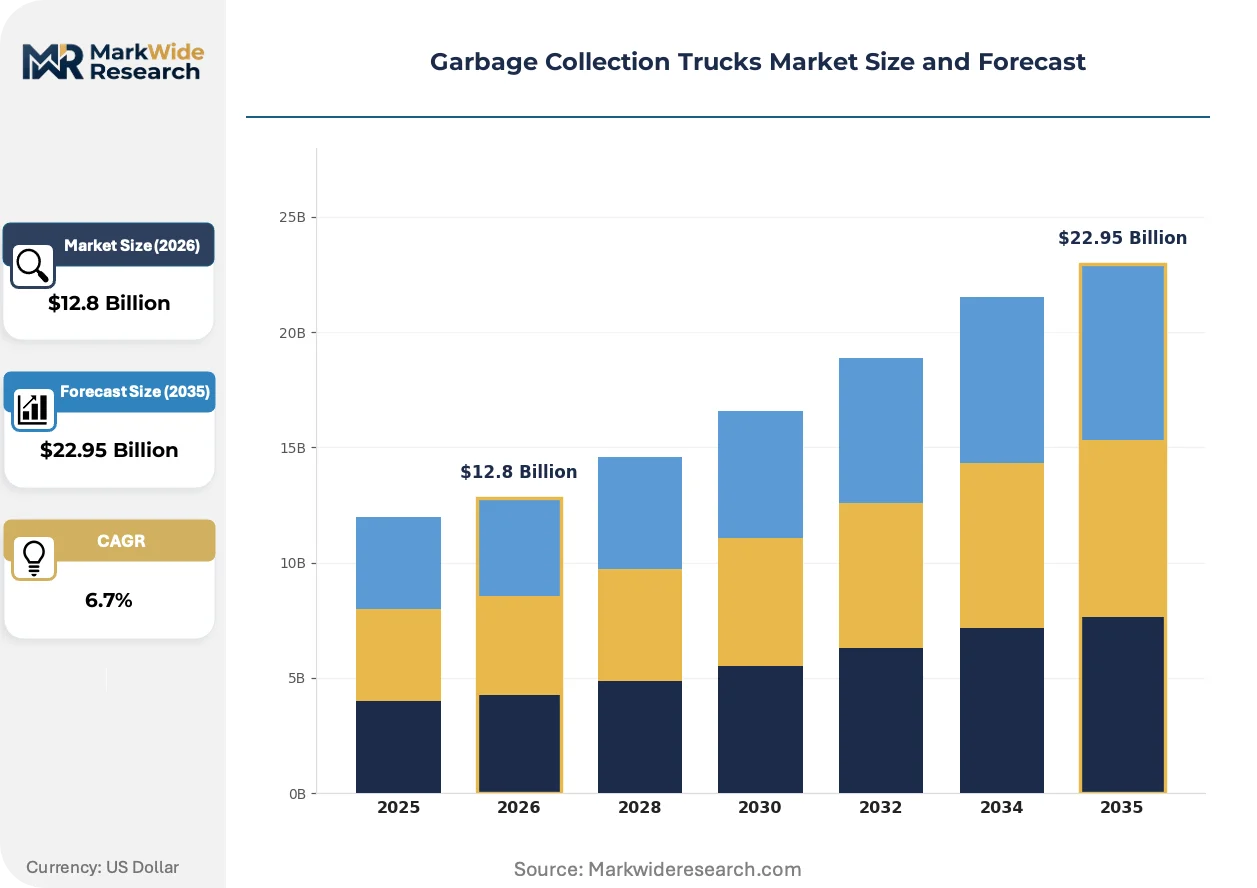
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Rear Loader, Front Loader, Side Loader, Multi-Compartment Fuel Type: Diesel, CNG, LNG, Electric Payload Capacity: 3-5 Tons, 5-10 Tons, 10-15 Tons, Above 15 Tons Application: Municipal, Commercial, Industrial, Construction |
| Companies Covered | Oshkosh Corporation, Daimler AG, Heil Environmental, New Way, Scania Group, McNeilus Truck and Manufacturing, Volvo Group, Mack Trucks, Inc., DESA (Henan Desa Automobile Co., Ltd.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garbage Collection Trucks Market Emerging Trajectories
Electrification is fragmenting the traditional chassis-body supplier relationship, creating new entry points for battery integrators and software-defined vehicle platforms. Three convergent developments are compressing legacy procurement cycles.
Solid-state battery prototyping is decomposing the range-payload tradeoff that has constrained electric refuse truck deployment. German municipal fleet operators are piloting 400-kilometer-range configurations for regional landfill transfer routes. The technology is decomposing diesel's residual advantage in low-frequency, long-haul collection applications.
EU Green Deal emissions benchmarks are binding member states to fleet decarbonization timelines that outpace current replacement cycles. France's national low-carbon strategy mandates 50% electric or hydrogen-powered municipal vehicles by 2030. Scandinavian operators are responding with accelerated CNG bridge investments pending full electrification readiness.
Performance-based service contracting is displacing traditional equipment ownership models among budget-constrained municipalities. Dutch waste management authorities now contract for tonnes-collected-per-euro rather than vehicle availability metrics. This shift concentrates procurement authority with integrated operators capable of absorbing residual value risk.
Garbage Collection Trucks Market Segmentation
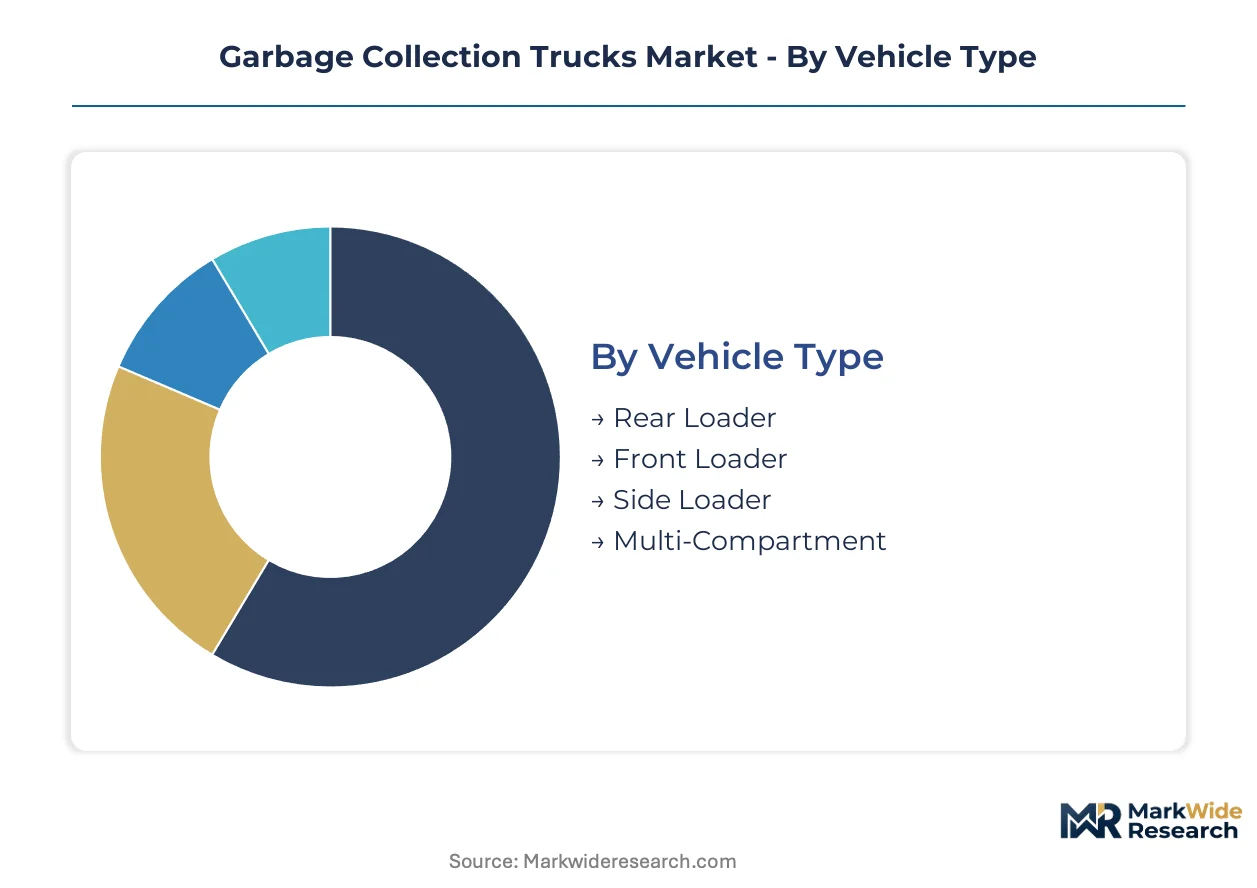
Segmentation in garbage collection trucks determines procurement specifications, total cost of ownership calculations, and fleet replacement cycles. Municipal buyers prioritize payload efficiency and labor reduction, while private operators weigh route density against fuel infrastructure availability.
Vehicle Type:
Geographic concentration varies sharply by configuration. Rear loaders dominate domestic municipal fleets in established markets. Side loaders and multi-compartment units command premium positioning in export contracts where labor costs and source-separation mandates drive specification upgrades.
- Rear Loader:Standard hopper-body configuration with manual or semi-automated lifting. Municipal fleet operators in Germany and the United States specify these for high-density urban routes where proven reliability outweighs labor efficiency gains.
- Side Loader:Single-operator automated arm systems reduce crew requirements by eliminating manual bin handling. Demand concentrates in Australian and Canadian municipalities facing acute labor shortages and union-negotiated staffing minimums.
- Front Loader:Heavy-duty container-lifting mechanism for commercial roll-off applications. Construction and industrial waste contractors in Texas and Alberta specify these for demolition debris routes.
- Multi-Compartment:Segregated hopper design enabling simultaneous collection of organics, recyclables, and residual waste. Dutch and Swedish municipalities mandate these for circular economy compliance.
Rear loaders command the established base. The steepest expansion runs through side loaders.
Fuel Type:
Cost tier stratification is restructuring competitive positioning. Diesel retains economy-segment dominance. Electric and CNG variants capture premium municipal contracts where total cost of ownership models incorporate carbon pricing and health externalities.
- Diesel:Compression-ignition powertrain with established service networks and lowest capital expenditure. Fleet operators in rural Poland and Indiana continue procurement where charging infrastructure gaps and extended route distances persist.
- CNG:Spark-ignition natural gas engines with 20-25% CO2 reduction versus diesel. Italian and Californian municipalities prioritize these where biomethane injection creates closed-loop waste-to-fuel opportunities.
- LNG:Cryogenic liquid storage enabling extended range for regional landfill transfer. German inter-municipal cooperatives specify these for routes exceeding 200 kilometers.
- Electric:Battery-electric drivetrains with overnight depot charging and zero tailpipe emissions. Urban fleet operators in Shenzhen and Oslo mandate these for low-emission zone compliance.
Diesel retains volume leadership. Electric configurations are gaining share fastest.
Payload Capacity:
Application-specific loading patterns dictate specification. Light-duty segments serve narrow-street residential collection. Heavy-duty configurations dominate commercial and industrial contracts where compaction density determines route economics.
- 3-5 Tons:Compact chassis for historic city centers and gated communities. Paris and Venice municipal authorities specify these for pedestrian-zone access.
- 5-10 Tons:Mid-range capacity balancing maneuverability with volume efficiency. Standard specification for Japanese and Korean urban fleet renewal programs.
- 10-15 Tons:Heavy-duty compaction for commercial waste streams. Brazilian and Mexican private operators deploy these for supermarket and retail chain contracts.
- Above 15 Tons:Maximum-density configurations for industrial and construction debris. Australian mining towns and Saudi industrial cities specify these for bulk material handling.
The 5-10 ton segment anchors current procurement. Above-15-ton units are expanding most quickly in resource-sector applications.
Application:
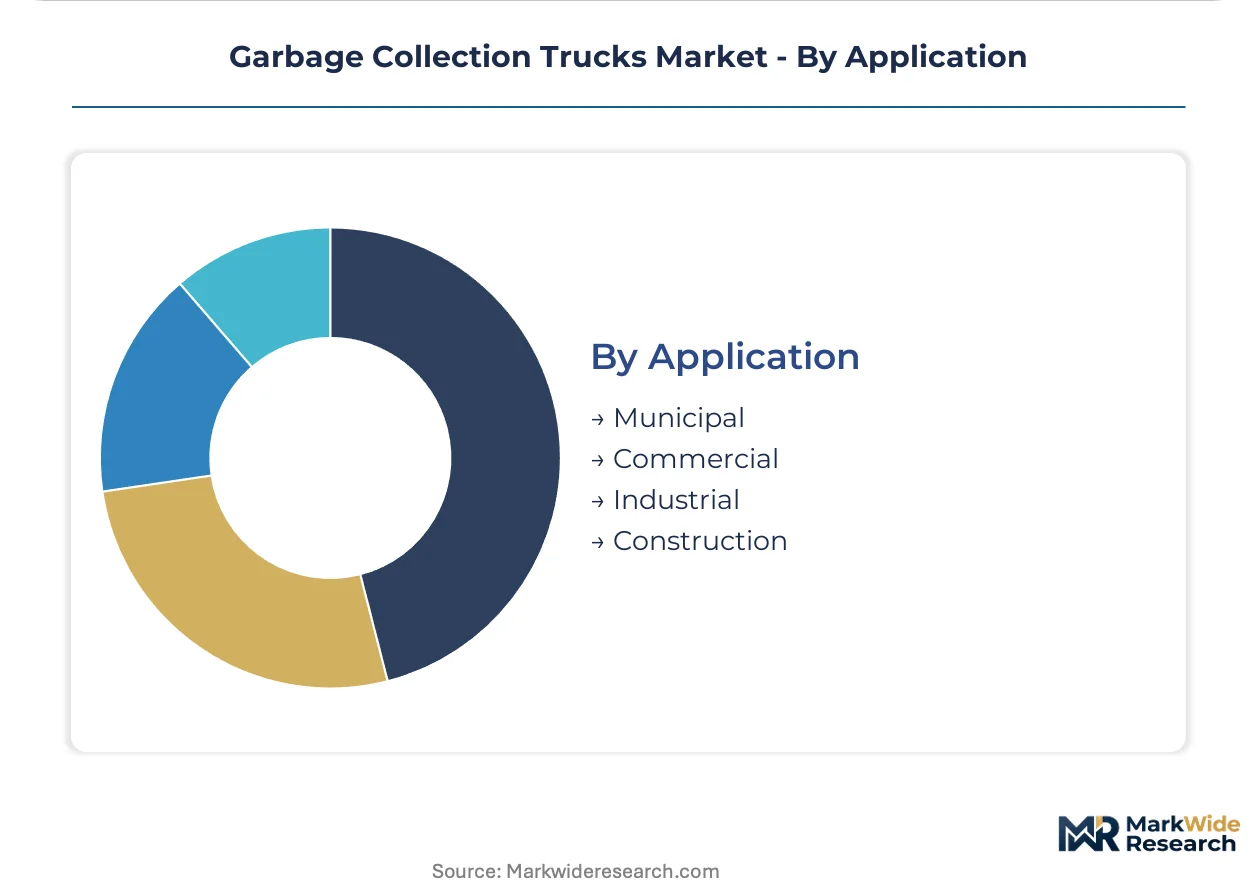
Customer-type concentration shapes margin structures. Municipal contracts emphasize lifecycle cost and emissions compliance. Commercial and industrial buyers prioritize payload utilization and uptime guarantees.
- Municipal:Tax-funded fleet procurement with multi-year replacement cycles and emissions mandates. City authorities in France and California specify electric and CNG platforms under binding decarbonization timelines.
- Commercial:Private waste management operators serving retail, hospitality, and office sectors. UK and German contractors favor automated side loaders for labor cost containment.
- Industrial:Manufacturing and logistics facility waste collection with hazardous material handling requirements. Texas and Louisiana petrochemical clusters specify specialized containment configurations.
- Construction:Demolition and renovation debris collection with reinforced body specifications. Dubai and Singapore infrastructure projects drive demand for heavy-duty front loaders.
Municipal procurement anchors installed base volumes. Commercial applications are climbing the fastest as privatization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal fleet operators concentrate procurement authority in Germany, the United States, and China, where urban density and waste management privatization compress replacement cycles. Binding emissions mandates in each jurisdiction reshape powertrain specifications and total cost of ownership calculations.
United States
California Air Resources Board mandates drive the fastest fleet conversion timeline nationwide, with Los Angeles and San Francisco specifying electric chassis for low-emission zone compliance. EPA greenhouse gas Phase 3 standards bind municipal operators to binding emissions reductions. Texas and Indiana markets retain diesel procurement where rural route distances exceed current battery range thresholds.
Germany
Municipal cooperatives prioritize CNG bridge investments pending full electrification readiness, with Hamburg and Berlin piloting solid-state battery configurations for regional landfill transfer. EU Green Deal emissions benchmarks compel member states to accelerate replacement cycles beyond historical patterns. Bavarian inter-municipal waste authorities specify LNG cryogenic storage for routes exceeding 200 kilometers.
China
Shenzhen mandates battery-electric drivetrains for all new municipal fleet additions, with Yangtze River Delta cities expanding depot charging infrastructure at unprecedented scale. MIIT new energy vehicle production quotas channel domestic OEM capacity toward refuse truck electrification. Pearl River Delta manufacturing clusters supply chassis components across Asia-Pacific procurement channels.
India
Smart Cities Mission central funding enables mechanized waste collection in tier-2 and tier-3 municipalities, with Maharashtra and Gujarat urban local bodies leading tender issuance. National clean air program regulations tighten particulate emissions standards for commercial vehicle fleets. Delhi-NCR operators face court-ordered fleet modernization timelines that compress procurement cycles.
Netherlands
Performance-based service contracting displaces equipment ownership models, with Rotterdam and Amsterdam authorities contracting for tonnes-collected-per-euro metrics. National low-carbon strategy mandates 50% electric or hydrogen-powered municipal vehicles by 2030. Dutch circular economy compliance requirements drive multi-compartment vehicle specifications for source-separated collection streams.
Garbage Collection Trucks Market Vendor Landscape
Player mix skews toward integrated chassis-body specialists with established municipal procurement relationships. Market structure exhibits tiered concentration, with defense-contracting manufacturers and automated mechanism specialists occupying premium positions alongside volume-driven commercial vehicle platforms. Three archetypes dominate: ISO 9001-certified integrated OEMs, automated lifting technology specialists, and emerging electric powertrain integrators. Competitive dynamics center on strategic partnerships with battery pack suppliers and geographic expansion into Asia-Pacific municipal channels.
Within the integrated OEM tier, Oshkosh Corporation and Scania Group exemplify contrasting regional anchoring strategies, with the former representing North American defense-contracting manufacturing discipline and the latter embodying European refuse truck powertrain integration capabilities. Heil Environmental occupies a specialist position in automated arm configurations. Among Asia-based fabricators, DESA (Henan Desa Automobile Co., Ltd.) represents Chinese domestic OEM capacity expansion under MIIT production quota frameworks.
| Leading Market Players |
|---|
| Oshkosh Corporation |
| Daimler AG |
| Heil Environmental |
| New Way |
| Scania Group |
| McNeilus Truck and Manufacturing |
| Volvo Group |
| Mack Trucks, Inc. |
| DESA (Henan Desa Automobile Co., Ltd.) |
| Others |
Supply Flow & Price Mechanics
Fourteen-week chassis lead times from European foundries concentrate pricing power with integrated OEMs capable of buffering steel hopper body inventory, while municipal fleet operators face cost-plus escalation clauses indexed to nickel and cobalt exchange benchmarks. Battery pack integrators command premium positioning as depot charging infrastructure mandates reshape total cost of ownership calculations across procurement cycles.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate municipal fleet procurement, with steel sheet and lithium-ion cell costs passing through to operators via quarterly adjustment mechanisms. Price differentiation hinges on ISO 9001 certification tier and automated arm technology bundling, with qualified OEMs capturing 15-20% premiums over secondary assemblers. Pricing pressure stems from cobalt price volatility compressing electric chassis margins. Rural diesel fleet operators in Poland and Indiana exhibit highest price sensitivity, while Dutch performance-contracting authorities prioritize lifecycle cost over capital expenditure.
Supply Chain Analysis
Strait of Malacca transit underwrites 60% of global rare earth magnet supply for electric drivetrain motors, exposing chassis manufacturers to maritime logistics disruption. Manufacturing concentrates in Germany, China, and the United States, with battery cell production anchored in South Korea and Japan. Raw material dependencies include high-strength steel plate, hydraulic compaction cylinders, and nickel-manganese-cobalt cathode formulations. Single-source vulnerability runs through Chinese rare earth processing. Distribution feeds from OEM assembly plants through municipal procurement channels and integrated waste management operator fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Garbage collection trucks are transitioning toward platform-economics architecture as telematics-enabled compaction monitoring and predictive maintenance algorithms create subscription revenue streams interoperable across municipal fleet management systems.
For Market Incumbents: Compound defensive positioning through backward integration into battery pack assembly and captive supply of automated lifting mechanisms, countering emerging electric powertrain specialists threatening chassis-body supplier relationships. Prioritize ISO 9001 certification maintenance to preserve municipal tender eligibility as audit timelines extend. Accelerate depot charging infrastructure partnerships to lock in fleet operator switching costs.
For New Entrants and Emerging Players: TÜV Rheinland certification fast-track enables qualification for German municipal cooperatives piloting solid-state battery configurations, the most penetrable entry point among premium European markets. Target India's tier-2 Smart Cities Mission municipalities where central funding compresses procurement cycles and incumbent presence remains thin. Pursue biomethane-compatible CNG powertrain specialization for Italian and Californian closed-loop waste-to-fuel opportunities.
For Investors and Strategic Acquirers: Long-term, this sits as a utility-like infrastructure play because municipal waste collection operates on essential-service demand inelasticity with decade-long fleet replacement visibility. Acquisition focus should center on automated mechanism specialists with software-defined vehicle platform capabilities. Monitor California Air Resources Board fleet conversion acceleration as inflection signal for electric chassis demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures nickel-manganese-cobalt cell allocation from Korean suppliers for electric chassis assembly scale-up. |
| Depot Charging Infrastructure Partnership | Locks in municipal fleet operator loyalty through overnight grid upgrade financing and installation bundling. |
| Automated Arm Technology Acquisition | Integrates single-operator collection capabilities defending against labor cost containment pressures. |
| Biomethane Injection Certification | Enables closed-loop fuel sourcing from anaerobic digestion facilities for Italian and Dutch operators. |
| Telematics Platform Integration | Creates subscription revenue streams through real-time compaction monitoring and predictive maintenance algorithms. |
Methodological Framework
Cross-validation between municipal procurement database analysis and OEM production records anchors the qualitative findings, combining primary interviews with fleet operations directors, chassis platform engineers, battery integrator procurement leads, and aftermarket service heads with secondary validation through EPA regulatory filings, EU Green Deal implementation reports, MIIT production quota disclosures, and municipal tender documentation. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers.
Sensitivity analysis on battery cost trajectories and charging infrastructure deployment pace shapes the analytical framework across the projection horizon, with vehicle type, fuel architecture, payload capacity tier, and application segment dimensions modeled independently. CAGRs derive from logistic diffusion curves fitted to replacement cycle data and emissions mandate compliance timelines. Industry-specific inputs include depot charging infrastructure capex curves and solid-state battery prototyping readiness indicators.
Underlying assumptions cover lithium-ion cost stabilization, EU member state fleet decarbonization adherence, and Chinese MIIT quota enforcement, with deviation risk concentrated in raw material price volatility and high-voltage technician certification pipeline constraints. Practitioners should keep alternative scenarios live as solid-state battery commercialization timelines and biomethane injection infrastructure buildout evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Digger Derrick Truck Market