
 Europe Fire Truck Market | 2026-2036
Europe Fire Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fire Truck Market Analysis
EN 1846 firefighting vehicle classification is bifurcating the competitive landscape into certified premium suppliers and regional assemblers. Rosenbauer International AG leverages its integrated chassis-body manufacturing to sustain pricing power across pumper and aerial platforms. Magirus GmbH anchors its position through deep specialization in turntable ladder technology and German municipal channel control.
A fire truck is a purpose-built emergency vehicle incorporating a fire pump, water tank, aerial device, or specialized rescue equipment mounted on a heavy-duty commercial chassis, with gross vehicle weights typically ranging from 12 to 40 tonnes depending on configuration and mission profile. Its primary purpose is to transport firefighters, suppress fires, and execute technical rescue operations under hazardous conditions. Pumper configurations occupy the largest volume share due to universal municipal deployment requirements, while electric and hybrid technology segments capture expanding margin pools as battery-electric range capabilities mature for urban duty cycles. Aerial platforms retain premium positioning through structural complexity and extended service intervals that lock in aftermarket revenue streams.
CE marking under the EU Machinery Directive and EN 1846 standards govern vehicle safety and performance certification, while the EU Green Deal's CO2 reduction pathways and national low-emission zones in Germany, France, and the Netherlands are restructuring procurement specifications toward electrified drivetrains. ECHA chemical restrictions on halogenated flame retardants further reshape material selection for cab interiors and hose assemblies. Fleet managers and OEM program directors must weigh total cost of ownership against charging infrastructure readiness when committing to next-generation platform architectures.
Market Dynamics
The EU Green Deal's CO2 reduction mandates are restructuring municipal procurement specifications across Central Europe, forcing fleet managers to evaluate battery-electric drivetrains against total cost of ownership frameworks before charging infrastructure maturity permits full deployment.
Growth Catalysts
- EU Green Deal Emissions Pathways:National low-emission zones in Germany, France, and the Netherlands are mandating electrified drivetrain adoption in municipal fleets. Cities accelerate replacement cycles to comply with 2030 CO2 targets.
- Wildland Response Networks:Nordic countries are expanding specialized aerial platform and all-terrain pumper procurement to address extended fire seasons and urban-wildland interface protection.
- EN 1846 Certification Premium:The bifurcation between certified premium suppliers and regional assemblers creates pricing power for integrated chassis-body manufacturers serving German and French municipal channels.
Market Restraints
- Battery Pack Cost Volatility:Lithium-ion cell pricing uncertainty compresses margin visibility for electric pumper programs, forcing OEMs to absorb input fluctuations or pass through to municipal buyers with multi-year budget cycles.
- Central European Manufacturing Concentration:Chassis and aerial device supply clusters in Germany and Austria create geographic vulnerability to single-source disruption for turntable ladder components.
- Halogenated Flame Retardant Restrictions:ECHA chemical limitations on legacy cab interior and hose assembly materials force material requalification, extending certification timelines for new platform introductions.
Strategic Opportunities
- Polish and Romanian Municipal Fleet Modernization:EU structural fund allocations for emergency services infrastructure in Eastern Europe create first-mover advantage for EN 1846-certified suppliers establishing local service networks.
- Battery-Electric Range Convergence:Urban duty cycle battery chemistry improvements enable 150-kilometer operational radius, unlocking full pumper electrification for city-center departments previously constrained by range anxiety.
- Aftermarket Service Unbundling:Extended aerial platform service intervals create recurring revenue streams through predictive maintenance contracts and component lifecycle management programs.
Industry Challenges
- High-Voltage Technician Scarcity:Municipal maintenance departments lack trained personnel for battery-electric fire truck servicing, forcing OEMs to embed field service engineers or fund vocational retraining partnerships.
- CE Marking and EN 1846 Recertification Burden:Each drivetrain variant requires separate EU Machinery Directive compliance documentation, multiplying engineering overhead for hybrid-electric platform portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fire Truck Market |
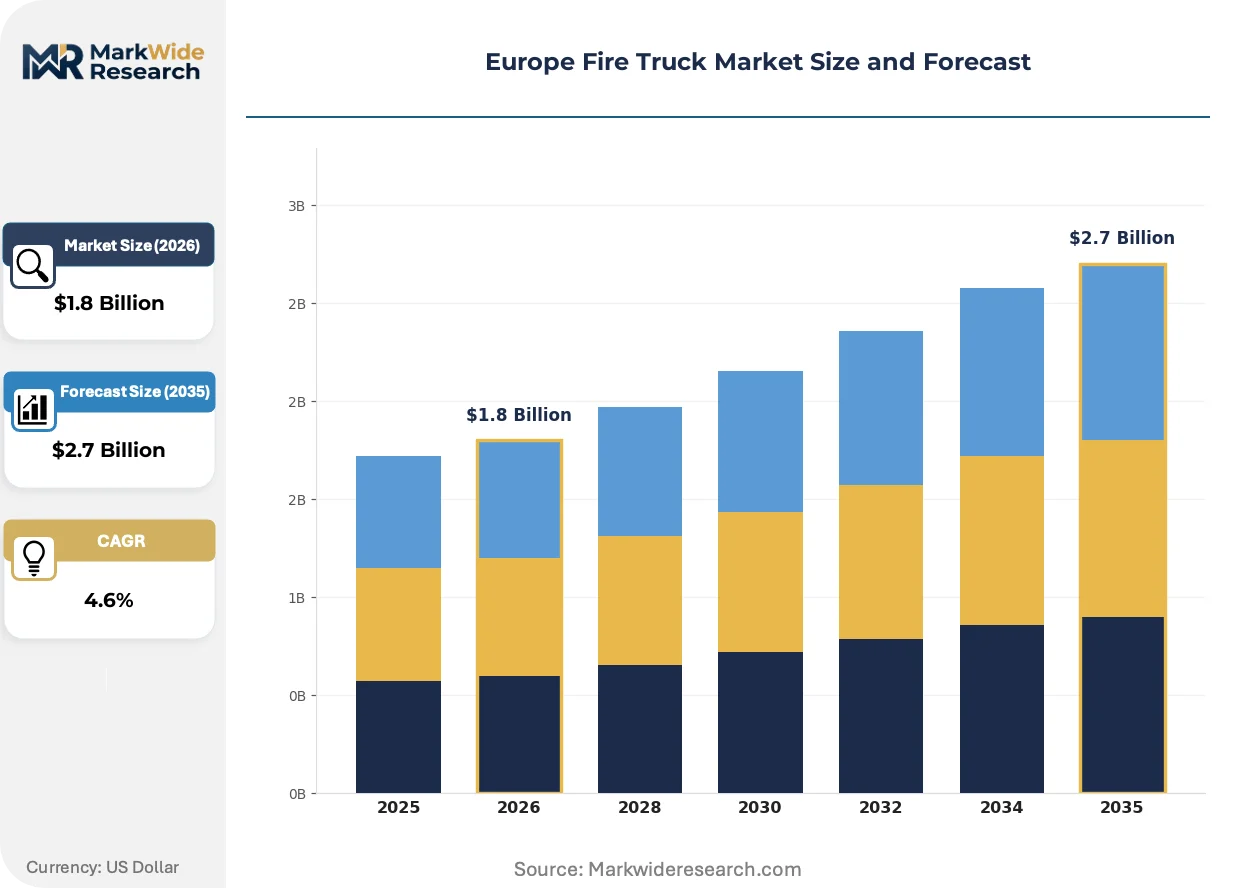
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumper, Aerial, Tanker, Brush Truck Application: Urban Firefighting, Industrial Response, Wildland Control, Emergency Medical Services End User: Municipal Fire Departments, Industrial Facilities, Forestry Services, Private Sector Technology: Conventional, Hybrid, Electric, Autonomous |
| Companies Covered | Rosenbauer International AG, Magirus GmbH, Albert Ziegler GmbH, Nordic Rescue Group, Euro GV, Scania AB, MAN Truck & Bus SE, IVECO S.p.A., Gimaex GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fire Truck Market Emerging Trajectories
Electrification architecture and connected fleet management systems are converging to redefine operational economics for European municipal fire departments, compressing traditional replacement cycles and reshaping supplier-buyer relationships.
Modular battery-electric drivetrain platforms are supplanting conventional diesel pumper configurations in urban procurement specifications. German municipal departments in Berlin and Munich are piloting 18-tonne electric pumpers with 350 kWh battery packs. This technology is compressing total cost of ownership calculations by eliminating diesel particulate filter maintenance and reducing brake wear through regenerative braking systems.
The EU Green Deal's CO2 reduction pathways are mandating lifecycle emissions disclosure in public procurement tenders. Municipal buyers must now document cradle-to-grave carbon footprints for fleet acquisitions, favoring suppliers with verified supply chain decarbonization. French and Dutch fire authorities are incorporating these requirements into multi-year framework agreements, locking out non-compliant regional assemblers.
Swedish and Norwegian fire authorities are consolidating purchasing through national cooperative procurement frameworks, displacing fragmented municipal tendering. These centralized buying organizations negotiate volume discounts and standardize specifications across regional departments. The shift concentrates bargaining power with Stockholm and Oslo-based fleet managers while reducing customization flexibility for specialized rural response units.
Europe Fire Truck Market Segmentation
EN 1846 certification tiers and EU Green Deal compliance pathways fragment procurement specifications across European municipal channels. Fleet managers must align segment selection with duty cycle requirements, emissions zone restrictions, and total cost of ownership frameworks before platform commitment.
Product Type:
CE marking under the EU Machinery Directive creates divergent compliance burdens across chassis-body integration complexity, with integrated manufacturers capturing premium positioning in certified aerial configurations.
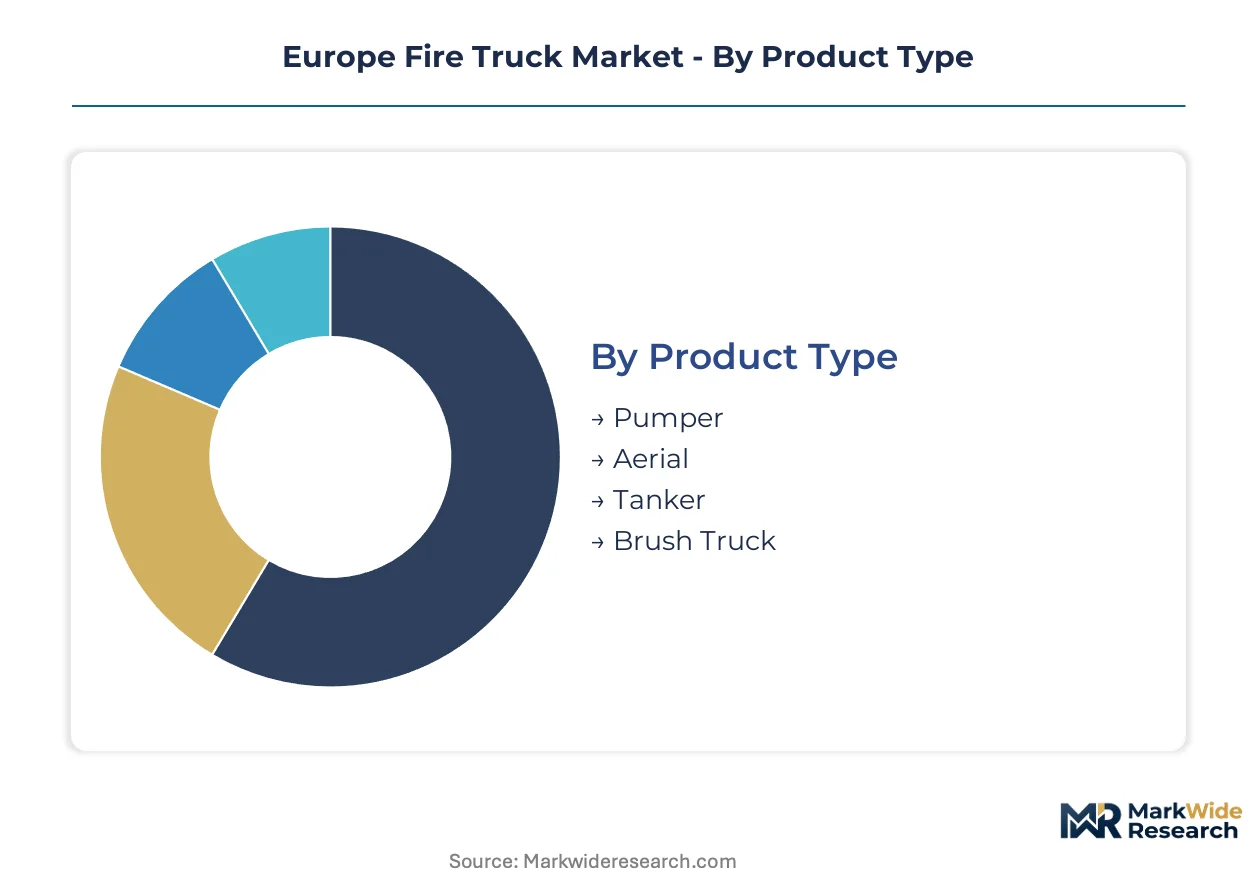
- Pumper:Universal municipal deployment configuration incorporating fire pump, water tank, and hose storage on heavy-duty chassis. German and French municipal departments concentrate replacement demand here as baseline fleet modernization accelerates under national low-emission zone mandates.
- Aerial:Turntable ladder and platform configurations with extended structural complexity lock in aftermarket revenue through specialized service intervals. Nordic urban-wildland interface protection programs are expanding procurement of these premium units despite longer production lead times.
- Tanker:High-capacity water transport for rural response networks where hydrant infrastructure is sparse. Forestry Services in Poland and Romania deploy these for extended wildland operations.
- Brush Truck:Compact off-road configuration for vegetation fire suppression and initial attack. Portuguese and Spanish fire authorities prioritize these for Mediterranean scrubland response.
Pumper configurations handle the majority of throughput; electric pumper variants are gaining share fastest as battery chemistry matures for urban duty cycles.
Application:
Operational environment dictates equipment specification intensity, with urban departments facing the steepest electrification pressure under municipal emissions frameworks.
- Urban Firefighting:Dense infrastructure response requiring maneuverable chassis and rapid deployment systems. Berlin and Munich pilot programs are validating 18-tonne electric platforms with 350 kWh battery packs for city-center deployment.
- Industrial Response:Hazardous material and technical rescue operations demanding specialized foam systems and breathing apparatus integration. German chemical corridor facilities along the Rhine mandate these configurations for regulatory compliance.
- Wildland Control:Extended fire season operations across Nordic and Mediterranean territories. Swedish and Norwegian national procurement frameworks are consolidating volume purchases for these specialized units.
- Emergency Medical Services:Dual-purpose rescue vehicles with patient transport capability. French departmental fire services integrate these into multi-mission fleet architectures.
Urban Firefighting commands the largest equipment volume; Wildland Control is expanding most quickly as climate adaptation budgets reallocate across Northern Europe.
End User:
Procurement centralization trends are restructuring buyer concentration, with national cooperative frameworks displacing fragmented municipal tendering in Scandinavia.
- Municipal Fire Departments:Primary volume channel across German, French, and Benelux cities. EU structural fund allocations in Eastern Europe are unlocking modernization cycles in Polish and Romanian departments.
- Industrial Facilities:On-site response units for chemical, petrochemical, and manufacturing complexes. Rotterdam and Antwerp port authorities maintain dedicated fleets under industrial safety directives.
- Forestry Services:National and regional agencies managing wildland fire suppression across Sweden, Finland, and Iberian territories. Seasonal deployment patterns create irregular procurement timing.
- Private Sector:Airport rescue and industrial contract fire services operating under concession agreements. London Heathrow and Frankfurt Airport maintain specialized procurement specifications.
Municipal Fire Departments anchor equipment demand; Industrial Facilities are climbing the fastest on share as site-specific safety regulations tighten.
Technology:
Battery-electric range convergence and high-voltage technician scarcity are creating a transitional technology mix, with hybrid platforms bridging infrastructure gaps.
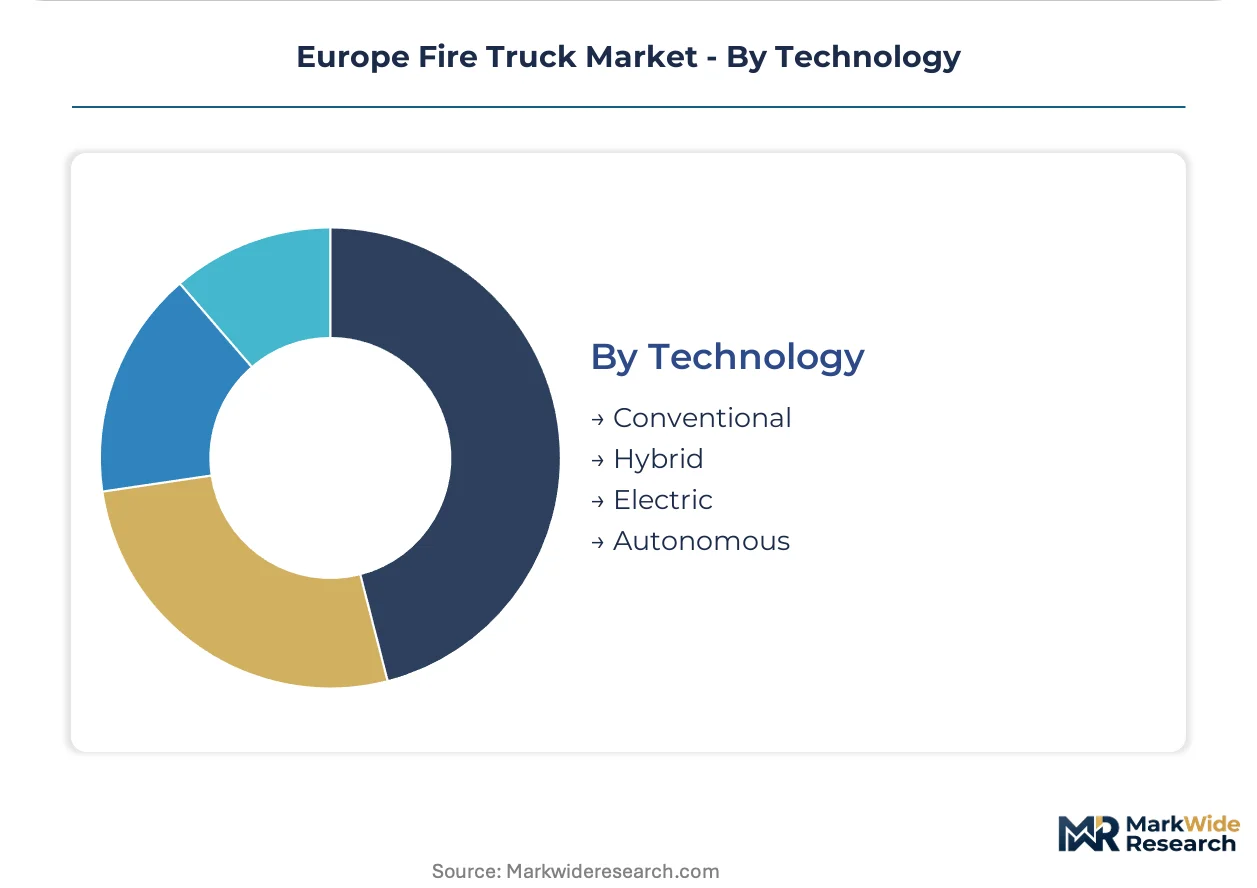
- Conventional:Diesel powertrain with established service networks and parts availability. Rural departments in Austria and Switzerland retain these where charging infrastructure remains underdeveloped.
- Hybrid:Dual-mode drivetrain combining diesel range extension with electric operation in low-emission zones. Dutch fire authorities specify these for transitional compliance before full electrification.
- Electric:Battery-electric platforms with regenerative braking and eliminated particulate filter maintenance. Copenhagen and Amsterdam city-center departments are deploying these under strict municipal emissions mandates.
- Autonomous:Remote-operated or teleoperated platforms for hazardous environment reconnaissance. Limited pilot programs in German industrial test zones.
Conventional technology retains the installed base; Electric configurations show the steepest expansion trajectory as 150-kilometer operational radius becomes viable for standard pumper duty cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's CO2 reduction mandates are restructuring municipal procurement specifications across Central Europe, forcing fleet managers to evaluate battery-electric drivetrains against total cost of ownership frameworks before charging infrastructure maturity permits full deployment.
Germany
Berlin and Munich municipal departments are piloting 18-tonne electric pumpers with 350 kWh battery packs. The KBA enforces stringent emissions certification for municipal fleet acquisitions. Manufacturing clusters in Baden-Württemberg and Bavaria host integrated chassis-body producers serving French and Benelux export channels.
France
Departmental fire services are consolidating multi-mission fleet architectures around dual-purpose rescue vehicles. National low-emission zones in Paris, Lyon, and Marseille mandate electrified drivetrain adoption with 2030 compliance deadlines. The Île-de-France region anchors procurement volume for aerial platform specialization.
Sweden
National cooperative procurement frameworks are displacing fragmented municipal tendering across Stockholm, Gothenburg, and Malmö. Extended fire seasons are expanding specialized aerial platform procurement for urban-wildland interface protection. Forestry Services in Norrland deploy high-capacity tankers for extended wildland operations.
Poland
EU structural fund allocations are unlocking modernization cycles in Warsaw, Kraków, and Wrocław municipal departments. ECHA chemical restrictions on halogenated flame retardants are forcing material requalification for cab interiors. Silesian manufacturing corridors are emerging as assembly hubs for EN 1846-certified exports.
Netherlands
Amsterdam and Rotterdam city-center departments are deploying full battery-electric platforms under strict municipal emissions mandates. Dutch fire authorities specify hybrid configurations for transitional compliance before full electrification. Port authorities in Rotterdam maintain dedicated industrial response fleets under safety directives.
Europe Fire Truck Market Vendor Landscape
Listed leaders compete with private specialists across chassis-body integration complexity, creating a tiered structure where certification depth determines pricing power. The vendor base concentrates around integrated manufacturers capturing premium positioning in aerial configurations, while regional assemblers serve price-sensitive municipal channels. Two strategic archetypes dominate: integrated chassis-body producers with captive supply chains, and specialized aerial device fabricators with aftermarket service lock-in. Competitive moves center on EN 1846 recertification speed and geographic expansion into Eastern European municipal markets.
Among German-based integrated manufacturers, Rosenbauer International AG and Magirus GmbH exemplify the premium-tier archetype through deep specialization in turntable ladder technology and municipal channel control. Albert Ziegler GmbH occupies a position within the certified supplier tier, representing the pattern of family-owned fabricators with long-standing regional service networks. These three anchors illustrate how EN 1846 certification bifurcation creates sustainable competitive positioning against non-certified regional assemblers.
| Leading Market Players |
|---|
| Rosenbauer International AG |
| Magirus GmbH |
| Albert Ziegler GmbH |
| Nordic Rescue Group |
| Euro GV |
| Scania AB |
| MAN Truck & Bus SE |
| IVECO S.p.A. |
| Gimaex GmbH |
| Others |
Supply Flow & Price Mechanics
EN 1846 certification gates both supplier qualification and price differentiation simultaneously, bifurcating European municipal procurement into premium integrated manufacturers and price-sensitive regional assemblers. Municipal fleet managers in Germany and France weigh total cost of ownership against electrification mandates, compressing margin visibility for OEMs navigating battery pack cost volatility and multi-year budget cycles.
Pricing Analysis
Certification level under EN 1846 and CE marking creates the primary spread between premium integrated chassis-body producers and non-certified regional suppliers. Three-tier pricing structure separates EN 1846-certified aerial platforms from standard pumper configurations and economy-grade tanker units. Cost compression in electric pumper segments is intensifying because lithium-ion cell pricing uncertainty forces OEMs to absorb input fluctuations or pass through to municipal buyers. Polish and Romanian municipal departments exhibit highest price sensitivity due to EU structural fund dependency, while German chemical corridor facilities show lowest sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Extended production lead times for turntable ladder components stretch 12-18 months for aerial platform configurations. Manufacturing gravity centers on Germany, Austria, and Poland for chassis-body integration and aerial device fabrication. Supply chains draw from high-strength steel mills in Sweden, lithium-ion cell producers in South Korea, and electronic control systems from Japanese Tier 1 suppliers. Single-source vulnerability concentrates in German turntable ladder component clusters. Distribution runs through municipal procurement frameworks, national cooperative purchasing organizations in Scandinavia, and industrial facility direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's electrification mandates constitute a structural inflection, accelerating fleet replacement cycles and reshaping competitive positioning across Central and Eastern European municipal channels.
For Market Incumbents: Shield premium positioning by accelerating EN 1846 recertification for battery-electric platform variants before Eastern European structural fund windows close. Deepen backward integration into high-voltage battery pack assembly to capture margin pools threatened by cell cost volatility. Lock in municipal channel control through predictive maintenance contract bundling that offsets upfront electrification premiums.
For New Entrants and Emerging Players: Anchor in Polish and Romanian municipal fleet modernization cycles where EU structural fund allocations create first-mover advantage for EN 1846-certified suppliers establishing local service networks. Target wildland response configurations for Nordic national procurement frameworks consolidating volume purchases. Pursue aftermarket service unbundling as the primary go-to-market angle, leveraging extended aerial platform service intervals for recurring revenue capture.
For Investors and Strategic Acquirers: The EU Green Deal's 2030 CO2 compliance deadlines reshape the acquisition landscape toward electrification-ready platform portfolios and captive charging infrastructure partnerships. Long-term viability favors integrated chassis-body manufacturers with verified supply chain decarbonization and established municipal channel relationships. Target acquisition archetype: mid-cap EN 1846-certified fabricators with Eastern European service network gaps. Monitor battery-electric range convergence past 150-kilometer operational radius as the signal to watch for full pumper electrification inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EN 1846 Recertification Acceleration | CE marking compliance under EU Machinery Directive locks out non-certified regional assemblers from German and French municipal tenders. |
| Battery-Electric Platform Development | 350 kWh battery pack integration for 18-tonne urban pumpers validates Copenhagen and Amsterdam municipal deployment specifications. |
| Eastern European Service Network Buildout | EU structural fund allocations in Poland and Romania reward first-mover EN 1846-certified suppliers with multi-year framework agreements. |
| Predictive Maintenance Contract Bundling | Extended aerial platform service intervals create recurring revenue streams that offset upfront electrification premiums for municipal buyers. |
| High-Voltage Technician Training Partnerships | Municipal maintenance department capability gaps force OEMs to embed field service engineers or fund vocational retraining programs. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with fleet managers, OEM program directors, municipal procurement officers, and aftermarket service heads; and secondary validation through KBA emissions certification records, EU Machinery Directive CE marking databases, ECHA chemical restriction filings, and municipal tender documentation. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs by product type, application, end user, and technology segments. CAGRs were derived from regression analysis of historical replacement cycles, electrification adoption curves, and EU Green Deal compliance pathway assumptions. Forecast inputs incorporated battery chemistry maturation trajectories for urban duty cycles and Nordic wildland response network expansion budgets.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and lithium-ion cell pricing stabilization; material deviation in regulatory timelines or battery cost trajectories would warrant model refresh. Supply chain disruption scenarios and municipal budget austerity measures represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Global Connected Truck Market