
 Europe Medium & Heavy-Duty Truck Rental Market | 2026-2036
Europe Medium & Heavy-Duty Truck Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medium & Heavy-Duty Truck Rental Market Insights
Buyer concentration across European logistics is decoupling as mid-sized freight operators fragment into specialized regional carriers while large retail consolidators expand fleet outsourcing. Fraikin SAS leverages its full-service lease model to anchor fleet management contracts across France and Southern Europe. TIP Group sustains pan-European coverage through its trailer and tractor rental network. Penske Truck Leasing competes on integrated maintenance programs for cross-border operators.
Medium and heavy-duty truck rental covers commercial vehicles above 3.5 tonnes gross vehicle weight, including tractor units, box trucks, flatbed trucks, and refrigerated trucks, typically offered through short-term rental, long-term rental, lease, or fleet management arrangements with pricing structured around daily rates, mileage, or subscription terms. Refrigerated trucks command premium positioning due to cold-chain compliance costs and specialized equipment depreciation. Short-term rental is gaining share among e-commerce fulfillment networks facing seasonal volume spikes. Long-term lease structures dominate construction and retail sectors seeking balance sheet flexibility.
Euro VI standards under the European Commission framework, REACH chemical compliance for vehicle materials, and the EU Green Deal carbon reduction targets collectively reshape fleet procurement toward lower-emission rental options. ECHA substance restrictions and national low-emission zones in German, French, and British cities limit older vehicle deployment, accelerating rental fleet turnover. Stakeholders must monitor regulatory tightening on CO2 performance standards and assess how zero-emission mandates alter total cost of ownership calculations across rental contract structures.
Market Dynamics
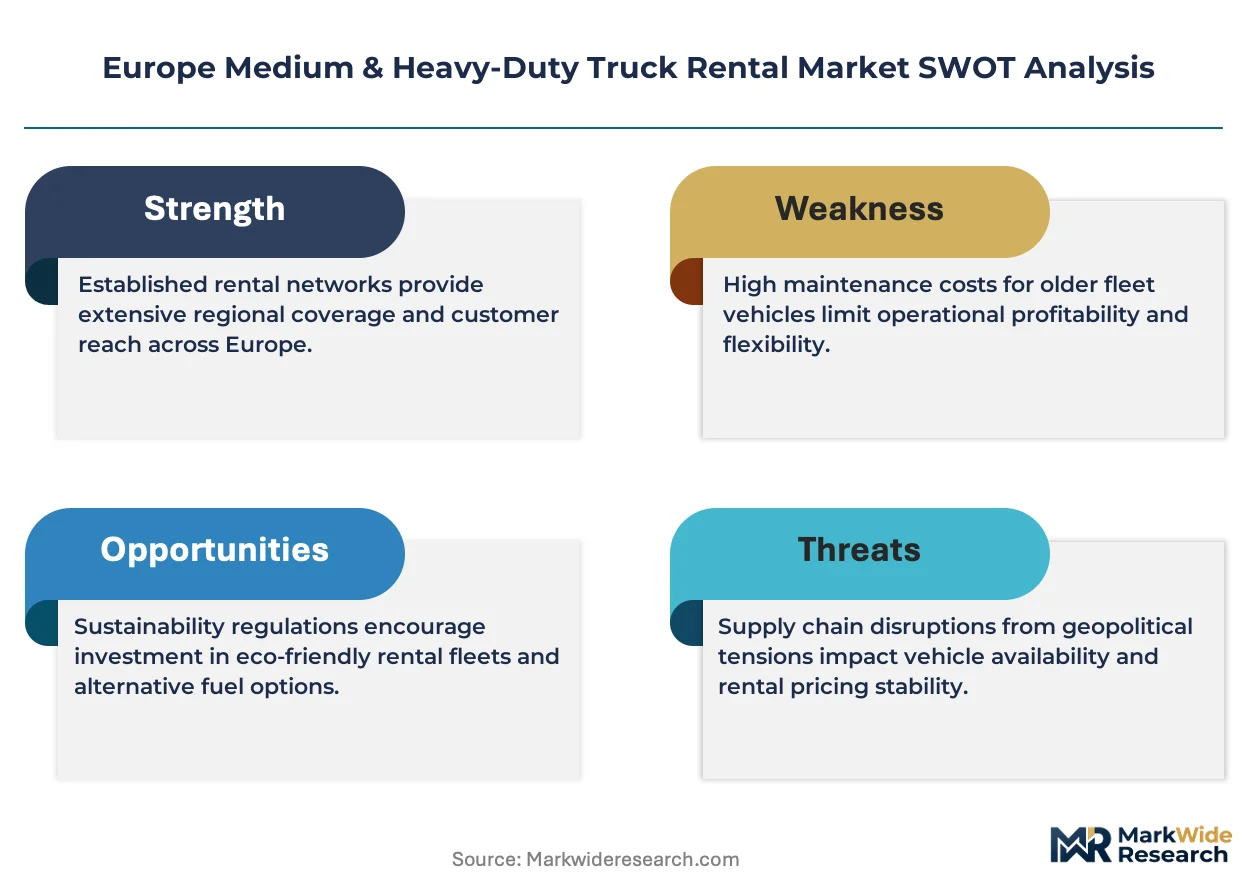
Fleet procurement across Europe is fragmenting as mid-sized logistics operators abandon ownership models in favor of flexible rental structures that transfer residual value risk to lessors while accommodating volatile freight volumes.
Growth Catalysts
- Euro VI Emissions Standards:KBA enforcement in Germany and ANSM low-emission zones in French urban centers are accelerating fleet turnover toward compliant rental vehicles as operators delay capital commitments to owned assets.
- Cold-Chain Logistics Expansion:Pharmaceutical distributors and fresh-food retailers in the Netherlands are scaling refrigerated truck rentals to meet GDP compliance for temperature-sensitive cargo without bearing equipment depreciation.
- Battery-Electric Powertrain Maturation:Rental fleets are absorbing technology transition risk as OEMs introduce zero-emission tractor units, allowing operators to test range capabilities before committing to purchase.
Market Restraints
- Semiconductor Supply Concentration:ECU and sensor shortages concentrated in Asian foundries are extending delivery timelines for new rental fleet additions across European lessors.
- Residual Value Uncertainty:Depreciation curves for alternative-fuel trucks remain unproven, compressing lessor margins and tightening credit terms for fleet expansion.
- REACH Chemical Compliance:ECHA substance restrictions on vehicle materials are raising refurbishment costs for older rental units and accelerating scrappage decisions.
Strategic Opportunities
- Poland and Romania Logistics Corridors:Underpenetrated rental markets along east-west freight routes offer expansion potential as manufacturing investment shifts eastward within the EU.
- EU Green Deal Carbon Pricing:Emissions trading scheme expansion is creating cost advantages for electric rental fleets versus diesel ownership, incentivizing contract migration.
- Telematics-Subscription Bundling:Fleet management platforms integrating real-time tracking with rental contracts are capturing ancillary revenue streams from construction and waste management verticals.
Industry Challenges
- Technician Certification Gaps:High-voltage electric drivetrain servicing requires specialized training that European technical institutes have not scaled to match fleet electrification timelines.
- Cross-Border Regulatory Friction:Divergent national low-emission zone rules between Germany, France, and the United Kingdom complicate pan-European rental contract standardization and vehicle deployment logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medium & Heavy-Duty Truck Rental Market |
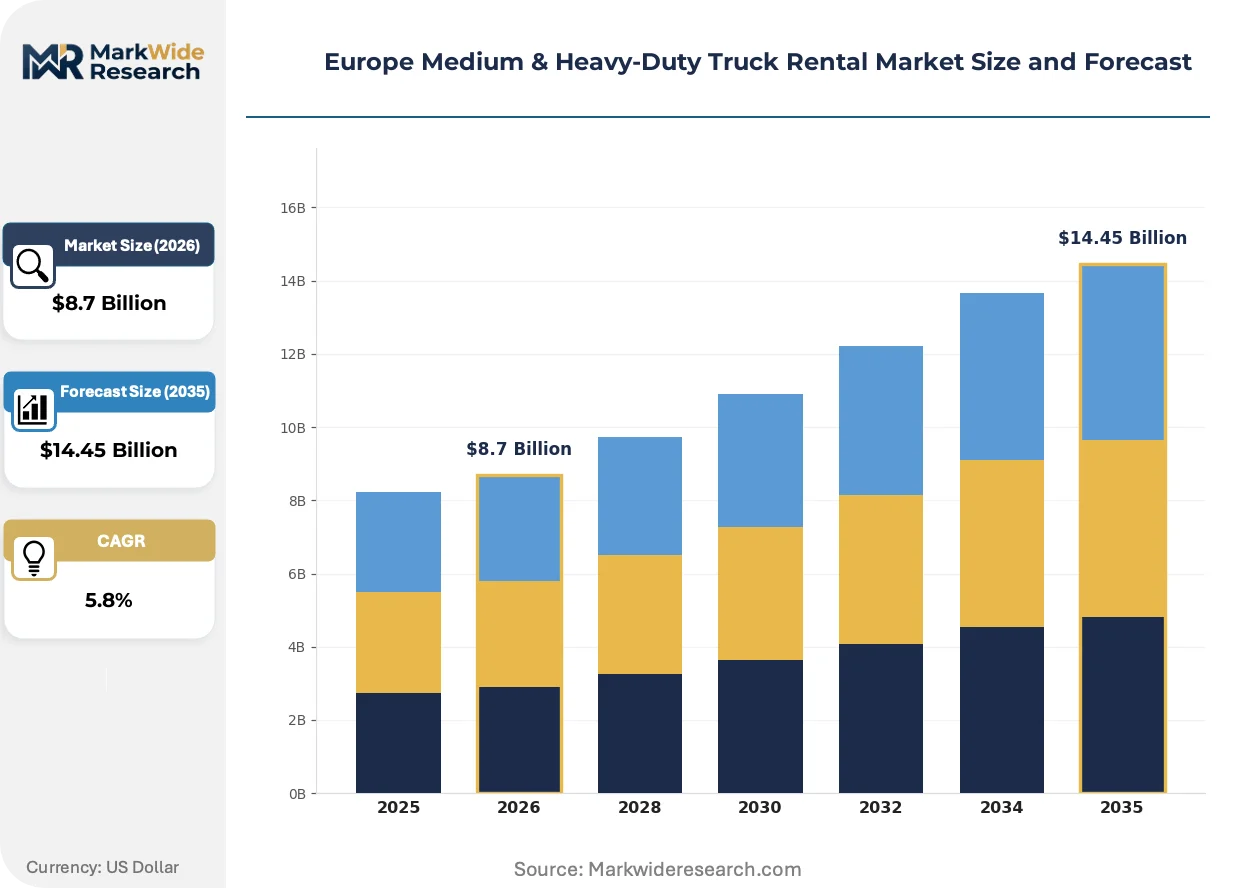
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Tractor Units, Box Trucks, Flatbed Trucks, Refrigerated Trucks Service Type: Short-Term Rental, Long-Term Rental, Lease, Fleet Management End User: Construction, Logistics, Retail, E-Commerce Pricing Model: Pay-As-You-Go, Subscription, Daily Rates, Mileage-Based |
| Companies Covered | Penske Truck Leasing, Tip Trailer Services Germany GmbH, TIP Group, Scania Rent, Mercedes-Benz CharterWay, Fraikin SAS, PACCAR Leasing Company, ATL Renting, Ryder System Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medium & Heavy-Duty Truck Rental Market Trends and Innovations
Telematics integration and alternative powertrain deployment are restructuring how rental fleets are priced, maintained, and deployed across European logistics corridors.
Telematics platforms are converging with predictive maintenance algorithms to transform rental fleet operations. German construction contractors are adopting these systems fastest, using real-time diagnostics to minimize unplanned downtime. This convergence is compressing traditional break-fix service models into uptime-guarantee contracts that shift operational risk to lessors.
EU Green Deal carbon reduction targets are mandating zero-emission fleet procurement across member states. The European Commission's CO2 performance standards for heavy-duty vehicles are forcing rental providers to accelerate electric and hydrogen tractor unit deployment. Logistics operators in the United Kingdom and France are responding by favoring rental contracts that include guaranteed replacement vehicles during charging downtime.
Seasonal volume volatility is driving demand for short-term rental structures among e-commerce fulfillment networks. Peak-season surges in parcel volumes are displacing year-round lease commitments with on-demand capacity contracts. This pattern is most visible in the Netherlands and Belgium, where distribution hub density supports rapid vehicle redeployment between regional carriers.
Europe Medium & Heavy-Duty Truck Rental Market Segmentation
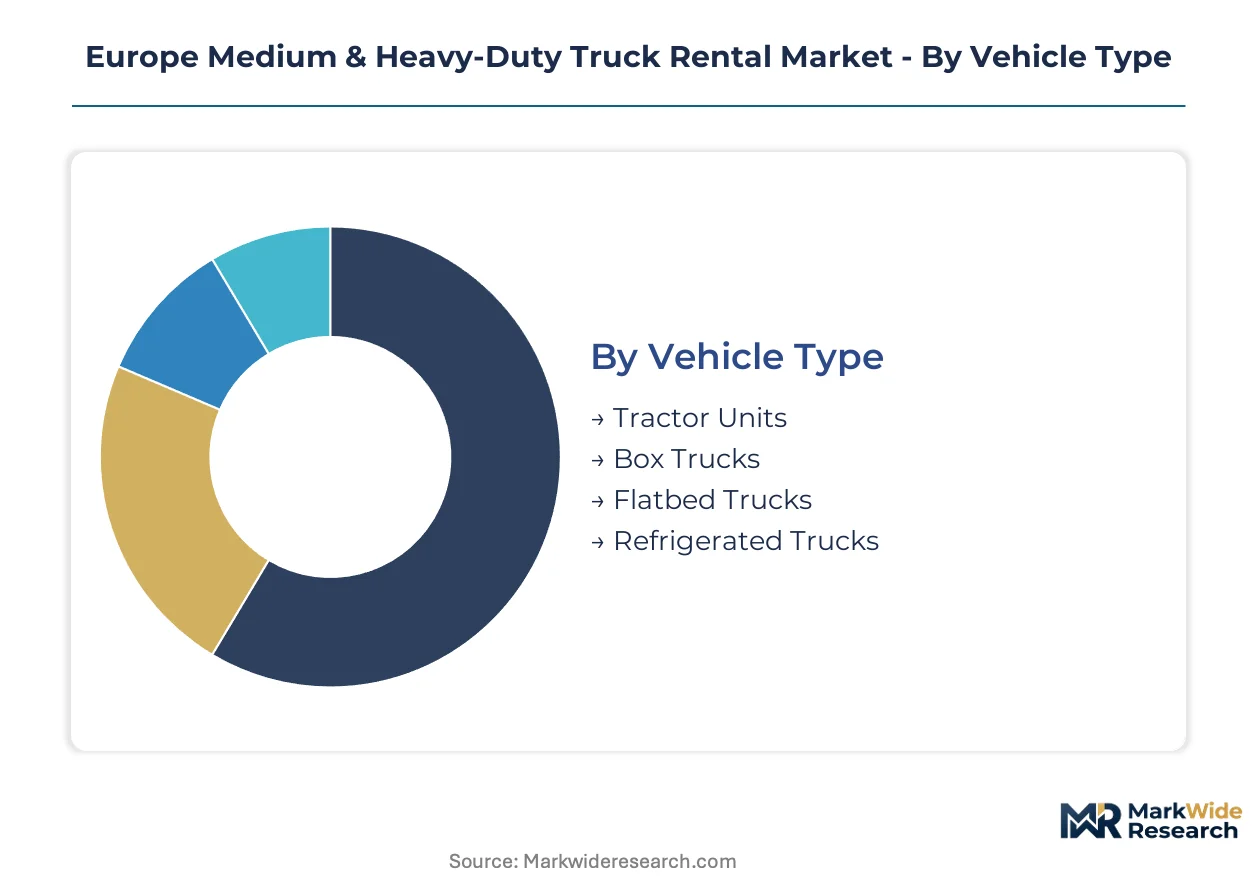
Segmentation in the Europe Medium & Heavy-Duty Truck Rental Market reveals how lessors structure contracts around asset intensity, regulatory exposure, and operational flexibility. Each dimension captures distinct risk-transfer preferences between fleet operators and rental providers.
Vehicle Type:
Volume deployment concentrates in standardized dry-freight platforms, while premium positioning attaches to temperature-controlled and specialized equipment.
- Tractor Units:Heavy-duty prime movers designed for semi-trailer coupling, typically rated above 16 tonnes gross vehicle weight. German long-haul operators favor rental structures here to defer Euro VI compliance costs amid KBA enforcement tightening.
- Refrigerated Trucks:Insulated box bodies with integrated refrigeration units maintaining cargo temperatures between -25°C and +25°C. Dutch pharmaceutical distributors and fresh-food retailers in France drive premium rental demand to satisfy GDP cold-chain compliance without capital lock-up.
- Box Trucks:Rigid-body vehicles with enclosed cargo areas, commonly 7.5 to 18 tonnes. Urban last-mile delivery networks in Belgium deploy these through short-term contracts during peak e-commerce seasons.
- Flatbed Trucks:Open-deck platforms for oversized or construction materials, often with removable side stakes. Spanish and Italian construction contractors source these through project-linked rental agreements tied to infrastructure build cycles.
Mature deployment sits with tractor units. Newer deployment is concentrated in refrigerated trucks.
Service Type:
Contract duration separates operational flexibility seekers from balance-sheet optimizers seeking predictable cost structures.
- Long-Term Rental:Fixed-term contracts typically spanning 12 to 60 months with bundled maintenance and residual value guarantees. French retail chains leverage these structures to preserve credit capacity for store expansion.
- Fleet Management:Comprehensive outsourcing encompassing vehicle acquisition, maintenance, compliance monitoring, and disposal. British logistics consolidators adopt these programs to centralize multi-site operations under single lessor accountability.
- Short-Term Rental:Daily to monthly arrangements for surge capacity or vehicle replacement. Polish and Romanian freight operators use these to navigate volatile east-west corridor volumes without fleet ownership.
- Lease:Finance lease structures transferring ownership risk at contract end, popular among German mid-sized carriers seeking asset control without upfront capital deployment.
Balance-sheet-driven adoption centers on fleet management. Operational flexibility seekers gravitate fastest toward short-term rental.
End User:
Application intensity determines whether rental contracts prioritize uptime guarantees, seasonal scalability, or regulatory compliance support.
- Logistics:Third-party freight operators and dedicated contract carriers requiring pan-European fleet deployment. German and Dutch corridor operators dominate contract volumes here.
- E-Commerce:Parcel and fulfillment networks facing extreme volume seasonality. Belgian and Netherlands distribution hubs drive demand for on-demand capacity scaling.
- Construction:Civil engineering and building contractors with project-linked equipment needs. Spanish infrastructure stimulus programs are expanding rental penetration in this vertical.
- Retail:Grocery and general merchandise chains operating private distribution fleets. French hypermarket operators favor long-term structures to lock in refrigerated capacity.
Established rental penetration sits with logistics. E-commerce is climbing the fastest as fulfillment networks abandon owned fleet models.
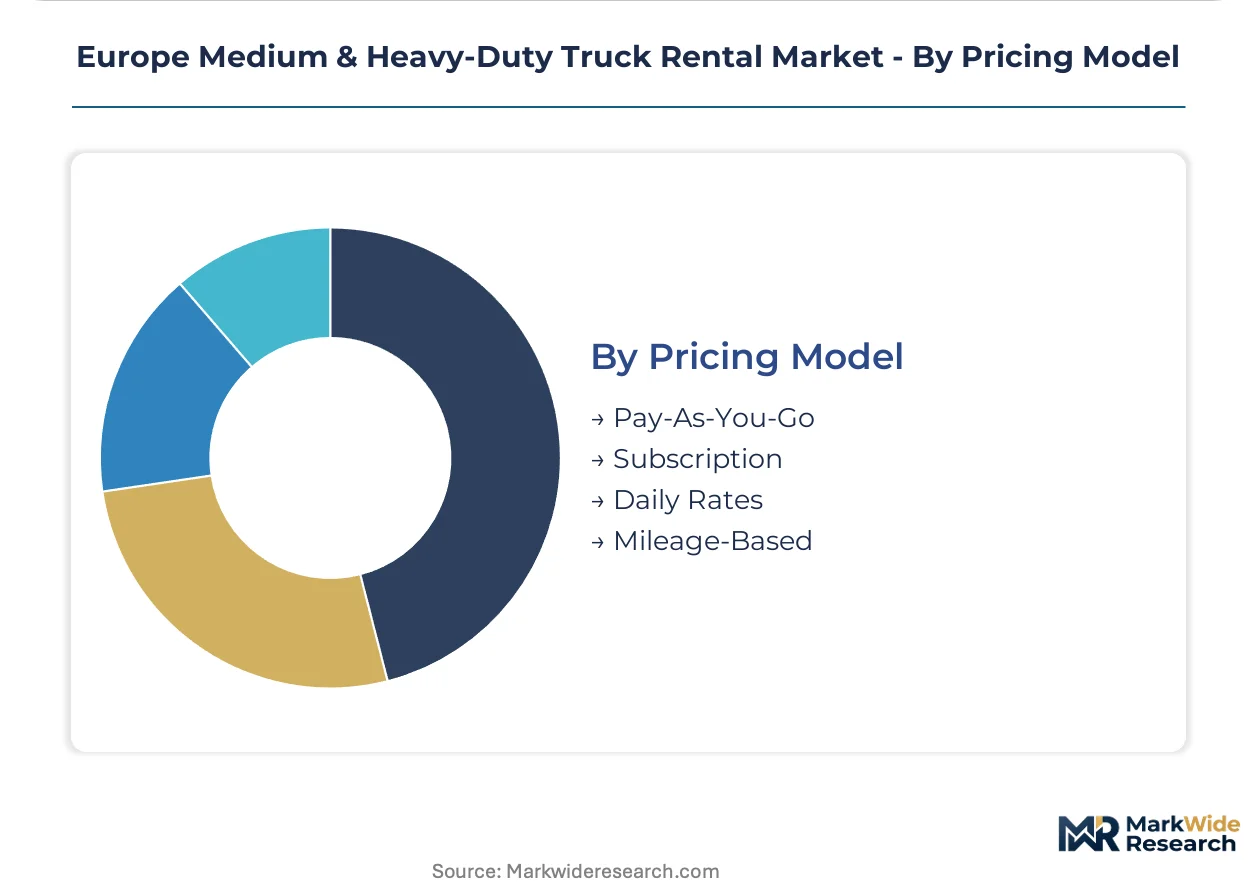
Pricing Model:
Cost predictability preferences segment buyers between consumption-based and fixed-commitment structures.
- Mileage-Based:Variable pricing tied to kilometers driven, with tiered rates for distance bands. Long-haul operators across German autobahn corridors favor this for transparent cost allocation.
- Subscription:Flat monthly fees covering vehicle access, maintenance, and insurance regardless of utilization. British urban delivery fleets adopt these for budget predictability amid congestion charge uncertainty.
- Daily Rates:Simple per-day pricing for short-term needs, common in replacement vehicle and seasonal surge scenarios. French construction contractors use these for equipment gaps during peak building seasons.
- Pay-As-You-Go:Usage-triggered billing with minimal base commitment, emerging in telematics-integrated platforms. Dutch last-mile operators pilot these for electric vehicle trials under EU Green Deal incentives.
Conventional dominance rests with mileage-based structures. Subscription models are gaining share fastest among sustainability-focused fleet renewals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhine-Ruhr logistics density and Dutch port throughput anchor European truck rental demand. The region's freight corridors concentrate contract volumes in Germany, the Netherlands, France, Belgium, and Poland.
Germany
Long-haul freight operators along the A2 and A3 autobahn corridors favor rental tractor units to defer Euro VI compliance costs. KBA enforcement tightens emission inspections for heavy-duty fleets. The Rhine-Ruhr industrial cluster around Düsseldorf and Cologne drives refrigerated truck contracts for chemical and pharmaceutical distribution.
Netherlands
Rotterdam port throughput and Schiphol cargo volumes generate sustained demand for temperature-controlled rental vehicles. ANSM low-emission zone rules in Amsterdam and Utrecht restrict older diesel deployment. The Randstad logistics ring concentrates short-term rental contracts for e-commerce fulfillment networks.
France
Parisian retail consolidators outsource fleet management to preserve balance-sheet flexibility for store expansion. Crit'Air vignette requirements in Lyon and Marseille accelerate rental fleet turnover toward compliant vehicles. The Île-de-France distribution hub anchors long-term lease structures for grocery and hypermarket chains.
Belgium
Antwerp-Brussels logistics density supports rapid vehicle redeployment between regional carriers during seasonal volume spikes. Low-emission zone regulations in Brussels and Ghent limit non-compliant truck circulation. The Flanders distribution corridor drives daily-rate contracts for construction material transport.
Poland
East-west manufacturing supply chains generate volatile freight volumes that favor short-term rental over ownership commitment. EU Green Deal carbon pricing creates cost advantages for electric rental fleets versus diesel procurement. The Silesian industrial basin and Warsaw logistics zone concentrate emerging rental penetration.
Europe Medium & Heavy-Duty Truck Rental Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue telematics-integrated subscription models and electric fleet specialization. The vendor base spans pan-European lessors, OEM-captive rental divisions, and independent fleet management specialists. Three archetypes dominate: full-service lease providers absorbing residual value risk, short-term rental specialists optimizing asset utilization rates, and technology-forward platforms bundling real-time tracking with flexible contracts. Competitive moves concentrate on geographic expansion along underpenetrated east-west corridors and portfolio diversification into refrigerated and electric vehicle segments.
Within the full-service lease tier, Fraikin SAS exemplifies the integrated fleet management archetype across France and Southern Europe. TIP Group occupies a position as a pan-European trailer and tractor rental network with coverage density in German and Dutch corridors. Penske Truck Leasing represents the maintenance-integrated model for cross-border operators seeking predictable cost structures. These three anchors illustrate how lessors differentiate through service bundling rather than asset ownership alone.
| Leading Market Players |
|---|
| Penske Truck Leasing |
| Tip Trailer Services Germany GmbH |
| TIP Group |
| Scania Rent |
| Mercedes-Benz CharterWay |
| Fraikin SAS |
| PACCAR Leasing Company |
| ATL Renting |
| Ryder System Inc. |
| Others |
Pricing and Supply Chain Analysis
Large retail consolidators in France and Germany anchor contract volumes toward long-term fleet management structures with bundled maintenance guarantees. Their procurement concentration shifts pricing power toward lessors offering residual value absorption and regulatory compliance support across Euro VI and EU Green Deal mandates.
Pricing Analysis
High-volume dry-freight tractor units trade on thin margins while refrigerated trucks and electric powertrains capture premium positioning. Three-tier pricing structure across premium cold-chain equipment, standard dry-freight platforms, and economy short-term rentals reflects certification grade and after-sales bundling intensity. Pricing pressure stems from unproven depreciation curves for battery-electric trucks compressing lessor returns. Small Polish and Romanian freight operators exhibit highest price sensitivity, while Dutch pharmaceutical distributors prioritize GDP compliance over rate negotiation.
Supply Chain Analysis
EU Green Deal local-content requirements and REACH chemical compliance are reshaping sourcing patterns for vehicle materials and battery components. Manufacturing concentration centers on Germany, Poland, and the Netherlands for final assembly, with critical dependence on Asian-sourced semiconductors, lithium-ion cells, and rare earth magnets. Single-source vulnerability in ECU and sensor supply creates fleet delivery risk for European lessors expanding electric portfolios. Distribution runs through OEM-captive rental divisions and pan-European lessor networks with regional depot density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Medium & Heavy-Duty Truck Rental Market sits in a technology-transition phase as battery-electric powertrains displace Euro VI diesel platforms across fleet procurement decisions.
For Market Incumbents: Deepen vertical integration into high-voltage servicing capabilities to offset technician certification gaps threatening electric fleet uptime guarantees. Lock in long-term battery supply agreements with cell manufacturers before capacity constraints tighten credit terms for fleet expansion. The residual value uncertainty for alternative-fuel trucks demands accelerated portfolio diversification into telematics-integrated subscription models. For New Entrants and Emerging Players: Telematics-first subscription platforms offer the clearest wedge for unseating legacy lessors in underpenetrated Polish and Romanian logistics corridors. Target short-term rental demand among east-west freight operators navigating volatile manufacturing supply chains. Lead with pay-as-you-go billing structures bundled with real-time tracking to differentiate from incumbent mileage-based contracts. For Investors and Strategic Acquirers: The window for entry favors fleet management specialists with proven electric vehicle deployment capabilities and dense depot networks in German and Dutch corridors. Acquisition targets should demonstrate integrated maintenance platforms and established relationships with retail consolidators seeking balance-sheet flexibility. Watch for EU Green Deal carbon pricing expansion as the inflection signal accelerating contract migration from ownership to rental structures.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Deployment Partnership | Absorbs technology transition risk for logistics operators testing zero-emission range capabilities. |
| Telematics-Platform Integration | Transforms break-fix service models into uptime-guarantee contracts shifting operational risk to lessors. |
| East-West Corridor Expansion | Captures underpenetrated rental demand along Poland-Romania manufacturing supply chains. |
| Refrigerated Capacity Specialization | Locks in premium positioning through GDP cold-chain compliance for pharmaceutical distributors. |
| High-Voltage Technician Certification Program | Closes servicing capability gaps threatening electric fleet maintenance scalability. |
Research Methodology
Trade association filings, EU regulatory databases, and OEM production disclosures formed the secondary backbone for market sizing and fleet deployment tracking. Primary interviews with fleet procurement directors, rental contract managers, and aftermarket service heads validated contract structure preferences and pricing sensitivity patterns. Bottom-up triangulation across vehicle registration data and lessor fleet disclosures was cross-checked against top-down macroeconomic freight volume indicators.
Historical trendline analysis of rental penetration rates and fleet turnover patterns informed the projection framework across the analysis window. Segmentation modeling incorporated vehicle type, service duration, end-use vertical, and pricing model dimensions with propulsion architecture as an industry-specific overlay. CAGRs were derived from regression analysis of fleet expansion trajectories and regulatory compliance cost curves, with specific weighting for Euro VI enforcement timelines and EU Green Deal procurement mandates.
Several conditions sit outside the modeled scope, including abrupt semiconductor supply disruptions, unilateral national low-emission zone rule changes, and battery raw material price spikes beyond historical volatility bands. Forecasts reflect documented assumptions around electrification technology maturation and carbon pricing implementation schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Garbage Collection Trucks Market