
 China Full-Truck-Load (FTL) Market | 2026-2036
China Full-Truck-Load (FTL) Market Size, Share, and Industry Trends Forecast 2026-2036
China Full-Truck-Load (FTL) Market Insights
Buyer concentration among e-commerce platforms is broadening as JD Logistics and Alibaba-affiliated merchants build captive trucking networks. SF Express leverages its integrated air-ground infrastructure to secure premium express-lane contracts. Deppon Logistics anchors heavy-freight corridors between coastal manufacturing zones and inland distribution centers. Full Truck Alliance operates the dominant digital freight-matching platform, displacing traditional broker intermediaries.
Full-Truck-Load denotes road freight transport where a single shipper contracts an entire truck capacity for direct point-to-point delivery, typically requiring minimum loads of three to fifteen tons depending on vehicle class and lane distance. Dry freight commands the largest volume pool across China's highway network, while refrigerated transport captures expanding margin pools as cold-chain food safety standards tighten. Box trucks dominate urban last-mile insertion, whereas flatbed trucks handle steel and machinery flows from Hebei and Jiangsu mills.
MIIT enforces NEV penetration mandates for urban logistics fleets, compelling operators to electrify medium-duty routes. SAMR monitors platform-economy pricing under anti-monopoly guidelines, constraining algorithmic rate coordination by digital brokers. GB standards for commercial vehicle emissions tighten periodically, forcing engine upgrades and retirement of legacy diesel tractors. Stakeholders must weigh electrification capex against fuel savings while monitoring how platform regulation reshapes broker economics.
Market Dynamics
MIIT's NEV penetration mandates for urban logistics fleets are compressing diesel tractor economics while redistributing capital toward battery-swapping infrastructure and charging networks.
Growth Catalysts
- E-commerce captive fleet expansion:Platform merchants under JD Logistics and Alibaba are internalizing truck capacity to secure lane reliability during peak consumption windows.
- Dual carbon goals:Provincial governments in Jiangsu and Zhejiang are channeling subsidies toward electric heavy-duty tractors operating Yangtze River Delta manufacturing corridors.
- Digital freight-matching platforms:Algorithmic load consolidation is collapsing information asymmetries between shippers and owner-operators, accelerating spot market liquidity.
Market Restraints
- Battery cost volatility:Lithium carbonate price swings are distorting total-cost-of-ownership calculations for fleet electrification capex cycles.
- Charging infrastructure gaps:Highway corridor coverage remains sparse outside coastal provinces, constraining electric tractor deployment on long-haul lanes exceeding 500 kilometers.
- SAMR platform pricing oversight:Anti-monopoly guidelines on algorithmic rate coordination are limiting margin extraction by digital freight brokers.
Strategic Opportunities
- Inland cold-chain corridors:Sichuan and Shaanxi provinces show underpenetrated refrigerated transport density relative to coastal benchmarks.
- Battery-as-a-service models:Swappable battery leasing is emerging as a capital-light pathway for mid-size operators to access electric tractors without full asset ownership.
- GB standards tightening:Periodic emissions upgrades are accelerating retirement of legacy diesel fleets, creating replacement demand windows.
Industry Challenges
- Driver shortage escalation:Long-haul operator demographics are aging while younger cohorts avoid cab-over lifestyle tradeoffs, compressing available labor pools.
- Intermodal integration friction:Rail-water-road handoff protocols lack standardized data exchange, creating cargo visibility gaps at inland port terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Full-Truck-Load (FTL) Market |
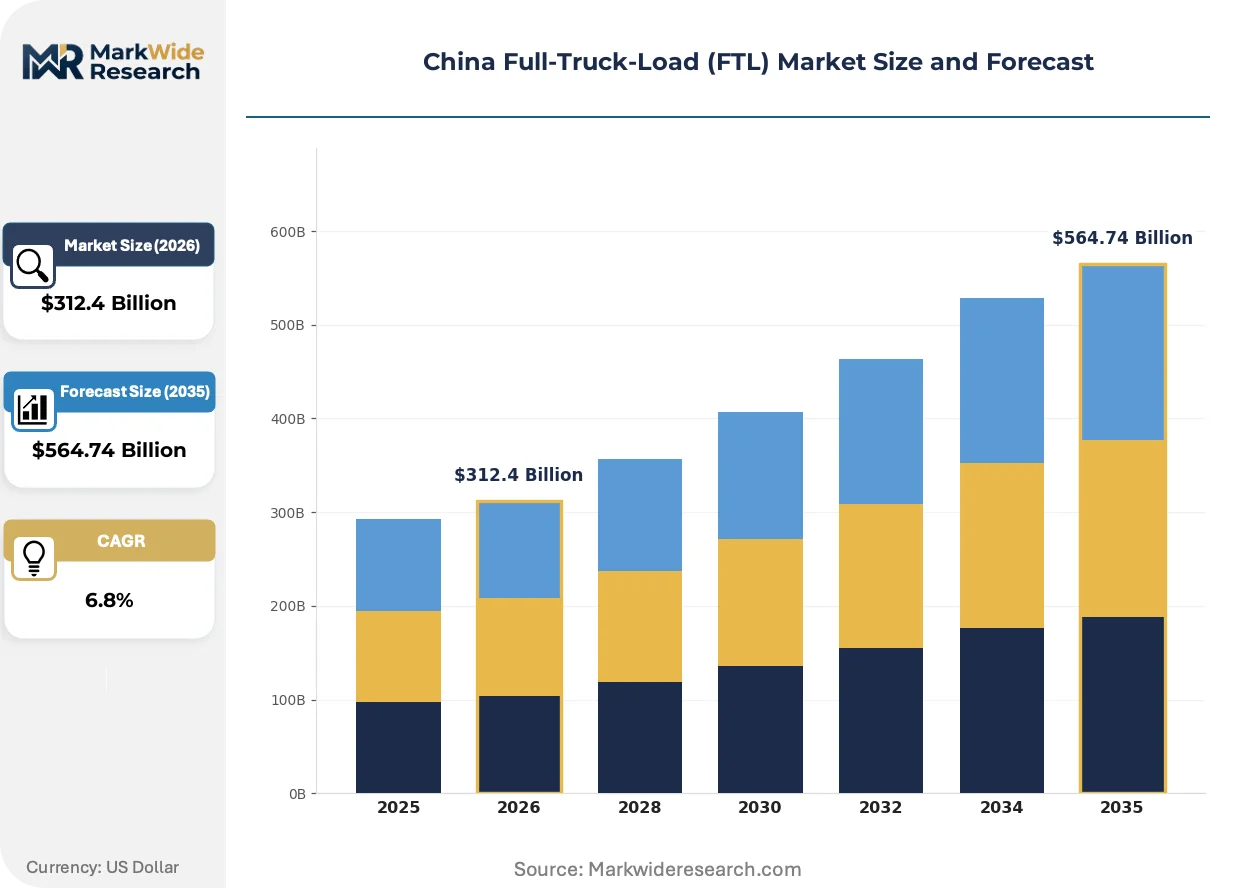
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dry Freight, Refrigerated Transport, Hazardous Goods, Expedited Shipping Vehicle Type: Box Trucks, Flatbed Trucks, Tanker Trucks, Dump Trucks End User: Manufacturing, Retail, E-Commerce, Construction Pricing Model: Hourly Rate, Distance-Based, Flat Fee, Contractual Rates |
| Companies Covered | Deppon Logistics, SF Express, SINOTRANS, JD Logistics, DHL Group, CMA CGM Group, Changan Minsheng APLL Logistics, Shanghai Yunda Freight, Full Truck Alliance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Full-Truck-Load (FTL) Market Trends and Innovations
Telematics penetration and battery chemistry advances are converging to reshape fleet economics, with regulatory pressure accelerating technology substitution timelines.
Cell-to-pack battery architectures are modularizing tractor chassis design, allowing manufacturers to standardize platforms across multiple vehicle classes. Logistics operators in Guangdong and Jiangsu are piloting these configurations for rapid battery swap compatibility. The approach is modularizing aftermarket service networks by reducing proprietary component dependencies.
GB standards for commercial vehicle emissions are tightening inspection protocols for nitrogen oxide and particulate matter, forcing engine control unit recalibrations or premature asset retirement. Heavy-freight corridors between Hebei steel mills and Jiangsu manufacturing zones face the steepest compliance costs. Deppon Logistics and similar operators are responding by front-loading electric tractor procurement in affected lanes.
Shippers are consolidating procurement through platform-direct contracts, bypassing traditional broker intermediaries that historically managed lane matching. Full Truck Alliance's dominance in digital freight-matching is compressing commission structures for legacy brokerages. This channel disintermediation is most visible in Yangtze River Delta manufacturing clusters where e-commerce volume concentration enables direct shipper-carrier relationships.
China Full-Truck-Load (FTL) Market Segmentation
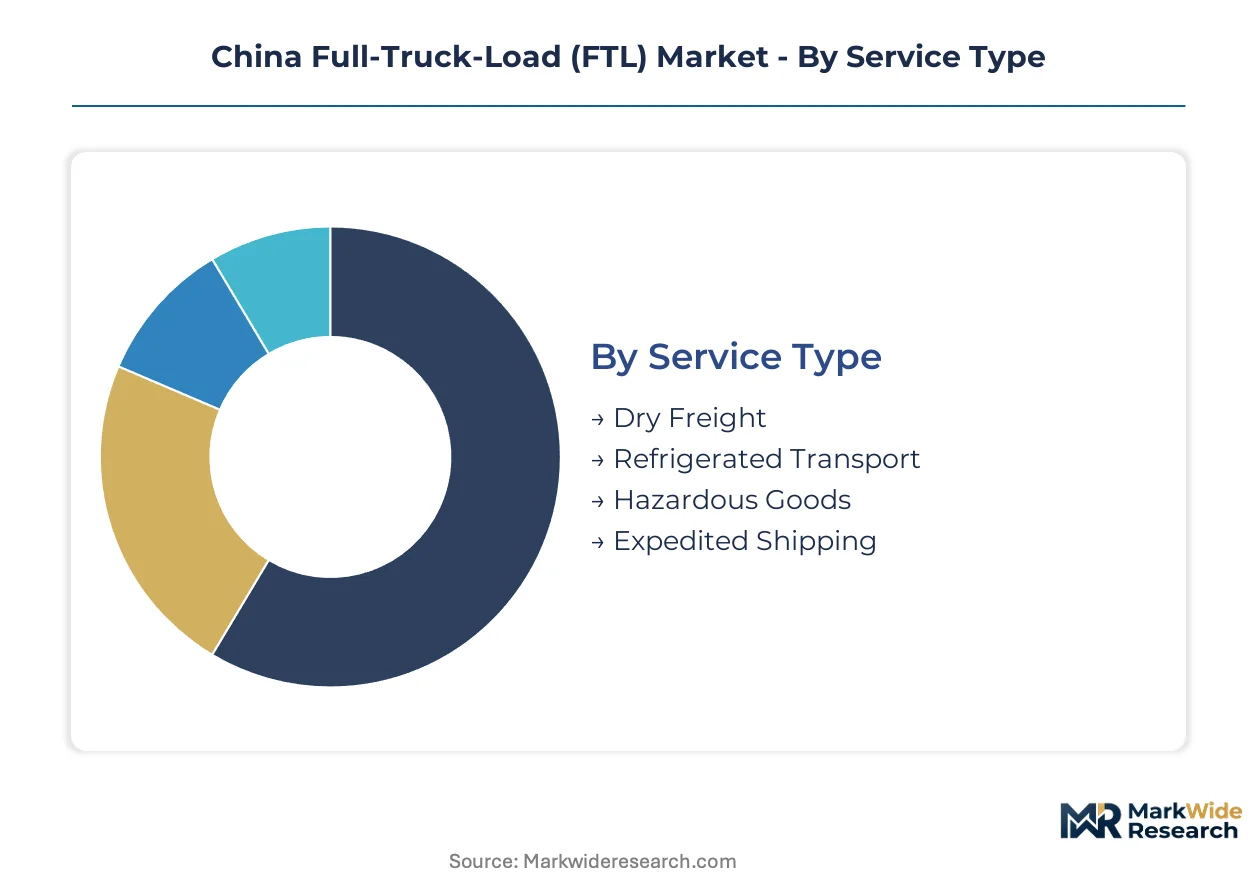
FTL segmentation reveals how capital deployment, regulatory exposure, and customer concentration vary across service tiers and asset classes. Fleet operators and platform investors allocate resources differently depending on which segment combinations they target.
Service Type:
Capital intensity peaks in specialized temperature-controlled infrastructure, while commodity dry freight runs on thinner asset margins.
- Dry Freight:Standard palletized and bulk cargo moves through unconditioned van trailers with minimal equipment specialization. Manufacturing clusters in Guangdong and Jiangsu generate the heaviest volume flows, though rate compression is severe on backhaul lanes.
- Refrigerated Transport:Insulated trailers with integrated refrigeration units carry frozen and fresh goods under strict temperature protocols. Cold-chain food safety enforcement by SAMR is tightening compliance costs for operators serving JD Logistics and supermarket distribution centers.
- Hazardous Goods:Tanker and specialized container fleets transport flammable liquids and chemicals under MEE environmental permits.
- Expedited Shipping:Premium time-definite services command rate multiples through guaranteed delivery windows.
Most installed capacity flows through Dry Freight. Expansion is steepest in Refrigerated Transport.
Vehicle Type:
Platform economics favor standardized box configurations, while specialized chassis serve narrow verticals with higher margin but lower utilization.
- Box Trucks:Enclosed van bodies protect general cargo from weather and theft during urban and intercity hauls. E-commerce last-mile insertion in Shanghai and Hangzhou depends on medium-duty box configurations that MIIT is pushing toward NEV powertrains.
- Flatbed Trucks:Open decks accommodate oversized machinery, steel coils, and construction materials with flexible loading geometry. Hebei steel mills and Jiangsu equipment manufacturers dominate demand, though securing return loads challenges asset productivity.
- Tanker Trucks:Cylindrical vessels haul liquid chemicals, fuels, and food-grade products with sealed containment systems.
- Dump Trucks:Hydraulically tilting beds discharge loose aggregates and construction debris at destination.
Box Trucks carry the highest fleet penetration. Flatbed Trucks face the tightest supply constraints on coastal manufacturing corridors.
End User:
Customer concentration and contract duration vary sharply across verticals, with e-commerce platforms rewriting procurement norms.
- E-Commerce:Platform merchants under Alibaba and JD Logistics internalize dedicated fleet capacity to secure peak-season reliability. Volume spikes during Singles Day and Mid-Autumn Festival windows strain spot market liquidity.
- Manufacturing:Just-in-time component flows and finished goods distribution anchor recurring lane contracts. Automotive and electronics factories in the Yangtze River Delta require precise scheduling coordination.
- Retail:Department store and supermarket chains run scheduled replenishment programs with predictable frequency.
- Construction:Project-based material deliveries follow irregular patterns tied to infrastructure spending cycles.
E-Commerce is capturing procurement volume fastest. Manufacturing retains the longest average contract tenures.
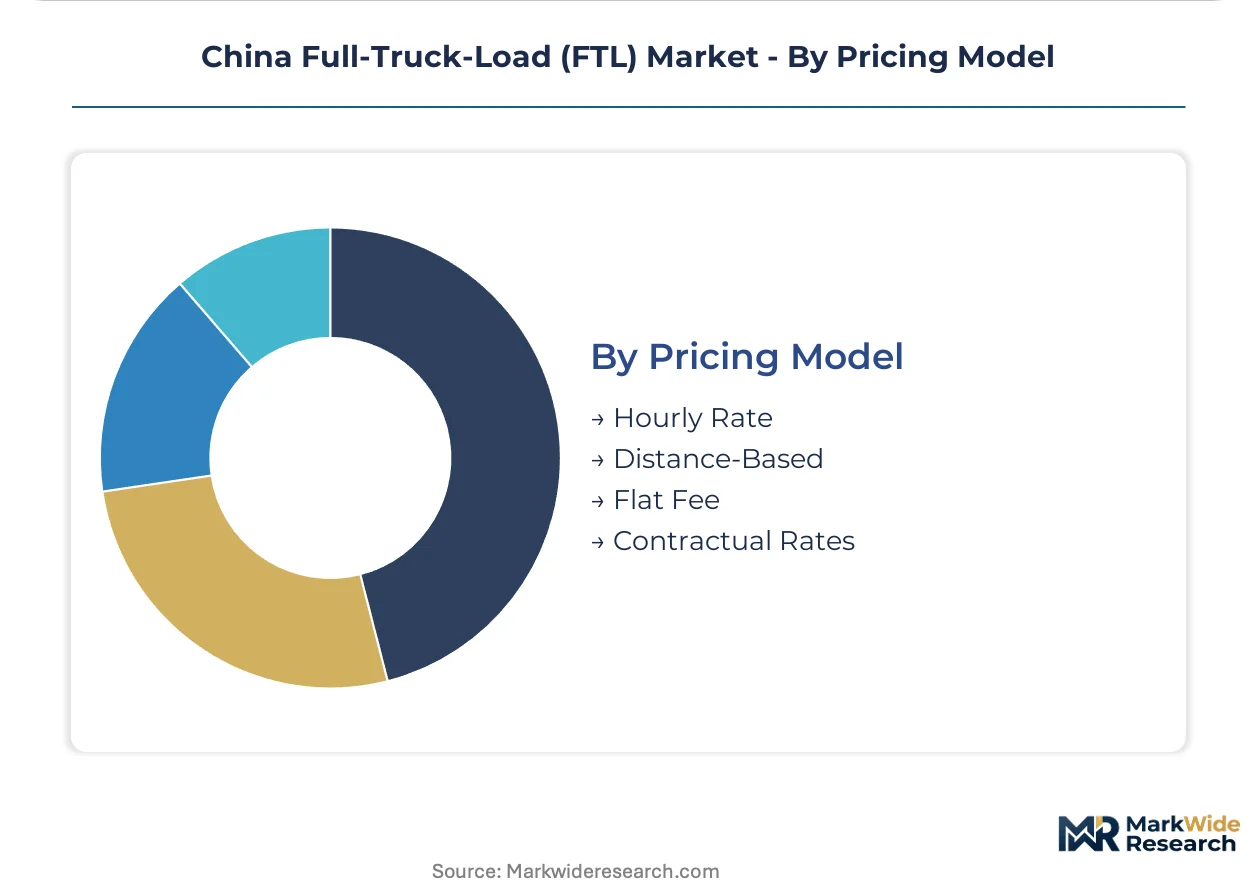
Pricing Model:
Contract structures determine working capital intensity and exposure to spot market volatility.
- Contractual Rates:Multi-month or annual agreements fix per-kilometer or per-ton pricing, insulating shippers from spot volatility. Large manufacturing accounts in Jiangsu prefer this structure for core lanes.
- Distance-Based:Tariffs scale linearly with haul length, common in interprovincial lanes where fuel and toll costs correlate with mileage.
- Flat Fee:All-inclusive pricing for defined origin-destination pairs simplifies budgeting for irregular shippers.
- Hourly Rate:Time-based billing applies to urban distribution with multiple stops or loading delays.
Contractual Rates lock in the largest revenue share. Distance-Based pricing is gaining adoption on digital freight platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Driver pools concentrate along coastal manufacturing belts where freight density supports viable owner-operator economics. Provincial subsidy regimes and MIIT electrification mandates are redistributing fleet investment across China's interior corridors.
Yangtze River Delta
E-commerce fulfillment centers and automotive component factories generate the heaviest FTL volume flows. Jiangsu and Zhejiang provincial governments channel subsidies toward electric heavy-duty tractors under dual carbon implementation timelines. Shanghai's port-centric logistics clusters anchor dedicated fleet contracts for container drayage and last-mile distribution.
Pearl River Delta
Electronics manufacturing in Shenzhen and Dongguan sustains high-frequency just-in-time component movements. Guangdong's pilot programs for cell-to-pack battery architectures are modularizing tractor chassis design for rapid swap compatibility. The region's dense charging infrastructure supports higher NEV penetration rates than northern provinces.
Beijing-Tianjin-Hebei
Steel and machinery flows from Hebei mills dominate heavy-freight demand on flatbed configurations. GB standards for commercial vehicle emissions enforce steep compliance costs through nitrogen oxide inspection protocols. Tianjin's port terminals face intermodal integration friction where rail-water-road handoffs lack standardized data exchange.
Sichuan-Chongqing
Inland cold-chain corridors show underpenetrated refrigerated transport density relative to coastal benchmarks. Western China development programs are extending highway connectivity to reduce reliance on eastern transshipment. Chengdu's automotive and electronics factories are pulling dedicated contract capacity away from spot market dependency.
Shandong Peninsula
Chemical and petrochemical clusters generate hazardous goods transport demand under MEE environmental permit requirements. Qingdao's port infrastructure supports multimodal linkages to Korean and Japanese markets. The province's heavy-industry base maintains longer average contract tenures than e-commerce-driven regions.
China Full-Truck-Load (FTL) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across China's FTL market structure. Platform operators with integrated logistics arms face asset-heavy trucking companies and digital freight-matching intermediaries. Three archetypes dominate: captive e-commerce fleets, independent asset operators, and algorithmic brokerage platforms. Competitive moves center on electrification capex cycles and strategic partnerships for battery-swapping infrastructure.
Within the captive fleet tier, JD Logistics and SF Express exemplify vertical integration strategies that internalize truck capacity for lane reliability. Among asset-light intermediaries, Full Truck Alliance occupies a position as the dominant digital freight-matching platform, displacing traditional broker economics through algorithmic load consolidation. Deppon Logistics anchors the heavy-freight specialist archetype, serving manufacturing corridors with dedicated contract structures.
| Leading Market Players |
|---|
| Deppon Logistics |
| SF Express |
| SINOTRANS |
| JD Logistics |
| DHL Group |
| CMA CGM Group |
| Changan Minsheng APLL Logistics |
| Shanghai Yunda Freight |
| Full Truck Alliance |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply access and premium-tier pricing power for fleet operators deploying NEV-compliant tractors on Yangtze River Delta corridors. Shippers with electrified dedicated fleets command contract rate premiums while diesel-dependent carriers face margin compression on carbon-intensive lanes.
Pricing Analysis
Bundled service packages encompassing fleet provision, real-time tracking, and guaranteed delivery windows separate from unbundled spot-market transactions on digital freight platforms. Three-tier pricing structure across premium express-lane contracts, standard scheduled lanes, and economy backhaul tiers reflects service reliability guarantees and carbon compliance status. Cost compression in standard dry-freight lanes is intensifying because algorithmic load-matching by Full Truck Alliance collapses information rents previously captured by traditional brokers. E-commerce platforms exhibit the lowest price sensitivity due to peak-season reliability premiums, while commodity manufacturers in Hebei steel corridors show acute sensitivity to per-kilometer rate fluctuations.
Supply Chain Analysis
Domestic-content mandates under MIIT NEV penetration rules are reshaping sourcing toward Chinese battery cell manufacturers and domestic tractor chassis producers. Tractor assembly draws from lithium carbonate processors in Jiangxi, cell-to-pack architecture suppliers in Guangdong, and electric drivetrain specialists in Shanghai. Single-source vulnerability concentrates in battery-grade lithium refining capacity where price volatility transmits directly to fleet procurement cycles. Distribution runs through manufacturer-direct sales to large fleet operators, with aftermarket parts flowing via provincial service networks anchored in manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's FTL market compounds steadily as e-commerce captive fleet expansion locks in recurring dedicated capacity demand across consumption corridors.
For Market Incumbents: Extend electrified fleet coverage along subsidized Yangtze River Delta corridors before subsidy windows narrow, while consolidating maintenance network density to defend against battery-as-a-service entrants. Backward integration into charging infrastructure at owned distribution centers reduces dependency on sparse highway charging networks that constrain electric tractor deployment beyond 500-kilometer lanes. For New Entrants and Emerging Players: Enter via inland cold-chain corridors in Sichuan and Shaanxi where refrigerated transport density lags coastal benchmarks and SAMR food safety enforcement is tightening compliance requirements. Battery-swapping partnerships with cell-to-pack architecture pilots in Guangdong offer a capital-light entry angle without full tractor asset ownership. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size regional operators with dense lane coverage in Jiangsu and Zhejiang but limited electrification progress. The long-term viability window favors platforms with algorithmic freight-matching scale or heavy-freight specialists with manufacturing contract tenures exceeding e-commerce average durations. Watch MIIT subsidy renewal announcements as the inflection signal for accelerated NEV fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Deployment | Swappable leasing models reduce capital barriers for mid-size operators accessing MIIT-compliant electric tractors. |
| Cold-Chain Corridor Expansion | Inland refrigerated density gaps in Sichuan create first-mover advantages under tightening SAMR food safety protocols. |
| Digital Platform Integration | Direct shipper-carrier contracts on Full Truck Alliance disintermediate legacy broker economics in Yangtze Delta clusters. |
| Charging Infrastructure Partnership | Highway corridor coverage gaps outside coastal provinces constrain long-haul electric deployment without collaborative buildout. |
| Heavy-Freight Electrification | GB standards enforcement on Hebei steel corridors accelerates diesel tractor retirement and replacement demand windows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with fleet operations directors, logistics procurement managers at e-commerce platforms, charging infrastructure developers, and SAMR regulatory specialists with secondary validation. Customs trade data, MIIT NEV penetration filings, provincial subsidy disbursement records, and Full Truck Alliance platform transaction disclosures anchored the quantitative layer. Bottom-up fleet size estimates triangulated against top-down freight volume flows from manufacturing cluster output data.
Segment-weighting approaches distributed value and volume across service type tiers, vehicle class configurations, end-user verticals, and pricing model structures. The projection horizon incorporated electrification capex cycles, dual carbon policy implementation trajectories, and e-commerce fulfillment network expansion patterns. CAGRs derived from slope-consistency checks against historical freight volume elasticity to industrial output and consumption index movements.
Inputs from provincial transportation bureaus and platform operator disclosures were available through the study window; gaps in real-time spot-rate transaction transparency introduce uncertainty bands around short-term pricing trajectory assumptions. Forecasts reflect documented assumptions regarding subsidy continuity, battery cost curves, and driver demographic trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Tipper Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market