
 Digger Derrick Truck Market | 2026-2036
Digger Derrick Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Digger Derrick Truck Market Insights
North American manufacturing capacity is rewriting competitive dynamics for heavy aerial equipment. Altec Industries leverages vertical integration across boom fabrication and chassis mounting to sustain delivery advantages. Terex Corp anchors its position through specialized utility-focused distribution networks. Elliott Equipment Company competes on custom engineering depth for transmission-line contractors.
A digger derrick truck integrates a rotating auger drive with a telescopic or articulating boom mounted on a commercial chassis, typically delivering digging depths of ten to fifteen feet and lifting capacities exceeding twenty thousand pounds for utility pole setting and material handling. The telescopic boom segment dominates revenue due to its simpler maintenance profile and broader rental fleet compatibility, while articulating boom configurations capture premium positioning in congested urban zones where maneuverability constraints limit straight-boom deployment. Electric utilities represent the most concentrated end user industry, though telecommunications carriers are expanding orders as fiber-optic backhaul builds accelerate pole-loading requirements.
FAA regulations governing aerial work near airport approach zones, OSHA standards for crane operator certification, and EPA Phase 2 greenhouse gas emissions rules for heavy-duty engines collectively elevate compliance costs and equipment complexity. State-level public utility commissions in Texas, California, and Florida are incorporating storm-hardening mandates that specify digger derrick payload and reach minimums for mutual aid fleets. Stakeholders must monitor how pending federal infrastructure disbursement timelines affect municipal agency procurement rhythms and rental-versus-purchase decisions.
Market Dynamics
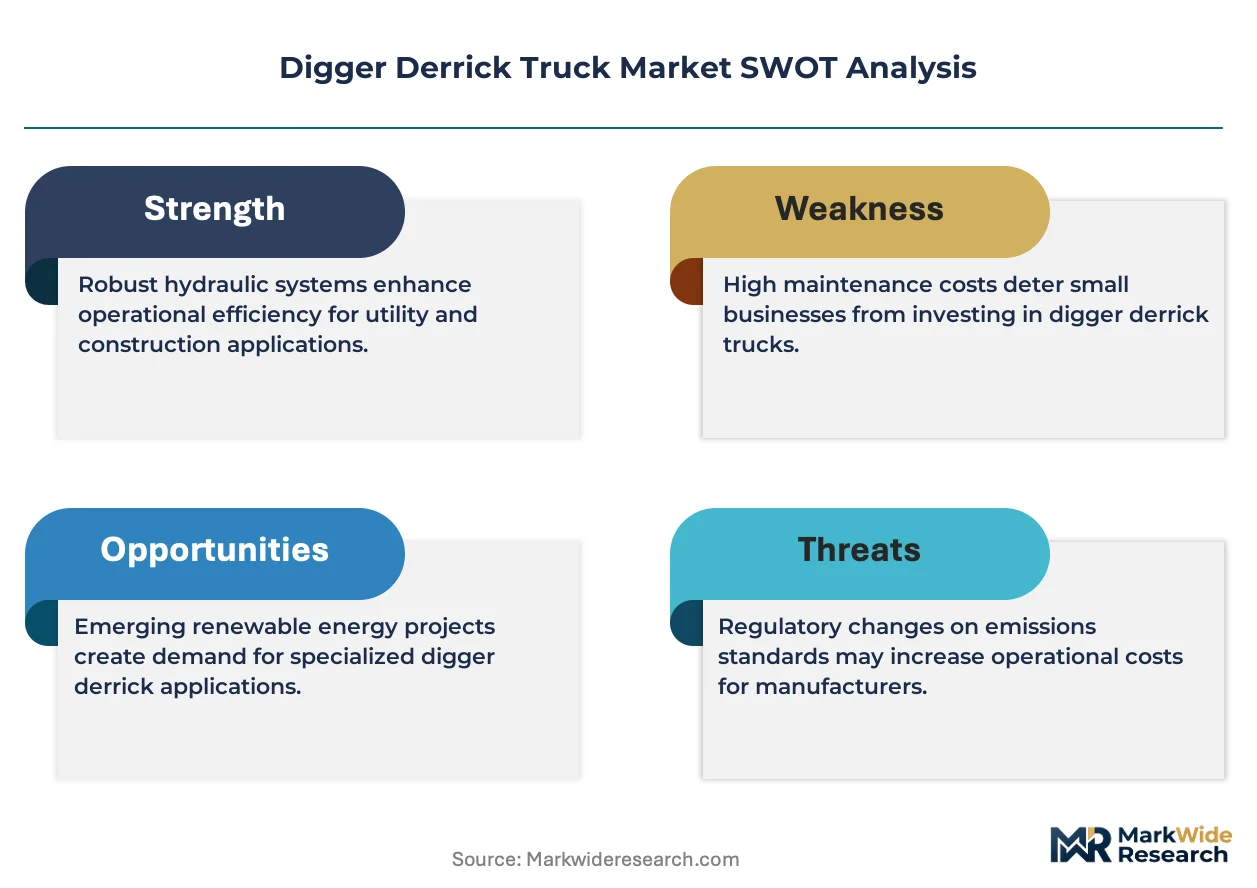
EPA Phase 2 greenhouse gas emissions rules for heavy-duty engines are forcing simultaneous redesigns of chassis powertrains and hydraulic systems, compressing development cycles for equipment manufacturers serving electric utility fleets.
Growth Catalysts
- Storm-hardening mandates:State public utility commissions in Texas, California, and Florida specify digger derrick payload minimums for mutual aid fleets, accelerating replacement schedules.
- Fiber-optic backhaul expansion:Telecommunications carriers are expanding pole-loading orders as 5G and rural broadband builds intensify aerial infrastructure deployment.
- FAA approach zone protocols:Height-restricted airport corridors create demand for compact articulating boom configurations with sub-50-foot stowed profiles.
Market Restraints
- Steel and aluminum input volatility:Boom fabrication costs fluctuate with commodity indexes, squeezing margin visibility for chassis-integrated equipment.
- Specialized hydraulic component concentration:Precision valve and pump sourcing concentrates among German and Japanese suppliers, exposing lead time risks.
- OSHA crane operator certification:Compliance timelines extend delivery windows by 30-90 days for rental fleet operators lacking in-house certified personnel.
Strategic Opportunities
- Underpenetrated Canadian utility sector:Provincial hydroelectric authorities lag US peers in fleet modernization, creating first-mover positioning for compliant equipment.
- Electrified chassis convergence:Battery-electric medium-duty platforms from commercial truck OEMs enable zero-emission digger derrick variants for urban utility contracts.
- Rental channel expansion:Independent equipment rental networks are adding transmission-grade digger derricks to capture storm-response spot demand.
Industry Challenges
- Certified hydraulic technician scarcity:Boom diagnostics and repair require specialized training that vocational programs have not scaled to match equipment complexity.
- Legacy telematics integration:Municipal fleets operate mixed-vintage equipment with incompatible data protocols, complicating unified fleet management software deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digger Derrick Truck Market |
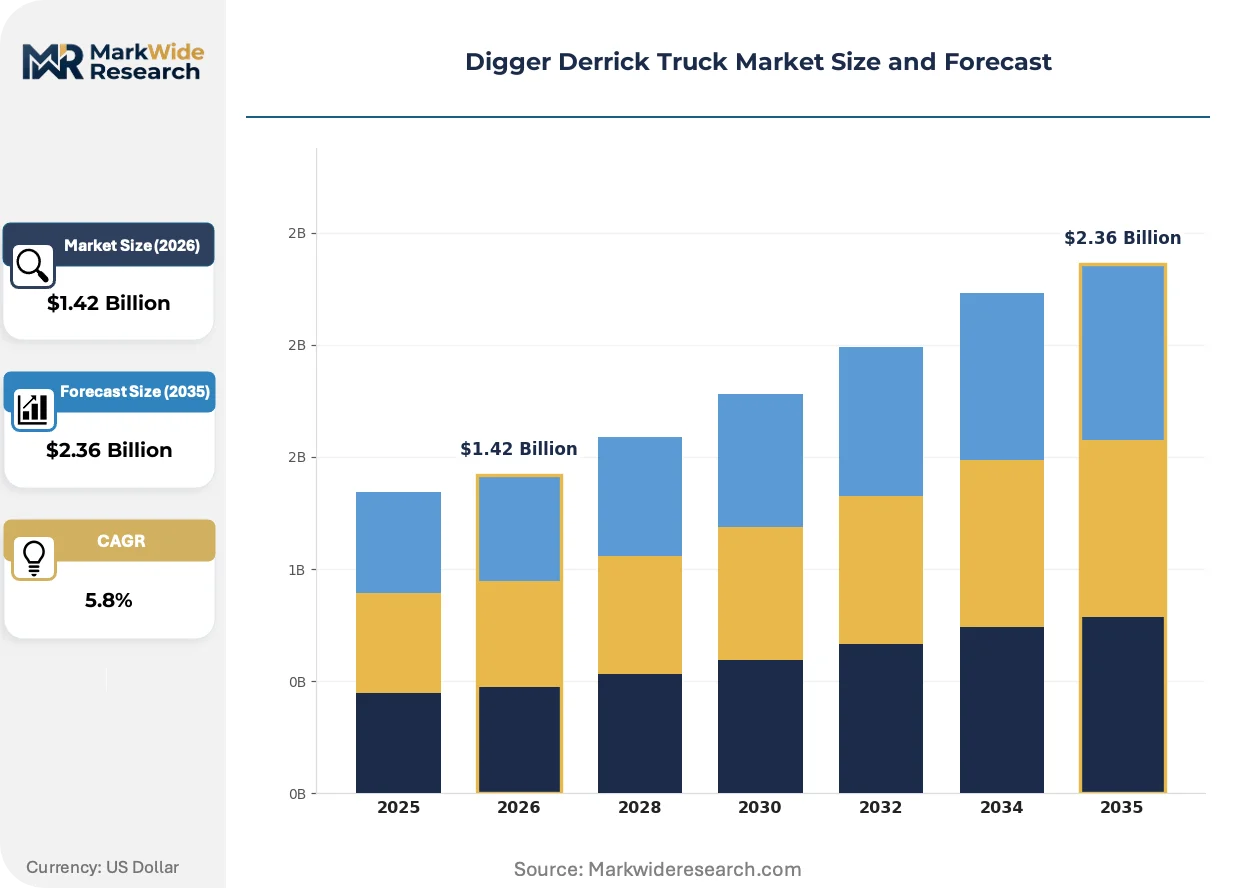
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic Boom, Articulating Boom, Hydraulic Lift, Cable Hoist, Pneumatic Crane Application: Utility Maintenance, Construction, Telecommunications, Forestry Operations, Heavy Lifting End User Industry: Electric Utilities, Oil & Gas Extractors, Infrastructure Contractors, Forestry Services, Municipal Agencies Deployment: On-Road, Off-Road, Remote Sites, Urban Zones, Rural Locations |
| Companies Covered | Elliott Equipment Company, Derrick Corporation, Altec Industries, Hiab, Drake-Scruggs Equipment, Versalift, Rigs, Derricks Etc., LLC, National Crane, Terex Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digger Derrick Truck Market Trends and Innovations
Active reshaping in this market centers on powertrain electrification, regulatory compliance automation, and procurement model rationalization as utility capital planning tightens.
Telematics-enabled predictive maintenance is collapsing the traditional reactive service model for boom and auger systems. Electric utilities with centralized fleet operations are adopting these platforms fastest, compressing unplanned downtime intervals from weeks to hours and shifting aftermarket revenue from parts replacement to subscription diagnostics.
OSHA's updated crane operator certification requirements are mandating simulator-based training modules before field qualification. Equipment manufacturers must now integrate training documentation into delivery packages, with rental fleet operators absorbing the steepest compliance cost increases as they rotate operators across multiple machine types.
Utility procurement departments are consolidating vendor relationships and demanding lifecycle cost guarantees rather than upfront capital quotes. This behavior concentrates purchase authority at integrated manufacturers with captive service networks, marginalizing smaller fabricators in the Midwest utility corridor where municipal cooperative buying groups dominate.
Digger Derrick Truck Market Segmentation
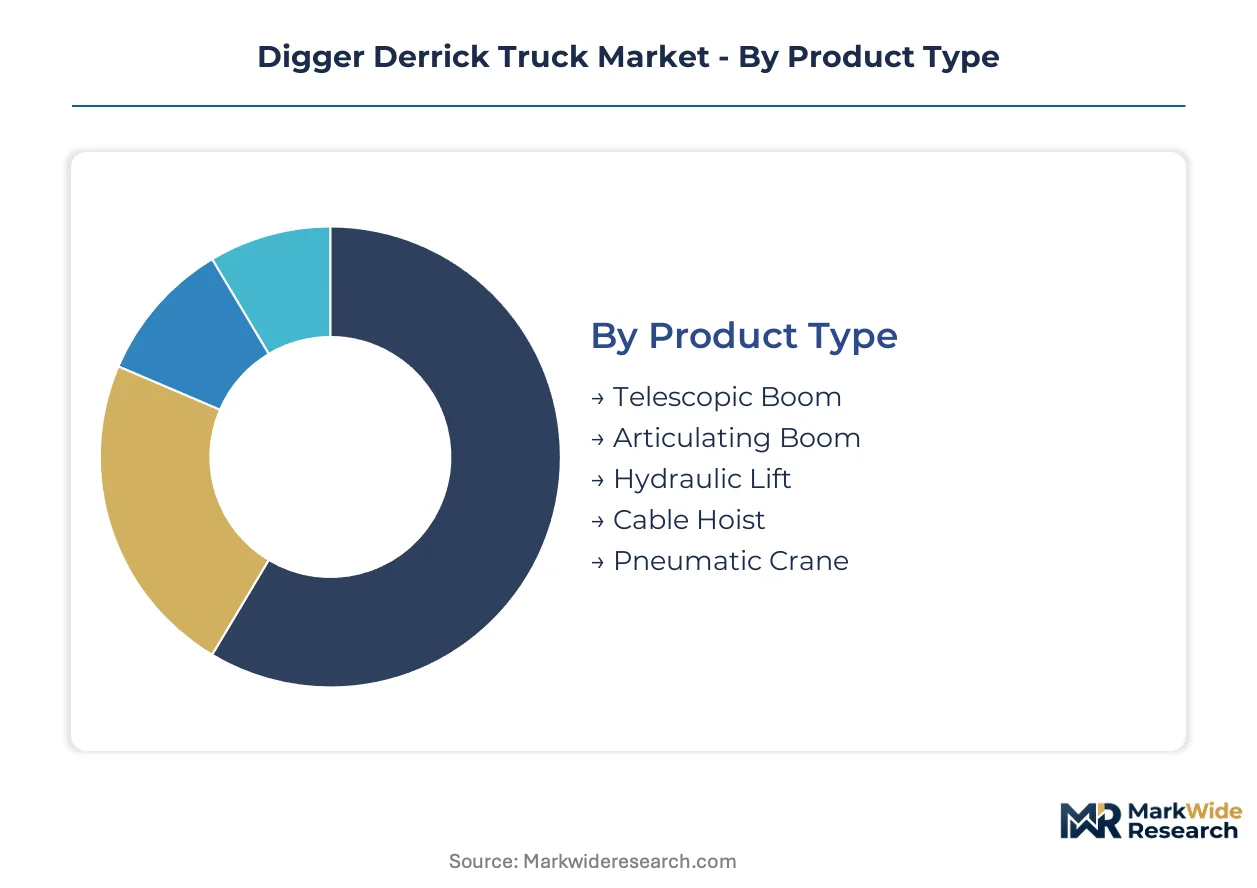
Digger derrick truck segmentation reflects divergent equipment specifications across utility infrastructure, construction, and resource extraction workflows. Procurement patterns vary sharply between fleet operators seeking standardized rental compatibility and specialized contractors demanding custom boom configurations.
Product Type:
Mature boom architectures dominate rental fleet procurement, while emerging configurations target congested urban corridors and height-restricted airspace.
- Telescopic Boom:Straight-section aluminum or steel booms extend through nested hydraulic cylinders, delivering simpler field maintenance and broader parts interchangeability. Electric utilities across the US utility corridor from Texas through the Midwest concentrate orders here, driven by fleet standardization mandates and mutual aid interoperability requirements.
- Articulating Boom:Knuckle-jointed designs fold into compact stowed profiles below fifty feet, enabling deployment near airport approach zones governed by FAA protocols. Telecommunications carriers in dense urban markets prioritize these units for fiber-optic backhaul builds where street width and overhead clearance constrain straight-boom maneuverability.
- Hydraulic Lift:Scissor or vertical-lift mechanisms provide stable elevated work platforms for transformer maintenance and substation construction.
- Cable Hoist:Winch-based lifting systems serve legacy pole-setting operations in rural cooperative territories with lower precision requirements.
- Pneumatic Crane:Compressed-air actuation suits explosive atmosphere environments in oil and gas extraction fields where spark ignition risks prohibit conventional hydraulics.
Telescopic boom configurations handle the majority of throughput; articulating boom variants are expanding most quickly on share.
Application:
Cost tier stratification separates capital-intensive transmission work from routine maintenance cycles with shorter equipment utilization windows.
- Utility Maintenance:Scheduled pole replacement, transformer servicing, and storm damage response constitute the core revenue base. State public utility commissions in Texas, California, and Florida specify payload minimums for mutual aid fleets, accelerating replacement schedules among electric utilities.
- Telecommunications:5G and rural broadband builds intensify aerial infrastructure deployment, with carriers expanding pole-loading orders beyond traditional utility customers. OSHA crane operator certification requirements extend delivery windows for rental fleet operators lacking in-house certified personnel.
- Construction:General building sites employ digger derricks for foundation drilling and material placement where crane mobilization costs prove prohibitive.
- Forestry Operations:Logging road maintenance and harvest equipment servicing in remote terrain demands off-road chassis configurations.
- Heavy Lifting:Transmission-line contractors deploy high-capacity units for conductor stringing and tower erection in wind farm and interstate corridor projects.
Utility maintenance absorbs the largest equipment allocation; telecommunications application demonstrates the steepest expansion trajectory.
End User Industry:
Volume concentration tracks infrastructure investment cycles, with margin profiles diverging between regulated utilities and cyclical resource extraction.
- Electric Utilities:Investor-owned utilities, municipal cooperatives, and rural electric associations operate the dominant installed base. Fleet modernization programs concentrate procurement authority at integrated manufacturers with captive service networks.
- Infrastructure Contractors:Transmission-line specialists and substation builders demand custom engineering depth for project-specific reach and payload requirements.
- Oil & Gas Extractors:Field service units in Permian Basin and Appalachian shale plays require explosion-proof configurations for wellhead maintenance.
- Forestry Services:Timber harvest operators in Pacific Northwest and Southeast regions utilize modified chassis for unimproved road access.
- Municipal Agencies:City and county public works departments face compressed capital timelines tied to federal infrastructure disbursement schedules.
Electric utilities command the dominant procurement volume; infrastructure contractors exhibit the most volatile demand spikes tied to project awards.
Deployment:
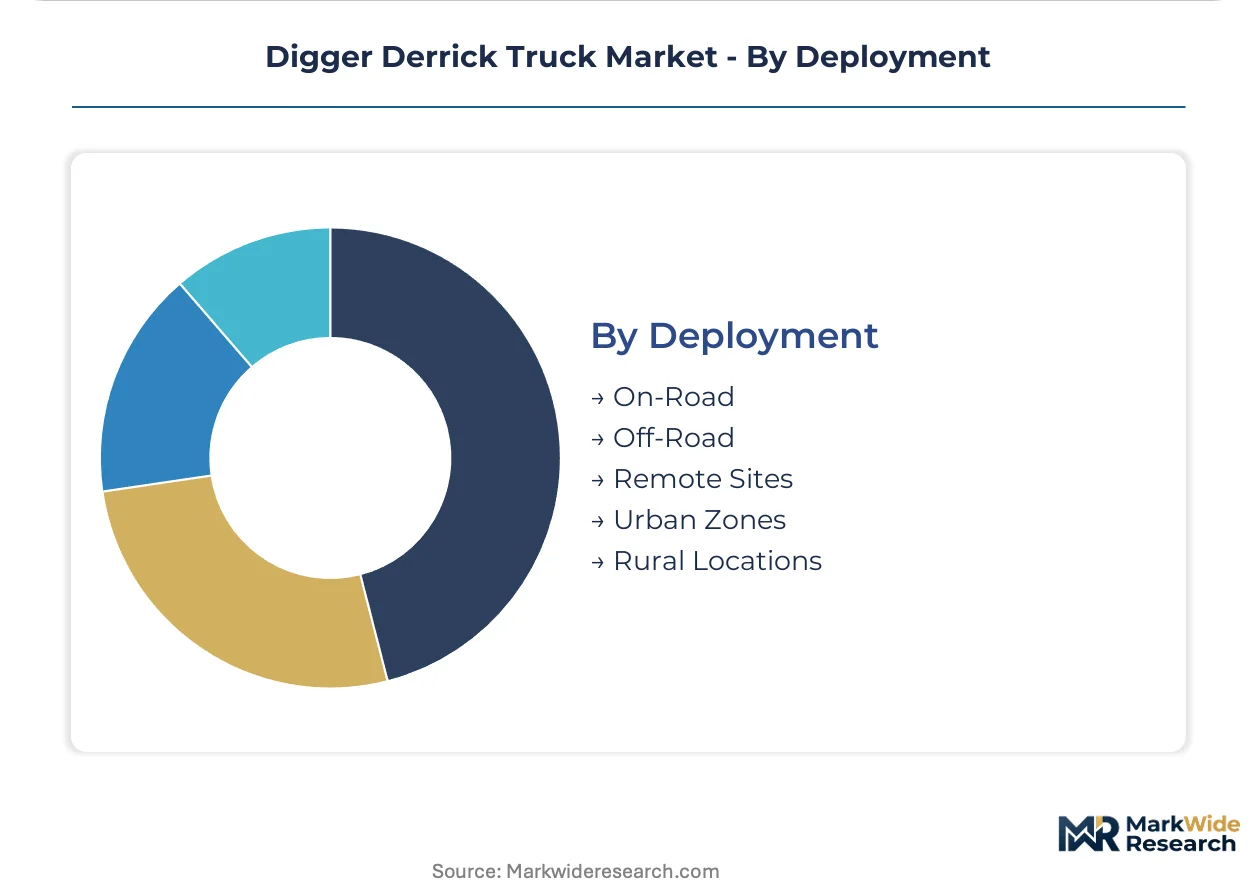
Geography dictates chassis specification, with supply chain configuration varying between highway-legal fleet rotations and site-bound specialized units.
- On-Road:Highway-legal Class 7 and 8 chassis enable rapid mutual aid dispatch across state lines. EPA Phase 2 greenhouse gas emissions rules force simultaneous powertrain and hydraulic system redesigns for this segment.
- Off-Road:Severe-duty suspensions and all-terrain tires serve remote transmission corridors and extraction fields beyond paved access.
- Urban Zones:Compact turning radii and sub-fifty-foot stowed heights navigate dense street grids and underground utility congestion.
- Rural Locations:Extended-range fuel tanks and simplified electronics address extended dispatch distances from service depots.
- Remote Sites:Self-contained power generation and satellite telematics support operations beyond cellular coverage in western transmission corridors.
On-road deployment represents the largest equipment category; urban zone specifications are gaining share fastest amid fiber-optic densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chassis fabrication and boom assembly concentrate among integrated manufacturers serving the United States utility corridor. Equipment procurement patterns diverge sharply between regulated electric utilities and municipal cooperative buying groups.
United States
Electric utilities across Texas through the Midwest drive fleet modernization with mutual aid interoperability requirements. EPA Phase 2 greenhouse gas emissions rules force simultaneous powertrain and hydraulic system redesigns for Class 7 and 8 chassis. Storm-hardening mandates from public utility commissions in Texas, California, and Florida accelerate replacement schedules in Houston and Dallas-Fort Worth metro clusters.
Canada
Provincial hydroelectric authorities lag US peers in fleet standardization, creating positioning opportunities for EPA-compliant equipment. The country's national environmental regulator maintains alignment with US emissions protocols for cross-border fleet compatibility. Ontario Hydro and BC Hydro procurement offices in Toronto and Vancouver are expanding transmission maintenance vehicle orders.
Germany
Precision hydraulic component suppliers concentrate manufacturing for global boom OEMs serving utility markets. EU machinery directives and CE marking requirements shape export specifications for equipment bound into European utility fleets. Industrial fabrication clusters around Stuttgart and Munich supply specialized valve and pump assemblies.
Japan
Specialized hydraulic component manufacturers dominate precision pump and valve sourcing for global boom fabricators. METI industrial standards and JIS certification requirements govern equipment specifications for domestic utility procurement. Manufacturing concentration in the Chubu region around Nagoya supports tier-one supplier networks.
Australia
Remote mining and transmission corridor maintenance drive demand for severe-duty off-road chassis configurations. The country's national workplace safety regulator enforces crane operator certification protocols aligned with international standards. Equipment deployment concentrates in Western Australia mining belts and Queensland rural electrification zones.
Digger Derrick Truck Market Competitive Landscape
Integrated chassis-boom fabricators and specialized hydraulic component suppliers split the market into distinct capability tiers. Three strategic archetypes dominate: vertically integrated manufacturers with captive service networks, regional fabricators serving municipal cooperatives, and precision hydraulic specialists supplying tier-one assemblies. Competitive moves center on fleet standardization contracting and mutual aid interoperability certification.
Among North American integrated manufacturers, Altec Industries and Terex Corp exemplify the full-line archetype with chassis mounting and boom fabrication capabilities. Elliott Equipment Company occupies a position within the custom engineering tier serving transmission-line contractors with specialized reach configurations. Hiab represents European hydraulic lifting technology integration into utility vehicle platforms.
| Leading Market Players |
|---|
| Elliott Equipment Company |
| Derrick Corporation |
| Altec Industries |
| Hiab |
| Drake-Scruggs Equipment |
| Versalift |
| Rigs, Derricks Etc., LLC |
| National Crane |
| Terex Corp |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum input volatility determines both pricing tier spreads and supply chain shape, compressing margin visibility for chassis-integrated equipment manufacturers while forcing dual-sourcing strategies for boom fabrication inputs.
Pricing Analysis
EPA Phase 2 greenhouse gas emissions rules dictate the pricing tier structure across the digger derrick truck market, separating EPA-compliant premium configurations from legacy powertrain economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier is intensifying because municipal cooperative buying groups concentrate procurement authority at integrated manufacturers. Rental fleet operators exhibit the highest price sensitivity due to utilization-driven depreciation schedules, while transmission-line contractors demonstrate lower sensitivity given project-specific custom engineering requirements.
Supply Chain Analysis
High-strength steel plate from Germany, Japan, and South Korea feeds boom fabrication, while precision hydraulic components concentrate among German and Japanese tier-one suppliers. Raw material dependencies center on alloy steel grades, aluminum extrusions, and specialized hydraulic valves. Single-source vulnerability in precision pump sourcing exposes lead time risks for North American chassis integrators. Distribution runs through utility-focused dealer networks and independent rental channels serving storm-response spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified hydraulic technician scarcity constrains fleet expansion timelines, creating acquisition premiums for manufacturers with captive training infrastructure and aftermarket service networks.
For Market Incumbents: Insulate market position by deepening backward integration into boom fabrication and expanding captive service technician training programs. Battery-electric chassis convergence from commercial truck OEMs threatens traditional powertrain suppliers, making EPA compliance certification investment the critical defensive lever for fleet standardization contracts. For New Entrants and Emerging Players: Pursue underpenetrated Canadian provincial hydroelectric authorities with EPA-compliant equipment offerings tailored to cross-border fleet compatibility requirements. Municipal cooperative buying groups in the Midwest utility corridor represent the most penetrable procurement channel, with rental fleet operator certification support as the differentiated go-to-market angle. For Investors and Strategic Acquirers: EPA Phase 2 enforcement timelines reshape the acquisition landscape toward integrated manufacturers with captive chassis mounting and boom fabrication capabilities. Long-term viability across the analysis window favors vertically integrated fabricators over regional specialists dependent on outsourced hydraulic assemblies. The signal to watch is federal infrastructure disbursement acceleration affecting municipal agency capital commitment pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boom Fabrication | Captive supply of high-strength steel assemblies reduces exposure to German and Japanese tier-one pricing volatility. |
| Certified Technician Training Program | OSHA crane operator compliance creates recurring revenue streams from rental fleet operators lacking in-house personnel. |
| Battery-Electric Chassis Partnership | Commercial truck OEM collaborations unlock zero-emission variants for urban utility contracts in California and Texas. |
| Mutual Aid Interoperability Certification | State public utility commission storm-hardening mandates in Florida accelerate replacement schedule capture. |
| Predictive Maintenance Platform Deployment | Telematics-enabled diagnostics shift aftermarket revenue from parts replacement to subscription services for electric utilities. |
Research Methodology
A standing panel of fleet maintenance directors, utility procurement officers, rental fleet operators, and hydraulic component procurement leads provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with equipment manufacturers and aftermarket service providers against secondary validation through EPA regulatory filings, OSHA crane operator certification databases, and state public utility commission storm-hardening mandate records. Bottom-up unit economics triangulated with top-down infrastructure investment flow analysis.
Scenario-bracketing around emissions compliance timelines and federal infrastructure disbursement pacing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include boom configuration type, end-user industry concentration, deployment geography, and chassis powertrain architecture. CAGRs derived from utility capital expenditure cycle analysis and telecommunications carrier pole-loading order trajectories. Industry-specific forecast inputs incorporated electric utility fleet modernization program announcements and fiber-optic backhaul build schedules.
Sensitivities concentrate around EPA enforcement acceleration, steel commodity index movements, and municipal capital commitment delays. Forecasts reflect documented assumptions regarding mutual aid interoperability standardization and rental channel penetration rates. Cross-checking against state public utility commission procurement database filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Garbage Collection Trucks Market