
 Global Human Liver Models Market | 2026-2036
Global Human Liver Models Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Liver Models Market Foresight
Bioprinting facilities in Germany and the Netherlands are recalibrating production lines to accommodate perfusable liver tissue architectures for pharmaceutical clients. Emulate, Inc. leverages its Organ-Chip platform to anchor relationships with top-20 drug developers seeking predictive toxicology data. Mimetas sustains competitive differentiation through its proprietary OrganoPlate microfluidic technology, which enables high-throughput 3D cell culture screening.
Human liver models comprise engineered biological systems that replicate hepatic tissue architecture, metabolic enzyme expression, and bile canalicular function for predictive in vitro testing. These constructs typically incorporate primary hepatocytes, Kupffer cells, and hepatic stellate cells within collagen or Matrigel matrices to simulate drug metabolism, detoxification pathways, and disease progression. Organ-on-a-chip systems command premium positioning due to their dynamic fluid flow capabilities and multi-organ linking potential, while spheroid formats occupy the high-volume segment for hepatotoxicity screening. Microphysiological systems represent the fastest-expanding category as regulatory agencies increasingly accept human-relevant data for investigational new drug filings.
The FDA's Modernization Act 2.0 and EMA's 3Rs initiative are reshaping preclinical validation requirements, directly expanding addressable demand for liver models that replace animal protocols. ISO 10993 biocompatibility standards and OECD Test Guideline 497 further govern material selection and validation protocols for in vitro hepatic assays. Stakeholders must monitor evolving regulatory acceptance criteria across jurisdictions to align product development roadmaps with submission-ready data packages.
Market Dynamics
Regulatory abandonment of mandatory animal testing protocols is compressing validation timelines and redirecting pharmaceutical R&D expenditure toward human-relevant in vitro systems, fundamentally restructuring preclinical service procurement patterns.
Growth Catalysts
- FDA Modernization Act 2.0:The US pharmaceutical regulator eliminated compulsory animal testing for drug approvals, redirecting sponsor budgets toward liver-on-a-chip platforms and microphysiological systems.
- EMA 3Rs initiative:The European medicines agency's replacement, reduction, refinement framework accelerates validation acceptance for hepatic organoid data in investigational new drug submissions.
- Boston-San Diego corridor concentration:Biotech clusters in these US metropolitan areas house the densest concentration of contract research organizations adopting perfusable liver tissue architectures.
Market Restraints
- Primary hepatocyte supply volatility:Donor liver tissue availability fluctuates seasonally, creating input cost instability for model manufacturers dependent on fresh human cell sourcing.
- Matrigel price concentration:Basement membrane extract pricing remains controlled by limited qualified suppliers, compressing margins for collagen-alternative matrix developers.
- Cross-jurisdictional validation friction:Divergent acceptance criteria between FDA, EMA, and PMDA submissions force redundant qualification studies, extending commercialization timelines.
Strategic Opportunities
- India CDSCO pathway expansion:The national pharmaceutical regulator's evolving biosimilar guidelines create entry points for hepatotoxicity screening services in generic drug development.
- Multi-organ linking convergence:Liver-kidney and liver-heart chip integration is opening subscription-based pharmacokinetic modeling contracts with mid-cap biotech sponsors.
- OECD Test Guideline 497 alignment:Standardized in vitro phototoxicity protocols are creating certified laboratory accreditation demand across Asia-Pacific contract research markets.
Industry Challenges
- Microfluidic engineering talent scarcity:The specialized intersection of cell biology and chip fabrication expertise commands premium compensation, constraining scale-up velocity for platform developers.
- ISO 10993 biocompatibility certification timelines:Material qualification protocols for novel hydrogel matrices extend product launch schedules by 18-24 months.
- Legacy animal study data reconciliation:Pharmaceutical sponsors struggle to bridge historical toxicology archives with human-relevant model outputs for regulatory comparability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Liver Models Market |
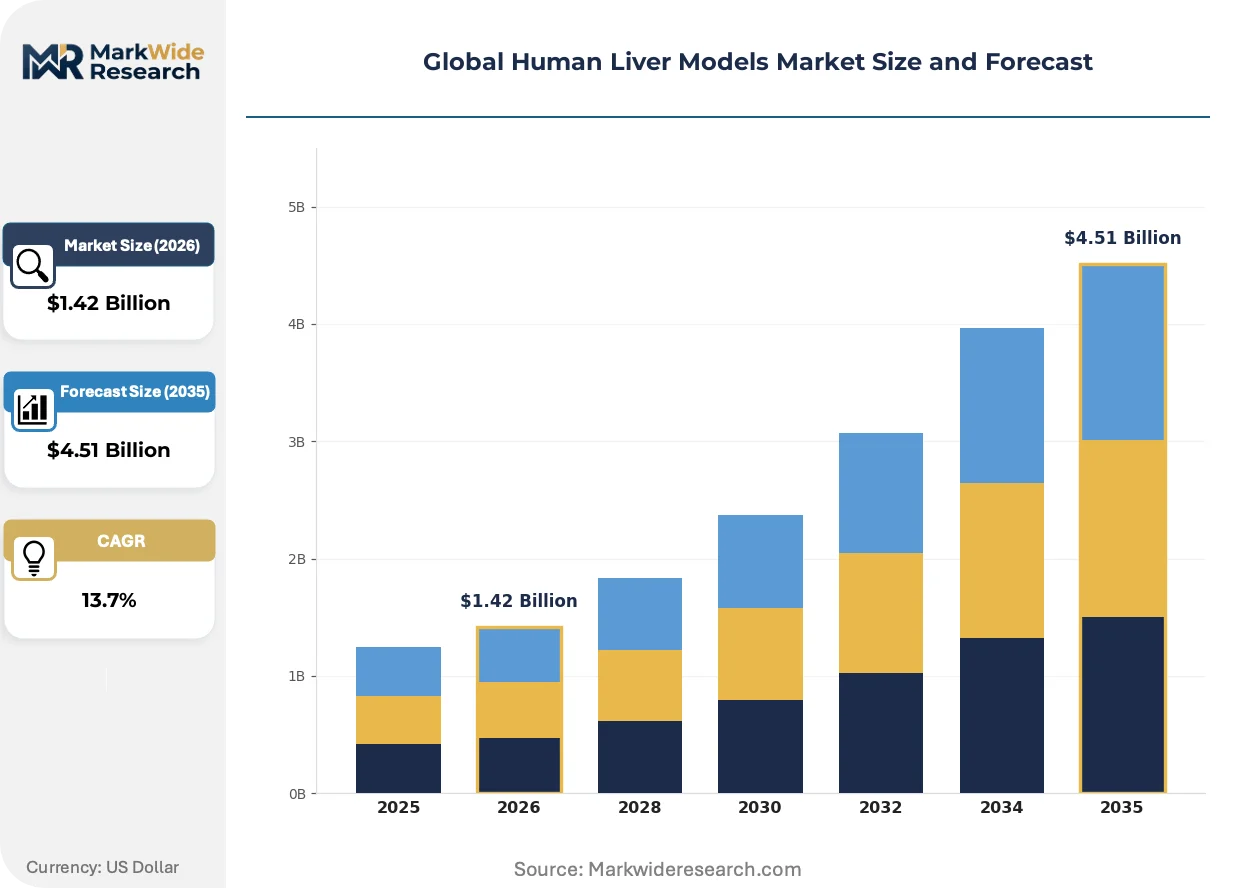
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Model Type: 3D Bioprinted Models, Organ-on-a-Chip, Spheroids, Microphysiological Systems Application: Drug Toxicity Screening, Disease Modeling, Pharmacokinetics Analysis, Personalized Medicine End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Research Organizations Technology: Stem Cell Technology, Tissue Engineering, Microfluidics, Gene Editing |
| Companies Covered | Emulate, Inc., InSphero, BioIVT, Organovo Holdings Inc., Mimetas, CN Bio Innovations Ltd, Merck KGaA, ATCC, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Liver Models Market Shifts & Advancements
Perfusion-capable microphysiological systems are displacing static culture formats as the dominant validation platform, compressing the gap between in vitro prediction and clinical outcomes while enabling multi-organ pharmacokinetic simulation.
Organ-on-a-chip technology is integrating dynamic fluid flow control with primary hepatocyte co-culture architectures to replicate bile canalicular transport and zone-specific metabolic gradients. Top-20 pharmaceutical developers are adopting these platforms for first-in-human dose prediction, replacing traditional sandwich culture hepatocyte assays. The structural consequence is a compression of preclinical attrition rates as human-relevant metabolism data enters regulatory submissions earlier.
REACH regulation amendments in Europe are mandating animal testing alternatives for chemical safety assessments, directly expanding addressable demand for validated hepatic toxicity models. Industrial chemical manufacturers must now submit in vitro data packages for new substance registrations, creating a parallel buyer segment beyond pharmaceutical applications. Germany and the Netherlands-based bioprinting facilities are scaling production to capture this industrial toxicology demand.
Pharmaceutical procurement departments are consolidating vendor relationships around integrated platform providers capable of multi-organ pharmacokinetic studies. Single-organ hepatotoxicity screening contracts are migrating toward subscription-based partnerships with vendors offering linked liver-intestine-kidney systems. This consolidation pattern is most visible among Boston and San Diego-based biotech clusters, where sponsor technical teams prioritize predictive translatability over per-assay cost minimization.
Global Human Liver Models Market Segmentation
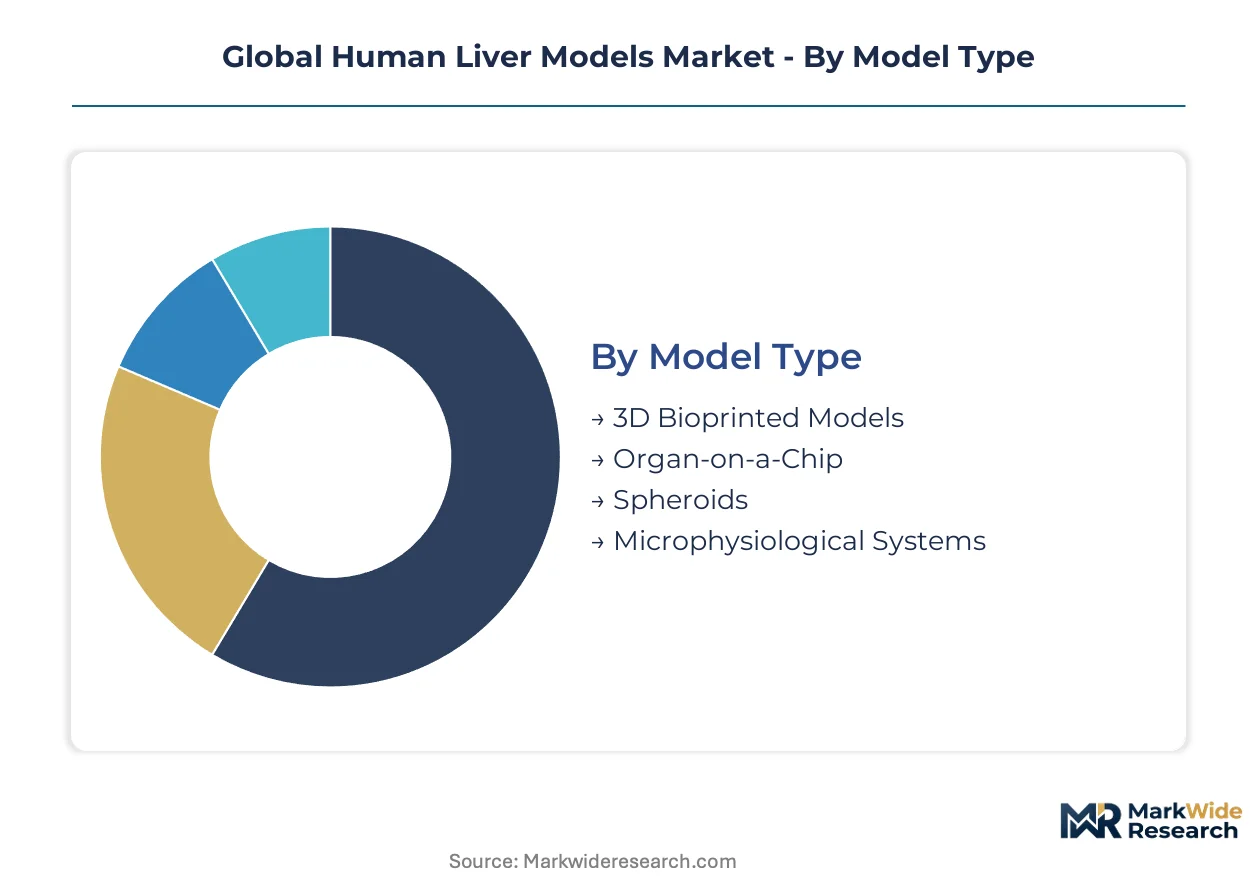
Segmentation in human liver models reflects divergent technical capabilities and regulatory acceptance thresholds. Pharmaceutical sponsors select formats based on prediction fidelity requirements, throughput demands, and submission pathway compatibility.
Model Type:
Technical architecture determines fluidic control precision, co-culture complexity, and metabolic fidelity to native hepatic zonation.
- Organ-on-a-Chip:Microfluidic platforms integrate primary hepatocytes with endothelial channels to replicate bile canalicular transport and shear stress responses. Demand concentrates among top-20 drug developers in the United States seeking FDA submission-grade pharmacokinetic data. These systems command premium positioning due to multi-organ linking capabilities.
- Microphysiological Systems:Advanced perfusion architectures enable zone-specific oxygen gradients and long-term metabolic enzyme induction studies. Boston and San Diego biotech clusters are scaling procurement of these platforms for first-in-human dose prediction workflows. Regulatory agencies are expanding acceptance criteria for this category.
- 3D Bioprinted Models:Layer-by-layer fabrication produces scalable hepatic tissue constructs for industrial toxicology screening under amended REACH protocols.
- Spheroids:Self-assembled hepatocyte aggregates occupy high-volume hepatotoxicity screening contracts where cost-per-assay minimization dominates procurement decisions.
Spheroids lead on scale; microphysiological systems lead on momentum.
Application:
End-use requirements range from binary toxicity classification to mechanistic disease pathway interrogation and patient-specific therapeutic optimization.
- Drug Toxicity Screening:Hepatotoxicity prediction remains the dominant procurement driver, with pharmaceutical sponsors replacing sandwich culture assays ahead of IND submissions. The FDA Modernization Act 2.0 is accelerating validation acceptance for in vitro hepatic safety data.
- Pharmacokinetics Analysis:ADME profiling contracts require metabolic enzyme induction and drug-drug interaction capabilities. CROs in Germany and the Netherlands are investing in perfusable liver architectures to capture industrial chemical registration demand.
- Disease Modeling:NAFLD and NASH progression models support mechanistic target validation for metabolic disease pipelines.
- Personalized Medicine:Patient-derived hepatocyte applications are gaining traction in oncology combination therapy optimization, though scale constraints limit current addressable market.
Toxicity screening dominates current procurement volume; pharmacokinetics analysis is climbing the fastest as multi-organ platform adoption accelerates.
End User:
Buyer sophistication and technical integration capabilities vary substantially across organizational categories.
- Pharmaceutical Companies:Internal platform deployment and strategic CRO partnerships characterize procurement patterns among large-cap sponsors. These buyers prioritize predictive translatability and regulatory submission readiness over per-assay economics.
- Contract Research Organizations:Service providers in the United States are consolidating vendor relationships around integrated platform suppliers capable of liver-kidney and liver-intestine linking. Subscription-based partnership models are displacing transactional assay contracts.
- Biotechnology Firms:Mid-cap developers leverage outsourced hepatotoxicity screening to conserve capital for clinical milestone advancement.
- Academic Research Institutes:Investigator-initiated studies drive early-stage platform validation and publication output, though commercial procurement volumes remain limited.
Pharmaceutical companies anchor demand concentration; contract research organizations are gaining share fastest through platform consolidation.
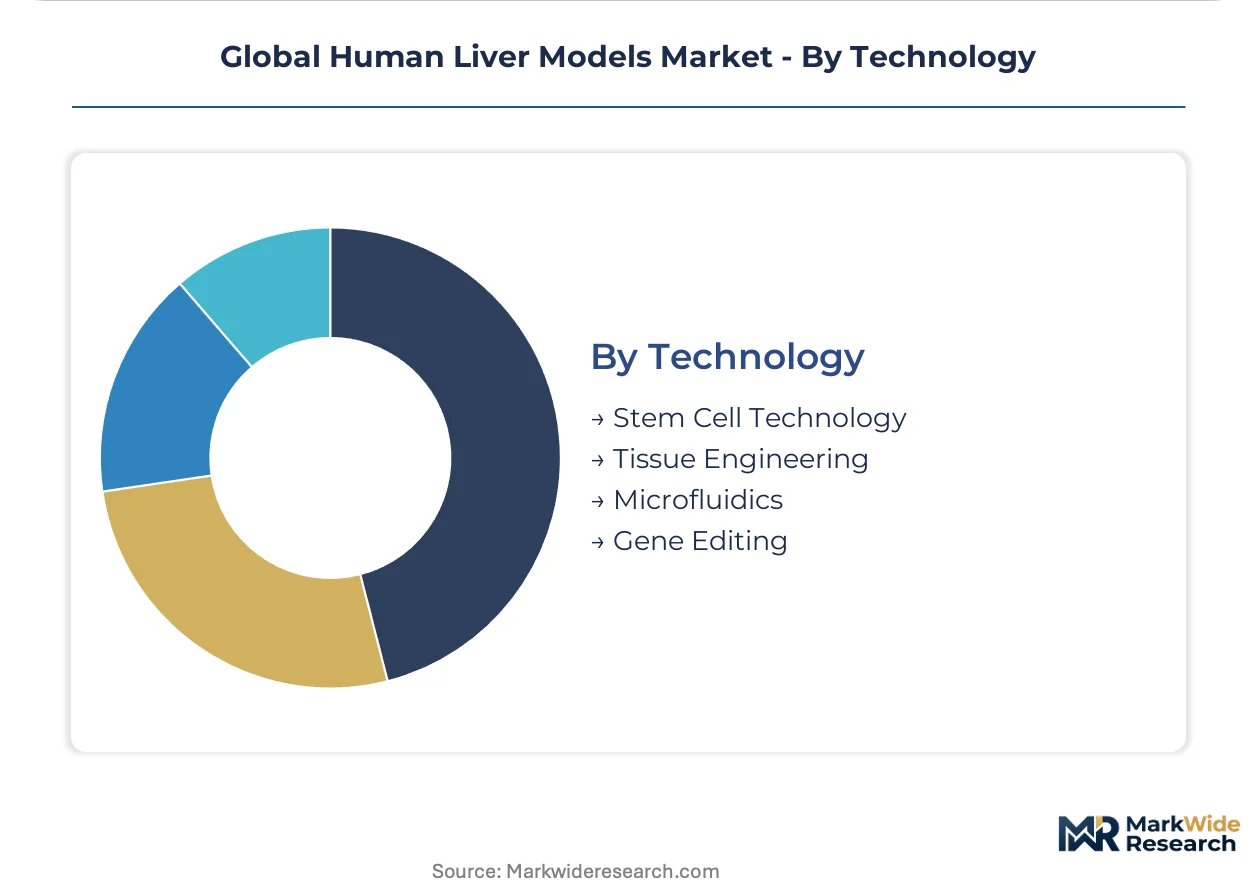
Technology:
Underlying technical enablers determine differentiation sustainability and manufacturing scalability.
- Microfluidics:Precision fluid control enables dynamic perfusion and real-time metabolite sampling. Engineering talent scarcity at the cell biology-chip fabrication intersection constrains scale-up velocity for platform developers.
- Stem Cell Technology:iPSC-derived hepatocyte maturation protocols are reducing dependency on primary cell sourcing volatility. Japan's PMDA pathway evolution is creating demand for standardized pluripotent cell quality documentation.
- Tissue Engineering:Scaffold and hydrogel matrix development supports 3D architecture fidelity, though ISO 10993 biocompatibility certification extends product launch timelines.
- Gene Editing:CRISPR-mediated disease model construction enables mechanistic pathway studies, with adoption concentrated in academic and biotech research segments.
Microfluidics leads on commercial deployment; stem cell technology is expanding most quickly as donor tissue supply constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting liver model production toward markets with streamlined biocompatibility certification pathways. Manufacturers are arbitraging compliance cost gaps by establishing technical facilities in jurisdictions offering accelerated validation timelines for microphysiological systems.
United States
FDA Modernization Act 2.0 eliminated mandatory animal testing requirements, redirecting sponsor budgets toward liver-on-a-chip platforms. Boston and San Diego biotech clusters house the densest concentration of contract research organizations adopting perfusable tissue architectures. These metropolitan markets are consolidating vendor relationships around integrated multi-organ platform providers.
Germany
Amended REACH regulations mandate animal testing alternatives for chemical safety assessments, expanding industrial toxicology demand beyond pharmaceutical applications. ECHA guidance on in vitro methods accelerates validation acceptance for hepatic organoid data. Bioprinting facilities in Baden-Württemberg and North Rhine-Westphalia are scaling production lines to capture industrial chemical registration contracts.
Netherlands
Leiden and Eindhoven research corridors concentrate microfluidic engineering talent for organ-on-a-chip fabrication. Dutch national innovation programs support high-throughput 3D cell culture infrastructure development. Mimetas anchors regional competitive positioning through proprietary OrganoPlate technology serving European pharmaceutical sponsors.
Japan
PMDA pathway evolution creates demand for standardized iPSC-derived hepatocyte quality documentation. METI funding initiatives target microphysiological system commercialization for first-in-human dose prediction. Tokyo-Osaka pharmaceutical corridors are integrating liver-kidney chip platforms into preclinical service procurement patterns.
India
CDSCO evolving biosimilar guidelines create entry points for hepatotoxicity screening services in generic drug development. National pharmaceutical clusters in Hyderabad and Mumbai are attracting contract research investment for cost-competitive in vitro validation. Domestic stem cell research programs aim to reduce dependency on imported primary hepatocyte sourcing.
Global Human Liver Models Market Competitive Landscape
United States producers anchor the premium technology tier; European specialists hold position in industrial toxicology applications. The vendor structure concentrates around integrated platform developers capable of multi-organ pharmacokinetic studies. Three archetypes dominate: microfluidic chip fabricators, primary cell sourcing specialists, and bioprinted tissue manufacturers. Strategic consolidation centers on M&A for technology licensing portfolios and geographic expansion into Asia-Pacific regulatory markets.
Within the integrated platform tier, Emulate, Inc. and Mimetas occupy positions exemplifying divergent technical approaches to organ-on-a-chip commercialization. Thermo Fisher Scientific Inc. anchors the life sciences conglomerate archetype with distribution infrastructure spanning validation reagent supply. Among cell sourcing specialists, BioIVT represents the primary hepatocyte supply chain control model that manufacturers depend upon for metabolic fidelity in hepatic constructs.
| Leading Market Players |
|---|
| Emulate, Inc. |
| InSphero |
| BioIVT |
| Organovo Holdings Inc. |
| Mimetas |
| CN Bio Innovations Ltd |
| Merck KGaA |
| ATCC |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Pharmaceutical procurement consolidation around multi-organ platform providers is forcing liver model manufacturers to absorb Matrigel and primary hepatocyte cost volatility while maintaining subscription pricing predictability for CRO partners.
Pricing Analysis
Distributor margins on consumable reagents run 15-25% above direct platform sales, creating channel conflict for matrix suppliers serving both routes. Pricing stratifies across FDA submission-grade organ-on-a-chip systems, standard throughput spheroid assays, and economy-tier 2D hepatocyte cultures. Cost compression in the spheroid segment is intensifying as BioIVT and competing cell suppliers expand donor network coverage. Mid-cap biotech sponsors exhibit highest price sensitivity, while top-20 pharmaceutical developers prioritize predictive translatability over per-assay economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States pharmaceutical developers, while distributor networks serve European CROs and Asia-Pacific academic institutes. Manufacturing concentrates in the United States, Germany, and the Netherlands, with bioprinting facilities in Baden-Württemberg and North Rhine-Westphalia scaling for REACH-mandated industrial toxicology contracts. Raw material sourcing draws from limited-qualified Matrigel suppliers, seasonal primary hepatocyte donor networks, and precision microfluidic fabrication foundries. Single-source vulnerability in basement membrane extract supply creates margin instability for collagen-alternative developers. Distribution runs through life sciences distributors for reagent consumables and direct technical sales for integrated platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between FDA's Modernization Act 2.0 and Japan's evolving PMDA pathways creates arbitrage opportunities for manufacturers establishing technical facilities in jurisdictions with accelerated biocompatibility certification timelines.
For Market Incumbents: Extend platform capabilities into liver-kidney and liver-intestine linking to defend against specialized microfluidic entrants capturing pharmacokinetic modeling contracts. Invest in ISO 10993 certification for novel hydrogel matrices to preempt regulatory friction in multi-jurisdictional submissions. Capacity addition in the Netherlands and Germany captures REACH-mandated industrial toxicology demand beyond pharmaceutical applications. For New Entrants and Emerging Players: Enter via CDSCO-aligned hepatotoxicity screening services for Indian generic drug developers, where biosimilar guideline evolution outpaces domestic platform supply. Target mid-cap United States biotech sponsors in Boston and San Diego clusters seeking outsourced alternatives to capital-intensive internal platform deployment. A subscription-based partnership model with CROs displaces transactional assay contracts most effectively. For Investors and Strategic Acquirers: Asymmetric upside sits with stem cell technology specialists reducing primary hepatocyte dependency through iPSC maturation protocols. The five-to-ten year viability window favors platforms demonstrating regulatory submission-grade data packages across FDA and EMA pathways. Acquisition targets include microfluidic engineering teams at the cell biology-chip fabrication intersection, with PMDA iPSC quality documentation standardization serving as the inflection indicator for Asia-Pacific market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Organ Platform Integration | Liver-kidney linking captures pharmacokinetic modeling contracts from mid-cap biotech sponsors in Boston. |
| ISO 10993 Biocompatibility Certification | Novel hydrogel matrix qualification accelerates product launch timelines for 3D bioprinted tissue manufacturers. |
| REACH-Aligned Industrial Toxicology Expansion | German bioprinting facilities capture chemical safety assessment contracts beyond pharmaceutical applications. |
| iPSC Hepatocyte Maturation Investment | Reduced donor tissue dependency insulates manufacturers from seasonal primary cell supply volatility. |
| CDSCO Pathway Alignment | Indian generic drug developers create entry points for cost-competitive hepatotoxicity screening services. |
Research Methodology
Coverage spans the United States, Germany, the Netherlands, Japan, and India, with primary inputs from each market cluster. The research combines structured interviews with drug development executives, regulatory affairs leads at organ-on-a-chip developers, CRO procurement managers, and academic principal investigators with secondary validation. Secondary sources include FDA Modernization Act 2.0 implementation guidance, EMA 3Rs initiative documentation, ECHA REACH amendments, OECD Test Guideline 497 protocols, and ClinicalTrials.gov hepatotoxicity study records. Bottom-up segment sizing and top-down market triangulation cross-validate volume estimates.
Granularity-level modeling captures organ-on-a-chip, microphysiological systems, 3D bioprinted models, and spheroid architectures at the platform tier; drug toxicity screening, pharmacokinetics analysis, disease modeling, and personalized medicine at the application tier; and pharmaceutical companies, contract research organizations, biotechnology firms, and academic institutes at the end-user tier. CAGRs derive from segment-level growth trajectory analysis incorporating regulatory acceptance timeline acceleration, multi-organ platform adoption curves, and primary hepatocyte supply elasticity assumptions. Forecast inputs include EMA 3Rs validation expansion rates and PMDA iPSC quality documentation pathway evolution.
The model holds under sustained regulatory acceptance of human-relevant in vitro data; deviation in cross-jurisdictional validation friction or Matrigel supply disruption would shift platform adoption timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Metabolomics Market
Medical Research
US Academic Medical Centers Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Epigenomics Market
Medical Research
PDX Models Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
Mice Model Technologies Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Epigenetics Market
Medical Research
Organoids and Spheroids Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Placenta Market