
 Global Health Kiosk Market | 2026-2036
Global Health Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Global Health Kiosk Market Foresight
Aluminum alloy enclosures are rebalancing unit economics as manufacturers replace heavier steel chassis to reduce shipping costs and extend deployment flexibility in mobile kiosk configurations. NCR Corp. leverages its ATM heritage to dominate self-service check-in terminal production for hospital networks. Olea Kiosks Inc. specializes in custom medical-grade housings that sustain premium positioning across telemedicine deployments. Diebold Nixdorf Inc. competes through integrated systems that combine biometric authentication with payment processing.
A health kiosk constitutes a freestanding, interactive terminal engineered to capture physiological data, facilitate remote clinical encounters, or deliver targeted health information through integrated touchscreens, medical sensors, and secure network connectivity. These units typically incorporate FDA-cleared blood pressure cuffs, pulse oximeters, and ECG modules operating within IEC 60601-1 electrical safety parameters, serving to extend clinical reach into non-traditional care settings while reducing staffed facility overhead. Vital signs monitor kiosks anchor current volume as pharmacies and corporate wellness centers prioritize low-complexity, high-frequency biometric screening. Telemedicine kiosk configurations represent the fastest-expanding segment, propelled by reimbursement parity for remote consultations and specialist access gaps in rural geographies. Self-service check-in terminals occupy a mature position with thinner margin pools, though cloud-connected deployment architectures are redistributing software revenue toward recurring service contracts.
FDA clearance requirements under 510(k) pathways shape hardware development timelines and sensor integration choices for manufacturers targeting US clinical settings. The EU Medical Device Regulation and CE marking obligations impose parallel conformity demands for European market entry, while ISO 13485 quality management certification operates as a baseline procurement filter for health system buyers across jurisdictions. Stakeholders must monitor evolving cybersecurity frameworks from NIST and state-level biometric privacy statutes that will determine liability exposure and data architecture investments.
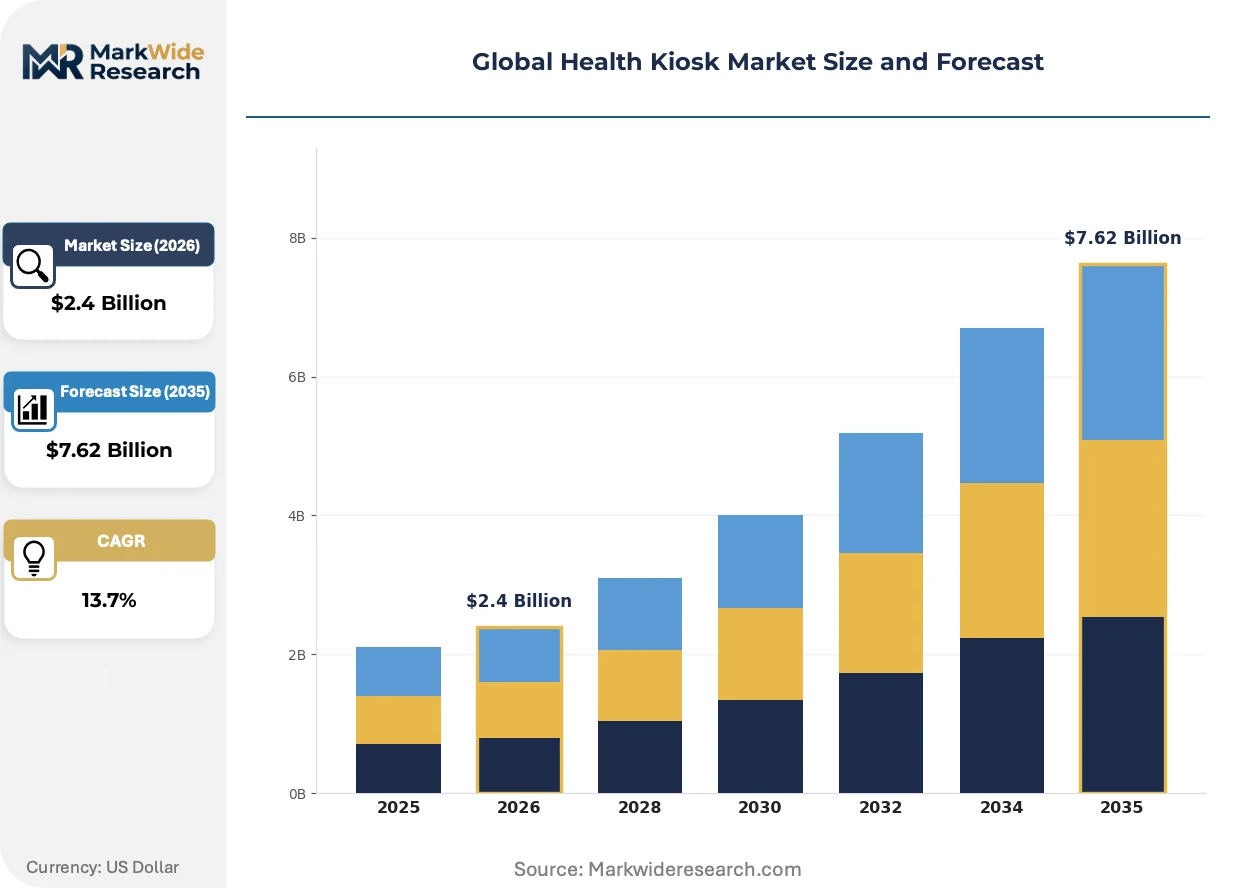
Market Dynamics
Retail pharmacy chains and corporate wellness programs are pulling kiosk volumes toward high-frequency biometric screening, while FDA 510(k) clearance timelines compress hardware refresh cycles and sensor integration roadmaps for manufacturers targeting clinical-grade deployments.
Growth Catalysts
- Employer wellness mandates:Large self-insured employers in the United States are installing screening kiosks to satisfy ACA preventive care requirements and reduce downstream claims costs.
- Reimbursement parity for telehealth:CMS and state Medicaid programs extending payment parity to remote consultations is accelerating telemedicine kiosk deployments in rural primary care deserts.
- Aluminum chassis substitution:Manufacturers replacing steel enclosures with aluminum alloys are cutting per-unit shipping weight by 40 percent, enabling mobile and pop-up clinic configurations previously uneconomical.
Market Restraints
- Semiconductor sensor supply concentration:Pulse oximeter and ECG module fabrication concentrates among Taiwanese and South Korean foundries, exposing hardware timelines to foundry allocation volatility.
- Biometric privacy litigation exposure:Illinois BIPA and emerging state statutes impose statutory damages per biometric capture, forcing architecture investments in on-device processing and edge storage.
- Legacy EMR integration friction:Hospital IT departments face 12-18 month integration timelines with Cerner and Epic systems, delaying kiosk network expansions and compressing vendor cash conversion cycles.
Strategic Opportunities
- Underserved Indian primary care:India's Jan Aushadhi scheme and Health and Wellness Center expansion create procurement channels for low-cost vital signs kiosks in 150,000 rural sub-centers.
- Mental health screening convergence:Integration of PHQ-9 and GAD-7 digital assessments with physiological monitoring opens reimbursement pathways in behavioral health carve-outs.
- EU MDR Class IIa pathway:The Medical Device Regulation's software classification clarity is enabling CE-marked kiosk-as-medical-device positioning for telemedicine configurations in Germany, France, and the Netherlands.
Industry Challenges
- Cybersecurity engineering talent scarcity:NIST 800-53 and state biometric privacy compliance require embedded security architects, a skill set concentrated among defense contractors and medical device incumbents.
- IEC 60601-1 third-party certification backlog:Electrical safety testing laboratory capacity constraints in North America and Europe are extending hardware launch timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Health Kiosk Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vital Signs Monitor, Telemedicine Kiosk, Self-Service Check-In, Health Information Terminal, Diagnostic Kiosk Application: Patient Screening, Wellness Assessment, Remote Consultation, Health Education, Chronic Disease Management End User: Pharmacies, Corporate Wellness Centers, Clinics, Community Centers, Educational Institutions Deployment: Standalone Units, Integrated Systems, Mobile Kiosks, Cloud-Connected, On-Premises Installation |
| Companies Covered | NCR Corp., Olea Kiosks Inc., KIOSK Information Systems, Diebold Nixdorf Inc., Glory Ltd., Zebra Technologies Corp., XIPHIAS Group, Fabcon Inc., Nexcom International Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Health Kiosk Market Shifts & Advancements
Edge computing architectures and on-device AI inference are displacing cloud-dependent processing models, reducing latency for real-time clinical decision support while addressing data sovereignty constraints in multi-jurisdictional deployments.
Computer vision-based contactless vital signs monitoring is converging with traditional cuff-based measurement in hybrid kiosk configurations. Pharmacy chains including CVS and Walgreens are piloting camera-derived heart rate and respiratory rate capture to reduce consumable costs and maintenance intervals. This convergence is compressing the addressable market for single-modality vital signs kiosks while expanding total screening throughput per square foot of retail floor space.
The EU AI Act's risk classification framework for medical device software is reshaping product development roadmaps for kiosk manufacturers seeking European market entry. High-risk AI systems deployed in healthcare settings face conformity assessment obligations that parallel MDR requirements, forcing vendors to maintain dual technical documentation streams. German hospital procurement committees are already inserting AI Act compliance clauses into tender specifications ahead of full enforcement.
Subscription-based service contracts are displacing perpetual software licenses in hospital network deployments. Health systems in the United States are unbundling hardware acquisition from software maintenance, preferring per-screening or per-clinician-minute pricing models that align vendor incentives with utilization rates. This shift is most visible in IDN-managed specialty clinic networks where capital budget constraints favor operating expenditure treatment for kiosk infrastructure.
Global Health Kiosk Market Segmentation
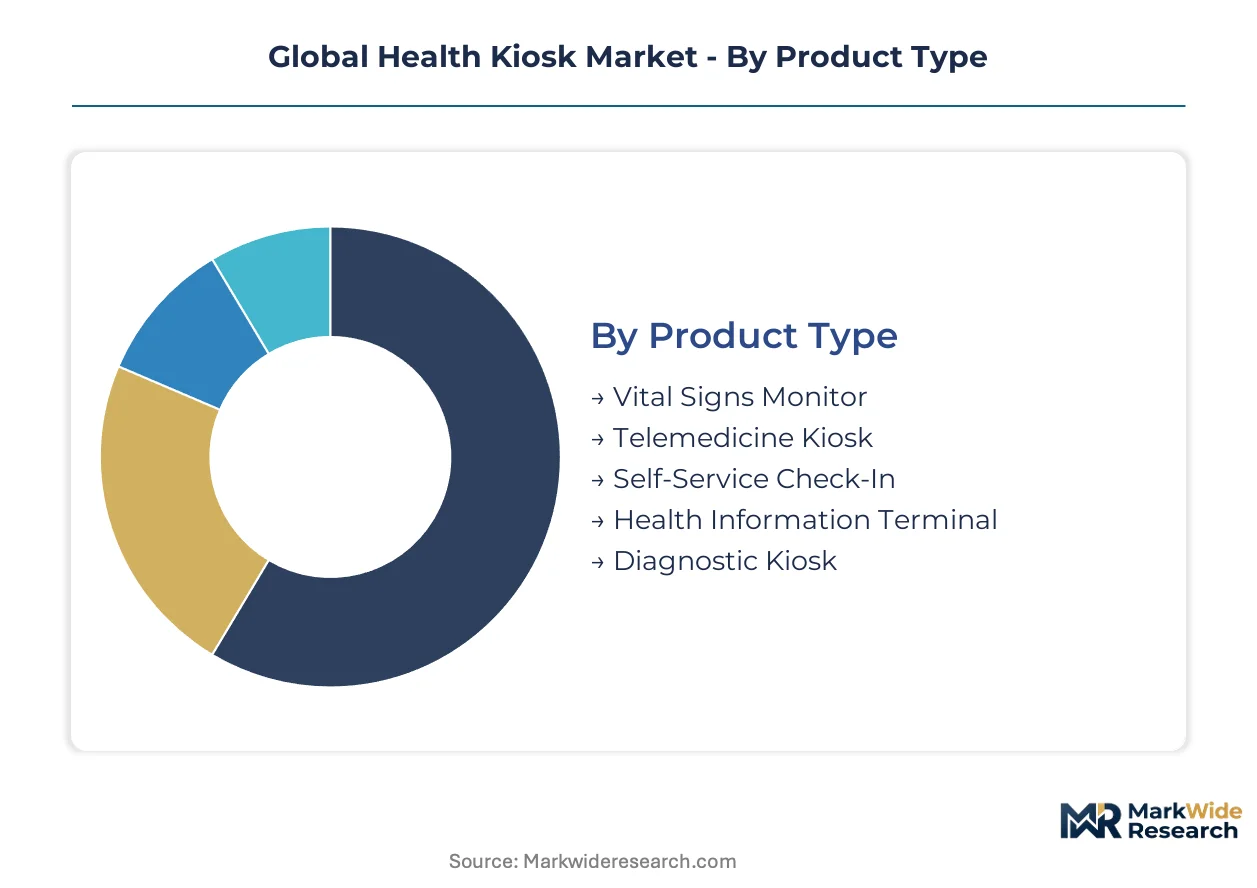
Health kiosk segmentation reveals divergent hardware architectures and software stacks optimized for distinct clinical workflows. Manufacturers configure sensor arrays, connectivity protocols, and enclosure designs around specific reimbursement pathways and end-user technical capabilities.
Product Type:
Standardized vital signs modules dominate pharmacy deployments while telemedicine configurations demand bespoke camera, audio, and peripheral integration for specialist consultation fidelity.
- Vital Signs Monitor:Compact units integrate FDA-cleared blood pressure cuffs, pulse oximeters, and ECG modules within IEC 60601-1 electrical enclosures. Pharmacies across the United States deploy these for high-frequency biometric screening under employer wellness contracts, constrained by consumable replacement logistics and calibration maintenance intervals.
- Telemedicine Kiosk:Full-duplex audio, high-definition pan-tilt-zoom cameras, and stethoscope peripherals enable remote specialist examinations. Rural primary care deserts in Texas, Montana, and Alaska drive procurement as CMS reimbursement parity eliminates financial barriers to virtual consultation adoption.
- Self-Service Check-In:Streamlined terminals manage patient registration, insurance verification, and queue routing.
- Health Information Terminal:Touchscreen displays deliver targeted educational content and preventive care reminders.
- Diagnostic Kiosk:Expanded sensor suites capture laboratory-quality measurements including spirometry and blood glucose.
Leading the category by volume: Vital Signs Monitor. Expanding most quickly: Telemedicine Kiosk.
Application:
Volume concentrates in preventive screening workflows while chronic disease management applications command premium pricing through longitudinal data integration requirements.
- Patient Screening:Rapid biometric capture for triage, occupational health, and insurance underwriting. Corporate wellness mandates in the United States accelerate installations as self-insured employers seek ACA compliance and claims cost reduction through early risk identification.
- Chronic Disease Management:Scheduled monitoring protocols for diabetes, hypertension, and congestive heart failure with automated alert escalation. Medicare Advantage plans in Florida, Arizona, and California reimburse remote patient monitoring codes, driving kiosk placement in senior housing and community centers.
- Wellness Assessment:Lifestyle and behavioral risk profiling for preventive care programs.
- Remote Consultation:Synchronous clinical encounters bridging geographic specialist access gaps.
- Health Education:Interactive content delivery for medication adherence and lifestyle modification.
Patient Screening generates the highest unit shipments. Chronic Disease Management claims the steepest expansion trajectory as value-based care contracts proliferate.
End User:
Procurement sophistication spans from standardized retail pharmacy tenders to highly customized corporate wellness specifications with branding and EMR integration demands.
- Pharmacies:CVS, Walgreens, and independent chains deploy screening kiosks to drive foot traffic and clinical service revenue. United States retail health expansion programs prioritize compact footprints and minimal staff intervention for 24/7 lobby accessibility.
- Corporate Wellness Centers:On-site biometric screening for employee populations with data integration into benefits administration platforms. Fortune 500 headquarters in Illinois, California, and Texas mandate installations satisfying biometric privacy statutes including BIPA compliance architecture.
- Clinics:Federally qualified health centers and rural health clinics extend capacity through kiosk-augmented workflows.
- Community Centers:Public health department deployments for underserved population outreach.
- Educational Institutions:University health services and K-12 nurse office installations for student screening.
Pharmacies anchor procurement volume. Corporate Wellness Centers are climbing the fastest as employer-sponsored healthcare cost containment intensifies.
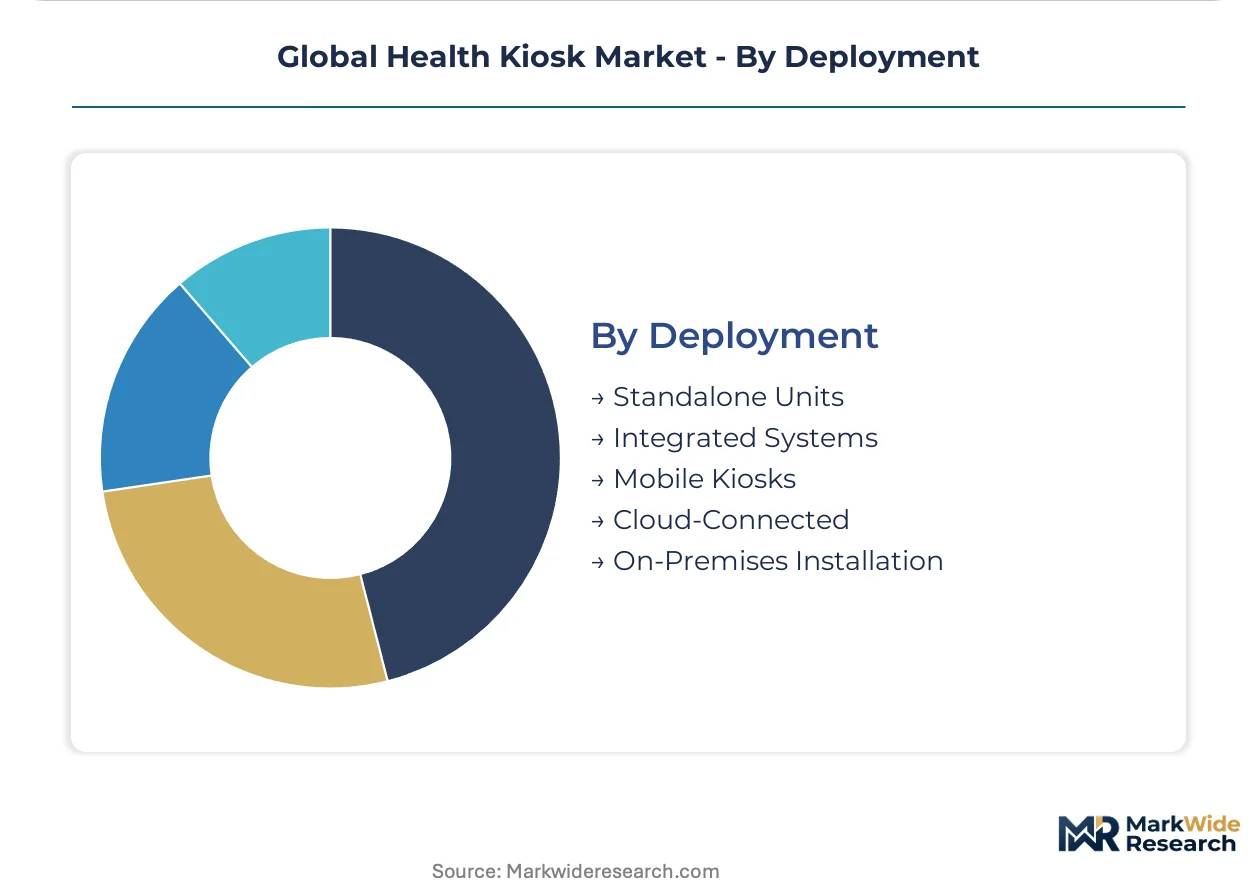
Deployment:
Physical configuration choices reflect mobility requirements, network reliability constraints, and capital versus operating expenditure preferences.
- Standalone Units:Self-contained kiosks with embedded computing, local storage, and cellular backup connectivity. Mobile clinic operators in India and sub-Saharan Africa favor these for deployment in infrastructure-constrained environments where cloud dependency creates unacceptable clinical risk.
- Cloud-Connected:Thin-client architectures streaming data to centralized EMR repositories and AI diagnostic engines. German hospital networks adopt these configurations to satisfy EU AI Act and GDPR data sovereignty requirements through regional cloud instance hosting.
- Integrated Systems:Kiosk modules embedded within broader hospital information system architectures.
- Mobile Kiosks:Battery-powered units with aluminum alloy enclosures for pop-up clinic and disaster response deployment.
- On-Premises Installation:Hardwired configurations with dedicated server infrastructure for maximum data control.
Standalone Units lead deployment volume. Cloud-Connected configurations are gaining share fastest as health systems unbundle hardware from software maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retail health expansion and employer wellness mandates concentrate demand for biometric screening infrastructure, while reimbursement parity for telehealth consultations accelerates rural kiosk deployment across Texas, Montana, and Alaska.
United States
CVS and Walgreens pharmacy chains drive volume through 24/7 lobby accessibility programs, while Fortune 500 headquarters in Illinois, California, and Texas mandate installations satisfying biometric privacy statutes. FDA 510(k) clearance pathways compress hardware refresh cycles for clinical-grade sensor integration. Greater Boston anchors telemedicine kiosk development, with Massachusetts General Hospital pilots validating remote specialist consultation workflows.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia insert EU AI Act compliance clauses into tender specifications ahead of full enforcement. The Medical Device Regulation's software classification clarity enables CE-marked kiosk-as-medical-device positioning for telemedicine configurations. Berlin-Brandenburg clusters cloud-connected deployment architectures to satisfy GDPR data sovereignty through regional cloud instance hosting.
India
Jan Aushadhi scheme procurement channels open for low-cost vital signs kiosks across 150,000 rural sub-centers under Health and Wellness Center expansion. The Central Drugs Standard Control Organization regulates medical device imports while domestic manufacturing incentives accelerate local assembly. Maharashtra and Gujarat industrial corridors concentrate enclosure fabrication and sensor module integration for cost-optimized standalone units.
Japan
Ministry of Economy, Trade and Industry promotes aging-in-place technologies, driving kiosk placement in senior housing and community centers for chronic disease monitoring. Pharmaceutical and Medical Devices Agency clearance requirements parallel FDA timelines for pulse oximeter and ECG module integration. Kanto region hospital networks pilot subscription-based service contracts that unbundle hardware acquisition from software maintenance.
United Arab Emirates
Dubai Health Authority mandates digital health infrastructure in new commercial developments, creating procurement channels for integrated check-in and screening terminals. Ministry of Health and Prevention guidelines shape biometric data governance requirements for employer wellness installations. Abu Dhabi clusters cloud-connected configurations serving medical tourism facilities seeking seamless international patient registration workflows.
Global Health Kiosk Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent ATM and payment terminal manufacturers pivot medical-grade enclosure expertise toward health kiosk configurations. The vendor base stratifies across three tiers: legacy financial self-service equipment suppliers with certified manufacturing infrastructure, specialized medical enclosure fabricators with IEC 60601-1 compliance track records, and emerging regional assemblers serving price-sensitive procurement channels. Consolidation pressure concentrates among mid-scale players seeking FDA 510(k) clearance capabilities through acquisition. Technology licensing agreements for biometric authentication modules represent a secondary competitive vector.
Within the legacy financial equipment tier, NCR Corp. and Diebold Nixdorf Inc. occupy positions shaped by decades of ATM production heritage and payment processing integration. Olea Kiosks Inc. exemplifies the specialized medical enclosure archetype, with custom housing fabrication sustaining premium positioning across telemedicine deployments. These three entities represent distinct strategic postures: scale-driven platform leverage, certification-intensive custom engineering, and integrated biometric-payment convergence.
| Leading Market Players |
|---|
| NCR Corp. |
| Olea Kiosks Inc. |
| KIOSK Information Systems |
| Diebold Nixdorf Inc. |
| Glory Ltd. |
| Zebra Technologies Corp. |
| XIPHIAS Group |
| Fabcon Inc. |
| Nexcom International Co. Ltd. |
| Others |
Supply & Pricing Matrix
Embedded security architects concentrated in Massachusetts and California defense corridors command wage premiums that compress margins for IEC 60601-1 certified enclosure manufacturers, widening spreads between FDA-cleared premium tiers and uncertified economy configurations.
Pricing Analysis
Volume concentrates in vital signs monitor kiosks with thin margins, while telemedicine configurations capture premium pricing through FDA 510(k) clearance requirements and custom peripheral integration. Price differentiation hinges on certification grade (FDA-cleared vs. non-clinical wellness tier) and EMR integration depth, with cloud-connected architectures commanding recurring SaaS premiums. Pricing pressure stems from aluminum chassis substitution reducing hardware costs and forcing margin compression in standard tiers. Corporate wellness centers exhibit highest price sensitivity due to procurement standardization, while hospital IDNs accept premium pricing for cybersecurity-hardened configurations.
Supply Chain Analysis
Regional distribution centers in Texas and Ohio anchor North American fulfillment, with hub-and-spoke patterns extending to hospital networks and pharmacy chains. Component sourcing concentrates in Taiwan and South Korea for pulse oximeter and ECG module fabrication, with domestic aluminum enclosure production in Michigan and Ohio. Supply chain risk centers on foundry allocation volatility for semiconductor sensors. Distribution runs through medical device distributors and direct OEM relationships with health system GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FDA 510(k) clearance timelines and cybersecurity compliance costs force sub-scale manufacturers toward acquisition or exit.
For Market Incumbents: Cement certification moats by accelerating IEC 60601-1 third-party testing investments and acquiring embedded security engineering capabilities from defense contractor talent pools. Defend against emerging computer vision contactless monitoring substitutes by integrating hybrid sensor architectures that preserve cuff-based clinical validation while adding camera-derived throughput enhancements. For New Entrants and Emerging Players: Edge AI inference modules for on-device biometric processing offer a technology-first wedge into rural primary care deserts and Indian Jan Aushadhi procurement channels underserved by cloud-dependent incumbents. Target standalone unit configurations for mobile clinic operators in infrastructure-constrained environments, leveraging aluminum alloy enclosure partnerships with Maharashtra fabrication clusters to undercut legacy steel chassis economics. For Investors and Strategic Acquirers: The window for entry favors mid-scale manufacturers with FDA 510(k) clearance track records but incomplete cybersecurity engineering benches, as hospital procurement committees harden NIST 800-53 compliance requirements. Monitor Illinois BIPA litigation volume and state biometric privacy statute proliferation as the signal indicating which portfolio companies face liability exposure acceleration versus architecture investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates hospital procurement eligibility and commands 40% pricing premiums over wellness-tier alternatives. |
| CE Marking Under EU MDR | Unlocks German hospital procurement committees and satisfies AI Act conformity assessment obligations ahead of enforcement. |
| Hospital System Partnership | Secures recurring SaaS revenue streams through subscription-based service contracts replacing perpetual licenses. |
| Software Companion Development | Enables PHQ-9 and GAD-7 mental health screening integration opening behavioral health reimbursement pathways. |
| Reimbursement Strategy | Aligns kiosk placement with CMS remote patient monitoring codes and Medicare Advantage chronic disease management contracts. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, hospital procurement database patterns, and pharmacy chain deployment announcements anchored the trend analysis, supplemented by interviews with biomedical engineers, GPO contracts managers, health system CIOs, and kiosk manufacturer product directors. Secondary validation drew from FDA 510(k) database filings, CMS reimbursement code updates, hospital capital expenditure disclosures, and EU MDR notified body certification records. Bottom-up unit shipment estimates triangulated against top-down health system IT budget allocations.
Segment-weighting applied product type, application workflow, end-user procurement sophistication, and deployment architecture dimensions across the projection horizon. CAGRs derived from regression analysis of historical kiosk installation velocities against reimbursement policy inflection points and health system capital cycle timing. Industry-specific inputs included semiconductor foundry allocation forecasts and state biometric privacy statute enactment trajectories.
Several conditions sit outside the modeled scope, including pandemic-era emergency use authorization reversals, major EMR vendor acquisition discontinuities, and geopolitical semiconductor export restrictions. Forecasts reflect documented assumptions regarding reimbursement parity maintenance and regulatory clarity timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market