
 Plastic Door and Window Market | 2026-2036
Plastic Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Door and Window Market Analysis
Renovation contractors are redrawing demand patterns in the plastic door and window sector, pulling volume away from pure new-construction channels. Deceuninck NV leverages its extrusion scale to dominate European renovation supply chains. Veka AG anchors its position through rigid PVC formulation leadership and fabricator network density. Andersen Corporation competes by extending its fiberglass composite expertise into premium replacement segments.
Plastic doors and windows are factory-assembled frame-and-sash systems extruded primarily from unplasticized polyvinyl chloride (uPVC) or pultruded fiberglass, designed to deliver thermal insulation, acoustic dampening, and weather resistance in building envelopes. Casement and sliding configurations lead residential volume, while commercial specification tilts toward fixed and awning geometries with reinforced steel or aluminum inserts. uPVC commands the material mix due to cost efficiency and recyclability, though fiberglass composites are capturing margin pools in high-performance and coastal applications where dimensional stability under thermal cycling matters.
EPA ENERGY STAR certification, the EU F-Gas Regulation, and REACH chemical compliance collectively shape product formulation, insulating glass specifications, and market access thresholds across major demand centers. Building codes in Germany, California, and the United Kingdom now mandate U-value minimums that favor multi-chamber profiles and warm-edge spacer technology. Stakeholders must monitor how embodied-carbon accounting and extended producer responsibility schemes recalibrate material selection and end-of-life recovery economics.
Market Dynamics
Residential renovation channels are absorbing volume from new-build contractors as housing stock ages across mature economies, forcing extruders to reconfigure fabrication networks toward replacement-grade lead times and custom dimension flexibility.
Growth Catalysts
- ENERGY STAR criteria tightening:The EPA's evolving thermal performance thresholds in the United States are mandating multi-chamber profiles and warm-edge spacers, pulling upgrade demand from existing housing stock.
- Urban housing modernization:China, India, and Brazil are concentrating replacement activity as municipal governments enforce building envelope efficiency codes in legacy residential towers.
- uPVC recyclability:Closed-loop regrind systems are lowering input costs for fabricators while satisfying extended producer responsibility schemes emerging in European waste frameworks.
Market Restraints
- Resin price volatility:PVC feedstock costs track ethylene and chlorine spot markets, compressing margin stability for profile extruders without captive chlor-alkali capacity.
- Steel reinforcement supply:Galvanized steel insert fabrication concentrates in Turkish and Chinese rolling mills, exposing European and North American window fabricators to tariff and logistics friction.
- Aluminum substitution:Thermally broken aluminum frames are capturing specification share in commercial high-rise segments where structural load requirements exceed uPVC mechanical limits.
Strategic Opportunities
- Coastal corrosion resistance:Pultruded fiberglass composites are penetrating Florida, Queensland, and Mediterranean markets where salt-laden atmospheres degrade PVC dimensional stability within warranty periods.
- Smart glass integration:Electrochromic and thermochromic glazing convergence with plastic frame systems is opening premium residential retrofit channels in Germany and California.
- Fabricator network consolidation:Independent regional window assemblers in the United Kingdom and Poland present acquisition targets for extruders seeking captive installation capacity.
Industry Challenges
- Warm-edge spacer certification:IGCC and ift Rosenheim testing timelines for thermal bridge reduction components extend 14-18 months, delaying product launches for reformulated frame geometries.
- Skilled installer scarcity:Precision replacement of legacy steel-frame units with uPVC systems demands certified fitters; vocational pipeline gaps in France and Italy constrain renovation throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Door and Window Market |
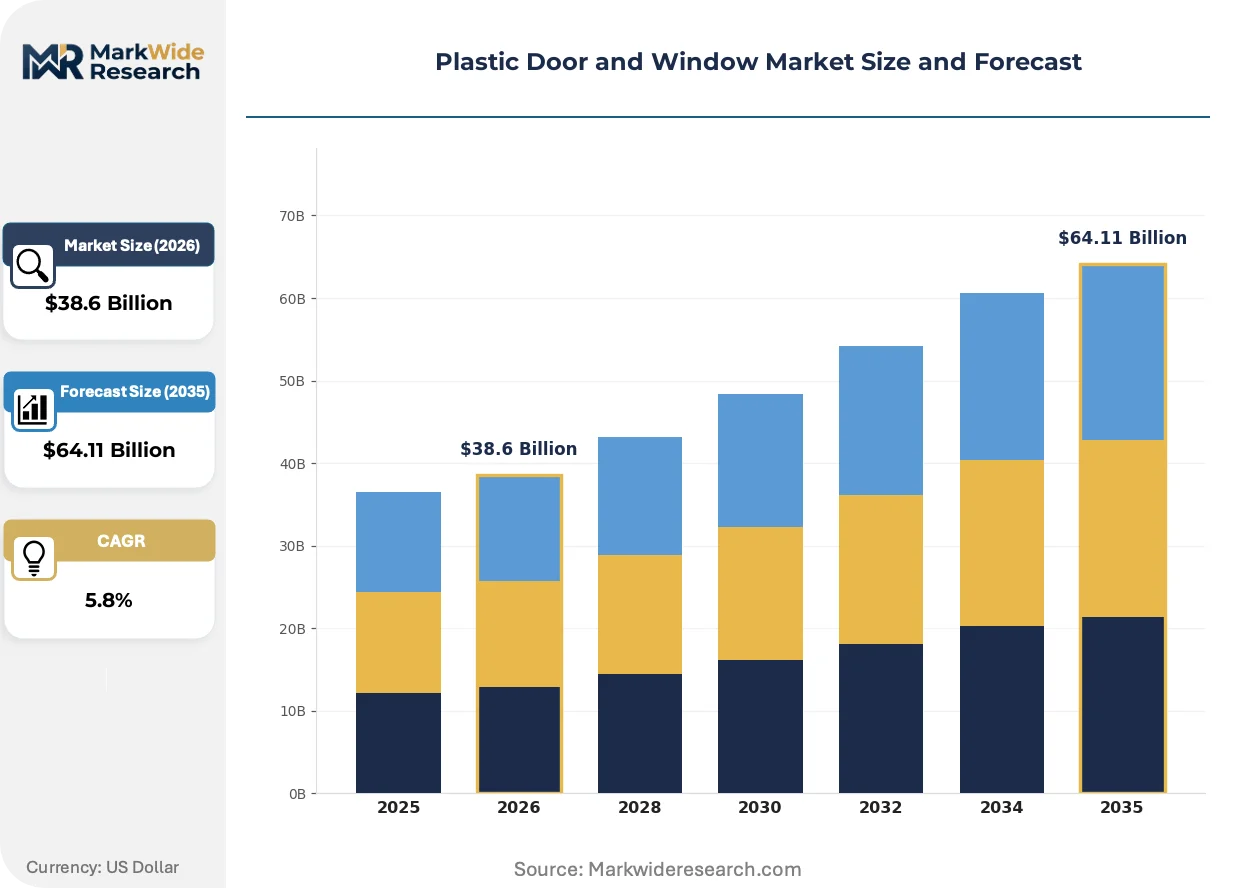
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Windows, Casement Windows, Awning Windows, Double-Hung Windows Material: uPVC, PVC, Fiberglass, Composite Application: Residential, Commercial, Industrial, Renovation End User: Homeowners, Builders, Architects, Contractors |
| Companies Covered | Deceuninck NV, Rehau AG + Co, Andersen Corporation, Veka AG, Aluplast GmbH, Pella Corporation, Schuco International KG, GEALAN, JELD-WEN, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Door and Window Market Emerging Trajectories
Material science advances and regulatory thermal thresholds are compressing traditional product lifecycles while opening premium tiers for high-performance composites and integrated glazing systems.
Multi-chamber uPVC extrusion is decomposing the cost-performance tradeoff that historically favored aluminum in mid-rise commercial specification. German and Austrian fabricators are adopting seven and eight-chamber geometries with foam-filled profiles to meet Passive House Institute criteria. This engineering trajectory is decomposing the aluminum premium in institutional and multifamily new construction across Northern Europe.
REACH chemical compliance is forcing reformulation of stabilizer packages and pigment systems across European supply chains. ECHA substance of very high concern listings for lead-based heat stabilizers are accelerating calcium-zinc and organotin transitions. Profile extruders serving France, Germany, and Benelux are qualifying alternative formulations 18-24 months ahead of sunset dates to maintain fabricator network loyalty.
Direct-to-homeowner digital channels are fragmenting traditional distributor-fabricator-retailer chains in replacement markets. Online configurators with photorealistic rendering and automated quoting are capturing lead generation in the United Kingdom and Australian residential renovation segments. Installer-matching platforms are compressing the sales-to-installation cycle from weeks to days in metropolitan markets.
Plastic Door and Window Market Segmentation
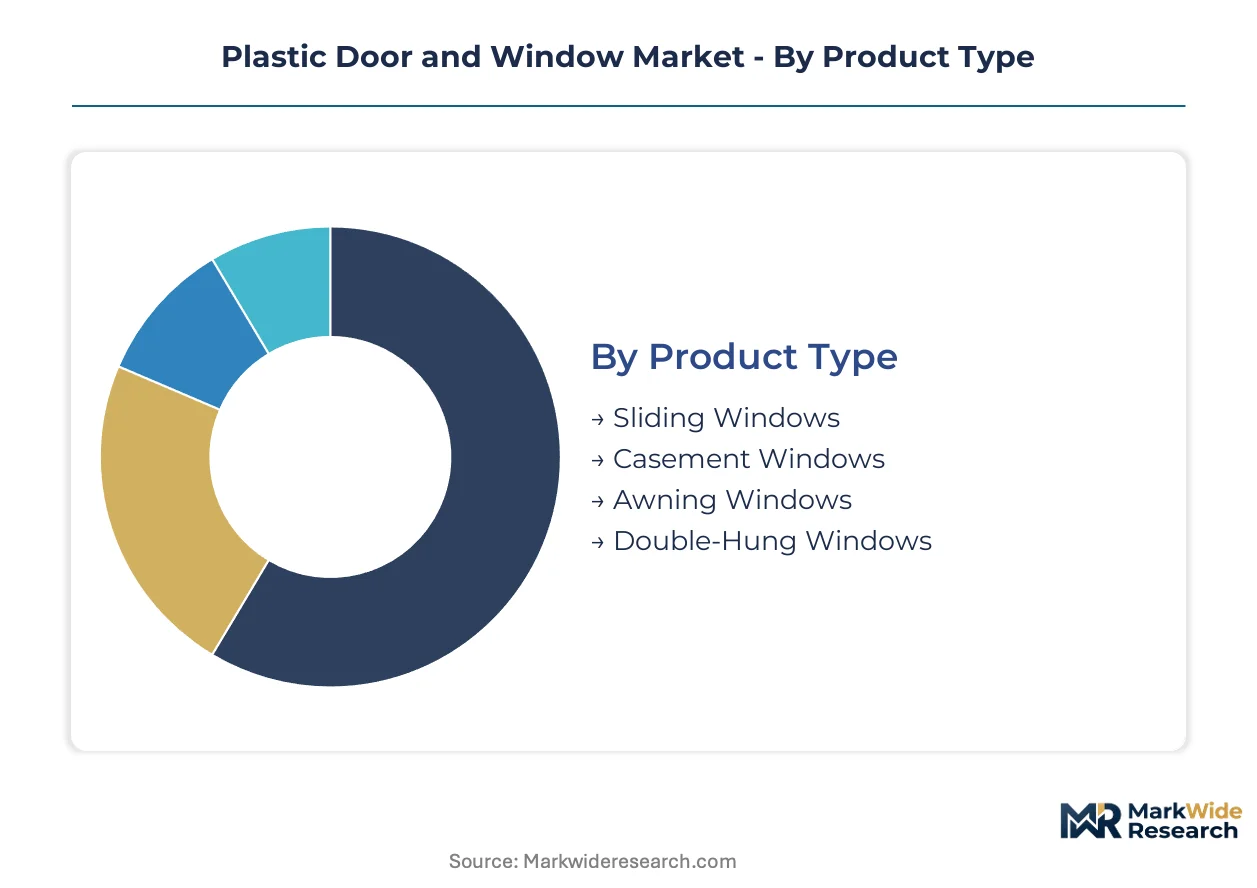
Segmentation in the plastic door and window market reveals how thermal performance thresholds, installation channel requirements, and material cost structures fragment demand across distinct specification tiers. Regulatory divergence between residential renovation and new construction channels forces extruders to maintain parallel product lines with different certification burdens and lead time expectations.
Product Type:
REACH compliance in Europe and evolving ENERGY STAR criteria in the United States are tightening thermal performance thresholds that favor specific operating geometries over others.
- Sliding Windows:Horizontal sash translation systems with tandem roller assemblies and interlocking meeting rails. Demand concentrates in Brazil and India's high-rise residential towers where space constraints eliminate swing clearance; municipal envelope efficiency codes in São Paulo and Mumbai are accelerating replacement of legacy aluminum sliders with multi-chamber uPVC equivalents.
- Casement Windows:Side-hinged sash systems with multi-point locking hardware and compression seals delivering superior air infiltration resistance. European renovation contractors in Germany and Poland specify these for Passive House retrofits where crank-operated hardware enables precise compression against bulb gaskets.
- Awning Windows:Top-hinged projection systems with rain-shedding geometry and limited opening angle for secure ventilation.
- Double-Hung Windows:Vertical sliding sash pairs with counterbalance mechanisms; dominant in North American replacement channels where historical architectural compatibility matters.
Sliding windows handle the majority of throughput; casement configurations are expanding most quickly on share as thermal codes tighten.
Material:
Cost tier differentiation separates commodity volume from premium specification, with feedstock volatility and recycling economics determining fabricator margin stability.
- uPVC:Unplasticized polyvinyl chloride with multi-chamber extrusion and steel reinforcement delivering cost-efficient thermal breaks. Demand clusters in European renovation supply chains where closed-loop regrind systems satisfy extended producer responsibility schemes in Germany and Benelux.
- PVC:Plasticized formulations with higher impact modifiers for tropical climates and coastal applications. Brazilian and Indian fabricators favor these for legacy housing stock modernization where dimensional tolerance under humidity cycling exceeds thermal performance priorities.
- Fiberglass:Pultruded glass-reinforced profiles with coefficient of thermal expansion matching glazing units. Coastal markets in Florida and Queensland specify these where salt-laden atmospheres degrade PVC dimensional stability within warranty periods.
- Composite:Hybrid systems combining uPVC exterior skins with fiberglass or aluminum structural cores. Premium replacement segments in California and Germany adopt these for high-performance residential retrofits where embodied-carbon accounting favors durable substrates.
uPVC commands the volume base; fiberglass composites are climbing the fastest as coastal corrosion resistance becomes a specification priority.
Application:
Customer type determines installation channel configuration, with renovation demand pulling fabrication networks toward custom dimension flexibility and certified fitter networks.
- Residential:Single-family and multifamily new construction and replacement. Volume concentrates in China's urban housing modernization where municipal governments enforce envelope efficiency codes in legacy residential towers.
- Commercial:Office, retail, and institutional specifications with fire-rated and structural load requirements. Thermally broken aluminum frames capture share here where uPVC mechanical limits constrain mid-rise applications.
- Industrial:Warehousing and manufacturing facilities with large-format fixed glazing and security-rated hardware. Limited penetration for plastic systems due to impact resistance specifications favoring steel or aluminum.
- Renovation:Replacement of legacy steel, aluminum, or wood-frame units in existing building stock. European channels dominate here with Deceuninck NV and Veka AG leveraging extrusion scale and fabricator network density.
Renovation handles the majority of throughput; residential new construction is gaining share fastest as urban housing stock modernizes in emerging economies.
End User:
Procurement authority and specification influence separate price-sensitive volume from margin-rich custom work, with digital channels fragmenting traditional distributor chains.
- Homeowners:Direct purchasers in replacement markets, increasingly reached through online configurators with photorealistic rendering. United Kingdom and Australian metropolitan markets show compressed sales-to-installation cycles through installer-matching platforms.
- Builders:Production homebuilders and multifamily developers purchasing at volume with standardized specifications. Cost efficiency and lead time reliability dominate procurement criteria over thermal performance differentiation.
- Architects:Specification authorities in commercial and institutional projects with Passive House or LEED certification requirements. German and Austrian fabricators cultivate these relationships through seven and eight-chamber profile geometries.
- Contractors:Installation and project management firms with certified fitter networks. Vocational pipeline gaps in France and Italy constrain renovation throughput despite strong demand.
Builders handle the majority of throughput; homeowners are expanding most quickly on share as direct-to-consumer digital channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extruders supply renovation-grade uPVC profiles to Polish and Czech fabricators, while Chinese manufacturers export fiberglass-reinforced systems to Australian coastal markets facing salt corrosion.
United States
Replacement contractors in Florida and California drive demand for corrosion-resistant fiberglass frames. EPA ENERGY STAR Version 7.0 mandates multi-chamber profiles with warm-edge spacers, effective 2023. Andersen Corporation and Pella Corporation anchor supply chains in the Upper Midwest fabrication cluster.
Germany
Passive House retrofits in Berlin and Hamburg accelerate specification of seven-chamber uPVC geometries. ECHA REACH compliance deadlines force calcium-zinc stabilizer transitions across Bavarian extrusion plants. Veka AG and Rehau AG dominate fabricator networks in the Rhine-Ruhr industrial corridor.
China
Municipal envelope efficiency codes in Shanghai and Shenzhen trigger replacement of legacy aluminum windows in residential towers. MIIT green building standards mandate U-value minimums for public housing retrofits. Yangtze River Delta fabricators concentrate pultruded fiberglass capacity for coastal high-rise export.
Brazil
Humidity-resistant PVC formulations gain share in São Paulo and Rio de Janeiro renovation channels. ANVISA building material certification aligns with municipal efficiency codes in legacy housing stock. Minas Gerais extruders serve the Southeast construction belt with tropical-grade profile systems.
India
Urban housing modernization in Mumbai and Delhi-NCR concentrates demand for sliding window configurations in high-rise towers. BIS thermal performance standards for fenestration products tighten compliance burdens on fabricators. Gujarat-based profile extruders supply the Western India construction corridor.
Plastic Door and Window Market Vendor Landscape
Player mix skews toward integrated extruders with captive fabrication networks. Market structure concentrates around European specialists with multi-decade fabricator relationships and North American premium replacement brands. Two strategic archetypes dominate: scale-driven profile extruders serving renovation supply chains, and performance-focused composite specialists capturing coastal corrosion applications. Competitive moves center on fabricator network consolidation and REACH-compliant formulation transitions ahead of regulatory deadlines.
Within the European integrated extruder tier, Deceuninck NV and Veka AG exemplify scale-driven positioning through dense fabricator networks. Andersen Corporation anchors the North American premium replacement segment. Rehau AG occupies a position bridging industrial automation expertise with fenestration systems. Aluplast GmbH and Schuco International KG sit within the German-speaking technical specification tier. GEALAN represents the mid-market fabricator supply archetype in Central European renovation channels.
| Leading Market Players |
|---|
| Deceuninck NV |
| Rehau AG + Co |
| Andersen Corporation |
| Veka AG |
| Aluplast GmbH |
| Pella Corporation |
| Schuco International KG |
| GEALAN |
| JELD-WEN, Inc. |
| Others |
Supply Flow & Price Mechanics
Fiberglass composite substitution for coastal uPVC applications simultaneously redraws supply geography toward pultrusion-capable plants in Florida and Queensland while compressing pricing premiums historically commanded by corrosion-resistant formulations. This material transition feeds back into extruder sourcing strategies as fabricators reassess inventory exposure to resin volatility.
Pricing Analysis
Three-chamber uPVC profiles, seven-chamber thermal-break geometries, and pultruded fiberglass systems occupy distinct pricing tiers based on thermal performance certification. Pricing stratifies across premium, standard, and economy tiers where ENERGY STAR Version 7.0 compliance and Passive House Institute certification command 15-25% premiums over baseline multi-chamber products. Cost compression in standard-grade uPVC is intensifying because Turkish and Chinese steel reinforcement suppliers face tariff friction, squeezing fabricator margins. Production homebuilders exhibit highest price sensitivity due to volume procurement and specification standardization, while architects specifying Passive House retrofits show lowest sensitivity to premium positioning.
Supply Chain Analysis
Strategic stockpiling of PVC resin and steel reinforcement inserts dominates over just-in-time preferences given ethylene feedstock volatility and galvanizing capacity concentration. Raw material sourcing draws from German and Austrian extrusion clusters for European renovation supply, Chinese Yangtze River Delta fabricators for fiberglass pultrusion, and Turkish rolling mills for galvanized steel inserts. Single-source vulnerability concentrates in steel reinforcement supply where Turkish mills serve 60% of European fabricator demand. Distribution runs through captive fabricator networks in Germany and Poland, independent regional assemblers in the United Kingdom, and direct-to-homeowner digital channels in Australian metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA ENERGY STAR Version 7.0 and ECHA REACH chemical compliance deadlines constitute a dual regulatory inflection compressing product lifecycles while opening premium tiers for reformulated profiles and certified fabricators.
For Market Incumbents: Consolidate fabricator network control through acquisition of independent regional assemblers in Poland and the United Kingdom to secure captive installation capacity. Accelerate calcium-zinc stabilizer qualification 18-24 months ahead of ECHA sunset dates to maintain supply chain loyalty against reformulation laggards. Vertical integration into closed-loop uPVC regrind systems defends margin position against resin price volatility. For New Entrants and Emerging Players: Passive House Institute component certification fast-tracks entry into German and Austrian renovation channels where specification authority concentrates with architects and energy consultants. Coastal corrosion applications in Florida and Queensland present the most penetrable white-space segment given warranty failure rates of standard uPVC in salt-laden atmospheres. Direct-to-homeowner digital configurators with automated quoting and installer-matching compress sales cycles in United Kingdom and Australian replacement markets. For Investors and Strategic Acquirers: ECHA REACH compliance deadlines reshape the acquisition landscape toward extruders with qualified alternative stabilizer formulations and dense fabricator networks. Five-to-ten-year viability favors integrated profile extruders with backward integration into compounding and captive recycling infrastructure. The signal to watch is IGCC and ift Rosenheim warm-edge spacer certification timelines extending 14-18 months, which will strand non-compliant product lines and create distressed acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Fabricator Network Consolidation | Captive installation capacity in Poland and the United Kingdom secures renovation channel access against distributor fragmentation. |
| REACH-Compliant Formulation Transition | Calcium-zinc and organotin stabilizer qualification ahead of ECHA deadlines maintains fabricator loyalty in Benelux and Germany. |
| Coastal Corrosion Product Line Expansion | Pultruded fiberglass capacity addition in Florida and Queensland captures premium replacement demand from salt-degraded uPVC warranties. |
| Direct-to-Consumer Digital Channel Buildout | Online configurators with photorealistic rendering compress sales-to-installation cycles in United Kingdom and Australian metropolitan markets. |
| Closed-Loop Regrind System Investment | In-house PVC recycling infrastructure lowers input costs and satisfies extended producer responsibility schemes in European waste frameworks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with profile extruder plant managers, window fabricator procurement leads, certified installer network heads, and regulatory affairs directors at REACH compliance consultancies; and secondary validation through customs and trade data, ECHA substance registry filings, ENERGY STAR certification databases, and SEC 10-K disclosures from listed building products companies. Bottom-up triangulation across fabricator throughput estimates and top-down reconciliation against construction activity indices anchored volume and value projections.
Across the analysis window, the forecasting framework modeled demand by product type (sliding, casement, awning, double-hung), material grade (uPVC, PVC, fiberglass, composite), application channel (residential new construction, renovation, commercial), and end-user procurement authority (homeowners, builders, architects, contractors). CAGRs derived from regression against housing stock age profiles, regulatory thermal threshold tightening schedules, and urbanization rates in emerging economies. Industry-specific inputs included ENERGY STAR Version 7.0 adoption curves and municipal envelope efficiency code enforcement intensity in Chinese tier-one cities.
Underlying assumptions cover steady-state resin price volatility, REACH compliance timeline adherence, and skilled installer pipeline development, with deviation risk concentrated in ethylene feedstock cost spikes and IGCC certification backlogs. Revision becomes warranted when ECHA accelerates substance of very high concern listings or when municipal efficiency code enforcement in China and Brazil crosses thresholds that trigger nonlinear replacement demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Fire Rated Duct Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
China UPVC Doors and Windows Market