
 Asia-Pacific Construction Adhesives Market | 2026-2036
Asia-Pacific Construction Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Construction Adhesives Market Outlook
Aftermarket service revenue for adhesive application systems is tilting toward technical consulting and on-site bonding audits. Henkel AG & Co. KGaA leverages its regional technical centers to anchor specification-driven sales in commercial glazing projects across Australia and Singapore. Sika AG competes through backward integration into silicone intermediates, sustaining margin capture in high-performance roofing installations. H.B. Fuller Company specializes in hot-melt formulations for prefabricated wall panel assembly, occupying a niche in Japanese modular construction supply chains.
Asia-Pacific construction adhesives comprise formulated bonding agents engineered from polyurethane, silicone, epoxy, or acrylic chemistries, typically cured through moisture, heat, or chemical reaction to achieve structural or semi-structural joints between building substrates. These materials bond dissimilar surfaces—concrete to steel, glass to aluminum framing, or engineered wood to insulation—under performance parameters spanning temperature resistance from minus forty to plus one hundred fifty degrees Celsius and tensile-shear strengths exceeding ten megapascals. Polyurethane adhesives dominate flooring applications across the region due to superior flexibility and moisture tolerance in tropical climates, while silicone segments command premium positioning in window sealing where thermal movement cycles stress lesser formulations. Water-based technology leads residential end-use adoption, though reactive systems are gaining fastest in infrastructure projects demanding accelerated cure schedules and extended durability warranties.
China's SAMR enforces GB standards limiting volatile organic compound content in interior construction materials, directly reformulating water-based adhesive demand profiles across manufacturing bases in Jiangsu and Guangdong. India's BIS certification mandates for structural bonding agents in public infrastructure create compliance barriers for uncertified imports, channeling procurement toward domestically tested suppliers. Australia's NCC energy efficiency provisions for commercial building envelopes amplify specification of high-performance silicone and hybrid sealants in facade assemblies. Stakeholders must monitor divergence between national certification regimes and emerging cross-border mutual recognition agreements that could reshape competitive access across Southeast Asian procurement networks.
Market Dynamics
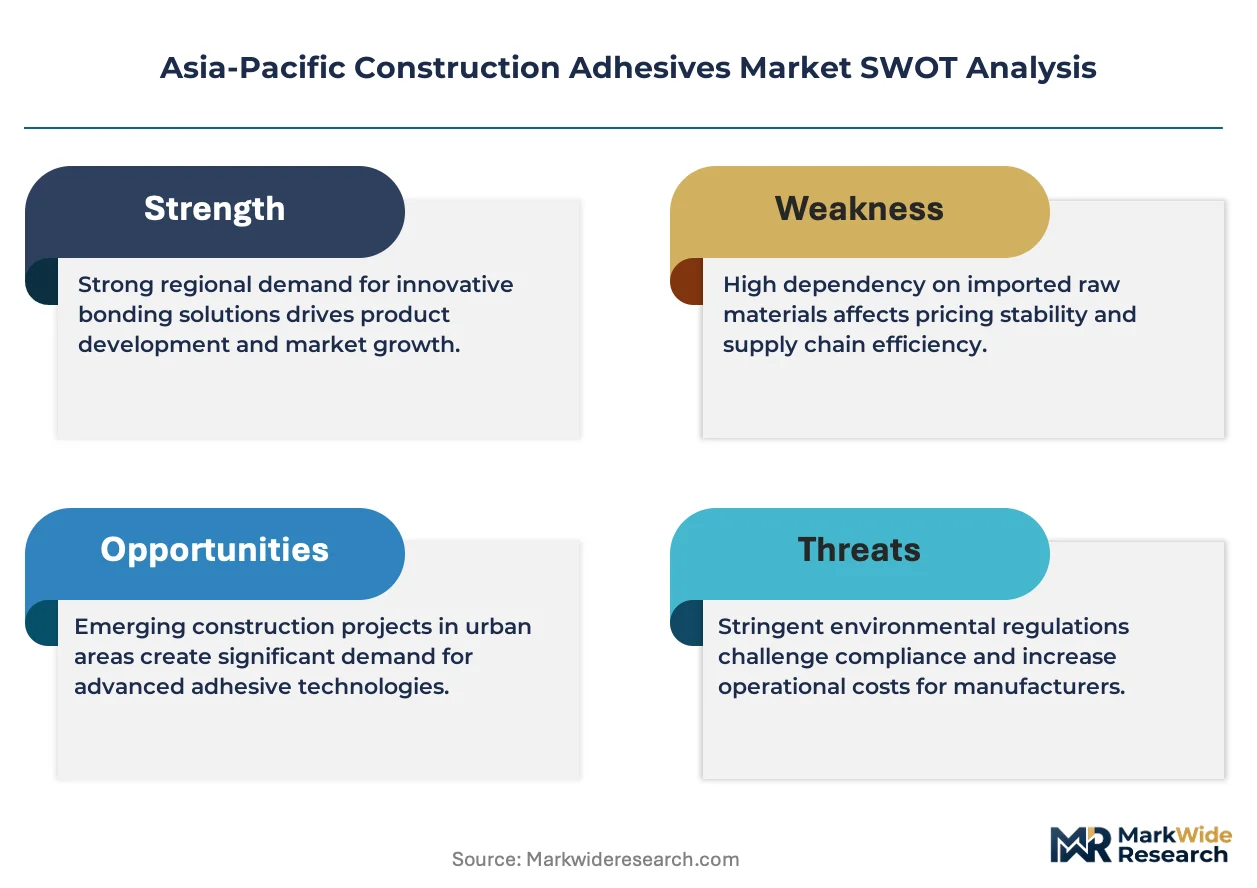
China's GB standards for low-VOC building materials are forcing reformulation across adhesive supply chains, compressing solvent-based capacity while expanding water-borne and reactive system investments in Jiangsu and Guangdong manufacturing clusters.
Growth Catalysts
- Prefabricated housing panels:Residential builders in India are scaling adhesive-intensive modular construction methods to accelerate project timelines and reduce on-site labor dependencies.
- GB standards enforcement:China's SAMR mandates on interior construction materials are redirecting procurement toward certified low-emission formulations across commercial and residential verticals.
- Infrastructure corridors:Southeast Asian governments are prioritizing bonded structural assemblies in transportation and energy projects linking Vietnam, Indonesia, and the Philippines.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and silicone intermediate costs fluctuate with crude oil and methanol pricing, compressing margin stability for formulated product manufacturers.
- Import certification barriers:India's BIS structural bonding mandates create compliance friction for uncertified foreign suppliers, limiting competitive access to public infrastructure procurement.
- Technical performance ceilings:Water-based acrylics face durability limitations in tropical high-humidity environments, restricting substitution potential in exterior structural applications.
Strategic Opportunities
- Philippines infrastructure buildout:The government's transportation and energy expansion programs are creating specification openings for high-performance epoxy and polyurethane systems in bridge and tunnel applications.
- Hybrid sealant convergence:Silane-modified polyurethane technology combines thermal movement tolerance with structural adhesion, opening facade assembly opportunities in Australia's NCC-compliant commercial envelopes.
- Technical consulting services:On-site bonding audits and specification support are emerging as high-margin revenue streams distinct from commodity adhesive sales.
Industry Challenges
- Application engineering talent scarcity:Qualified technicians capable of specifying cure schedules and substrate preparation protocols are concentrated in Japan and Australia, limiting service expansion.
- Multi-jurisdiction certification complexity:Divergent national standards across China, India, Australia, and Southeast Asian markets fragment product portfolios and extend registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Construction Adhesives Market |
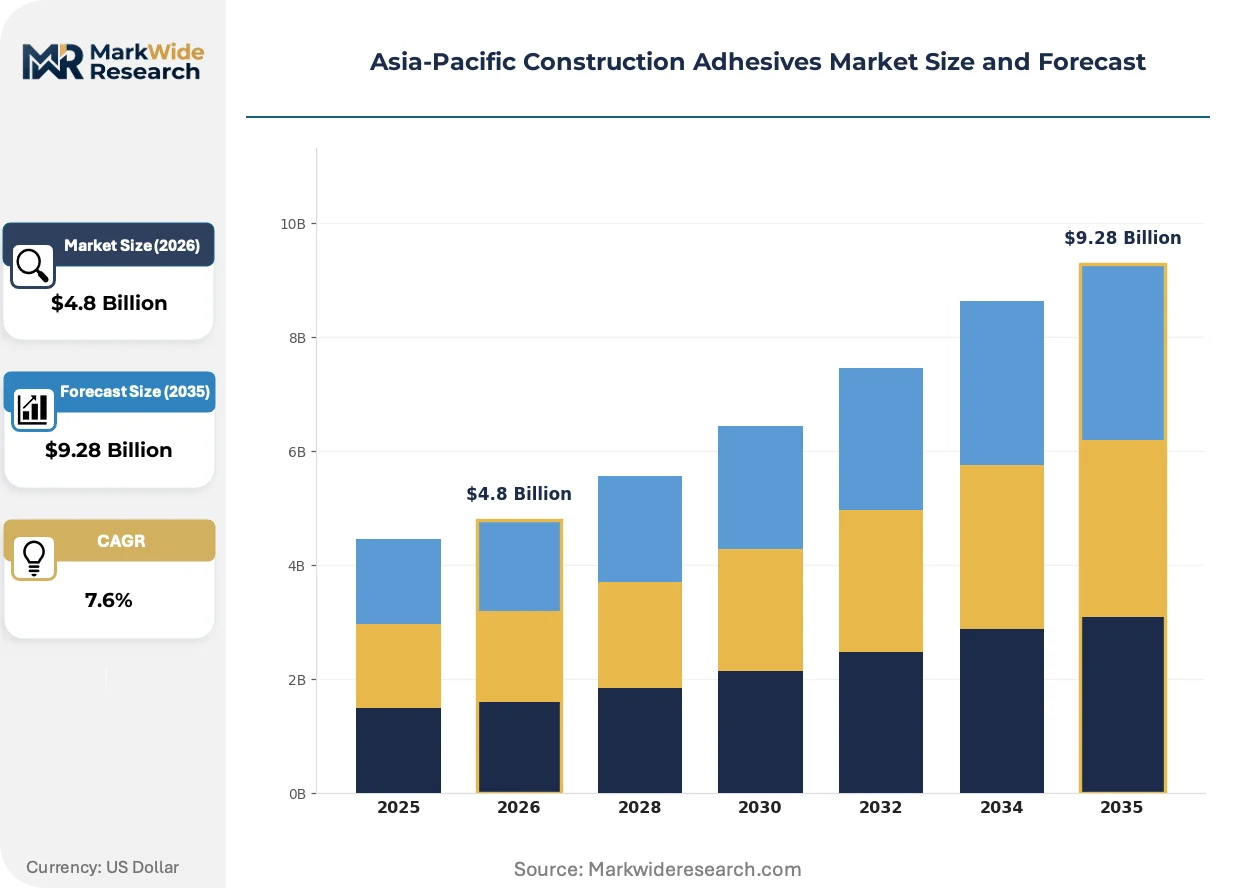
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Epoxy, Acrylic Application: Flooring, Wall Panels, Roofing, Windows End User: Residential, Commercial, Infrastructure, Industrial Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | Henkel AG & Co. KGaA, Arkema Group (Bostik), 3M, Huitian Adhesive, Pidilite Industries, H.B. Fuller Company, Sika AG, Kangda New Materials, Dow, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Construction Adhesives Market Strategic Shifts
Formulation chemistry and specification methodologies are converging around performance verification systems, with digital tools and regulatory compliance frameworks displacing traditional procurement patterns across the Asia-Pacific construction value chain.
Automated dispensing and cure-monitoring systems are digitizing quality assurance in prefabricated panel assembly. Japanese modular housing manufacturers are deploying sensor-integrated application equipment to capture real-time bond-line data. This capability is digitizing specification adherence, compressing warranty risk and enabling outcome-based contracting with general contractors.
Australia's NCC energy efficiency provisions for commercial building envelopes are mandating thermal performance verification in facade assemblies. The code's air-tightness requirements are elevating specification of high-performance silicone and hybrid sealants in curtainwall installations. Australian architects and facade engineers are responding by embedding adhesive performance criteria into design-stage digital models.
Buyers in Southeast Asian infrastructure projects are unbundling material supply from application supervision. Vietnamese and Indonesian contractors are separating adhesive procurement from technical service contracts, creating discrete vendor categories. This pattern is most visible in transportation infrastructure, where EPC firms now specify bonding agents independently of installation quality assurance.
Asia-Pacific Construction Adhesives Market Segmentation
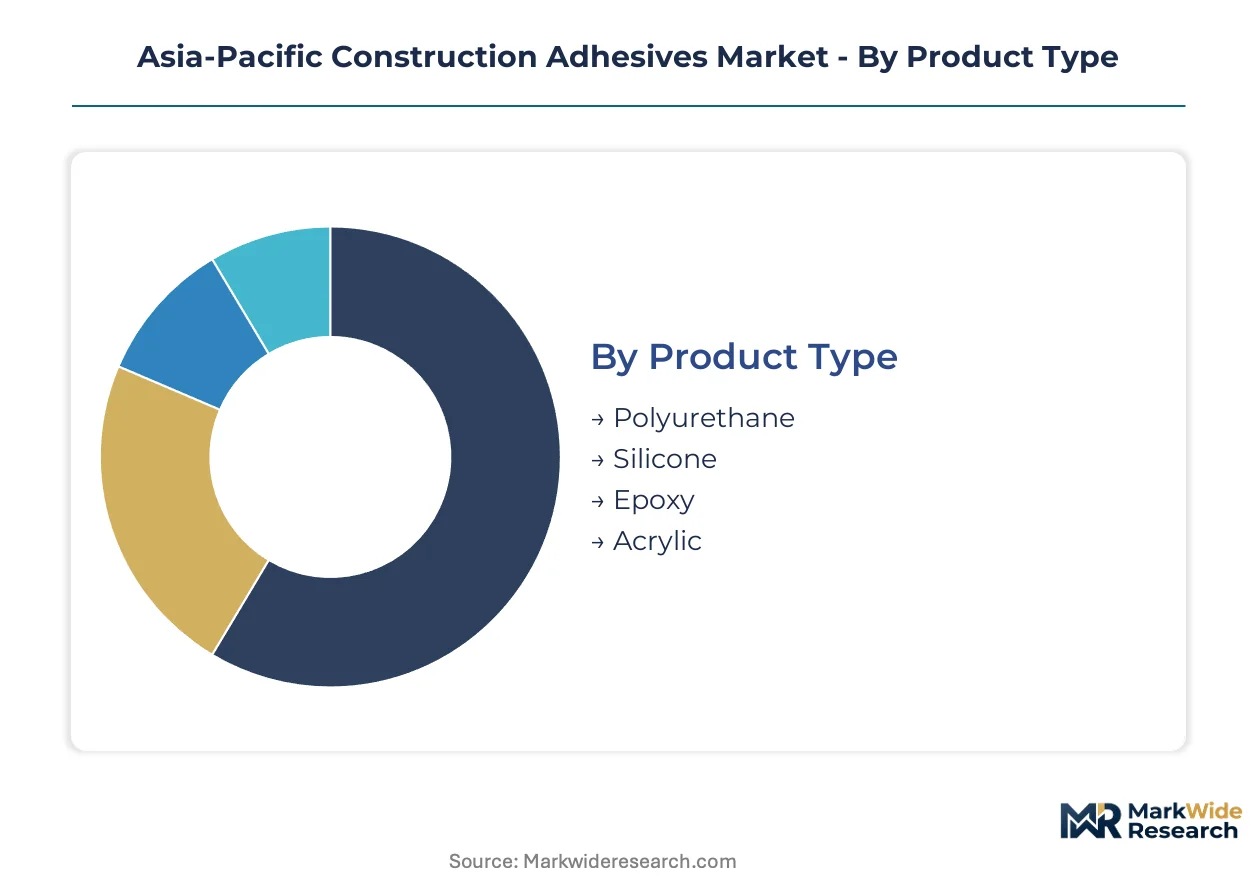
Construction adhesive purchasing in Asia-Pacific follows distinct technical and commercial logics across chemistry types, installation contexts, and cure technologies. Specification engineers weight performance parameters against certification requirements that vary sharply across national jurisdictions.
Product Type:
Chemistry selection maps directly to substrate compatibility, movement accommodation, and climatic exposure demands across tropical and temperate construction zones.
- Polyurethane:These moisture-curing systems deliver superior elongation and toughness for bonding dissimilar materials under thermal cycling. Demand concentrates in flooring installations across Southeast Asian infrastructure corridors where humidity tolerance and rapid green strength development compress project schedules.
- Silicone:Formulated from siloxane polymers with exceptional UV stability and temperature resistance from minus fifty to plus two hundred degrees Celsius. Premium positioning in Australia's NCC-compliant commercial glazing and curtainwall sealing reflects thermal movement engineering requirements that stress lesser chemistries.
- Epoxy:Two-part thermosetting systems offering structural load-bearing capacity exceeding fifteen megapascals tensile-shear strength.
- Acrylic:Water-borne and solvent-borne variants with rapid tack development for interior finishing applications.
Polyurethane commands the established base. The steepest expansion runs through silicone as facade performance standards tighten.
Application:
Installation context determines cure schedule requirements, equipment investment, and warranty exposure for bonding system suppliers.
- Flooring:Large-format tile and resilient surface bonding demands high green strength and moisture tolerance. Prefabricated housing panels in India are scaling adhesive-intensive subfloor assemblies that reduce on-site curing time.
- Roofing:Membrane attachment and flashing detail work requires sustained flexibility under ponding water and thermal shock. Sika AG's backward integration into silicone intermediates sustains margin capture in high-performance roofing specifications across Australian commercial builds.
- Wall Panels:Structural and non-structural bonding of engineered wood, insulation, and facade cladding.
- Windows:Perimeter sealing and structural glazing applications demanding air-tightness verification.
Flooring retains volume leadership. Roofing is gaining share fastest as building envelope energy codes proliferate.
End User:
Customer archetypes diverge in specification authority, procurement process complexity, and technical service requirements.
- Residential:Water-based acrylic and polyurethane systems dominate interior finishing and modular panel assembly. Japanese modular housing manufacturers deploy sensor-integrated dispensing equipment to digitize quality assurance.
- Infrastructure:Bridge deck waterproofing, tunnel segment bonding, and transportation structure repair demand epoxy and polyurethane systems with accelerated cure and extended durability warranties. Vietnam's transportation expansion programs are creating specification openings for certified structural bonding agents.
- Commercial:Curtainwall, interior fit-out, and facade assembly with performance verification requirements.
- Industrial:Manufacturing facility flooring, containment area lining, and equipment anchoring.
Residential absorbs the highest absolute volume. Infrastructure shows the most rapid specification upgrading as public procurement tightens certification requirements.
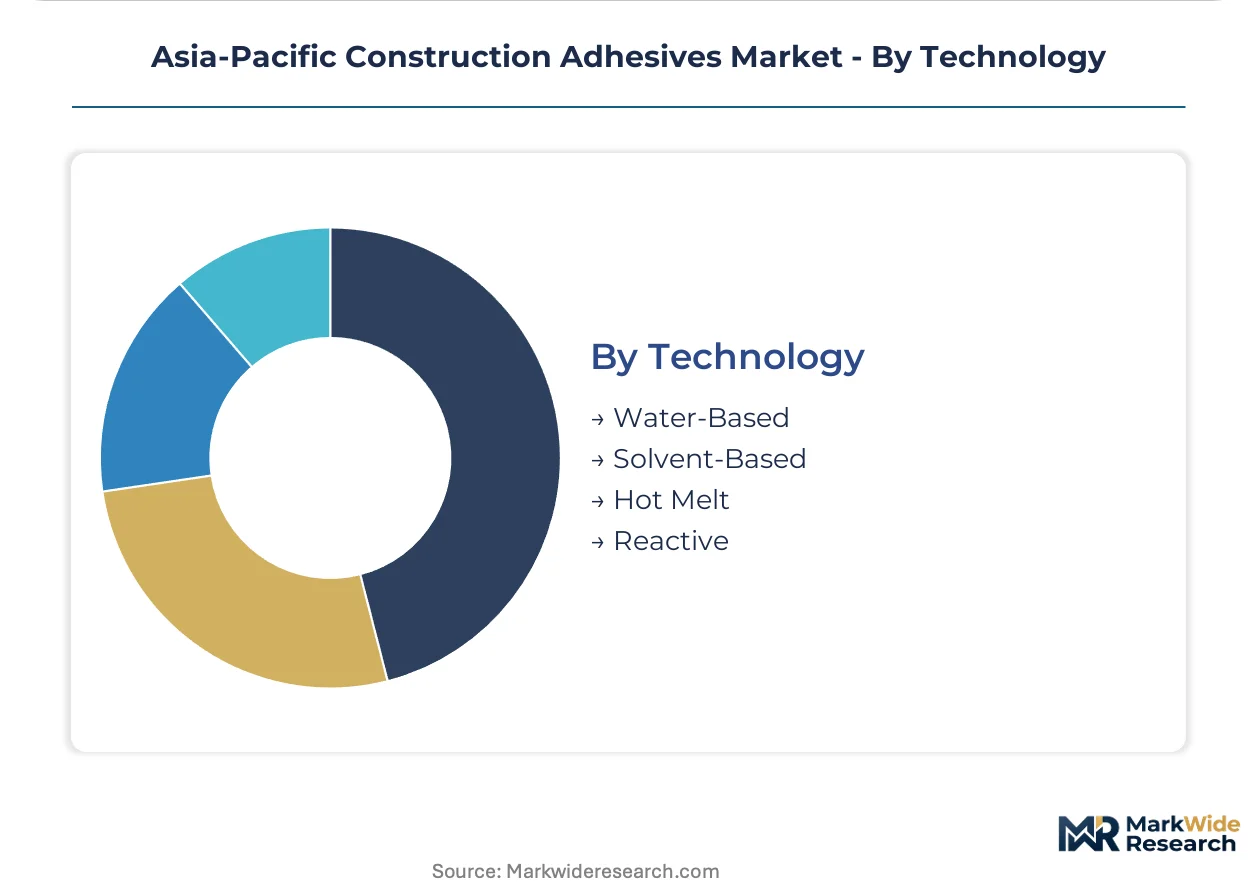
Technology:
Cure mechanism and carrier system determine emission profiles, application equipment needs, and performance envelopes under field conditions.
- Water-Based:Acrylic and polyurethane dispersions with low VOC content meeting China's GB standards for interior materials. SAMR enforcement is redirecting procurement toward certified low-emission formulations across Jiangsu and Guangdong manufacturing bases.
- Reactive:Two-part epoxy and polyurethane systems curing through chemical reaction rather than solvent evaporation. Infrastructure projects across Southeast Asia are specifying reactive systems for accelerated cure schedules and extended durability warranties that water-based alternatives cannot match.
- Solvent-Based:Rapid-drying systems facing capacity compression under tightening emission regulations.
- Hot Melt:Thermoplastic adhesives applied molten and solidifying on cooling for prefabricated panel assembly.
Water-based formulations hold the installed base. Reactive technology is climbing the fastest as infrastructure durability specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India consume construction adhesives at radically different intensities. Chinese demand concentrates in low-emission interior materials for high-rise commercial towers. Indian consumption tilts toward prefabricated housing acceleration and infrastructure bonding agents.
China
Commercial glazing and high-rise envelope construction dominate adhesive consumption. SAMR enforces GB standards capping volatile organic compounds in interior materials, forcing reformulation across Jiangsu and Guangdong manufacturing clusters. Guangdong province hosts the densest concentration of water-borne adhesive capacity expansion.
India
Residential builders deploy adhesive-intensive modular panels to compress construction timelines. BIS certification mandates for structural bonding agents in public infrastructure channel procurement toward domestically tested suppliers. Maharashtra and Gujarat house the fastest-growing prefabricated housing manufacturing corridors.
Australia
NCC energy efficiency provisions for commercial building envelopes amplify specification of high-performance silicone sealants in curtainwall assemblies. Sydney and Melbourne architects embed adhesive performance criteria into design-stage digital models. Victoria state leads facade engineering technical consulting revenue.
Vietnam
Transportation infrastructure expansion programs create specification openings for epoxy and polyurethane systems in bridge deck waterproofing. Government procurement separates material supply from technical service contracts, unbundling vendor categories. Ho Chi Minh City anchors bonded structural assembly demand.
Japan
Modular housing manufacturers deploy sensor-integrated dispensing equipment to digitize quality assurance in prefabricated panel assembly. METI standards govern structural adhesive performance in seismic-resistant construction. Kanto region technical centers concentrate application engineering talent.
Asia-Pacific Construction Adhesives Market Competitive Environment
Capability concentration sits with technical specialists; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: multinational adhesive formulators with regional technical centers, domestic champions with backward integration into intermediates, and application-technology specialists with digitized quality systems. Competitive moves center on strategic partnerships for specification anchoring and selective capacity expansion in low-emission formulation clusters.
Among European-headquartered formulators, Henkel AG & Co. KGaA and Sika AG exemplify contrasting archetypes. Henkel represents the technical-center-driven specification model. Sika occupies a position emphasizing captive supply of silicone intermediates. H.B. Fuller Company sits within the specialty hot-melt tier. Arkema Group through Bostik anchors the hybrid sealant convergence play. 3M exemplifies the diversified technology conglomerate with construction segment exposure.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Arkema Group (Bostik) |
| 3M |
| Huitian Adhesive |
| Pidilite Industries |
| H.B. Fuller Company |
| Sika AG |
| Kangda New Materials |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Guangdong's water-borne adhesive manufacturing clusters is compressing supplier pricing power while accelerating consolidation among regional formulators. SAMR's GB standard enforcement creates tiered compliance costs that stratify pricing across certified low-VOC formulations and legacy solvent-based capacity.
Pricing Analysis
Long-term offtake agreements dominate procurement for infrastructure-scale projects across Vietnam and Indonesia, while spot purchasing persists in residential finishing segments. Price differentiation rests on BIS certification tier and volume scale, with certified structural bonding agents commanding substantial premiums over uncertified imports. Pricing pressure stems from methanol feedstock volatility squeezing polyurethane margins. Residential builders exhibit highest price sensitivity; commercial glazing contractors prioritize performance verification over unit cost.
Supply Chain Analysis
Export-control regimes on advanced silicone polymer technology limit intermediate flows from select European and North American sources into Chinese manufacturing. Supply concentrates in China, Japan, and South Korea for formulated products, with siloxane monomer production anchored in Germany and the United States. Raw material dependencies include MDI, polyether polyols, and fumed silica. Single-source vulnerability runs through specialty epoxy hardener supply. Distribution feeds through regional technical centers with specification anchoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward specification-engineering consolidation as EPC firms and modular housing manufacturers centralize adhesive procurement decisions. Japanese and Australian technical consulting capabilities concentrate specification authority among fewer large-scale buyers.
For Market Incumbents: Pre-empt margin erosion in commodity water-based tiers by accelerating backward integration into polyether polyol production in Jiangsu clusters. Defend specification anchoring in Australia's NCC-compliant commercial envelopes through embedded technical consulting contracts that bundle material supply with on-site bonding audits.
For New Entrants and Emerging Players: Philippine infrastructure buildout represents the most penetrable white-space target, with transportation and energy expansion programs creating specification openings for certified epoxy systems. Target Vietnam's unbundled procurement model where material supply separates from technical service contracts. Enter through hybrid sealant technology bridging silicone thermal movement tolerance with polyurethane structural adhesion.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across reactive system manufacturing as infrastructure durability specifications harden. Long-term viability favors targets with captive intermediate supply and regional certification depth. Watch for BIS mutual recognition agreements with Southeast Asian regulators as the signal for competitive access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Sika AG's captive siloxane supply sustains margin capture in Australian roofing specifications. |
| Regional Technical Center Expansion | Henkel's Singapore and Sydney facilities anchor specification-driven sales in commercial glazing. |
| Sensor-Integrated Dispensing Deployment | Japanese modular housing manufacturers digitize quality assurance to compress warranty exposure. |
| Hybrid Sealant Technology Launch | Arkema's silane-modified polyurethane convergence opens Australia's NCC-compliant facade assembly. |
| Domestic Certification Investment | Indian suppliers channel public infrastructure procurement through BIS-tested structural bonding agents. |
Study Parameters
A standing panel of plant managers at Jiangsu and Guangdong manufacturing facilities, procurement leads at Indian modular housing developers, Australian facade engineering consultants, and Vietnamese EPC contractors provided ongoing calibration. Primary interviews combined with secondary validation from customs trade data, ACC regional reports, SAMR regulatory filings, and BIS certification databases. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across chemistry types and end-use segments.
Scenario-bracketing framed projections across the analysis window, with high and low cases reflecting regulatory enforcement intensity and infrastructure spending commitment. Segmentation dimensions modeled include chemistry type, cure technology, end-use vertical, and national certification regime. CAGRs derived from elasticity-adjusted demand curves incorporating construction output forecasts and adhesive intensity coefficients. Feedstock cost indices and regulatory timeline probabilities served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical conglomerates would shift outcomes. Material shifts in GB standard enforcement timelines or BIS mutual recognition progress would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
North America Decks Market