
 Space Frame Market | 2026-2036
Space Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Space Frame Market Analysis
Airport terminal developers is rotating toward modular space frame systems for expansive column-free concourses. Xuzhou LF Engineering & Construction Co leverages integrated fabrication yards in Jiangsu province to dominate domestic aviation infrastructure bids. Lindner Group anchors European premium positioning through precision-engineered aluminum node systems for cultural venues. DSI Spaceframes specializes in geodesic dome enclosures for bulk storage and industrial process buildings across North American utility clients.
A space frame is a three-dimensional structural system assembled from linear members connected at nodal points, typically achieving spans exceeding 40 meters with dead-to-live load ratios optimized for lightweight performance. The primary commercial purpose is to enclose large volumes without intermediate columns, serving arenas, hangars, and assembly halls where uninterrupted floor plates command premium rents. Steel space frames currently occupy the largest material share due to cost predictability and established welding protocols, while aluminum variants capture margin pools in corrosive environments and transportable event structures. Trussed frame configurations lead industrial applications for their load-distribution efficiency, whereas balloon frame systems penetrate temporary event infrastructure for rapid deployment cycles.
ISO 1090 execution class standards and Eurocode 3 design rules govern European structural steelwork certification, compelling fabricators to maintain factory production control systems that filter smaller competitors from public tender pools. China's SAMR enforces GB 50017 steel design codes and welding procedure qualifications that raise entry barriers for uncertified workshops serving stadium and convention center projects. India's BIS mandates IS 800 general construction standards with local material traceability that shapes procurement decisions for domestic arena developers. Stakeholders must monitor evolving carbon accounting requirements embedded in structural steel Environmental Product Declarations, as embodied emissions thresholds increasingly determine specification eligibility for publicly funded long-span buildings.
Market Dynamics
Carbon accounting mandates embedded in public procurement rules are compressing specification eligibility for structural steel space frames, forcing fabricators to requalify supply chains around Environmental Product Declaration thresholds.
Growth Catalysts
- Saudi Arabia's giga-project pipeline:Neom, Qiddiya, and Red Sea developments sustain large-scale orders for custom space frame enclosures across entertainment and hospitality venues.
- GB 50017 seismic code updates:China's tightened welding procedure qualifications filter uncertified workshops from stadium and convention center tender pools, consolidating demand among qualified fabricators.
- Modular airport terminal construction:Aviation infrastructure developers are rotating toward prefabricated space frame systems for column-free concourses exceeding 40-meter spans.
Market Restraints
- Structural steel price volatility:Scrap metal and hot-rolled coil input costs fluctuate with energy markets, compressing fabrication margins on fixed-price public contracts.
- Jiangsu province supply concentration:Integrated fabrication yards in Xuzhou and surrounding clusters control domestic Chinese aviation bids, creating geographic single-source risk for international developers.
- Balloon frame substitution:Temporary event infrastructure increasingly deploys rapid-deployment tension membrane systems that bypass permanent steel or aluminum node assemblies.
Strategic Opportunities
- India's PLI scheme for construction equipment:Domestic material traceability mandates under BIS IS 800 standards create procurement preference windows for local space frame fabricators serving arena developers.
- Geodesic dome bulk storage:North American utility clients are expanding procurement of aluminum node dome enclosures for industrial process buildings and material stockpiles.
- EU Green Deal embodied emissions thresholds:CSRD-aligned carbon accounting in publicly funded long-span buildings rewards fabricators with verified Environmental Product Declarations.
Industry Challenges
- Welding certification bottlenecks:ISO 1090 execution class compliance and Eurocode 3 factory production control systems require 12-18 month qualification timelines that filter smaller competitors from tender pools.
- Seismic zone engineering capacity:Specialized structural analysis for high-severity zones demands finite element modeling expertise that concentrates among a limited pool of licensed engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Frame Market |
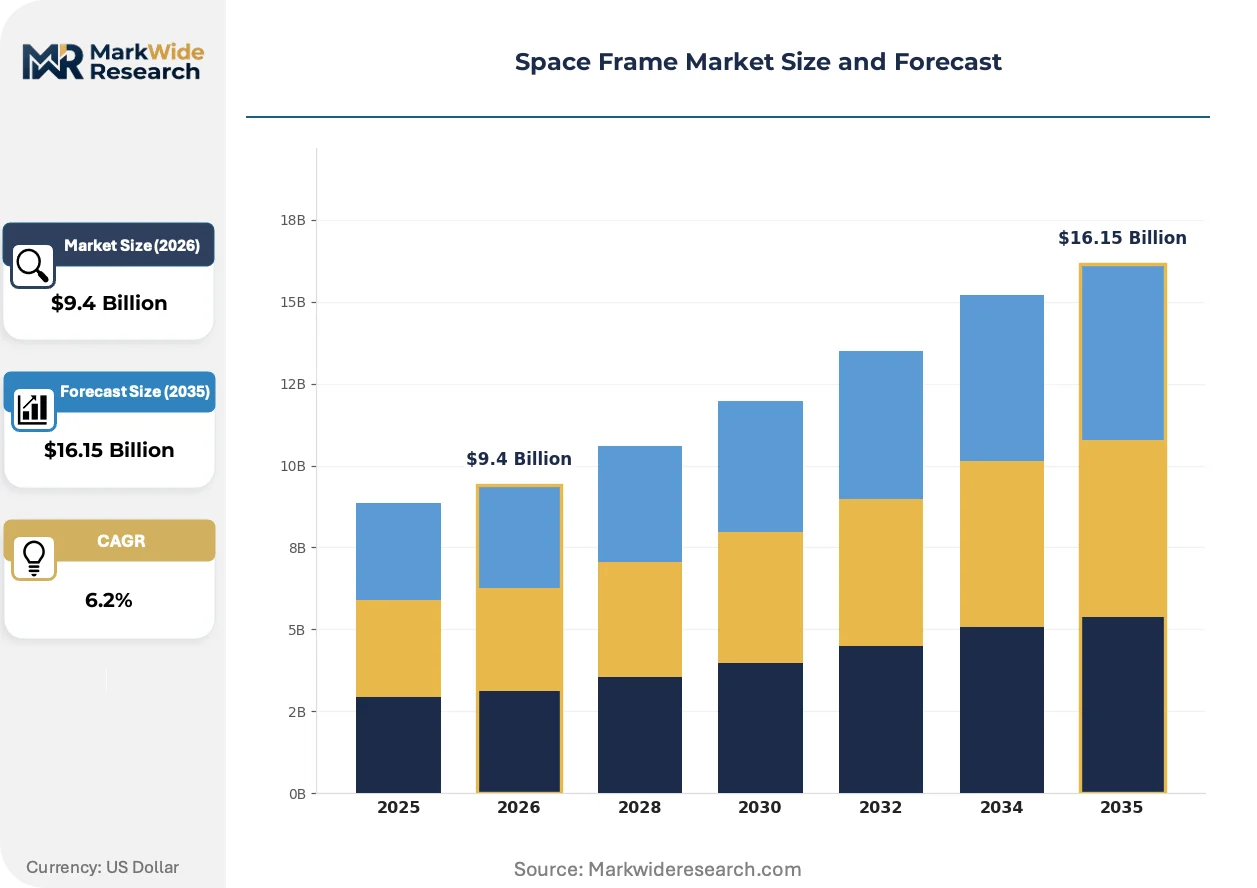
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Frame, O Frame, Ladder Frame, Trussed Frame End User: Construction, Aerospace, Automotive, Events Material: Aluminum, Steel, Composite, Others Application: Buildings, Aircraft, Vehicles, Stages |
| Companies Covered | Xuzhou LF Engineering & Construction Co, Delta Structures, Inc, DSI Spaceframes, Lindner Group, Zhejiang Southeast Space Frame Co., Ltd, Hindustan Alcox Limited, Triocon Space Frame Technologies Pvt, Ltd, USKON Space Frame System Construction Industry and Commerce Co. Inc, CST Industries, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Frame Market Emerging Trajectories
Digital fabrication workflows and regulatory carbon accounting are compressing traditional procurement cycles while expanding the addressable market for lightweight long-span enclosures.
Parametric design-to-fabrication software is decomposing conventional engineering handoffs between architects and steel contractors. Airport terminal developers in the Middle East and East Asia are adopting these tools for complex curved roof geometries. The technology is decomposing the traditional separation between design intent and shop-floor execution, enabling direct file-to-fabrication workflows that compress project timelines.
CSRD corporate sustainability reporting requirements and EU Green Deal procurement guidelines are mandating embodied carbon disclosure for structural steelwork. Public tender pools in Germany, France, and the Netherlands now disqualify bids lacking verified Environmental Product Declarations. Premium cultural venue projects are responding by specifying aluminum node systems with lower cradle-to-gate emissions profiles.
Fixed-price engineering-procurement-construction contracts are displacing traditional cost-plus arrangements in Middle Eastern giga-projects. Saudi developers are transferring fabrication risk to contractors while retaining design control, compressing supplier margins. This contracting model is most visible in entertainment and hospitality verticals where speed-to-operation dominates capital deployment decisions.
Space Frame Market Segmentation
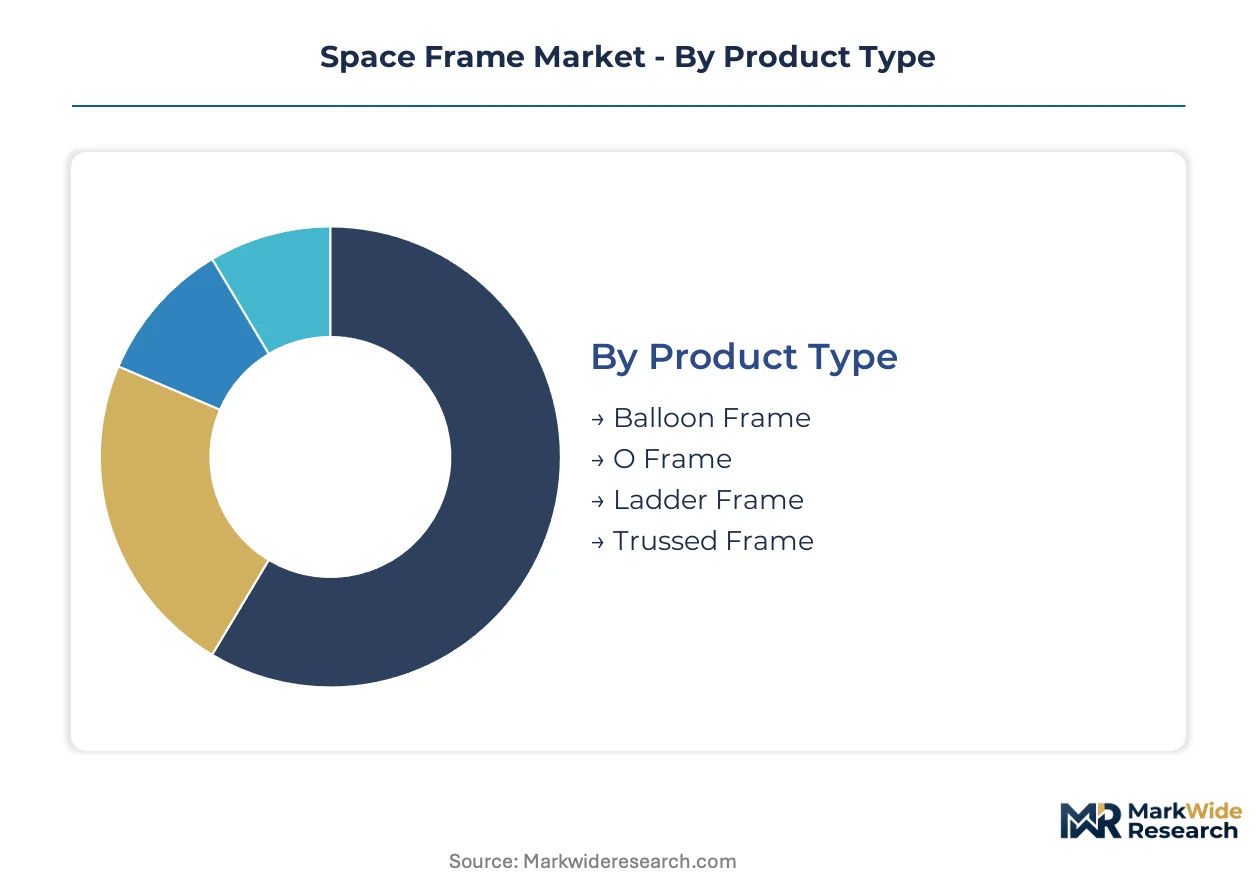
Space frame procurement patterns diverge sharply across structural typologies and end-use verticals. Specification engineers prioritize span capability, seismic performance, and node connection complexity when aligning product categories to project requirements.
Product Type:
Margin pools concentrate in long-span permanent installations where engineering certification commands premium pricing over temporary deployment systems.
- Trussed Frame:Triangulated member configurations distribute concentrated loads across multiple nodal points, achieving spans exceeding 60 meters with optimized dead-to-live load ratios. Stadium developers in Saudi Arabia specify these systems for Neom entertainment venues where uninterrupted sightlines drive procurement decisions.
- Balloon Frame:Rapid-assembly modular systems deploy without permanent foundations, serving exhibition centers and temporary event infrastructure where speed-to-operation outweighs structural permanence. Middle Eastern hospitality developers rotate toward these for pop-up pavilions at Red Sea giga-projects.
- O Frame:Circular ring configurations provide torsional rigidity for rotational equipment mounting and specialized industrial enclosures.
- Ladder Frame:Parallel chord assemblies suit bridge walkways and elevated maintenance platforms where bidirectional loading is minimal.
The dominant share belongs to Trussed Frame, while Balloon Frame is closing the gap fastest.
End User:
Construction verticals absorb the majority of fabricated tonnage, though aerospace qualification protocols sustain the highest per-kilogram value capture.
- Construction:Arena and convention center developers drive procurement volume through long-span roof specifications exceeding 40-meter clear spans. China's GB 50017 seismic code updates filter uncertified fabricators from stadium tender pools, consolidating demand among qualified suppliers.
- Aerospace:Aircraft hangar systems demand precision-tolerance node connections and fatigue-resistant aluminum alloys. Airport terminal developers in East Asia specify these for column-free concourses where modular prefabrication compresses construction schedules.
- Automotive:Assembly line enclosures and paint shop structures require corrosion-resistant coatings and rapid reconfiguration capability.
- Events:Temporary stage roofing and festival infrastructure prioritizes transportability and tool-free assembly cycles.
Construction commands the largest revenue pool, with Aerospace expanding most quickly on aviation infrastructure buildouts.
Material:
Steel maintains cost predictability for fixed-price public contracts, while aluminum captures margin in corrosive environments and transportable structures.
- Steel:Hot-rolled and hollow structural sections dominate permanent installations where welding procedure qualifications under ISO 1090 execution classes govern fabrication eligibility. European public tenders now embed CSRD-aligned carbon accounting that favors suppliers with verified Environmental Product Declarations.
- Aluminum:Lightweight extruded node systems serve coastal arenas and aircraft hangars where corrosion resistance and cradle-to-gate emissions profiles influence specification. Lindner Group anchors European premium positioning through precision-engineered aluminum nodes for cultural venues.
- Composite:Fiber-reinforced polymer systems penetrate radar-transparent enclosures and electromagnetic shielding applications.
- Others:Timber and hybrid configurations address niche sustainability mandates in Nordic public procurement.
Steel retains volume leadership, though aluminum is gaining share fastest on carbon accounting preferences.
Application:
Buildings applications concentrate fabrication capacity in integrated Jiangsu province yards, while aircraft specifications demand specialized engineering capacity.
- Buildings:Sports arenas, exhibition centers, and airport terminals constitute the core demand pool. Xuzhou LF Engineering leverages domestic fabrication integration to dominate Chinese aviation infrastructure bids.
- Aircraft:Hangar and maintenance facility specifications require wide-span clearances and aircraft tail clearance geometries.
- Vehicles:Bus and rail depot enclosures prioritize rapid door aperture configurations and ventilation integration.
- Stages:Concert and festival roofing systems emphasize modularity and wind-load certification for temporary occupancy.
Buildings holds the dominant position, with Aircraft climbing the fastest on terminal modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Neom giga-project pipeline underwrites Saudi Arabia's central role in space frame demand, while China's Jiangsu fabrication clusters and Germany's precision engineering centers anchor supply-side capacity across three continents.
Saudi Arabia
Neom, Qiddiya, and Red Sea entertainment venues sustain large-scale orders for custom space frame enclosures exceeding 40-meter spans. SFDA building codes and giga-project procurement guidelines mandate seismic-resistant node connections for hospitality structures. Riyadh-based project offices coordinate fabrication contracts with Chinese and European suppliers for speed-to-operation delivery.
China
Aviation infrastructure developers in Beijing and Shanghai specify modular space frame systems for column-free terminal concourses. SAMR enforces GB 50017 seismic code updates that filter uncertified workshops from stadium tender pools. Xuzhou LF Engineering leverages integrated fabrication yards in Jiangsu province to dominate domestic aviation bids and Middle East export contracts.
Germany
Cultural venue developers in Munich and Berlin specify precision-engineered aluminum node systems for premium long-span roofs. Eurocode 3 design rules and ISO 1090 execution class standards govern structural steelwork certification eligibility. Lindner Group anchors European premium positioning through factory production control systems that satisfy public tender requirements.
United States
North American utility clients expand procurement of geodesic dome enclosures for bulk storage and industrial process buildings. FAA airport standards and local seismic codes shape hangar and terminal specifications across California and Texas. DSI Spaceframes specializes in aluminum node dome systems serving material stockpile and energy sector clients.
India
Arena developers in Maharashtra and Karnataka drive procurement volume for sports infrastructure with clear span requirements exceeding 50 meters. BIS mandates IS 800 general construction standards with local material traceability that shapes domestic procurement decisions. Hindustan Alcox and Triocon Space Frame Technologies occupy positions serving stadium and convention center projects under PLI scheme preferences.
Space Frame Market Vendor Landscape
Concentration sits with integrated fabrication specialists and precision node engineers rather than generalist steel contractors. The vendor base stratifies across three tiers: domestic champions with captive Jiangsu yards, European precision engineers with aluminum specialization, and regional project fabricators serving single-country markets. Two dominant competitive moves are reshaping positioning: backward integration into hollow structural section rolling mills, and technology licensing partnerships for parametric design-to-fabrication software.
Among Chinese fabricators, Xuzhou LF Engineering & Construction Co. and Zhejiang Southeast Space Frame Co., Ltd. exemplify the integrated-yard archetype with domestic aviation and Middle East export concentration. Lindner Group GmbH and DSI Spaceframes, Inc. represent the precision-engineering tier with aluminum node specialization for cultural venues and industrial domes respectively. Delta Structures, Inc. and CST Industries, Inc. occupy positions in the North American project-fabricator segment serving utility and bulk storage verticals.
| Leading Market Players |
|---|
| Xuzhou LF Engineering & Construction Co |
| Delta Structures, Inc |
| DSI Spaceframes |
| Lindner Group |
| Zhejiang Southeast Space Frame Co., Ltd |
| Hindustan Alcox Limited |
| Triocon Space Frame Technologies Pvt, Ltd |
| USKON Space Frame System Construction Industry and Commerce Co. Inc |
| CST Industries, Inc |
| Others |
Supply Flow & Price Mechanics
ISO 1090 execution class standards gate both fabrication eligibility and price tiering simultaneously, compressing uncertified workshops into commodity tiers while rewarding factory production control systems with premium positioning on European public tenders. GB 50017 seismic code updates in China replicate this filtering mechanism, consolidating procurement among qualified suppliers who capture margin pools on stadium and convention center contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and project complexity. Premium tiers attach to aluminum node systems for cultural venues with Eurocode 3 compliance, while standard tiers serve steel trussed frames for aviation infrastructure under fixed-price EPC contracts. Cost compression in the economy tier intensifies because balloon frame substitutes and tension membrane systems erode pricing power for temporary deployment. Public sector buyers in Saudi Arabia exhibit lowest price sensitivity on giga-project timelines, whereas Indian arena developers under PLI scheme preferences demonstrate highest sensitivity to landed cost differentials.
Supply Chain Analysis
China and Germany anchor fabricated space frame production, with Jiangsu province yards supplying aviation infrastructure and precision engineering centers serving European cultural venues. Raw material draws from hot-rolled coil mills in Hebei, aluminum extrusion facilities in Bavaria, and hollow structural section rolling in the American Midwest. Single-source vulnerability concentrates in Xuzhou fabrication clusters, where integrated yards control domestic Chinese bids and Middle East export contracts. Distribution runs through engineering-procurement-construction contractors on fixed-price arrangements, transferring fabrication risk while retaining design control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated aviation infrastructure developers and giga-project procurement offices, fragmenting the fabricator base into tiered qualification pools. This concentration rewards backward-integrated suppliers with captive fabrication capacity.
For Market Incumbents: Compound factory production control investments to defend ISO 1090 execution class positioning against emerging Chinese yards seeking European certification. Anchor capacity in Jiangsu province clusters to maintain cost advantage on Middle East exports, while deepening aluminum node engineering expertise to capture CSRD-aligned carbon accounting premiums on German cultural tenders. For New Entrants and Emerging Players: Lead with geodesic dome specialization for North American utility bulk storage, where DSI Spaceframes has demonstrated aluminum node viability without competing directly on aviation infrastructure scale. Target Indian arena developers under BIS IS 800 traceability mandates, offering domestic material sourcing to satisfy PLI scheme procurement preferences. For Investors and Strategic Acquirers: EU Green Deal embodied emissions thresholds reshape the acquisition landscape toward fabricators with verified Environmental Product Declarations and parametric design-to-fabrication software partnerships. Long-term viability centers on suppliers who bridge carbon accounting compliance with digital workflow integration. Watch for CSRD enforcement acceleration in German, French, and Dutch public tender pools as the inflection signal for premium positioning capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hollow Structural Section Rolling | Captive steel supply secures margin stability against hot-rolled coil volatility for fixed-price contracts. |
| Parametric Design-to-Fabrication Software Licensing | Direct file-to-fabrication workflows compress project timelines for Saudi giga-project speed-to-operation demands. |
| Environmental Product Declaration Certification | Verified EPDs unlock CSRD-aligned public tender eligibility across German and Dutch long-span building procurement. |
| Aluminum Node System Capacity Expansion | Lower cradle-to-gate emissions profiles capture premium positioning on coastal arenas and cultural venues. |
| Seismic Zone Engineering Partnership | Finite element modeling expertise concentrates among limited licensed engineers for high-severity zone contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the space frame value chain, including stadium procurement directors, aviation infrastructure project managers, structural steel fabrication plant managers, and EPC contract officers. Secondary validation drew from GB 50017 code filings, SAMR factory certification registries, Eurocode 3 compliance databases, and customs records of hollow structural section trade flows. Bottom-up project pipeline aggregation triangulated against top-down construction spending forecasts to anchor volume estimates.
Across the projection horizon, the analytical framework modeled space frame demand by structural typology, material composition, end-use vertical, and regional regulatory cluster. CAGRs were derived from segment-level growth differentials weighted by procurement volume concentration. Forecast inputs incorporated Saudi giga-project commitment schedules, Chinese aviation infrastructure capex cycles, and EU Green Deal procurement guideline implementation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained giga-project execution, continued seismic code tightening, or stable aluminum-steel price spreads would require recalibration. Forecasts reflect documented assumptions about certification timeline completion and carbon accounting enforcement intensity. Recalibration cycles align with material shifts in public procurement rule amendments and raw material input cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Suborbital Space Tourism Market
Space
India Aviation, Defense, and Space Market
Space
Rocket Launchpad Market
Space
Space Ground System Market
Space
Asia-Pacific Space Logistics Market
Space
Europe Space Electronics Market
Space
Astronaut Spacesuit Market
Space
Space-Based Smart Sensors Market
Space
Canada Space Electronics Market
Space
Space on Board Computing Platform Market
Space
Spain Space Electronics Market
Space
Space in Orbit Refueling Market
Space
Space Oscillator Market
Space
Spacecraft Market
Space
Mexico Space Electronics Market
Space
Space As a Service Market