
 Space Technology (Spacetech) Market | 2026-2036
Space Technology (Spacetech) Market Size, Share, and Industry Trends Forecast 2026-2036
Space Technology (Spacetech) Market Analytics
Aerospace engineering talent pipelines is collapsing across legacy defense hubs, forcing incumbents to restructure recruitment. Lockheed Martin Corporation sustains classified satellite production through captive apprenticeship programs in Colorado and California. SpaceX dominates commercial launch cadence via vertical manufacturing of Merlin engines in Hawthorne. Northrop Grumman Corporation anchors national security space architecture through specialized payload integration at its Redondo Beach facilities.
Space technology encompasses the design, manufacture, and operation of systems that function in orbital or sub-orbital environments, including spacecraft with thermal protection rated for atmospheric re-entry above 1,650 degrees Celsius and propulsion systems delivering specific impulse exceeding 300 seconds in vacuum. Its primary commercial purpose is to enable telecommunications relay, geospatial intelligence, and autonomous navigation for terrestrial industries. Satellites command the largest revenue pool within product type segments, driven by constellation replenishment cycles for low-Earth orbit broadband networks. Propulsion systems within technology segments attract concentrated R&D investment as methane-fueled staged-combustion engines displace legacy kerosene architectures. Earth observation within application segments generates recurring government demand through weather monitoring and maritime surveillance contracts.
FAA launch licensing governs U.S. commercial orbital operations, while the FCC coordinates spectrum allocation for satellite constellations under Part 25 rules; both agencies are expanding environmental review requirements that extend pre-mission approval timelines. The EU Space Surveillance and Tracking framework imposes debris mitigation standards on operators accessing European ground infrastructure. Stakeholders must monitor how ITAR export controls and emerging national security space classifications reshape cross-border component sourcing before committing to multi-year manufacturing contracts.
Market Dynamics
Reusable launch vehicle maturation is compressing cost structures across orbital service tiers, forcing legacy expendable architectures into niche payload categories. This technological inflection redistributes capital toward vertical manufacturing and away from distributed supplier networks.
Growth Catalysts
- Methane-fueled staged-combustion engines:Higher specific impulse ratings above 300 seconds in vacuum enable heavier payload fractions per launch. Operators in the United States are retrofitting test stands to accommodate full-flow cycle validation.
- FAA Part 450 streamlined licensing:Consolidated safety approvals for reusable systems reduce pre-mission administrative timelines. Commercial operators gain flight-rate predictability previously reserved for government missions.
- Low-Earth orbit broadband replenishment:Constellation operators in China and the United States contract manufacturing slots years ahead of de-orbit schedules. Satellite bus production lines run at continuous cadence to maintain network density.
Market Restraints
- Titanium alloy supply concentration:Russian and Ukrainian feedstock disruption forces Western propulsion manufacturers into qualified alternative sourcing. Recertification timelines extend procurement cycles by 18-24 months.
- ITAR-controlled component restrictions:Cross-border transfer of cryogenic valve assemblies and inertial guidance units faces heightened classification review. Non-US payload integrators encounter integration delays.
- Launch site capacity bottlenecks:Eastern Range and Western Range slot availability constrains commercial cadence regardless of vehicle readiness. Range safety modernization lags behind operator demand.
Strategic Opportunities
- In-space servicing and debris removal:Orbital robotics platforms capture non-functional satellites for controlled de-orbit. European operators under EU Space Surveillance and Tracking mandates represent anchor demand.
- Sub-orbital point-to-point cargo:Hypersonic delivery concepts attract defense logistics investment for time-critical materiel transport. Test corridors over the Pacific Ocean enable iterative vehicle development.
- Green propellant transition:Ammonium dinitramide formulations replace hydrazine in satellite propulsion. NASA's Green Propellant Infusion Mission validates flight heritage for commercial adoption.
Industry Challenges
- Aerospace engineering talent scarcity:Captive apprenticeship pipelines at Lockheed Martin and Northrop Grumman exhaust regional graduate pools. Competitors poach mid-career specialists with equity-heavy compensation.
- Environmental review timeline expansion:FAA and EPA coordinated impact assessments for launch sites add 12-18 months to greenfield facility approvals. Operators absorb carrying costs on dormant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Technology (Spacetech) Market |
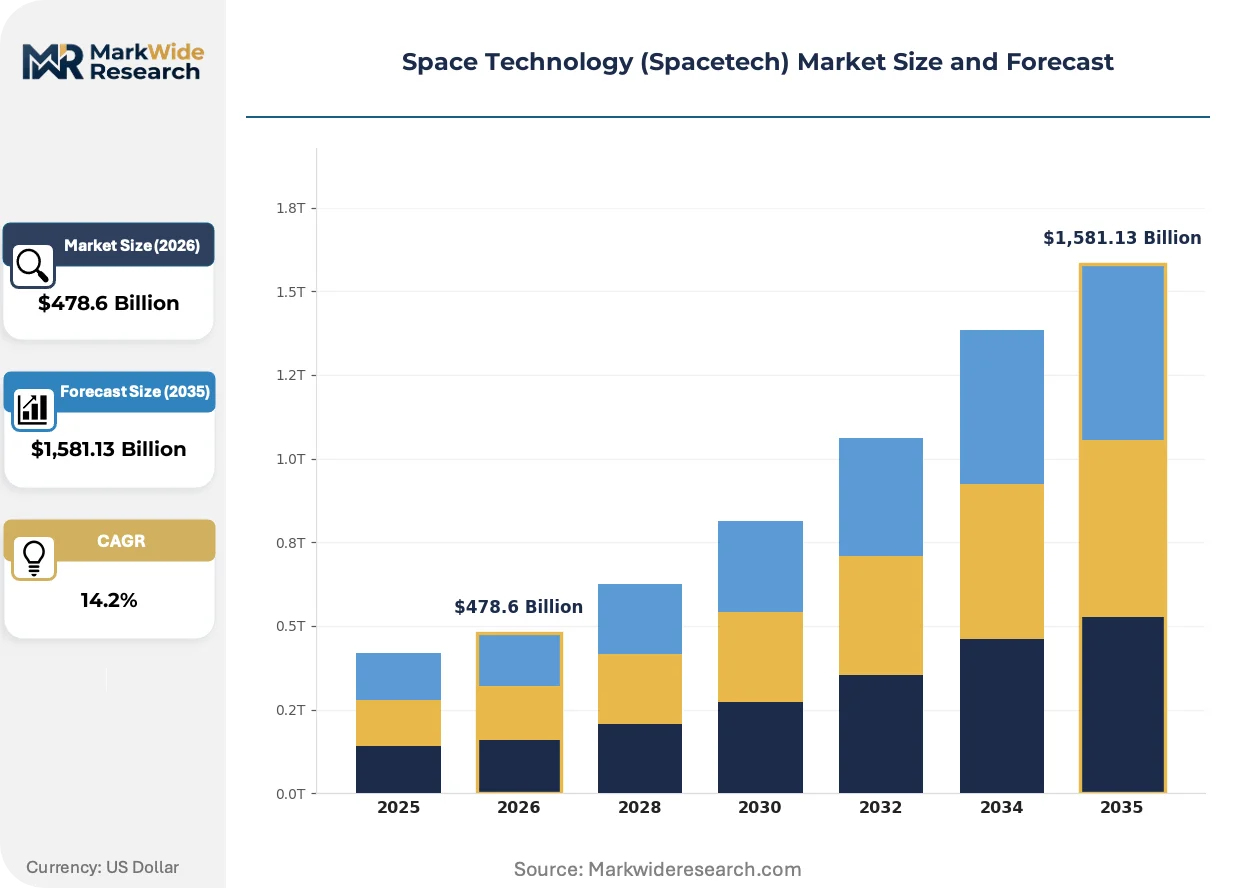
| Market Size in 2026 | $478.6 Billion |
| Market Size in 2035 | $1,581.13 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellites, Launch Vehicles, Ground Control Systems, Spacecraft Technology: Propulsion Systems, Communication Systems, Navigation Systems, Robotics End User: Government Agencies, Commercial Firms, Research Institutions, Military Application: Earth Observation, Space Exploration, Telecommunications, Navigation |
| Companies Covered | SpaceX, Lockheed Martin Corporation, Northrop Grumman Corporation, Boeing, Airbus SE, Rocket Lab USA, Thales Group, Maxar Technologies, Blue Origin LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Technology (Spacetech) Market Evolving Landscape
Additive manufacturing of Inconel thrust chamber components is collapsing lead times for engine qualification. Digital thread integration from design to test reduces iteration cycles across propulsion development programs.
Staged-combustion architectures burning liquid methane and liquid oxygen are decomposing the cost advantage of legacy kerosene-fueled open-cycle engines. Small launch vehicle developers in the United States and China adopt full-flow designs to reach price points below $2,000 per kilogram to orbit. This technology compression enables constellation operators to optimize satellite mass rather than launch vehicle selection.
EU Space Surveillance and Tracking debris mitigation standards now mandate collision avoidance maneuver capability and post-mission disposal reliability above 90 percent. Operators accessing European ground infrastructure must demonstrate compliance through design review and operational data submission. Satellite manufacturers in Germany and France reconfigure propulsion margins to satisfy end-of-life de-orbit requirements.
Defense procurement offices are consolidating launch service acquisition into multi-year task order vehicles rather than single-mission competitions. The National Security Space Launch program shifts risk allocation toward contractors through fixed-price milestone payments. This behavioral change concentrates volume with vertically integrated providers capable of absorbing development cost exposure.
Space Technology (Spacetech) Market Segmentation
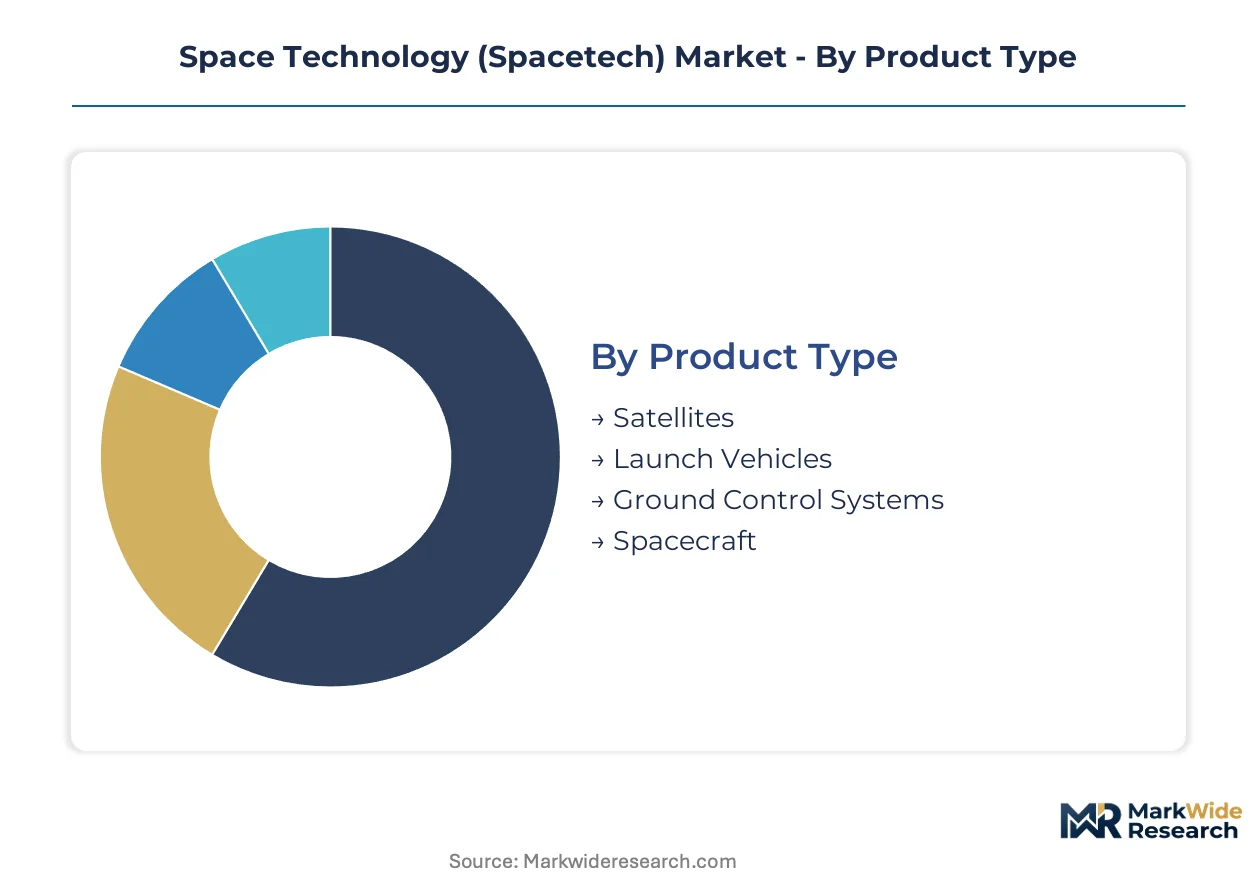
Segmentation in spacetech reveals distinct procurement rhythms across institutional and commercial buyers. Government agencies prioritize mission assurance over unit economics, while commercial constellation operators optimize for production cadence and launch cost compression. Technology selection diverges sharply between these constituencies.
Product Type:
Domestic production dominates satellites and launch vehicles in the United States, whereas ground control systems and specialized spacecraft components flow through export-licensed channels to allied nations.
- Satellites:Bus architectures range from 3U CubeSats to 6,000-kilogram geostationary platforms with electric propulsion. Demand clusters in low-Earth orbit broadband constellations across the United States and China, where operators contract manufacturing slots years ahead of de-orbit schedules. Thermal control systems and power subsystems face titanium alloy supply constraints extending procurement cycles.
- Launch Vehicles:Reusable first stages with vertical landing capability now anchor commercial cadence. United States operators dominate flight-rate economics through in-house engine production, while European and Japanese providers struggle with expendable architecture cost structures. FAA Part 450 licensing consolidation favors established domestic providers with range safety track records.
- Ground Control Systems:Telemetry, tracking, and command infrastructure supports constellation operations. Export-controlled encryption modules restrict cross-border deployment to ITAR-cleared allied facilities.
- Spacecraft:Crew-rated capsules and cargo vehicles with atmospheric re-entry thermal protection above 1,650 degrees Celsius. NASA Commercial Crew contracts anchor domestic demand.
Satellites command the established base. The steepest expansion runs through launch vehicles.
Technology:
Cost tier differentiation separates mature communication systems from emerging propulsion architectures requiring full qualification campaigns.
- Propulsion Systems:Staged-combustion engines burning liquid methane and liquid oxygen achieve specific impulse exceeding 300 seconds in vacuum. United States test stands retrofit for full-flow cycle validation as methane architectures displace legacy kerosene systems. Russian and Ukrainian titanium alloy feedstock disruption forces Western manufacturers into 18-24 month recertification timelines.
- Communication Systems:Phased-array antennas and optical inter-satellite links enable high-throughput data relay. Constellation operators in China and the United States drive volume demand for standardized transceiver modules.
- Navigation Systems:GPS augmentation and autonomous rendezvous sensors support precision orbital operations. Military demand concentrates in encrypted anti-jam configurations.
- Robotics:Orbital servicing platforms with capture mechanisms for non-functional satellite de-orbit. EU Space Surveillance and Tracking mandates generate anchor demand from European operators requiring 90 percent post-mission disposal reliability.
Communication systems represent the mature revenue base. Robotics is climbing the fastest as debris mitigation regulations tighten.
End User:
Customer type determines contract structure, with government agencies accepting cost-plus terms while commercial firms demand fixed-price milestones.
- Government Agencies:NASA and civil space organizations fund technology demonstration missions with extended development timelines. National Security Space Launch program consolidation shifts risk to contractors through fixed-price milestone payments.
- Commercial Firms:Constellation operators optimize for satellite mass production and rapid launch cadence. Vertical integration into engine manufacturing compresses cost structures for vertically integrated providers.
- Research Institutions:University-led CubeSat missions access rideshare launch opportunities. Limited budgets constrain sensor payload sophistication.
- Military:Classified satellite procurement through specialized payload integration facilities. ITAR controls restrict component sourcing to domestic qualified suppliers.
Government agencies anchor the established base. Commercial firms are gaining share fastest as broadband constellation deployment accelerates.
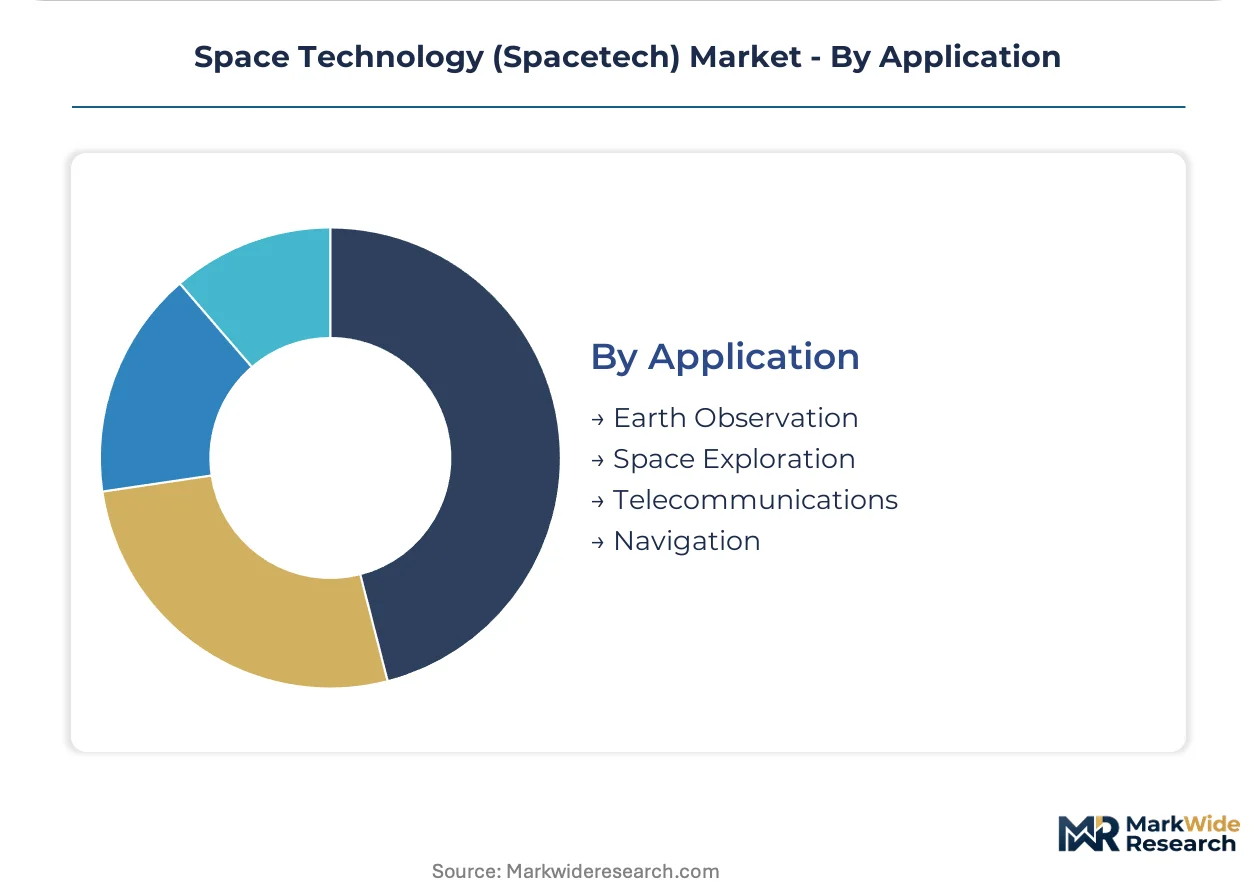
Application:
Application maturity varies from operational telecommunications services to exploratory space missions with undefined revenue models.
- Earth Observation:Weather monitoring and maritime surveillance contracts generate recurring government demand. European operators under EU Space Surveillance and Tracking mandates reconfigure propulsion margins for end-of-life de-orbit compliance.
- Space Exploration:Crewed lunar and Martian mission architectures require unproven in-situ resource utilization technologies. NASA Artemis program anchors near-term investment.
- Telecommunications:Low-Earth orbit broadband networks command continuous replenishment production. Satellite bus manufacturing lines in the United States and China run at sustained cadence.
- Navigation:GPS augmentation and autonomous vehicle positioning services leverage existing constellation infrastructure. Signal integrity requirements limit new entrant participation.
Telecommunications commands the established base. Space exploration shows the steepest expansion trajectory as lunar infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA launch licensing governs commercial orbital operations in the United States, while the FCC coordinates spectrum allocation for satellite constellations. National space agencies and defense procurement offices across multiple jurisdictions anchor institutional demand for spacecraft manufacturing and launch services.
United States
Commercial constellation operators contract manufacturing slots years ahead of de-orbit schedules to maintain network density. The FAA's Part 450 streamlined licensing reduces pre-mission administrative timelines for reusable systems. Hawthorne, California anchors vertical manufacturing of methane-fueled engines, while Redondo Beach facilities specialize in national security payload integration.
China
State-backed constellation programs drive continuous satellite bus production at sustained cadence for low-Earth orbit broadband networks. MIIT coordinates spectrum allocation and manufacturing standards through GB certification requirements. Yangtze River Delta manufacturing clusters produce standardized transceiver modules for phased-array antenna systems.
France
EU Space Surveillance and Tracking mandates generate anchor demand for orbital robotics platforms with 90 percent post-mission disposal reliability requirements. ESA procurement frameworks fund technology demonstration missions with extended development timelines. Toulouse and Paris-Saclay clusters reconfigure propulsion margins to satisfy end-of-life de-orbit compliance standards.
Japan
METI-funded propulsion research programs support staged-combustion engine development for small launch vehicle applications. JAXA coordinates domestic launch site capacity allocation through Tanegashima and Uchinoura range authorities. Nagoya industrial corridors specialize in titanium alloy component fabrication for cryogenic valve assemblies.
United Kingdom
Commercial small satellite manufacturers access rideshare launch opportunities through vertically integrated domestic payload integration facilities. UK Space Agency licensing frameworks align with EU debris mitigation standards for operators accessing European ground infrastructure. Scotland's vertical launch sites and Cornwall horizontal launch facilities compete for emerging commercial flight-rate demand.
Space Technology (Spacetech) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the spacetech competitive structure. Vertically integrated providers absorb development cost exposure through fixed-price milestone payments, while specialized payload integrators concentrate on classified national security architectures. Three archetypes dominate: full-stack launch operators with captive engine production, satellite manufacturers with continuous production lines, and ground systems specialists with export-controlled encryption capabilities. Competitive moves concentrate on captive supply of critical components and multi-year task order consolidation for defense procurement.
Among United States-based integrated operators, SpaceX and Blue Origin exemplify the full-stack archetype with vertical control over propulsion manufacturing. Lockheed Martin Corporation occupies a position within the specialized national security tier, anchoring classified satellite production through captive apprenticeship pipelines. These three entities represent the dominant competitive anchors across commercial launch cadence and institutional mission assurance segments.
| Leading Market Players |
|---|
| SpaceX |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Boeing |
| Airbus SE |
| Rocket Lab USA |
| Thales Group |
| Maxar Technologies |
| Blue Origin LLC |
| Others |
Value Network & Pricing Analysis
Fixed-price milestone payments for national security launch contracts lock in multi-year supply access and cost visibility for vertically integrated operators. This contract structure concentrates procurement power with domestic providers capable of absorbing titanium alloy and cryogenic component exposure under FAA and ITAR frameworks.
Pricing Analysis
United States launch services command substantial premiums over European and Japanese expendable alternatives due to reusable first-stage economics. Three-tier pricing structure across premium mission-assurance, standard commercial, and economy rideshare tiers differentiates government payloads from constellation replenishment batches. Price differentiation rests on ITAR-controlled component content and vertical manufacturing depth. Cost compression in small launch vehicle segments is intensifying as methane-fueled engine developers target price points below two thousand dollars per kilogram to orbit. Commercial constellation operators exhibit the highest price sensitivity, while national security procurement offices prioritize mission assurance over unit economics.
Supply Chain Analysis
Strategic stockpiling of titanium alloy feedstock dominates inventory strategy as Russian and Ukrainian supply disruption forces eighteen-to-twenty-four-month recertification timelines. Manufacturing concentration clusters in the United States, China, and Germany for satellite buses, propulsion systems, and ground control infrastructure. The supply chain draws from specialized inputs including Inconel superalloys, ammonium dinitramide green propellant formulations, and ITAR-restricted cryogenic valve assemblies. Single-source vulnerability in qualified titanium suppliers represents the primary structural risk. Distribution runs through captive vertical manufacturing networks for integrated launch operators and export-licensed channels for ground systems with encryption modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spacetech sits in early-cycle expansion as low-Earth orbit broadband constellation deployment accelerates beyond replacement rates into net capacity growth. Reusable launch maturation and streamlined FAA licensing compress barriers to orbital access for commercial applications.
For Market Incumbents: Secure captive apprenticeship pipelines in Colorado and California aerospace clusters against mid-career specialist poaching from equity-heavy competitors. Deepen upstream control over Merlin-class engine manufacturing and titanium alloy qualified sourcing to absorb ITAR review timeline extensions. Lockheed Martin and Northrop Grumman must defend classified satellite margins through multi-year National Security Space Launch task order consolidation.
For New Entrants and Emerging Players: Anchor in European orbital robotics and debris removal segments where EU Space Surveillance and Tracking mandates generate anchor demand with ninety percent disposal reliability requirements. Target United Kingdom small satellite manufacturing and Scotland-Cornwall launch site competition as the most penetrable geography. Pursue green propellant transition partnerships with NASA technology demonstration missions to establish flight heritage.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among satellite constellation operators with continuous manufacturing slots and de-orbit replenishment cycles. Long-term viability over the five-to-ten-year window favors vertically integrated launch providers with captive engine production and range safety track records. Acquisition targets should demonstrate FAA Part 450 licensing progress or EU debris mitigation compliance certification. The signal to monitor is Eastern Range and Western Range slot allocation expansion relative to commercial vehicle readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Launch Vehicle Scale-Up | SpaceX and Blue Origin compress cost structures through vertical Merlin and BE-4 engine manufacturing. |
| Green Propellant Certification | NASA's Green Propellant Infusion Mission validates ammonium dinitramide flight heritage for commercial satellite adoption. |
| EU Debris Mitigation Compliance | European operators reconfigure propulsion margins to satisfy Space Surveillance and Tracking disposal reliability mandates. |
| Captive Titanium Alloy Sourcing | Western manufacturers establish qualified alternative supply chains outside Russian and Ukrainian feedstock disruption zones. |
| Small Launch Vehicle Full-Flow Development | United States and Chinese developers target sub-two-thousand-dollar-per-kilogram price points through staged-combustion methane architectures. |
Research Methodology
A standing panel of launch vehicle program managers, satellite bus manufacturing directors, FAA licensing officers, and national security procurement specialists provided ongoing calibration throughout the study. Primary interviews with commercial constellation operators and defense payload integrators combined with secondary validation against FCC spectrum allocation databases, FAA Part 450 regulatory filings, ESA procurement records, and customs trade data for titanium alloy imports. Bottom-up manufacturing capacity estimates triangulated against top-down launch demand projections across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs for satellite production, launch service revenue, and ground system deployment. The analytical framework modeled segmentation across product type, technology category, end user archetype, and application use case throughout the forecast period. CAGRs derived from annual production slot contracting patterns and constellation replenishment schedules incorporated propulsion technology transition curves and debris mitigation regulatory phase-ins.
Material uncertainties — ITAR classification expansion, titanium supply recertification delays, and range safety modernization lag — sit outside the modeled envelope. Forecasts reflect assumptions regarding FAA licensing timeline stability and EU debris standard enforcement consistency. Revision becomes warranted when launch site capacity bottlenecks cross thresholds that constrain commercial cadence regardless of vehicle readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Spain Space Electronics Market
Space
South Korea Space Electronics Market
Space
UK Space Electronics Market
Space
Space in Orbit Refueling Market
Space
Space Burial Service Market
Space
Astronaut Spacesuit Market
Space
Space Semiconductor Market
Space
Europe Space Electronics Market
Space
Space Debris Monitoring Market
Space
Space Travel Market
Space
Suborbital Space Tourism Market
Space
Africa Space Electronics Market
Space
Space Lander and Rover Market
Space
Space Debris Monitoring and Removal Market
Space
Space Ground Station Equipment Market
Space
Space-Based C4ISR Market