
 Space in Orbit Refueling Market | 2026-2036
Space in Orbit Refueling Market Size, Share, and Industry Trends Forecast 2026-2036
Space in Orbit Refueling Market Insights
The EU Green Deal's push for sustainable space operations is hardening requirements for debris mitigation and satellite longevity across European procurement frameworks. Orbit Fab, Inc. anchors the commercial refueling segment with fluid transfer architectures designed for geostationary servicing. Northrop Grumman Corporation dominates government-backed life extension missions through its Mission Extension Vehicle program. Lockheed Martin Corporation leverages integrated satellite manufacturing capabilities to position refueling as a natural extension of its spacecraft lifecycle services.
Space in Orbit Refueling encompasses the transfer of propellants, coolants, or electrical energy to spacecraft already in orbital operation, typically requiring precision docking at relative velocities below 0.1 m/s and fluid coupling mechanisms rated for vacuum exposure and thermal cycling between -150°C and +120°C. The primary commercial purpose is extending operational lifespan of high-value geostationary satellites and enabling sustained logistics for cislunar infrastructure. Robotic Arm technology leads current deployment due to proven heritage from Canadarm derivatives and ISS servicing missions, while Cryogenic Handling represents the fastest-growing segment as lunar oxygen-hydrogen architectures mature. Satellite Operators command the largest end-user value pool given their direct economic incentive to defer replacement capital expenditure through on-orbit servicing.
FAA licensing requirements for commercial on-orbit activities and NASA's technical standards for rendezvous and proximity operations shape both market access and product safety baselines in the United States, while ISO 24330 space systems refueling interface standards provide the interoperability framework for multi-vendor architectures. ESA's Clean Space initiative and associated debris mitigation guidelines are tightening design-for-servicing mandates across European satellite procurements. Stakeholders must monitor which regulatory jurisdiction captures the first binding refueling certification regime, as this will determine supply chain location and partnership structures for the next wave of infrastructure investment.
Market Dynamics
Artemis program requirements for sustained lunar presence are compressing technology maturation timelines and forcing capital allocation toward cryogenic fluid management architectures that can operate across cislunar distances.
Growth Catalysts
- EU Green Deal debris mitigation mandates:European procurement frameworks now embed design-for-servicing requirements, creating binding demand for satellite life extension services.
- Cislunar logistics infrastructure buildout:NASA's sustained lunar presence objectives are accelerating demonstration missions for cryogenic oxygen-hydrogen transfer.
- Geostationary satellite capital deferral:Satellite operators facing replacement capex pressure are adopting refueling to extend high-value orbital assets.
Market Restraints
- Precision rendezvous cost structure:Relative velocity control below 0.1 m/s demands guidance systems consuming 40-60% of mission development budgets.
- Fluid coupling supply concentration:Vacuum-rated seals and cryogenic valves rely on a limited supplier base concentrated in aerospace clusters.
- ISO 24330 standardization gaps:Incomplete interoperability specifications force custom interface development for each mission architecture.
Strategic Opportunities
- ESA Clean Space initiative tailwinds:Debris mitigation guidelines are tightening design-for-servicing mandates across European satellite procurements.
- Cryogenic-electrical hybrid architectures:Convergence of superconducting power transfer with fluid handling enables new service categories.
- LEO constellation aftermarket:Emerging demand from megaconstellation operators for orbital maneuvering refueling represents unpenetrated white space.
Industry Challenges
- Rendezvous and proximity operations certification:FAA licensing timelines for commercial on-orbit activities create mission scheduling uncertainty.
- Thermal cycling qualification:Fluid coupling mechanisms must demonstrate reliability across -150°C to +120°C extremes, extending test programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space in Orbit Refueling Market |
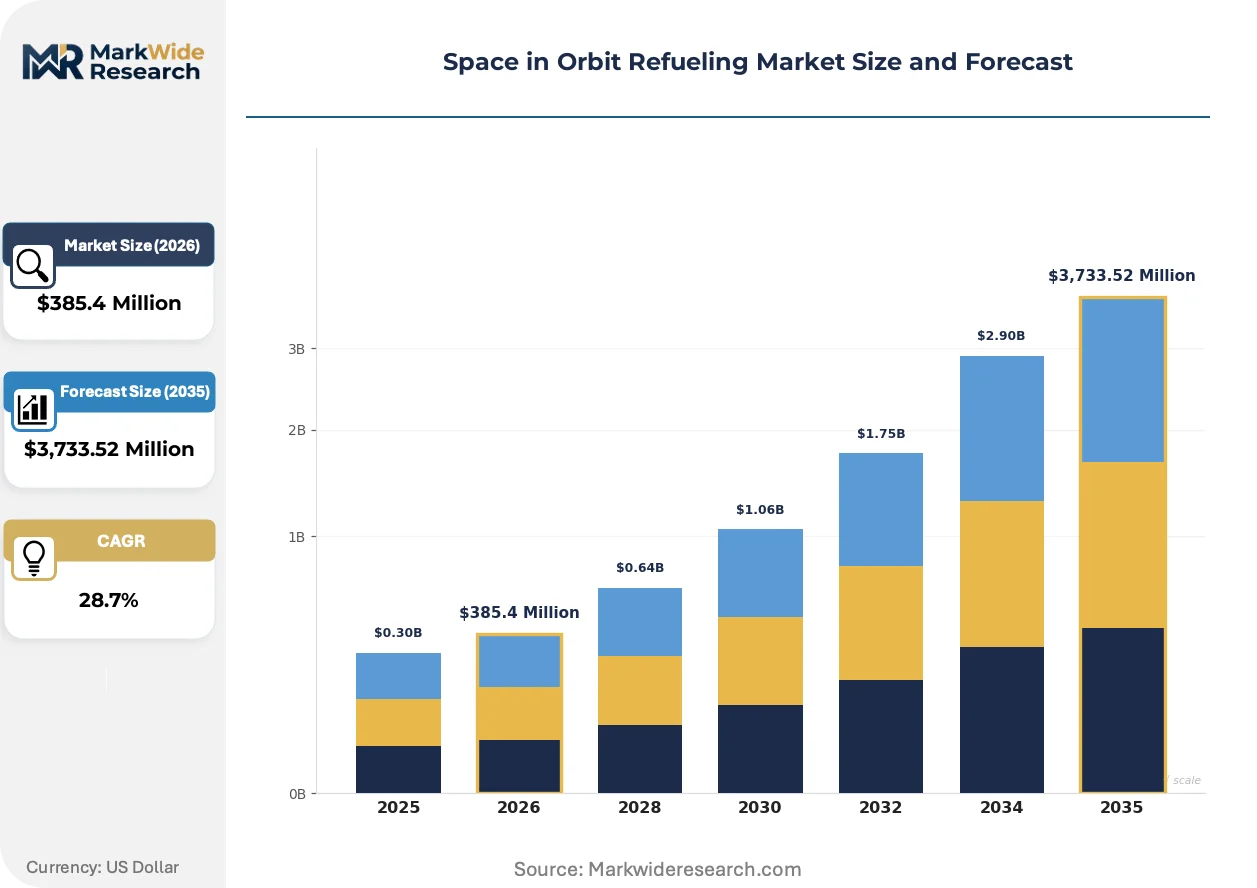
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $3,733.52 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Refueling Technology: Robotic Arm, Fluid Transfer, Cryogenic Handling, Autonomous Docking, Wireless Power, Manual Interface Service Offering: Fuel Delivery, Maintenance & Repair, Cargo Transfer, Satellite Boost, Life Extension, Debris Removal Spacecraft Type: Communication Satellites, Earth Observation, Navigation Probes, Science Platforms, Microgravity Labs, Space Telescopes End User: Satellite Operators, Government Agencies, Private Aerospace Firms, Research Institutions, Defense Contractors, Space Logistics Providers |
| Companies Covered | Astroscale Holdings Inc., Orbit Fab, Inc., Northrop Grumman Corporation, Lockheed Martin Corporation, D-Orbit SpA, Maxar Technologies Inc., Airbus SE, Obruta Space Solutions, SpaceX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space in Orbit Refueling Market Trends and Innovations
Active standardization efforts across multiple jurisdictions are reshaping interface architectures, while propellant type diversification and procurement model evolution are restructuring commercial relationships between service providers and satellite operators.
Autonomous docking algorithms derived from Canadarm heritage are converging with machine vision systems to reduce human-in-the-loop requirements for geostationary servicing missions. Satellite operators are integrating these capabilities into new build specifications at accelerating pace. This convergence is compressing the technical barrier between government-funded demonstration missions and commercially viable service offerings.
ISO 24330 space systems refueling interface standards are mandating physical and electrical interoperability across multi-vendor architectures. The standard's industrial consequence is forcing proprietary system designers toward modular component strategies. Geostationary satellite manufacturers are responding by embedding standardized refueling ports during initial production rather than retrofitting.
Lifecycle service contracting is displacing transactional satellite procurement across major operator portfolios. The traditional capex-heavy replacement cycle is yielding to operational expenditure models where refueling providers assume orbital performance risk. This shift is most visible among United States-based operators with concentrated government contracting exposure.
Space in Orbit Refueling Market Segmentation
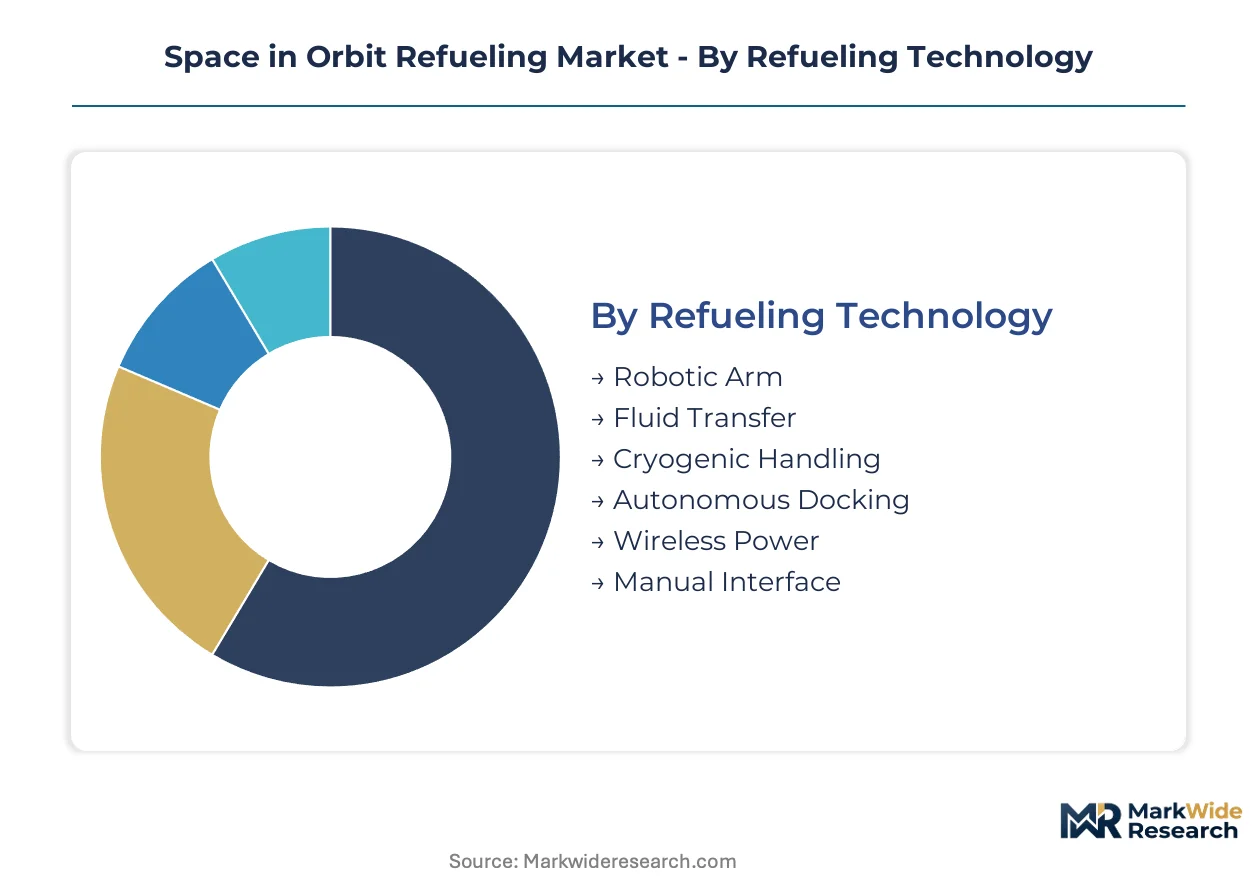
Segmentation in the Space in Orbit Refueling Market reveals how technology maturity, service economics, and customer risk tolerance partition commercial opportunity. Each dimension exposes different integration architectures and capital intensity requirements.
Refueling Technology:
Integration depth varies sharply across this category, with some technologies operating as standalone mission modules while others embed deeply into host spacecraft bus designs.
- Robotic Arm:Mechanical manipulation systems derived from Canadarm heritage execute precision capture and fluid coupling at relative velocities below 0.1 m/s. Demand concentrates in geostationary servicing missions where NASA technical standards for rendezvous and proximity operations mandate proven reliability. The FAA licensing framework for commercial on-orbit activities reinforces adoption of flight-proven mechanical architectures.
- Cryogenic Handling:Vacuum-insulated transfer systems rated for liquid oxygen and hydrogen across -150°C to +120°C thermal cycling. Artemis program requirements for sustained lunar presence are compressing demonstration timelines for cislunar oxygen-hydrogen architectures. NASA's technical standards for cryogenic fluid management in cislunar distances accelerate capital allocation toward this segment.
- Fluid Transfer:Standardized coupling mechanisms for hydrazine and xenon propellants using ISO 24330 interface specifications.
- Autonomous Docking:Machine vision and guidance systems reducing human-in-the-loop requirements for servicing missions.
- Wireless Power:Inductive and laser-based energy transfer for spacecraft unable to accommodate fluid coupling.
- Manual Interface:Human-tended servicing for high-value science platforms and crewed infrastructure.
Volume placements concentrate in Robotic Arm; the faster expansion belongs to Cryogenic Handling.
Service Offering:
Customer procurement models stratify this category, with some services contracted as transactional missions while others embed into long-term lifecycle performance agreements.
- Life Extension:Propellant replenishment and orbital station-keeping to defer satellite replacement capital expenditure. Satellite operators facing replacement capex pressure in the United States are adopting operational expenditure models where service providers assume orbital performance risk. The concentrated government contracting exposure among United States-based operators accelerates this shift from transactional to lifecycle contracting.
- Fuel Delivery:Scheduled propellant resupply for satellites with standardized refueling ports.
- Maintenance & Repair:Component replacement and anomaly correction requiring precision manipulation.
- Cargo Transfer:Logistics support for crewed platforms and orbital manufacturing facilities.
- Satellite Boost:Orbital transfer assistance for repositioning or deorbit maneuvers.
- Debris Removal:End-of-life propulsion assistance supporting EU Green Deal debris mitigation mandates.
Procurement volume clusters in Life Extension; steepest expansion trajectory is emerging in Debris Removal as European procurement frameworks harden design-for-servicing requirements.
Spacecraft Type:
Asset value concentration and mission criticality determine which spacecraft types justify refueling economics versus replacement.
- Communication Satellites:High-value geostationary assets generating sustained revenue streams that justify life extension investment. Satellite operators in the United States with concentrated government contracting exposure are embedding standardized refueling ports during initial production rather than retrofitting.
- Earth Observation:Constellation assets where refueling enables orbital plane maintenance and mission reconfiguration.
- Navigation Probes:Precision timing infrastructure requiring sustained station-keeping.
- Science Platforms:Research spacecraft with irreplaceable orbital positioning or observation geometry.
- Microgravity Labs:Crew-tended facilities with integrated logistics requirements.
- Space Telescopes:Unique orbital assets where replacement timelines span decades.
Commercial activity concentrates in Communication Satellites; Science Platforms command highest mission value per refueling event.
End User:
Contracting authority and risk tolerance partition demand across government, commercial, and institutional customers with diverging technical specifications.
- Satellite Operators:Commercial entities with direct economic incentive to extend high-value orbital assets and defer replacement capital expenditure. United States-based operators with concentrated government contracting exposure are displacing transactional satellite procurement with lifecycle service contracting across major portfolios.
- Government Agencies:NASA, ESA, and national space programs funding technology demonstration and cislunar infrastructure. Artemis program requirements for sustained lunar presence are accelerating cryogenic fluid management maturation.
- Private Aerospace Firms:Emerging launch and service providers building orbital logistics capabilities.
- Research Institutions:Scientific missions with extended operational timelines and limited replacement budgets.
- Defense Contractors:National security spacecraft requiring assured access and rapid reconstitution.
- Space Logistics Providers:Specialized operators offering multi-customer refueling infrastructure.
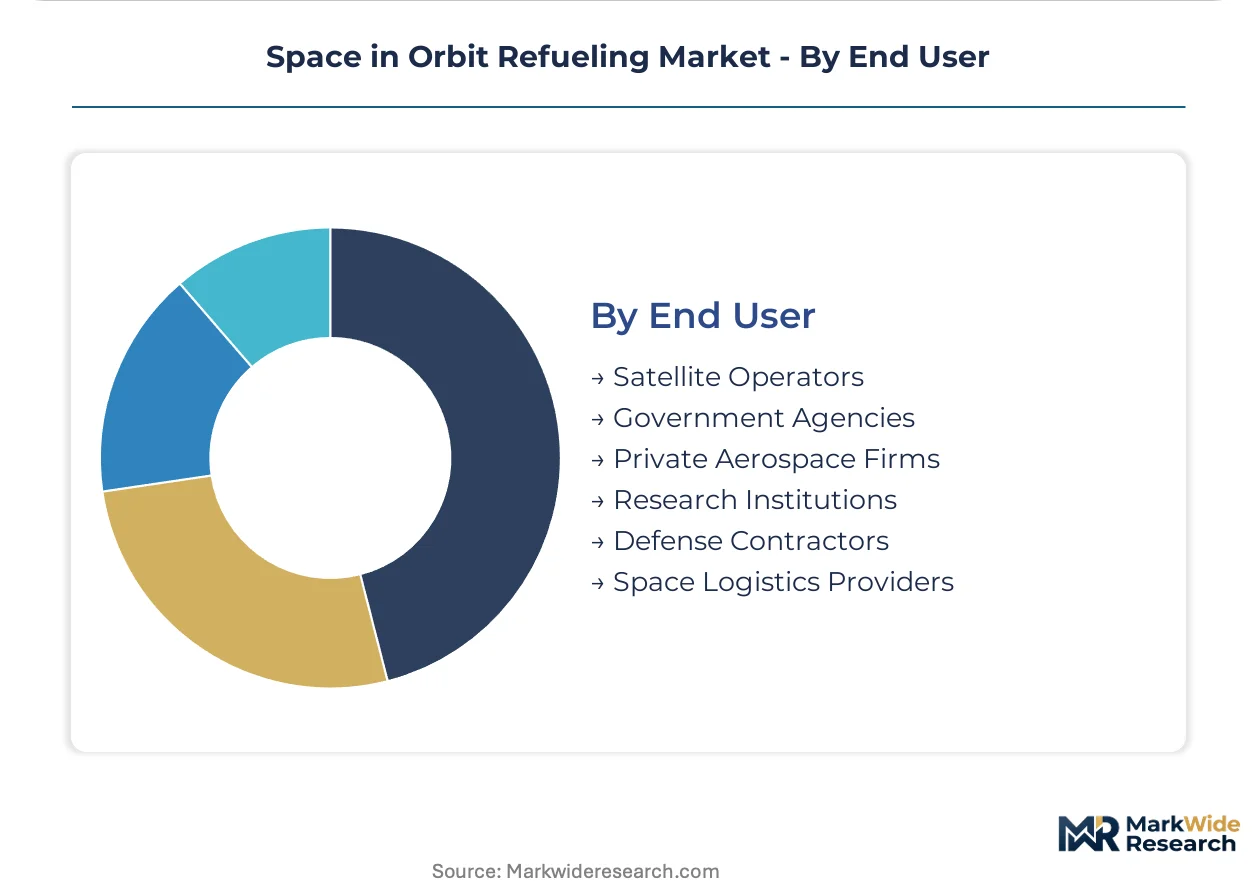
Contract flow concentrates in Satellite Operators; Government Agencies provide foundational demand for cryogenic and cislunar capability development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States while consumption spreads across established spacefaring nations. Government contracting density and private launch infrastructure determine where refueling technology matures first.
United States
NASA's Artemis program drives sustained lunar presence requirements that accelerate cryogenic fluid management maturation. FAA licensing frameworks for commercial on-orbit activities shape both market access and safety baselines. Houston and Los Angeles anchor the industrial cluster, with concentrated government contracting pulling private launch infrastructure toward Texas and California.
France
ESA's Clean Space initiative tightens design-for-servicing mandates across European satellite procurements. EU Green Deal debris mitigation requirements harden operational standards for satellite longevity. Toulouse hosts the primary aerospace manufacturing concentration, where Airbus SE integrates standardized refueling ports into initial production specifications.
Japan
METI funding for orbital logistics demonstration missions supports technology maturation timelines. JIS standards development for rendezvous and proximity operations creates regulatory scaffolding for commercial entry. Tokyo-Yokohama and Nagoya industrial corridors concentrate precision guidance system manufacturing for sub-0.1 m/s relative velocity control.
United Kingdom
UK Space Agency procurement for debris removal services stimulates demand for end-of-life propulsion assistance. National Space Strategy commitments to sustainable operations align with EU Green Deal debris mitigation frameworks. Harwell and Glasgow space clusters host emerging specialists in autonomous docking algorithms and machine vision integration.
Germany
DLR technology demonstration programs for cryogenic transfer systems advance cislunar oxygen-hydrogen architectures. REACH chemical safety regulations influence propellant handling protocols for orbital operations. Munich and Bremen aerospace clusters concentrate fluid coupling mechanism development for vacuum-rated seals and cryogenic valves.
Space in Orbit Refueling Market Competitive Landscape
The competitive structure tilts toward defense-integrated primes and venture-backed specialists. Tier-one contractors leverage government relationships and flight heritage to capture demonstration mission awards. Emerging players concentrate on modular fluid transfer architectures and standardized interface development. Dominant competitive moves include strategic partnerships for launch integration and portfolio diversification into lifecycle service contracting.
Among defense-integrated primes, Northrop Grumman Corporation and Lockheed Martin Corporation occupy positions shaped by Mission Extension Vehicle program execution and integrated satellite manufacturing capabilities. Orbit Fab, Inc. exemplifies the venture-backed specialist archetype, anchoring commercial refueling segment development with fluid transfer architectures designed for geostationary servicing. These three entities collectively represent the spectrum from government-backed life extension missions to commercially driven infrastructure buildout.
| Leading Market Players |
|---|
| Astroscale Holdings Inc. |
| Orbit Fab, Inc. |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| D-Orbit SpA |
| Maxar Technologies Inc. |
| Airbus SE |
| Obruta Space Solutions |
| SpaceX |
| Others |
Pricing and Supply Chain Analysis
Concentrated government procurement programs anchor demand for space in orbit refueling services, locking in long-term performance-based contracting that shields premium-tier providers from spot-market volatility. Satellite operators with Artemis program exposure negotiate lifecycle service agreements where providers assume orbital performance risk, compressing transactional pricing flexibility.
Pricing Analysis
Cost-down pressure on geostationary life extension missions accelerates as satellite operators consolidate vendor panels and demand standardized ISO 24330 interfaces. Three-tier pricing structure across heritage-proven, flight-qualified, and developmental service tiers separates Northrop Grumman's Mission Extension Vehicle premium from emerging autonomous docking alternatives. Price differentiation hinges on flight heritage depth and FAA licensing status, with uncrewed refueling startups facing acute buyer resistance. Government agencies demonstrate lowest price sensitivity given mission assurance requirements, while commercial constellation operators drive hardest bargain on per-kg propellant delivery.
Supply Chain Analysis
Return flows of decommissioned robotic arms and refurbished cryogenic valves from geostationary servicing missions feed secondary qualification programs for lunar demonstration architectures. Manufacturing concentrates in the United States, Germany, and Japan, with Houston, Munich, and Nagoya anchoring precision guidance system production. Vacuum-rated seals and cryogenic valve assemblies draw from aerospace clusters with limited qualified suppliers, creating single-source vulnerability for fluid coupling mechanisms. Distribution runs through prime contractor integration facilities before reaching launch service providers, elongating lead times for mission-critical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
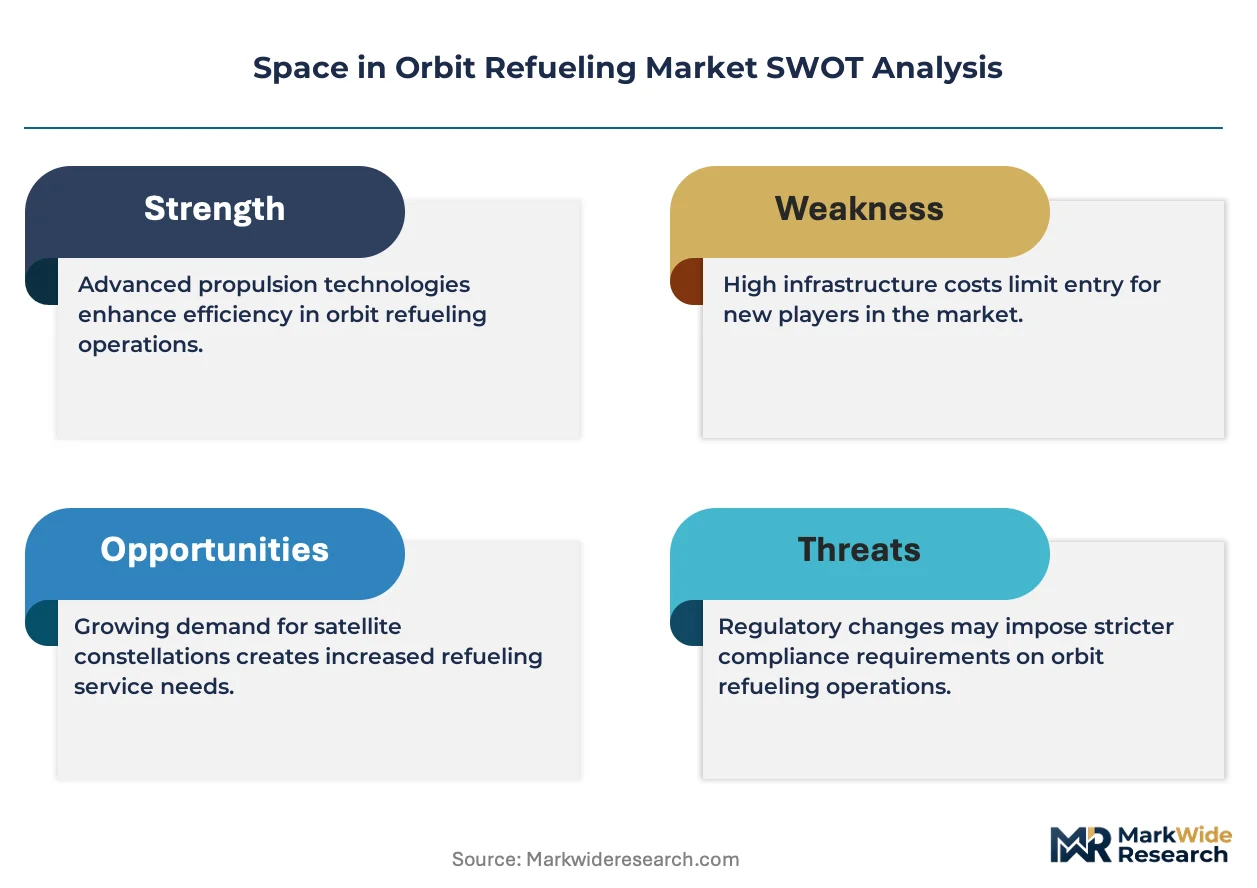
Limited qualified supplier capacity for vacuum-rated cryogenic hardware props pricing power for incumbents with demonstrated thermal cycling reliability. Bottleneck concentration in fluid coupling mechanisms sustains margin premiums across the analysis window.
For Market Incumbents: Cement flight heritage advantages by capturing ESA Clean Space initiative demonstration awards before ISO 24330 standardization commoditizes interface specifications. Deepen backward integration into cryogenic valve manufacturing to reduce exposure to German aerospace cluster supply constraints. Lockheed Martin and Northrop Grumman should extend lifecycle service contracting templates from geostationary assets to cislunar logistics infrastructure. For New Entrants and Emerging Players: Begin with debris removal service offerings under UK Space Agency procurement frameworks, where design-for-servicing mandates create binding demand without requiring full cryogenic handling capability. Target LEO constellation operators with standardized refueling port retrofits, leveraging autonomous docking algorithm development at Harwell and Glasgow clusters. Pursue partnership-based go-to-market models with established launch integrators rather than direct operator sales. For Investors and Strategic Acquirers: The window for entry favors venture-backed specialists with modular fluid transfer architectures and FAA licensing progress. Long-term viability rests on capturing cislunar oxygen-hydrogen demonstration missions before prime contractor consolidation closes acquisition pathways. Watch NASA cryogenic fluid management milestone schedules as inflection indicator for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 24330 Interface Standardization | Orbit Fab's modular coupling architectures gain procurement preference across European satellite manufacturers embedding standardized ports. |
| Cryogenic Fluid Management Demonstration | Artemis program oxygen-hydrogen transfer missions validate cislunar logistics economics for sustained lunar presence requirements. |
| Lifecycle Service Contracting Expansion | United States satellite operators displace transactional procurement with performance-based agreements assuming orbital risk. |
| Autonomous Docking Algorithm Development | Machine vision convergence with Canadarm heritage reduces human-in-the-loop requirements for geostationary servicing missions. |
| Debris Removal Service Buildout | EU Green Deal mandates harden design-for-servicing requirements across European procurement frameworks. |
Research Methodology
NASA technical standards documentation, ESA Clean Space initiative filings, and FAA commercial space licensing records formed the secondary backbone for regulatory trajectory assessment. Primary interviews with satellite fleet directors, rendezvous and proximity operations engineers, cryogenic fluid management specialists, and space logistics procurement officers validated demand assumptions across government and commercial segments. Bottom-up mission cost modeling triangulated against top-down addressable satellite population analysis.
Bottom-up unit economics for life extension missions combined with top-down geostationary asset replacement deferral potential across the projection horizon. Segmentation dimensions spanned refueling technology maturity, service offering procurement model, spacecraft type asset value, and end-user contracting authority. CAGRs derived from technology adoption curves weighted by Artemis program demonstration timelines and ESA debris mitigation enforcement schedules. Cryogenic handling growth assumptions rested on lunar oxygen-hydrogen architecture maturation curves.
Underlying measurement precision varies by segment; Robotic Arm and Life Extension carry tighter precision given flight heritage documentation, while Cryogenic Handling and Debris Removal reflect wider uncertainty bands pending demonstration mission outcomes. Forecasts embed assumptions regarding FAA licensing timeline acceleration and ISO 24330 interoperability adoption rates. Practitioners should monitor NASA cislunar logistics budget appropriations and ESA Clean Space procurement mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Near Space Robotics Market
Space
Europe Space Electronics Market
Space
Space Technology (Spacetech) Market
Space
Space Management Solutions Market
Space
Space Mobile Service Market
Space
Space-Based Solar Power Market
Space
North America Spacesuit Market
Space
Space Propulsion Systems Market
Space
Germany Space Electronics Market
Space
US Reusable Launch Vehicle Market
Space
Deep Space Robotics Market
Space
Europe Space Logistics Market
Space
US Space Electronics Market
Space
Space Robots Market
Space
Space Traffic Management Market
Space
Space Launch Services Market