
 US Space Electronics Market | 2026-2036
US Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
US Space Electronics Market Insights
The capability gap between vertically integrated prime contractors and specialized component suppliers is redrawing competitive boundaries in US space electronics. Northrop Grumman Corporation leverages captive semiconductor fabrication to sustain long-term program commitments for strategic satellites. Texas Instruments competes through high-reliability analog portfolios that anchor its position in power management subsystems for deep-space missions. Microchip Technology specializes in radiation-tolerant FPGA offerings that differentiate its catalog from commodity aerospace parts.
US space electronics encompass processors, power supplies, communication modules, and sensors engineered to withstand total ionizing dose thresholds exceeding 100 krad(Si), extreme temperature cycling, and single-event upset conditions in orbital and deep-space environments. These components enable command, control, telemetry, and payload processing functions across civilian and national security spacecraft. The product-type dimension shows processors commanding the largest revenue share due to computational demands of on-orbit autonomy, while sensors represent the fastest-expanding category driven by Earth observation constellation deployments. Within the end-user dimension, government agencies occupy the dominant funding position, though commercial satellites are accelerating procurement cycles through batch manufacturing approaches.
The Federal Aviation Administration, Department of Defense MIL-STD-883 screening protocols, and NASA-STD-8739 manufacturing requirements collectively govern component qualification, flight heritage documentation, and supplier certification for US space electronics. FCC spectrum licensing for commercial satellite operators shapes demand timing for communication modules and RF subsystems. Stakeholders must monitor how Space Development Agency proliferated-constellation contracts alter traditional prime-subcontractor relationships and qualification burden distribution.
Market Dynamics
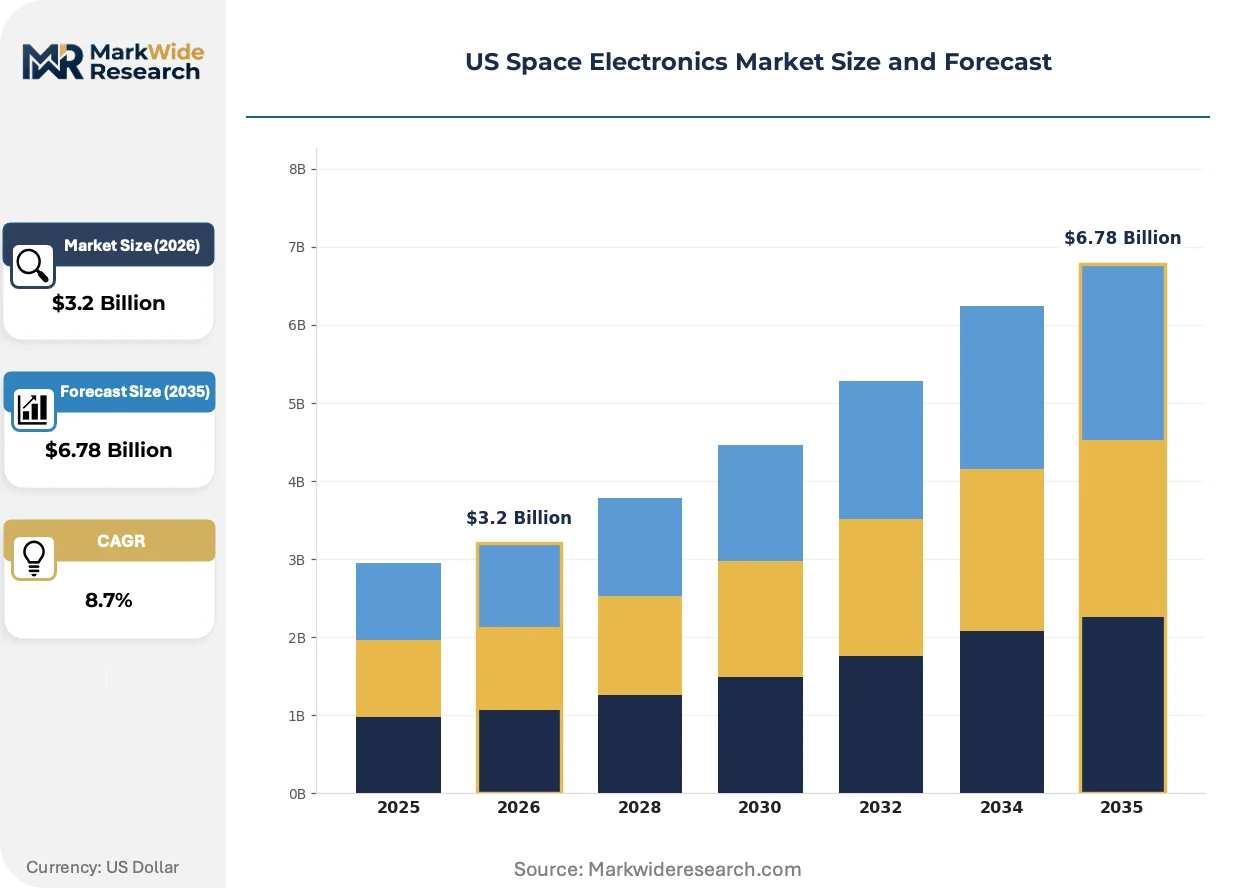
The US Space Electronics Market is being fundamentally restructured by the Space Development Agency's proliferated-constellation procurement model, which fragments traditional prime-subcontractor hierarchies and compresses qualification timelines for radiation-hardened component suppliers.
Growth Catalysts
- Artemis Program Requirements:NASA's lunar exploration mandates are accelerating demand for deep-space-qualified processors and power management systems with extended mission lifecycles.
- California Aerospace Corridor Concentration:Prime contractor clustering near Vandenberg Space Force Base and NASA JPL creates dense supplier ecosystems that reduce logistics friction and enable rapid design iteration.
- MIL-STD-883 Screening Protocols:Department of Defense qualification standards are creating flight heritage documentation that transfers credibility to commercial satellite operators seeking rapid deployment.
Market Restraints
- Radiation-Hardened Semiconductor Supply Concentration:Domestic foundry capacity for components exceeding 100 krad(Si) total ionizing dose thresholds remains concentrated among a handful of captive fabrication facilities.
- Extended Qualification Timelines:NASA-STD-8739 manufacturing requirements and FCC spectrum licensing procedures create multi-year certification pathways that delay revenue recognition for new entrants.
- Neuromorphic Computing Substitution Threat:Emerging radiation-tolerant neural processing architectures are beginning to displace traditional FPGA-based command and control architectures in certain autonomy applications.
Strategic Opportunities
- Texas and Arizona Semiconductor Expansion:CHIPS Act incentives are attracting advanced packaging facilities that could anchor secondary supply nodes beyond California's aerospace corridor.
- On-Orbit Servicing Applications:Emerging demand for satellite life extension and debris removal missions is creating new sensor and rendezvous electronics categories absent from traditional spacecraft specifications.
- Space Force Rapid Acquisition Pathways:Alternative contracting mechanisms are compressing procurement cycles for tactical demonstration missions, enabling faster supplier qualification for non-traditional vendors.
Industry Challenges
- Radiation Effects Engineering Talent Scarcity:The specialized skill set combining semiconductor physics with orbital mechanics remains concentrated among aging workforce cohorts at legacy defense contractors.
- Legacy Bus Architecture Integration Complexity:New commercial-off-the-shelf components must interface with spacecraft platforms designed around obsolete data bus standards, creating qualification testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Space Electronics Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processors, Power Supplies, Communication Modules, Sensors End User: Government Agencies, Commercial Satellites, Research Institutions, Defense Contractors Technology: Analog, Digital, Mixed-Signal, FPGA Application: Satellite Communication, Remote Sensing, Space Exploration, Scientific Research |
| Companies Covered | Honeywell International, Northrop Grumman Corporation, Lockheed Martin Corporation, BAE Systems, Texas Instruments, Microchip Technology, Teledyne Technologies, Astronics Corporation, TT Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Space Electronics Market Trends and Innovations
Commercial satellite batch manufacturing is eroding the traditional flight heritage premium that once protected incumbent suppliers, while radiation-tolerant commercial semiconductors are encroaching on markets historically reserved for fully qualified space-grade components.
Commercial-off-the-shelf (COTS) components with radiation-tolerant rather than radiation-hardened ratings are supplanting fully qualified space-grade parts in low-Earth orbit constellations. SpaceX and Amazon's Project Kuiper are deploying these components at scale for missions under five years duration. This substitution is compressing addressable margins for traditional suppliers while expanding total accessible market volume.
FCC spectrum licensing reforms are tightening coordination requirements for commercial satellite operators seeking radio frequency allocations. The revised procedures are extending pre-launch documentation timelines and forcing communication module suppliers to absorb additional certification engineering costs. Small satellite operators are responding by consolidating RF subsystem procurement with vertically integrated prime contractors.
Modular payload interfaces are displacing custom-designed electronics stacks across Earth observation constellations. Standardized mechanical and electrical connectors are enabling satellite bus manufacturers to swap sensors between missions without full requalification. This interoperability is most visible in California's NewSpace cluster, where venture-backed operators are prioritizing rapid reconfiguration over mission-specific optimization.
US Space Electronics Market Segmentation
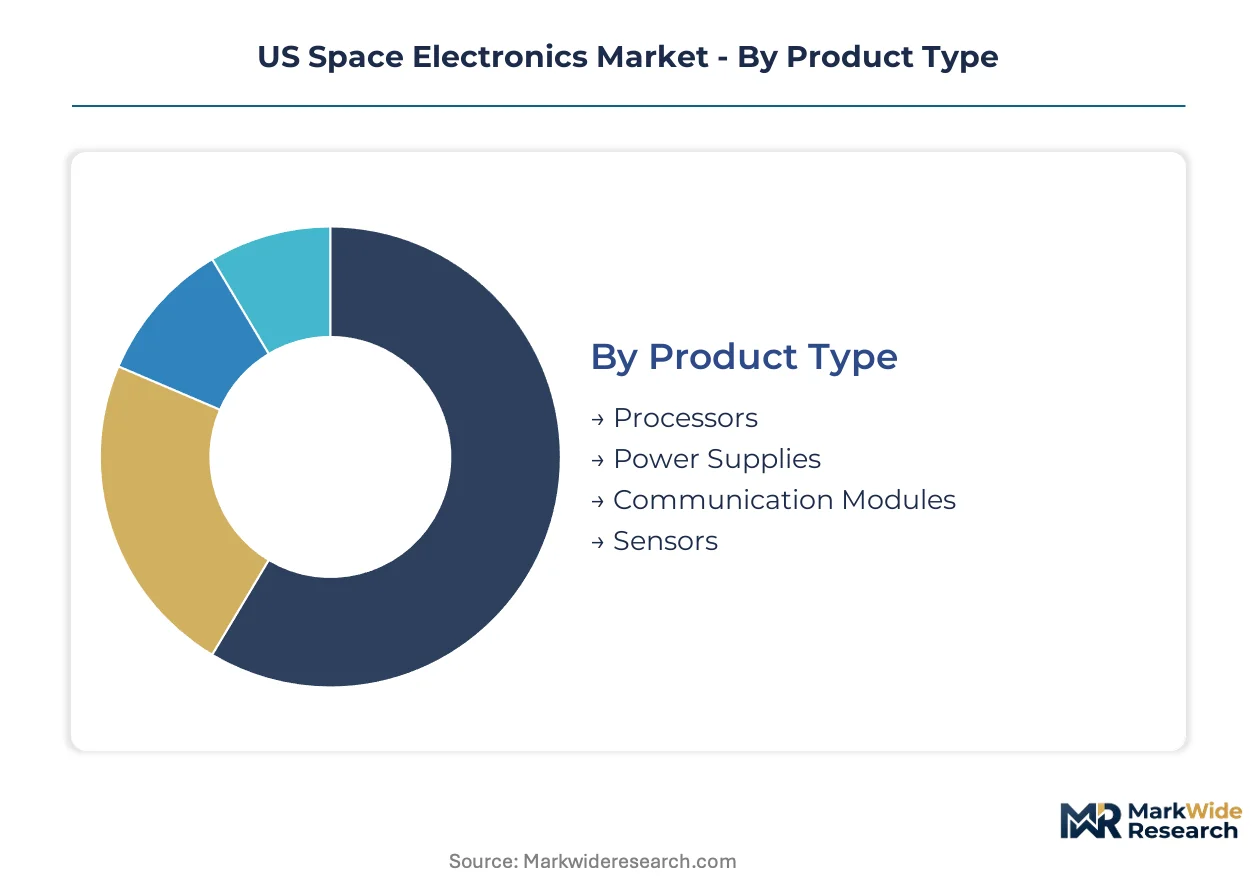
US space electronics procurement channels fragment sharply between defense prime contractors with captive qualification pathways and commercial operators sourcing through distributor networks. Understanding how each segment flows through these distinct channels determines supplier positioning and margin capture.
Product Type:
Prime contractors at Vandenberg Space Force Base and NASA JPL source processors and power supplies through direct vendor-managed inventory programs, while communication modules and sensors flow through specialized aerospace distributors serving smaller constellation operators.
- Processors:Radiation-hardened microcontrollers and system-on-chip architectures execute command, control, and payload processing functions under total ionizing dose thresholds exceeding 100 krad(Si). Demand clusters in California's aerospace corridor where Northrop Grumman and Lockheed Martin satellite programs anchor procurement volumes.
- Power Supplies:DC-DC converters and voltage regulators engineered for extreme temperature cycling stabilize spacecraft bus voltages across orbital thermal transits. Artemis program lunar lander contracts are accelerating qualification of high-efficiency gallium nitride topologies for deep-space missions.
- Communication Modules:RF transceivers and baseband processors enable telemetry and payload data downlink.
- Sensors:Earth observation constellations are driving imaging sensor procurement through batch manufacturing channels.
By volume, processors lead. By growth pace, sensors are expanding most quickly.
End User:
Cost tier stratification separates government agencies with multi-year qualification budgets from commercial operators prioritizing rapid deployment economics.
- Government Agencies:NASA and the Space Development Agency fund radiation-hardened component development through cost-plus contracts with extended qualification timelines. MIL-STD-883 screening protocols govern their procurement, creating flight heritage documentation that transfers to adjacent segments.
- Commercial Satellites:SpaceX and Amazon's Project Kuiper deploy radiation-tolerant COTS components at scale for missions under five years duration. FCC spectrum licensing requirements shape their communication subsystem procurement timing and vendor selection.
- Research Institutions:University-led CubeSat missions source through commercial distributors with limited radiation tolerance requirements.
- Defense Contractors:Prime contractors maintain captive semiconductor fabrication for strategic satellite programs.
Government agencies dominate absolute procurement value. Commercial satellites are climbing the fastest as constellation deployment accelerates.
Technology:
Application requirements dictate technology selection, with deep-space missions demanding hardened analog precision and low-Earth orbit autonomy favoring reconfigurable digital architectures.
- Analog:Precision voltage references and operational amplifiers maintain signal integrity across temperature extremes. Texas Instruments anchors this segment through high-reliability portfolios for power management subsystems.
- Digital:Microcontrollers and memory devices process telemetry and execute flight software. Neuromorphic computing substitution is beginning to displace traditional architectures in certain autonomy applications.
- Mixed-Signal:Data converters bridge sensor outputs to digital processing chains.
- FPGA:Microchip Technology specializes in radiation-tolerant offerings that differentiate from commodity aerospace parts through in-orbit reconfiguration capabilities.
Analog commands the steepest premium pricing. Digital is gaining share fastest as software-defined payloads proliferate.
Application:
Geographic concentration within the US varies by mission type, with California anchoring Earth observation development and Texas emerging for human spaceflight electronics.
- Satellite Communication:RF subsystems and baseband processors enable broadband constellations and military relay networks. FCC spectrum licensing reforms are tightening coordination requirements and extending pre-launch documentation timelines for commercial operators.
- Remote Sensing:Multispectral and synthetic aperture radar payloads drive sensor electronics demand. Modular payload interfaces are displacing custom-designed electronics stacks across Earth observation constellations in California's NewSpace cluster.
- Space Exploration:Deep-space-qualified components for lunar and Mars missions require extended lifecycle validation.
- Scientific Research:Heliophysics and astrophysics instruments demand specialized detector readout electronics.
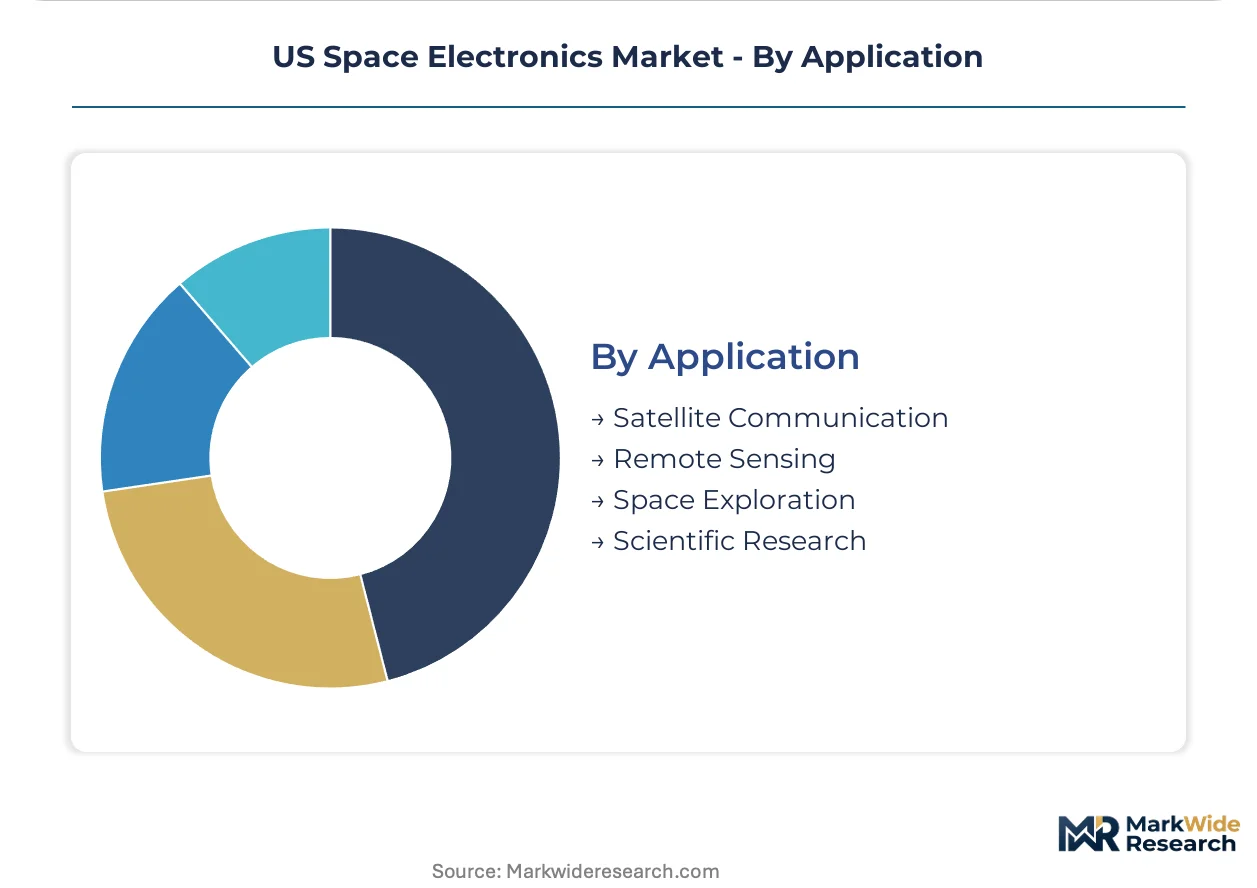
Satellite communication leads by installed base. Remote sensing shows the steepest expansion trajectory as Earth observation constellations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial satellite operators in low-Earth orbit constellations exhibit extreme price sensitivity, while NASA and Space Force procurement for deep-space missions tolerates substantial premiums for radiation-hardened qualification heritage.
California
Defense prime contractors cluster near Vandenberg Space Force Base and NASA JPL, driving concentrated demand for processors and power management systems. MIL-STD-883 screening protocols govern component qualification for strategic satellite programs. The aerospace corridor from Los Angeles to San Francisco hosts dense supplier ecosystems that enable rapid design iteration for Earth observation constellations.
Texas
CHIPS Act incentives are attracting advanced packaging facilities that could anchor secondary supply nodes beyond California. The state's emerging role in human spaceflight electronics complements its existing semiconductor fabrication infrastructure. Houston's Johnson Space Center coordinates Artemis program requirements that accelerate qualification of gallium nitride power topologies for lunar missions.
Colorado
The Space Force's rapid acquisition pathways compress procurement cycles for tactical demonstration missions. National Institute of Standards and Technology facilities support radiation effects testing capabilities. The Denver-Boulder corridor concentrates emerging satellite operators seeking non-traditional vendor qualification for proliferated constellations.
Florida
Kennedy Space Center launch activity generates demand for ground support electronics and pre-flight component verification. The state's space coast anchors East Coast launch infrastructure that shapes timing for communication module procurement. Cape Canaveral proximity enables just-in-time delivery for satellite integration schedules.
Arizona
CHIPS Act subsidies are drawing advanced semiconductor packaging investments that complement California's fabrication concentration. The state's dry climate supports cleanroom operations for sensitive component assembly. Phoenix-Tucson corridor facilities are positioning to capture overflow demand from California's capacity-constrained radiation-hardened foundries.
US Space Electronics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across component categories and qualification pathways. Captive semiconductor fabrication distinguishes prime contractors with sustained program commitments, while fabless specialists compete through radiation-tolerant FPGA and high-reliability analog portfolios. Three archetypes dominate: vertically integrated defense primes, diversified analog semiconductor suppliers, and radiation-tolerant programmable logic specialists. Competitive moves concentrate on strategic partnerships for accelerated qualification and geographic expansion of advanced packaging capacity.
Within the integrated prime tier, Northrop Grumman Corporation exemplifies captive fabrication strategies that sustain long-term satellite commitments. Texas Instruments occupies a position among diversified analog suppliers anchoring power management subsystems. Microchip Technology represents the programmable logic specialist archetype with radiation-tolerant FPGA offerings. These three entities collectively illustrate how qualification heritage and manufacturing control define competitive positioning in radiation-hardened procurement.
| Leading Market Players |
|---|
| Honeywell International |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| BAE Systems |
| Texas Instruments |
| Microchip Technology |
| Teledyne Technologies |
| Astronics Corporation |
| TT Electronics |
| Others |
Pricing and Supply Chain Analysis
MIL-STD-883 screening protocols govern component qualification while simultaneously stratifying price tiers, creating a dual-gate mechanism where radiation-hardened certification heritage commands substantial premiums over radiation-tolerant alternatives. This regulatory framework concentrates pricing power among domestic suppliers with captive fabrication capabilities, while commercial constellation operators absorb cost compression through COTS substitution.
Pricing Analysis
After-sales service contracts and extended qualification support generate lifetime value multiples exceeding initial component sales for radiation-hardened suppliers. Three-tier pricing structure across heritage-certified, radiation-tolerant, and commercial-off-the-shelf levels reflects total ionizing dose thresholds and mission-critical application requirements. Pricing pressure stems from SpaceX and Amazon's Project Kuiper deploying COTS components at scale for sub-five-year missions. Commercial satellite operators exhibit extreme price sensitivity, while NASA Artemis program procurement tolerates substantial premiums for deep-space qualification heritage.
Supply Chain Analysis
The United States anchors radiation-hardened semiconductor fabrication through captive facilities at Northrop Grumman and legacy defense contractors, while Taiwan and South Korea supply advanced packaging for commercial-grade components. Domestic foundry capacity draws from specialized substrate materials and precision analog process nodes unavailable through standard commercial channels. Single-source vulnerability concentrates in gallium arsenide and silicon carbide substrate supply for high-reliability power management systems. Distribution runs through direct vendor-managed inventory programs for prime contractors and specialized aerospace distributors serving constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Space Electronics Market exhibits cyclical recovery characteristics anchored to Department of Defense procurement cycles and NASA program milestone acceleration. Defense budget authorization patterns and proliferated-constellation contract awards create predictable demand waves across qualification-dependent supplier tiers.
For Market Incumbents: Fortify captive fabrication capacity through CHIPS Act facility expansion in Texas and Arizona, securing substrate supply agreements before gallium nitride process node competition intensifies. Deepen radiation effects engineering talent pipelines through university partnerships addressing workforce aging at legacy contractors. Lock in multi-year Artemis program vendor-managed inventory commitments before rapid acquisition pathways enable non-traditional supplier qualification. For New Entrants and Emerging Players: Radiation-tolerant FPGA configuration services represent an underserved layer where incumbents prioritize hardware sales over software enablement. Target Colorado's Denver-Boulder corridor satellite operators seeking accelerated qualification for Space Development Agency proliferated-constellation contracts. Establish technical service partnerships with university CubeSat programs to build flight heritage documentation transferable to commercial missions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed aerospace component distributors holding MIL-STD-883 screening infrastructure. Five-to-ten-year viability hinges on CHIPS Act geographic diversification success and neuromorphic computing substitution pace. Monitor Space Force rapid acquisition pathway contract velocity as inflection indicator for non-traditional vendor market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CHIPS Act Facility Expansion | Texas and Arizona advanced packaging investments reduce California aerospace corridor concentration risk. |
| Radiation Effects Engineering Pipeline Development | University partnerships address workforce aging at legacy defense contractors concentrated near Vandenberg. |
| Rapid Acquisition Pathway Qualification | Space Force alternative contracting mechanisms compress procurement cycles for tactical demonstration missions. |
| Neuromorphic Computing Architecture Investment | Radiation-tolerant neural processing displaces traditional FPGA command and control in autonomy applications. |
| On-Orbit Servicing Electronics Development | Satellite life extension and debris removal missions create sensor categories absent from traditional specifications. |
Research Methodology
Desk research of NASA program documentation, Department of Defense procurement databases, and FCC spectrum licensing records preceded structured interviews with radiation effects engineers, satellite program managers, and aerospace distributor procurement leads. Primary fieldwork with Space Development Agency contracting officers and commercial constellation operators combined with secondary validation through MIL-STD-883 qualification databases and CHIPS Act facility announcement filings. Bottom-up component demand modeling and top-down program budget allocation analysis provided triangulation across independent estimation approaches.
Variance decomposition across product type, end-user tier, technology architecture, and application mission profile shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include radiation tolerance grade, procurement channel structure, and geographic supply node concentration. CAGRs derived from program milestone timing, constellation deployment schedules, and qualification backlog conversion rates. Forecast inputs incorporated Artemis program hardware requirements and Space Force rapid acquisition contract velocity indices.
Forecasts assume regulatory continuity in FCC spectrum licensing procedures and NASA-STD-8739 manufacturing requirements; material policy shifts would require re-modeling of commercial satellite operator procurement timing. Specific risks include CHIPS Act facility construction delays, neuromorphic computing substitution acceleration, and Space Development Agency contract award volatility. Recalibration cycles align with material shifts in defense authorization appropriations and proliferated-constellation deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Deep Space Robotics Market
Space
Space Service Market
Space
Space Debris Monitoring and Removal Market
Space
Orbital Spaceflight Market
Space
Asteroid Mining Market
Space
LAMEA Space As a Service Market
Space
Italy Space Electronics Market
Space
Spacecraft Market
Space
Rocket Launchpad Market
Space
US Reusable Launch Vehicle Market
Space
US Space Launch Services Market
Space
Space Mobile Service Market
Space
Space Management Solutions Market
Space
South Korea Space Electronics Market
Space
UK Space Electronics Market
Space
Deep Space Exploration Market