
 Reusable Launch Vehicles Market | 2026-2036
Reusable Launch Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Launch Vehicles Market Outlook
Aerospace engineering talent scarcity is reorganizing how launch providers structure apprenticeship pipelines and university partnerships. SpaceX leverages its Hawthorne manufacturing campus to sustain vertical integration across engine and airframe production. Blue Origin anchors its workforce strategy around Huntsville propulsion test facilities. Rocket Lab competes through specialized carbon-composite structures and rapid electron refurbishment cycles.
Reusable launch vehicles are spacecraft or booster stages engineered for multiple flight missions through thermal protection systems, propulsive landing architectures, and engine reignition capabilities, primarily reducing per-kilogram payload costs for orbital and suborbital access. The vehicle type dimension shows rocket boosters capturing dominant flight volume while spaceplane architectures attract premium development investment for crew rotation missions. Technology segmentation reveals vertical takeoff and landing as the mature operational standard, with boost-back maneuvers gaining traction for geostationary transfer orbit recoveries where downrange landing infrastructure exists.
FAA launch licensing, EPA National Environmental Policy Act reviews, and FCC spectrum coordination collectively govern U.S. flight cadence and site expansion, creating compliance timelines that directly gate revenue realization for new vehicle programs. China's SAMR and MEE administer analogous environmental and safety clearances for CASC flight operations from Jiuquan and Wenchang. Stakeholders must monitor how regulator staffing levels and interagency coordination protocols evolve relative to announced flight manifest growth.
Market Dynamics
Flight-proven booster recovery is compressing per-launch economics and forcing incumbents to restructure capital deployment around rapid reuse cadence rather than expendable manufacturing scale.
Growth Catalysts
- LEO constellation deployment:Satellite operators in the United States and China are contracting dedicated rideshare missions that reward rapid turnaround. Reusable architectures align payload batching with orbital plane phasing requirements.
- FAA streamlined licensing:The Part 450 regulatory framework is consolidating experimental permits and launch licenses into unified operational authorizations. This reduces pre-flight administrative lead time for mature vehicle configurations.
- Propulsion test infrastructure:Vertical test stands at McGregor, Texas and Wenchang, Hainan are enabling concurrent engine qualification campaigns. Parallel hot-fire programs accelerate vehicle maturity without flight-risk exposure.
Market Restraints
- Thermal protection system refurbishment:Ablative and ceramic matrix composite heat shields require labor-intensive inspection between flights. Turnaround bottlenecks concentrate at specialized subcontractor facilities in California and Florida.
- Range scheduling congestion:Eastern and Western Range availability at Cape Canaveral and Vandenberg is allocated years in advance. New entrants face manifest gaps that delay revenue-generating flights regardless of vehicle readiness.
- Liquid oxygen supply volatility:Cryogenic propellant production capacity is tightening in Texas and Louisiana due to industrial gas competition from healthcare and semiconductor sectors. Spot pricing fluctuations compress margin predictability.
Strategic Opportunities
- India's Gaganyaan crew program:ISRO's human-rated vehicle development is creating demand for domestic reusable crew capsule recovery systems. Technology transfer partnerships with established providers are under negotiation.
- Point-to-point suborbital cargo:Military and express logistics buyers are evaluating Mach 5+ delivery timelines for critical spare parts. Regulatory frameworks for overflight rights remain underdeveloped, creating first-mover positioning potential.
- In-orbit servicing convergence:Rendezvous and proximity operations capabilities developed for booster landing are transferring to satellite life-extension missions. Dual-use engineering amortizes development across addressable markets.
Industry Challenges
- Turbomachinery welding expertise:Full-flow staged combustion engine production requires electron beam and friction stir welding skills concentrated at a handful of defense-aerospace suppliers. Workforce pipeline expansion lags vehicle program staffing demands.
- Range safety certification:Autonomous flight termination systems must demonstrate false-alarm rates below one per million flight-seconds. Validation campaigns consume substantial telemetry and ground infrastructure resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Launch Vehicles Market |
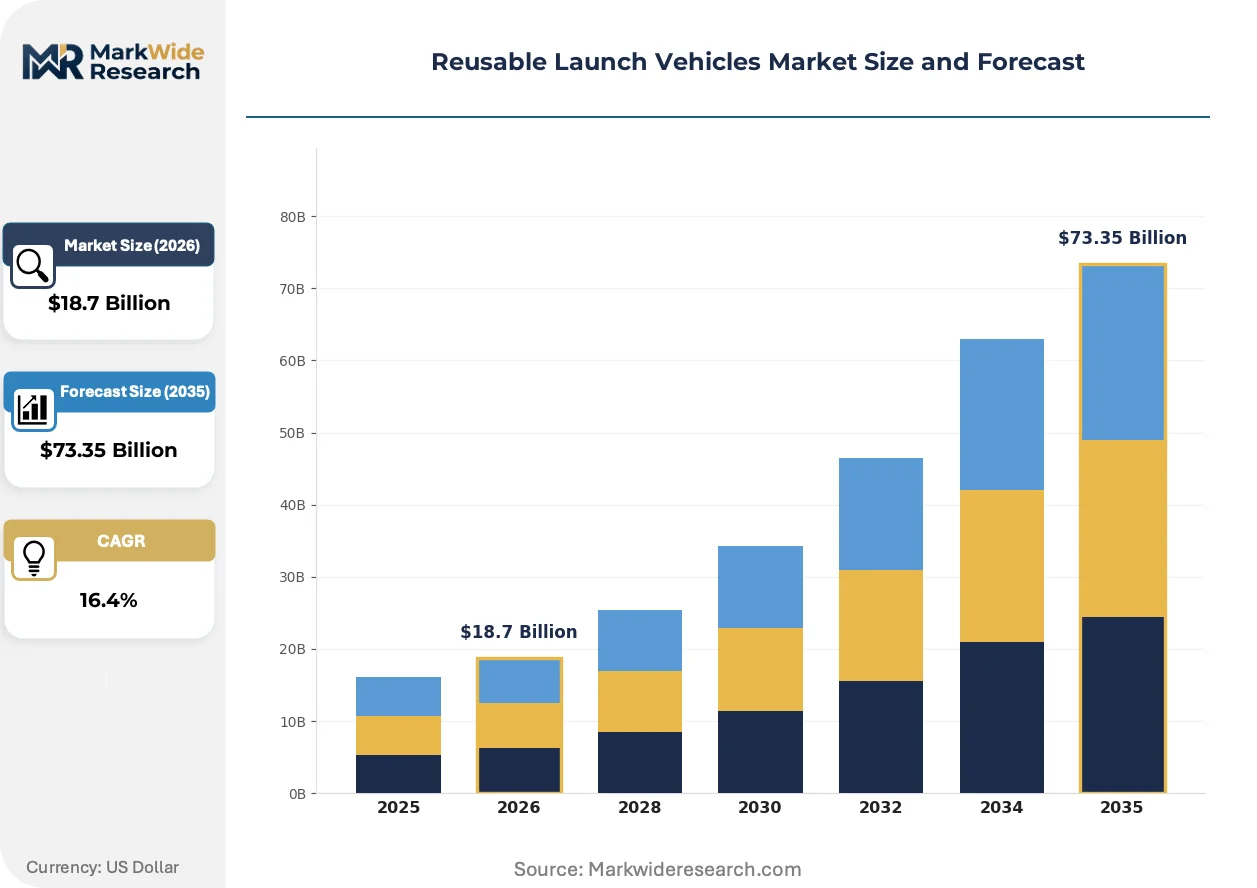
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Spaceplane, Rocket Booster, Orbital Launch System, Suborbital Vehicle Technology: Vertical Takeoff and Landing, Horizontal Landing, Reusable Engines, Boost-Back Service Type: Satellite Deployment, Cargo Delivery, Space Tourism, Research Missions End User: Government Agencies, Private Companies, Research Institutions, Commercial Providers |
| Companies Covered | SpaceX, Blue Origin, Rocket Lab, ArianeGroup, Relativity Space, United Launch Alliance, China Aerospace Science and Technology Corporation, ISRO, Firefly Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Launch Vehicles Market Strategic Shifts
Reusable launch vehicle development is pivoting from demonstration flights toward operational cadence optimization, with engineering resources concentrating on turnaround interval compression and subsystem modularity.
Carbon-composite cryotank structures are replacing aluminum-lithium alloys in upper stages and intertanks. Launch providers in the United States are qualifying filament-wound pressure vessels for liquid methane storage. This material transition is miniaturizing structural mass fractions while maintaining propellant capacity, enabling heavier payloads without booster scale-up.
China's SAMR and MEE are implementing enhanced environmental review protocols for coastal launch sites. The Wenchang Spacecraft Launch Site now requires marine ecosystem impact assessments for every flight manifest expansion. CASC is responding by relocating propellant loading operations to reduce coastal contamination exposure during countdown sequences.
Constellation operators are unbundling launch procurement from satellite manufacturing, contracting directly with launch brokers rather than turnkey system integrators. This disintermediation is compressing contract negotiation cycles and transferring mission assurance liability to launch providers. The shift is most pronounced among broadband constellation deployers in the United States seeking schedule flexibility for orbital plane population.
Reusable Launch Vehicles Market Segmentation
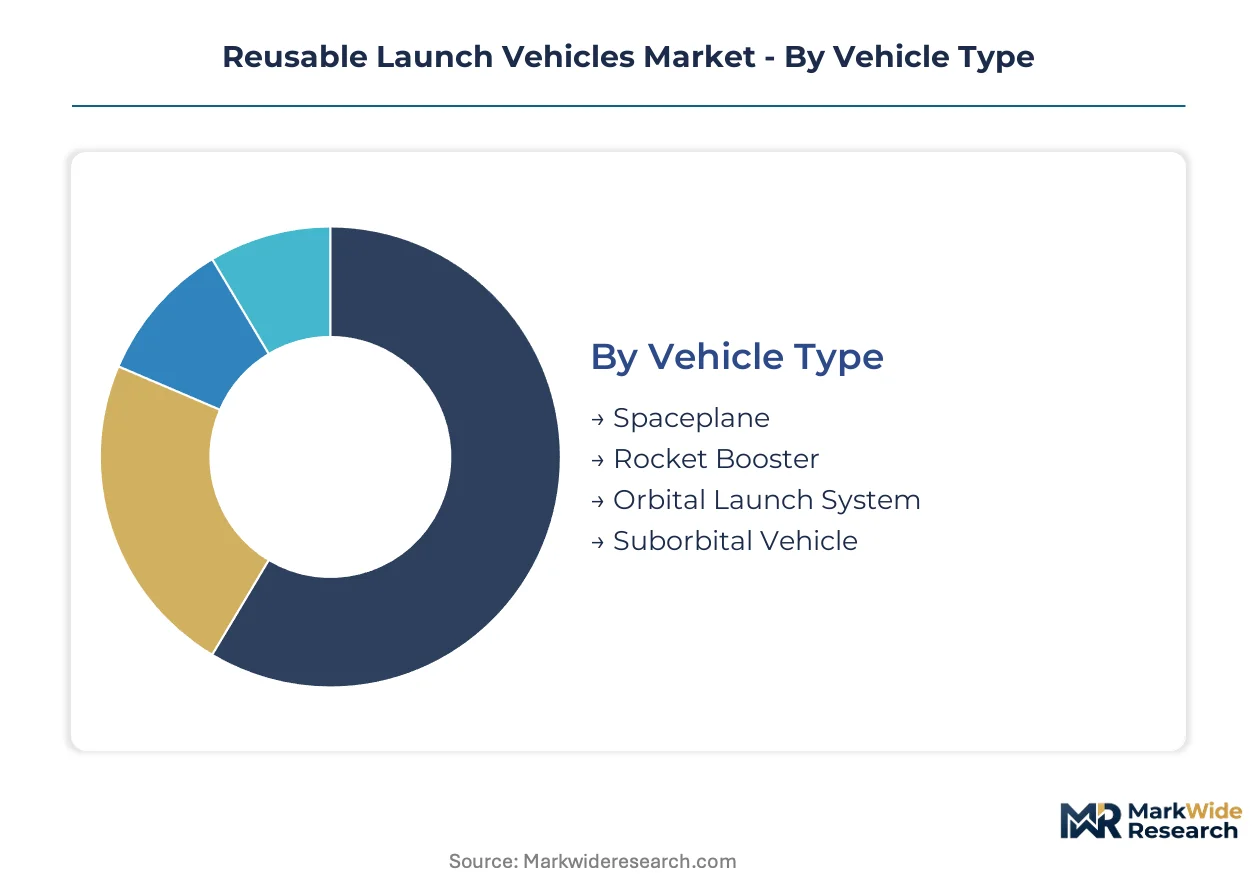
Reusable launch vehicle procurement decisions hinge on mission velocity requirements, payload mass envelopes, and regulatory certification pathways. Each segmentation dimension captures distinct technical trade-offs that govern operator selection criteria and manufacturer development priorities.
Vehicle Type:
FAA Part 450 licensing distinguishes crew-rated architectures from cargo-only systems through separate flightworthiness demonstration requirements.
- Rocket Booster:Propulsive landing architectures with grid fin aerodynamic control and engine reignition capability dominate commercial flight volume. United States launch providers concentrate recovery operations at Cape Canaveral and Vandenberg to minimize downrange logistics.
- Spaceplane:Winged re-entry vehicles with thermal protection system integration enable runway landing precision for crew rotation missions. Development investment clusters around human-rated certification timelines for orbital crew transport contracts.
- Orbital Launch System:Complete stack reusability combining booster and upper stage recovery remains in demonstration phase.
- Suborbital Vehicle:Single-stage systems with parachute or propulsive landing support microgravity research and point-to-point cargo evaluation.
Established volume favors Rocket Booster; emerging adoption favors Spaceplane.
Technology:
Propulsion architecture selection directly determines landing precision requirements and ground infrastructure investment profiles.
- Vertical Takeoff and Landing:Engine-throttled descent with landing leg deployment represents the operational standard for orbital-class recovery. China and the United States both maintain dedicated landing zones at Jiuquan and Cape Canaveral respectively.
- Boost-Back:Propulsive return-to-launch-site maneuvers enable geostationary transfer orbit missions with booster recovery. Downrange landing infrastructure at Vandenberg and Wenchang supports this trajectory optimization.
- Horizontal Landing:Winged re-entry with runway touchdown requires extensive thermal protection system refurbishment between flights.
- Reusable Engines:Full-flow staged combustion and gas generator cycle designs prioritize multiple ignition capability over specific impulse maximization.
Operational maturity concentrates in Vertical Takeoff and Landing; steepest expansion trajectory appears in Boost-Back.
Service Type:
Contract structure complexity varies with payload integration timelines and mission assurance liability allocation.
- Satellite Deployment:Constellation batch launches with dedicated rideshare sequencing generate recurring revenue through multi-manifest contracts. LEO broadband operators in the United States and China drive demand concentration for rapid turnaround cadence.
- Cargo Delivery:Pressurized and unpressurized logistics modules for orbital station resupply require NASA Commercial Resupply Services certification or analogous Chinese space station agreements.
- Space Tourism:Suborbital passenger flights carry distinct FAA human spaceflight informed consent requirements separate from orbital crew transport regulations.
- Research Missions:Microgravity experiment hosting and technology demonstration payloads prioritize schedule flexibility over cost minimization.
Revenue scale currently anchors Satellite Deployment; margin expansion potential concentrates in Space Tourism.
End User:
Procurement authority and mission assurance standards diver sharply between sovereign space programs and commercial operators.
- Government Agencies:NASA, CASC, and ISRO maintain dedicated launch manifests with stringent reliability requirements and domestic preference provisions. National security payloads impose additional encryption and supply chain verification protocols.
- Private Companies:Constellation operators and commercial station developers negotiate fixed-price launch services with schedule penalty clauses. Contracting directly with launch brokers rather than system integrators is compressing negotiation cycles.
- Research Institutions:University and laboratory payloads access subsidized rideshare opportunities through NASA's CubeSat Launch Initiative and comparable Chinese academy programs.
- Commercial Providers:Launch brokers and satellite manufacturers bundling launch with spacecraft production face consolidated liability exposure.
Contract volume leadership sits with Government Agencies; procurement velocity is accelerating fastest among Private Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Launch vehicle consumption patterns diverge sharply by geography: the United States prioritizes rapid reuse cadence for constellation deployment, China emphasizes state-directed vertical integration for sovereign access, and India concentrates on crew-rated system development with technology transfer partnerships.
United States
LEO broadband constellation operators drive launch procurement velocity through dedicated rideshare missions. FAA Part 450 licensing consolidates experimental permits and operational authorizations to compress pre-flight timelines. Hawthorne, California anchors vertical integration across engine and airframe production at SpaceX's manufacturing campus.
China
National space program expansion at CASC sustains flight-proven hardware scaling for space station logistics and lunar architecture. SAMR and MEE administer environmental and safety clearances with enhanced marine ecosystem protocols at Wenchang. Hainan Island concentrates propellant loading operations relocated to reduce coastal contamination exposure.
India
ISRO's Gaganyaan crew program generates demand for domestic reusable crew capsule recovery systems. Technology transfer negotiations with established providers shape procurement frameworks for human-rated vehicle development. Sriharikota launch complex supports concurrent satellite deployment and crew vehicle qualification campaigns.
Japan
Commercial satellite operators and government Earth observation programs sustain modest but steady launch demand. METI coordinates industrial policy supporting domestic propulsion component suppliers and materials specialists. Tanegashima and Uchinoura space centers maintain range infrastructure with limited expansion capacity.
Germany
ArianeGroup's launch system development anchors European reusable vehicle investment, with German engineering centers contributing propulsion and structures expertise. National space agency DLR channels R&D funding toward reusable upper stage technologies. Bavaria and Bremen host specialized subcontractors for turbomachinery and thermal protection systems.
Reusable Launch Vehicles Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the reusable launch vehicles market. The upper tier controls end-to-end manufacturing through captive engine production and recovery infrastructure ownership. Specialist competitors concentrate on carbon-composite structures, rapid refurbishment cycles, or regional launch site access. Dominant competitive moves include vertical integration into propulsion test infrastructure and strategic site licensing at Eastern and Western Range facilities.
Within the integrated leader archetype, SpaceX exemplifies rapid reuse cadence through Hawthorne manufacturing concentration and McGregor test stand ownership. Blue Origin occupies a position emphasizing Huntsville propulsion facilities and vertical landing architecture development. Rocket Lab represents the specialist tier through carbon-composite airframe expertise and Electron refurbishment cycle compression. These three anchors illustrate how geographic clustering around test infrastructure and manufacturing campuses shapes competitive differentiation.
| Leading Market Players |
|---|
| SpaceX |
| Blue Origin |
| Rocket Lab |
| ArianeGroup |
| Relativity Space |
| United Launch Alliance |
| China Aerospace Science and Technology Corporation |
| ISRO |
| Firefly Aerospace |
| Others |
Value Chain & Pricing Dynamics
Fixed-price launch service agreements with multi-flight block commitments lock in both propellant supply access and per-kilogram price visibility for constellation operators. These contract structures transfer mission assurance liability to launch providers while insulating buyers from liquid oxygen spot market volatility in Texas and Louisiana.
Pricing Analysis
Long-term offtake contracts dominate the procurement landscape, with LEO constellation operators securing dedicated rideshare missions through multi-manifest block purchases. Price differentiation hinges on flight-proven booster heritage and FAA Part 450 certification tier, with human-rated missions commanding substantial premiums over cargo-only configurations. Cost compression in the rideshare tier is intensifying as Rocket Lab and Firefly Aerospace compress Electron and Alpha refurbishment cycles. Government agencies exhibit lowest price sensitivity due to mission assurance requirements, while research institutions accessing NASA's CubeSat Launch Initiative represent the most price-constrained buyer segment.
Supply Chain Analysis
Inventory lead times for turbomachinery components now stretch 18-24 months due to electron beam welding capacity constraints at specialized defense-aerospace suppliers. Manufacturing concentrates in the United States, China, and Germany, with Hawthorne, Wenchang, and Bremen anchoring distinct propulsion and structures ecosystems. The supply chain draws from nickel-based superalloys, carbon-fiber prepreg, and cryogenic propellant production networks. Single-source vulnerability in full-flow staged combustion engine fabrication poses structural risk. Distribution runs through direct OEM procurement with minimal intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive returns as launch providers bundle satellite deployment with in-orbit servicing capabilities. Interoperability between booster landing architectures and rendezvous proximity operations creates cross-market leverage previously isolated to single revenue streams.
For Market Incumbents: Secure exclusive range scheduling allocations at Cape Canaveral and Vandenberg to gate new entrant manifest access. Deepen in-house production of thermal protection system components to reduce turnaround bottlenecks at California and Florida subcontractor facilities. The emerging threat of Chinese state-subsidized launch pricing demands captive propellant supply integration.
For New Entrants and Emerging Players: FAA Part 450 streamlined certification fast-tracks market entry for mature vehicle configurations derived from proven architectures. White-space concentrates in India's Gaganyaan crew program technology transfer partnerships and point-to-point suborbital cargo evaluation contracts. Target military express logistics buyers seeking Mach 5+ delivery timelines with regulatory-first go-to-market positioning.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive engine production and recovery infrastructure ownership. Long-term viability favors providers demonstrating operational cadence optimization rather than single-flight technical milestones. Watch for inflection when autonomous flight termination systems achieve sub-one-per-million false-alarm certification.
| Strategic Initiative | Industry Significance |
|---|---|
| Propulsion Test Infrastructure Expansion | McGregor and Wenchang test stand ownership accelerates engine qualification without flight-risk exposure. |
| Carbon-Composite Cryotank Qualification | Filament-wound liquid methane vessels reduce structural mass fractions for heavier payload capacity. |
| FAA Part 450 Certification Fast-Track | Unified operational authorizations compress pre-flight administrative lead time for new vehicle programs. |
| Downrange Landing Infrastructure Licensing | Vandenberg and Wenchang site control enables boost-back trajectory optimization for geostationary missions. |
| In-Orbit Servicing Capability Convergence | Rendezvous proximity operations transfer from booster landing to satellite life-extension revenue streams. |
Study Parameters
Operator-level perspectives from launch vehicle program managers, propulsion test engineers, constellation procurement leads, and FAA licensing officers anchored the qualitative base. Primary interviews with SpaceX Hawthorne manufacturing executives, Blue Origin Huntsville propulsion specialists, and ISRO Gaganyaan program directors combined with secondary validation from FAA launch license databases, SAMR environmental filing records, and ESA procurement disclosures. Bottom-up segment sizing triangulated against top-down market aggregation across vehicle type, technology, and service type dimensions.
Sensitivity analysis tested forecast robustness against range scheduling congestion scenarios and liquid oxygen supply volatility assumptions across the projection horizon. The analytical framework modeled vehicle type segmentation by reusability architecture, technology segmentation by landing mode, service type by payload integration complexity, and end user by procurement authority. CAGRs derived from flight cadence trajectory analysis and per-kilogram cost compression curves. Industry-specific inputs included FAA Part 450 implementation timelines and CASC Wenchang manifest expansion protocols.
Decision-makers should treat outputs as directional under assumed regulatory staffing growth and interagency coordination efficiency; material deviation in FAA licensing velocity or SAMR environmental review timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Lighting Market
Aircraft
America Attack Helicopter Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Aerospace Turbojet Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Firefighting Aircraft Market
Aircraft
Australia Aviation Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Latin America Business Jet Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Aircraft Control Surface Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
UK Aviation Market