
 US Remote Sensing Technology Market | 2026-2036
US Remote Sensing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
US Remote Sensing Technology Market Insights
Hyperspectral imaging and AI-driven analytics is rewriting how Earth observation data gets processed into actionable intelligence. Maxar Technologies leverages its satellite constellation and geospatial data archive to sustain leadership in high-resolution commercial imagery. Planet Labs PBC operates the largest fleet of Earth-imaging satellites and competes on daily global coverage frequency. L3Harris Technologies anchors defense-sector demand through classified sensor payloads and signals intelligence integration.
Remote sensing technology encompasses systems that detect and measure electromagnetic radiation reflected or emitted from Earth's surface, typically operating across spectral bands from ultraviolet to thermal infrared with spatial resolutions ranging from sub-meter to kilometer scale, serving purposes from crop health monitoring to missile warning networks. Active sensing and satellite-based deployment dominate revenue flows due to persistent Department of Defense and intelligence community budgets, while drone utilization and geospatial analysis represent the fastest-expanding segments as FAA Part 107 waivers proliferate and cloud-native processing cuts latency. Agriculture monitoring and environmental assessment applications attract growing private-sector investment as carbon credit verification and supply chain traceability standards tighten.
FAA regulations govern commercial drone operations and airspace integration, while NOAA and USGS set data standards for civilian Earth observation products, and NGA controls geospatial intelligence dissemination protocols for national security applications. These frameworks shape procurement eligibility, spectral data licensing terms, and cross-border data transfer restrictions that vendors must navigate. Stakeholders should monitor evolving classification guidelines for commercial satellite imagery and emerging EPA requirements for methane monitoring accuracy that will redefine sensor performance thresholds.
Market Dynamics
Federal procurement consolidation under the National Defense Authorization Act is concentrating contract eligibility among vendors with cleared facilities and domestic data processing infrastructure, squeezing mid-tier suppliers from defense-adjacent revenue streams.
Growth Catalysts
- Precision Agriculture Adoption:Large-scale farming operations across the Midwest Corn Belt are deploying multispectral sensors and variable-rate application systems to optimize nitrogen placement and irrigation scheduling.
- IRA Clean Energy Provisions:Federal tax credits for carbon monitoring infrastructure are accelerating investment in methane detection satellites and aerial verification platforms for oilfield and landfill operators.
- Hyperspectral Imaging Maturation:Sensor miniaturization and onboard processing advances are reducing payload costs for commercial smallsat constellations targeting mineral exploration and forest biomass assessment.
Market Restraints
- Launch Capacity Bottlenecks:Domestic heavy-lift availability constraints and Eastern Range scheduling limits are extending deployment timelines for constellation operators dependent on Space Coast facilities.
- ITAR Classification Friction:State Department jurisdiction over dual-use remote sensing components creates licensing delays that deter foreign capital participation in US-headquartered ventures.
- Radio Frequency Interference:C-band congestion from terrestrial 5G deployments is degrading synthetic aperture radar signal integrity in urban corridors and coastal zones.
Strategic Opportunities
- Wildfire Response Modernization:USDA Forest Service and state emergency management agencies are procuring thermal-infrared drone fleets for real-time perimeter mapping and hotspot detection during extended fire seasons.
- Offshore Wind Siting:Bureau of Ocean Energy Management mandates for pre-construction seabed surveys and operational bird-migration monitoring are opening dedicated procurement channels for lidar and radar sensor operators.
- AI-Assisted Analytics Convergence:Cloud-native machine learning pipelines trained on Planet Labs and Maxar imagery archives are collapsing time-to-insight for agricultural insurers and catastrophe modelers.
Industry Challenges
- Cleared Workforce Scarcity:Security clearance backlogs and STEM pipeline gaps in geospatial data science are constraining growth for firms pursuing classified NGA and NRO contracts.
- Sensor Calibration Drift:Orbital thermal cycling and radiation exposure degrade radiometric accuracy over mission lifetimes, requiring costly on-orbit reference cross-checks against NOAA ground targets.
- Legacy System Integration:Defense and intelligence community migration from stovepiped ground segment architectures to commercial cloud frameworks demands middleware development that few mid-size vendors can resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Remote Sensing Technology Market |
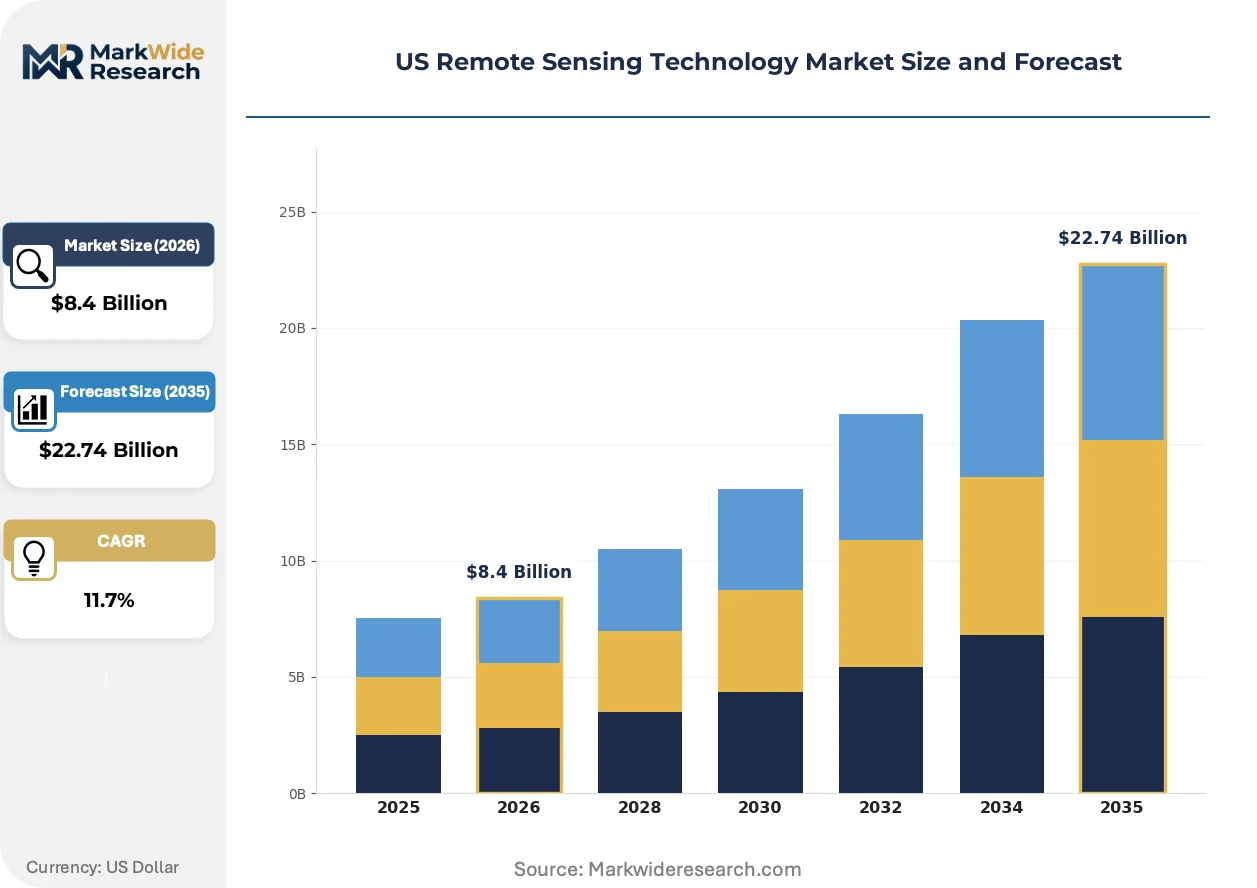
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active Sensing, Passive Sensing, Geospatial Analysis, Image Processing Application: Agriculture Monitoring, Environmental Assessment, Urban Planning, Defense and Security End User: Government Agencies, Research Institutions, Private Sector, NGOs Deployment: Satellite-Based, Aerial Platforms, Ground-Based, Drone Utilization |
| Companies Covered | Maxar Technologies, Planet Labs PBC, Teledyne Technologies Incorporated, Lockheed Martin Corporation, L3Harris Technologies, Esri, General Dynamics Mission Systems, Hexagon, Raytheon Technologies Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Remote Sensing Technology Market Trends and Innovations
Edge computing architectures and federated learning protocols are redistributing processing loads from centralized ground stations to orbital platforms and tactical field units, compressing decision latency for time-sensitive applications.
Small-form-factor hyperspectral sensors operating in 400-2500 nanometer bands are collapsing the cost floor for mineralogical mapping and agricultural stress detection, enabling county-level water district managers and independent agronomists to commission tasking orders previously reserved for federal agencies and major commodity traders.
EPA methane monitoring rules finalized under the Inflation Reduction Act are mandating quarterly aerial surveys for oil and gas production basins above specified throughput thresholds, forcing operators to contract satellite-based detection services or face escalating emissions fees that compound annually.
Subscription-based data access models are displacing per-scene licensing for commercial imagery, with California agricultural cooperatives and Texas energy midstream operators consolidating procurement through enterprise agreements that bundle archive access, tasking priority, and API-integrated analytics layers under single vendor relationships.
US Remote Sensing Technology Market Segmentation
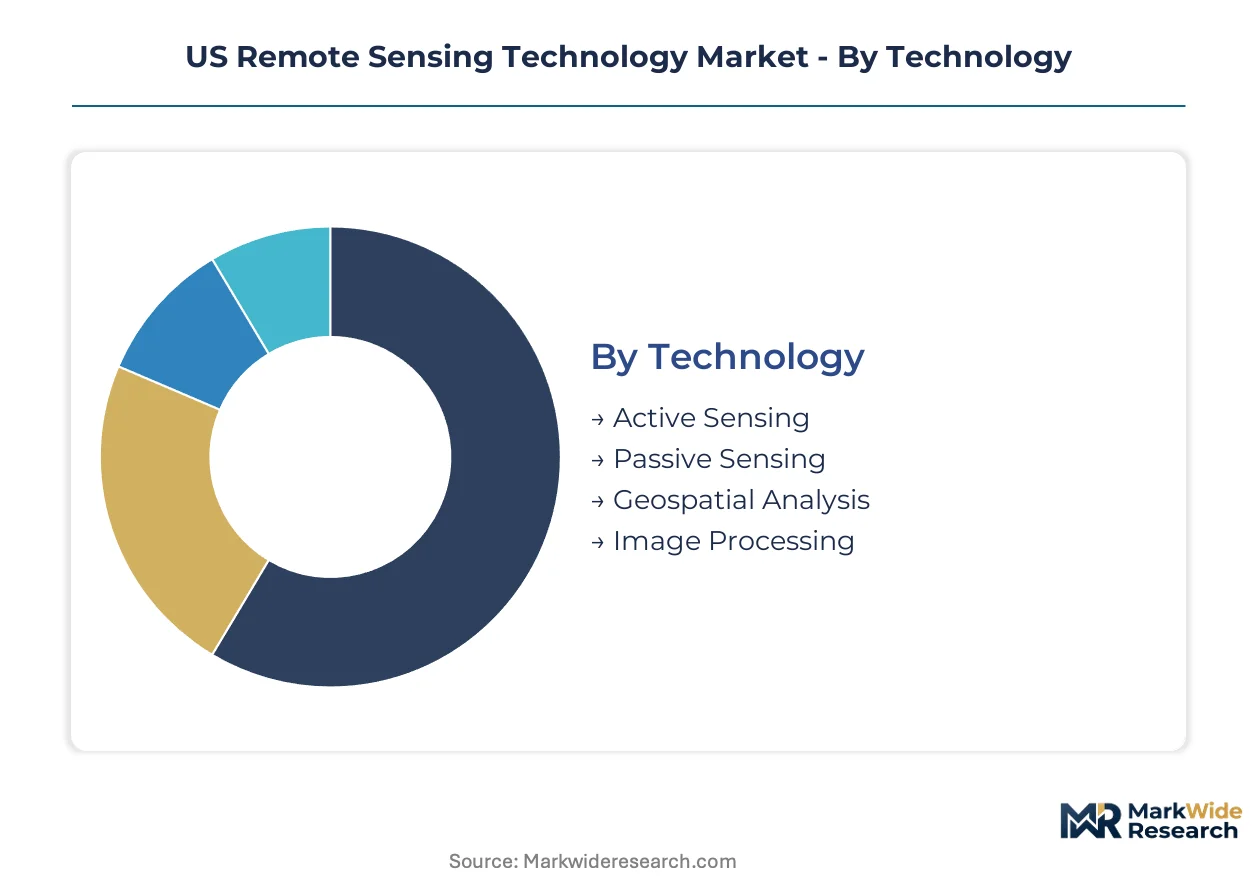
Segmentation reveals how procurement priorities diverge across federal, commercial, and research constituencies in the US remote sensing landscape. Technology choices and deployment modes reflect distinct budget cycles, security clearances, and data latency requirements that vendors must navigate simultaneously.
Technology:
Use-case spectrum spans classified missile warning networks to county-level water district management, with each technology tier serving distinct operational tempos and spectral precision requirements.
- Active Sensing:Lidar and synthetic aperture radar systems emit energy pulses to measure surface topography and structural deformation with millimetric accuracy. Department of Defense and intelligence community procurement concentrates here for all-weather, day-night surveillance capabilities against ITAR-controlled specifications.
- Passive Sensing:Multispectral and hyperspectral imagers capture reflected solar radiation across ultraviolet through thermal infrared bands. USDA and EPA contracts drive adoption for crop health indexing and methane plume detection under Inflation Reduction Act monitoring mandates.
- Geospatial Analysis:Cloud-native processing pipelines transform raw sensor feeds into actionable intelligence layers. Catastrophe modelers and agricultural insurers commission these services through API-integrated enterprise subscriptions.
- Image Processing:Onboard compression and radiometric correction algorithms extend mission lifetimes for smallsat operators facing orbital thermal cycling degradation.
Established volume favors Active Sensing; emerging adoption favors Geospatial Analysis.
Application:
Customer type dictates spectral resolution thresholds and revisit frequency requirements, with federal security applications demanding sub-meter accuracy while commercial agriculture tolerates coarser granularity for cost efficiency.
- Agriculture Monitoring:Variable-rate nitrogen placement and irrigation scheduling systems deploy multispectral sensors across Midwest Corn Belt operations. Large-scale farming cooperatives consolidate procurement through bundled archive access and tasking priority agreements.
- Environmental Assessment:Forest biomass quantification and carbon credit verification protocols rely on hyperspectral mineralogical mapping. EPA methane monitoring rules are accelerating satellite-based detection service contracts for Permian Basin operators.
- Urban Planning:Lidar-derived digital elevation models inform infrastructure resilience and flood risk mapping for municipal engineering departments.
- Defense and Security:Classified sensor payloads and signals intelligence integration anchor NGA and NRO procurement budgets with cleared facility requirements.
Defense and Security commands the dominant procurement dollar; Agriculture Monitoring climbs the fastest as precision farming scales beyond early adopters.
End User:
Budget authority and data classification levels segment procurement channels, with security clearance backlogs constraining vendor eligibility for intelligence community contracts.
- Government Agencies:USDA Forest Service thermal-infrared drone fleets, Bureau of Ocean Energy Management seabed surveys, and NOAA ground target calibration networks represent consolidated federal demand with multi-year appropriation cycles.
- Research Institutions:University-led smallsat missions and atmospheric chemistry studies access NASA Earth Science Division grant funding and shared ground station networks.
- Private Sector:California aerospace corridor firms and Texas energy midstream operators purchase enterprise imagery subscriptions for supply chain traceability and emissions compliance.
- NGOs:Conservation organizations commission tasking orders for protected area monitoring and illegal logging detection with limited procurement scale.
Government Agencies sustain the revenue base; Private Sector is expanding most quickly as carbon verification standards tighten.
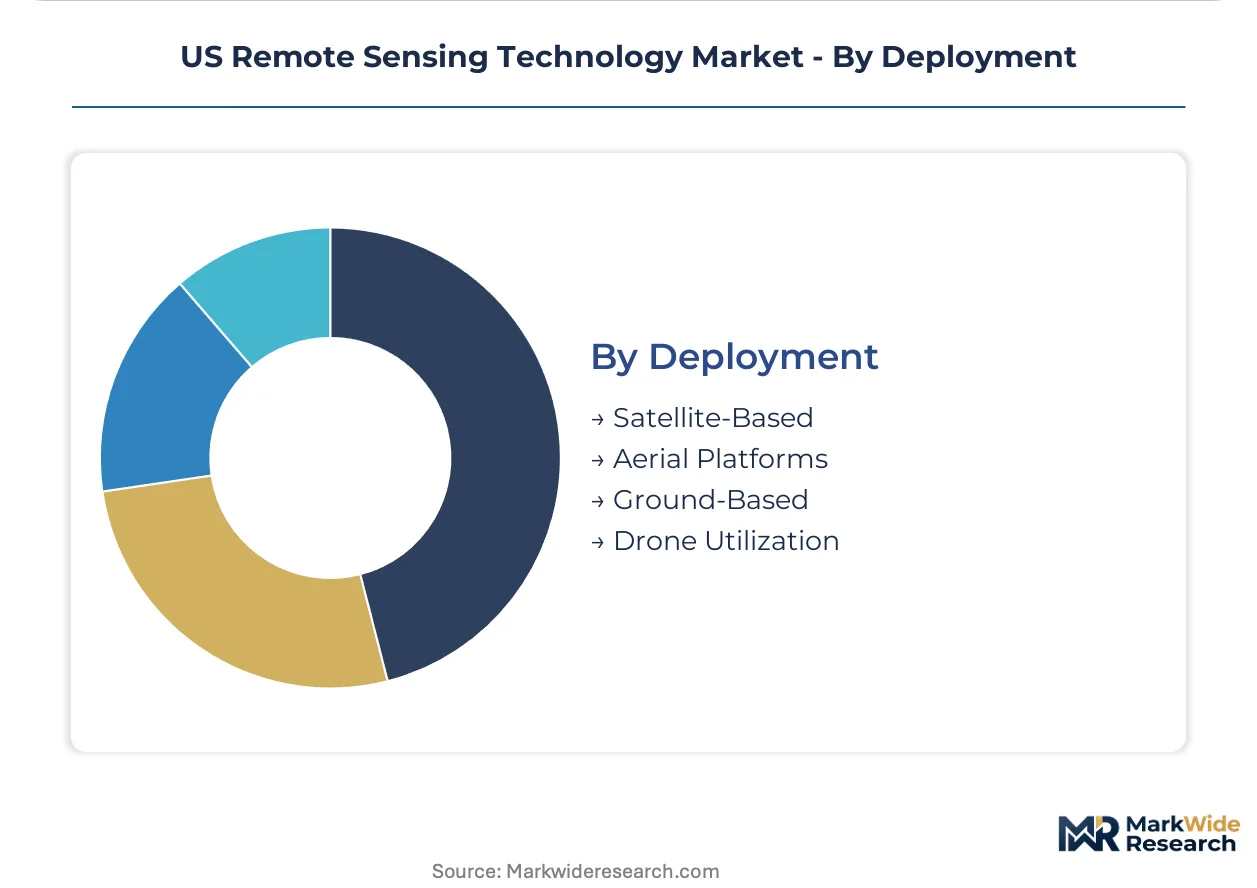
Deployment:
Altitude and persistence trade-offs define operational economics, with orbital platforms offering global coverage at capital-intensive scale and aerial systems delivering on-demand responsiveness.
- Satellite-Based:Constellation operators leverage daily global coverage frequency for agricultural stress detection and maritime surveillance. Launch capacity bottlenecks at Eastern Range facilities extend deployment timelines for new entrants.
- Drone Utilization:FAA Part 107 waivers proliferate for tactical field units requiring real-time perimeter mapping during extended fire seasons. Thermal-infrared payloads serve state emergency management agencies with compressed decision latency.
- Aerial Platforms:Manned aircraft host heavy lidar and radar sensors for pre-construction offshore wind siting surveys under BOEM mandates.
- Ground-Based:Fixed meteorological and seismic monitoring stations provide calibration reference data for orbital sensor drift correction.
Satellite-Based deployment captures the largest contract values; Drone Utilization shows steepest expansion trajectory as FAA airspace integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in coastal aerospace corridors while agricultural demand clusters across interior farming belts. Federal research funding flows toward university towns with established atmospheric science programs. Commercial satellite operators prioritize launch-adjacent real estate on the Space Coast.
California
Los Angeles-San Diego corridor hosts classified sensor payload development for NRO and NGA contracts. State climate mandates under SB 1383 drive methane monitoring procurement for oilfield operators in Kern County. JPL in Pasadena transfers dual-use imaging technology to commercial constellation operators.
Texas
Permian Basin oil and gas midstream operators contract satellite-based emissions verification under EPA IRA monitoring rules. FAA Houston Center coordinates Gulf Coast drone corridor development for offshore energy inspection. SpaceX Boca Chica launch activity accelerates smallsat deployment timelines for regional constellation ventures.
Colorado
USGS Earth Resources Observation and Science Center in Sioux Falls maintains calibration reference networks for orbital sensor drift correction. NOAA Boulder laboratories set radiometric standards civilian agencies adopt. Denver-Boulder metro concentration of geospatial software firms serves agricultural insurance and catastrophe modeling demand.
Virginia
NGA headquarters in Springfield concentrates cleared-facility requirements for intelligence community contracts. USDA Forest Service Eastern Region procures thermal-infrared drone fleets for Appalachian wildfire response. Hampton Roads NASA Langley Research Center advances lidar applications for offshore wind resource assessment.
Midwest Corn Belt
Iowa and Illinois large-scale farming cooperatives deploy multispectral sensors for variable-rate nitrogen placement. University of Minnesota remote sensing laboratories train agronomists in precision agriculture analytics. Chicago-based agricultural insurers integrate satellite-derived yield forecasts into policy pricing models.
US Remote Sensing Technology Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers. Federal defense contracts concentrate among cleared-facility holders with domestic data processing infrastructure, while commercial agriculture and environmental monitoring segments sustain mid-tier sensor operators and analytics specialists. Two strategic archetypes dominate: vertically integrated constellation operators controlling end-to-end data pipelines, and modular component suppliers feeding into prime contractor systems. Competitive moves center on security clearance acquisition for defense eligibility and cloud-native platform development for commercial subscription retention.
Within the constellation-operator archetype, Maxar Technologies and Planet Labs PBC occupy positions as anchor entities representing distinct coverage-frequency strategies. L3Harris Technologies exemplifies the defense-prime tier with cleared-facility concentration on classified payload integration. These three firms represent the structural segmentation between commercial imagery provision and national security system integration.
| Leading Market Players |
|---|
| Maxar Technologies |
| Planet Labs PBC |
| Teledyne Technologies Incorporated |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| Esri |
| General Dynamics Mission Systems |
| Hexagon |
| Raytheon Technologies Corporation |
| Others |
Pricing and Supply Chain Analysis
ITAR classification friction over dual-use remote sensing components determines both the premium tier spreads for cleared-facility vendors and the elongated supply chain shape that favors domestic data processing infrastructure over foreign capital participation.
Pricing Analysis
Cost-plus contracts with CPI indexation anchor federal procurement for classified sensor payloads, while commercial imagery shifts toward subscription SaaS tiers with API-integrated analytics bundling. Price differentiation hinges on security clearance tier and spectral resolution grade, with NGA-cleared vendors commanding substantial premiums over commercial-only operators. Pricing pressure stems from launch capacity bottlenecks extending deployment timelines and squeezing constellation operators' amortization schedules. Federal defense buyers show least price sensitivity given mission-critical requirements, whereas county-level water districts and independent agronomists face acute budget constraints on per-scene tasking orders.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become essential for smallsat component vendors navigating lengthy NRO procurement cycles. Manufacturing concentrates in the United States for ITAR-controlled payloads, draws from Taiwan and South Korea for radiation-hardened electronics, and rests on German precision optics for hyperspectral sensor cores. Critical dependencies include indium gallium arsenide detectors, synthetic aperture radar transmitters, and stabilized gimbal platforms. Single-source vulnerability runs through Eastern Range launch slots where Space Coast scheduling limits create chokepoints for constellation deployment. Distribution runs through cleared prime contractors for defense segments and direct enterprise sales for commercial agriculture subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
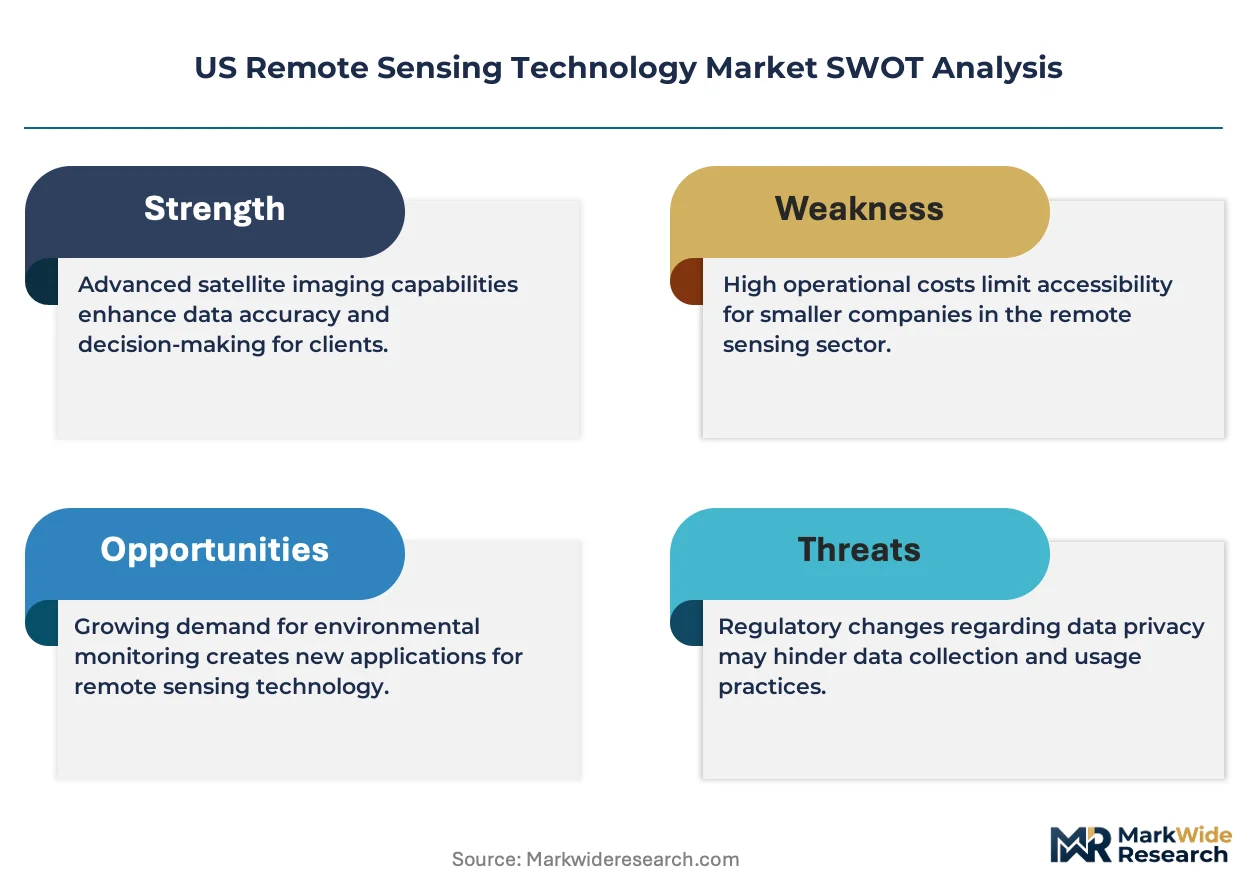
This market functions as a defensive-moat story where regulatory entrenchment through security clearance requirements and cleared-facility mandates creates substantial switching costs for federal customers.
For Market Incumbents: Entrench position by deepening backward integration into domestic satellite manufacturing to circumvent ITAR licensing delays and foreign component dependencies. Acquire cleared workforce capacity in geospatial data science to offset NGA contract backlogs. Counter emerging smallsat operators by locking multi-year enterprise subscription agreements with California agricultural cooperatives and Texas energy midstream operators before hyperspectral cost floors collapse further. For New Entrants and Emerging Players: Build out presence in methane monitoring verification services where EPA IRA rules create immediate demand from Permian Basin operators lacking incumbent relationships. Target USDA Forest Service thermal-infrared drone procurement where wildfire response modernization opens non-cleared procurement channels. Pursue county-level water district management as the most penetrable segment, offering tasking order marketplaces that bypass prime contractor markup structures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated constellation operators with end-to-end data pipeline control. Long-term viability over the coming decade rests on securing launch-adjacent real estate and domestic processing infrastructure as regulatory barriers intensify. Monitor Eastern Range capacity expansion announcements as the critical inflection signal for deployment timeline compression and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Security Clearance Acquisition | Unlocks NGA and NRO contract eligibility that anchors defense revenue stability. |
| Cloud-Native Analytics Platform Development | Enables API-integrated enterprise subscriptions that retain commercial agriculture buyers. |
| Hyperspectral Sensor Miniaturization | Collapses payload costs for smallsat constellations targeting mineral exploration contracts. |
| FAA Part 107 Operational Scale-Up | Accelerates drone utilization for wildfire response procurement from state emergency agencies. |
| Domestic Launch Infrastructure Investment | Mitigates Eastern Range scheduling bottlenecks constraining constellation deployment timelines. |
Research Methodology
Cross-validation between primary interviews and secondary data repositories anchors the qualitative findings on procurement pattern shifts. Conversations with NGA contracting officers, USDA precision agriculture specialists, commercial satellite operators, EPA methane monitoring enforcement leads, and FAA UAS integration managers informed demand-side dynamics. Secondary validation drew from National Defense Authorization Act procurement disclosures, NOAA radiometric standards documentation, SEC filings from publicly traded constellation operators, and Eastern Range launch manifests. Bottom-up segment sizing triangulated against top-down federal appropriation analysis.
Calibration against historical deployment timelines and spectral data licensing revenue flows shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology tier, application use-case, end-user budget authority, and deployment altitude with security clearance requirements. CAGRs derived from trend extrapolation of federal procurement consolidation, precision agriculture adoption curves, and methane monitoring mandate compliance schedules. Industry-specific inputs incorporated ITAR licensing delay distributions and FAA Part 107 waiver issuance rates.
Practitioners should monitor ITAR jurisdiction clarifications, EPA methane rule enforcement intensity, and Eastern Range capacity announcements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Japan Satellite Communication Market
Satellite
Russia Satellite Communications Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Europe Satellite Connectivity Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
GEO Satellite Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
UK Satellite Connectivity Market
Satellite
Low-Cost Satellite Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Global Broadband Satellite Services Market
Satellite
Germany Satellite Communications Market
Satellite
4K Satellite Broadcasting Market