
 Space Electronics Market | 2026-2036
Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Space Electronics Market Analysis
Component refurbishment revenue is reshaping margin distribution across the space electronics value chain, pulling profitability away from pure hardware sales toward lifecycle service models. RTX Corporation leverages its defense heritage to sustain long-term platform support contracts. Rocket Lab anchors New Zealand-originated launch-to-electronics verticality. L3Harris Technologies dominates mission-critical RF and communications payloads for government end users.
Space electronics encompasses radiation-hardened and high-reliability electronic subsystems engineered to operate across extreme temperature swings, vacuum conditions, and ionizing radiation doses measured in kilorads. These systems perform command, control, power management, and signal processing functions aboard spacecraft, launch vehicles, and orbital platforms where terrestrial-grade semiconductors would fail within hours. RF Electronics leads product type margins due to phased array antenna complexity and limited qualified supplier bases. Radiation-Hardened Components within the technology dimension command premium pricing as foundry capacity for qualified processes remains constrained. Commercial Satellites as an end user segment exhibits the steepest volume trajectory, though Defense Contractors retain higher average contract values.
NASA technical standards and ESA ECSS qualification regimes define radiation tolerance benchmarks and environmental testing protocols that gate market access for component vendors. FCC spectrum allocation proceedings and ITU coordination frameworks shape RF electronics demand by determining viable communication architectures for constellation operators. Stakeholders must track foundry qualification timelines and dual-use export control evolution as primary determinants of supply security and competitive positioning.
Market Dynamics
Commercial constellation operators are compressing procurement cycles and forcing component vendors to adapt qualification timelines originally designed for single-satellite missions toward batch-production economics.
Growth Catalysts
- LEO Broadband Constellation Deployments:Satellite operators are procuring radiation-hardened electronics in volumes that dwarf traditional geostationary programs, pulling foundry capacity toward commercial-grade qualification tiers.
- NASA Technical Standards Evolution:Relaxed heritage requirements for certain payload categories are opening qualification pathways for commercial semiconductor suppliers previously excluded from flight programs.
- Space Force Procurement Acceleration:US defense contracts are prioritizing rapid launch cadence over decade-long development cycles, compressing vendor selection and component delivery schedules.
Market Restraints
- Foundry Capacity Concentration:Qualified radiation-hardened fabrication lines concentrate at a handful of US and European facilities, creating single-source vulnerabilities for critical component categories.
- Dual-Use Export Control Friction:ITAR and EAR licensing requirements extend procurement timelines for international satellite operators and fragment supplier addressable markets.
- Technical Obsolescence Velocity:Commercial semiconductor process nodes advance faster than radiation-hardened qualification cycles, forcing designers to accept performance penalties or assume higher risk.
Strategic Opportunities
- India Launch Market Integration:ISRO's commercial arm and emerging private launch providers are creating captive demand for locally qualified electronics suppliers serving domestic and export missions.
- On-Orbit Servicing Electronics:Rendezvous, proximity operations, and docking subsystems represent an emerging application category with limited incumbent competition and premium pricing potential.
- Artemis Lunar Infrastructure:NASA's sustained lunar presence mandates electronics qualified for extreme thermal cycling and radiation environments beyond LEO experience bases.
Industry Challenges
- Radiation Effects Engineering Talent Scarcity:The specialized skill set spanning semiconductor physics, orbital mechanics, and failure analysis faces generational replacement gaps as experienced practitioners retire.
- Qualification Timeline Compression:ESA ECSS and NASA standards require extensive test campaigns that conflict with commercial constellation deployment schedules, forcing parallel risk acceptance strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Electronics Market |
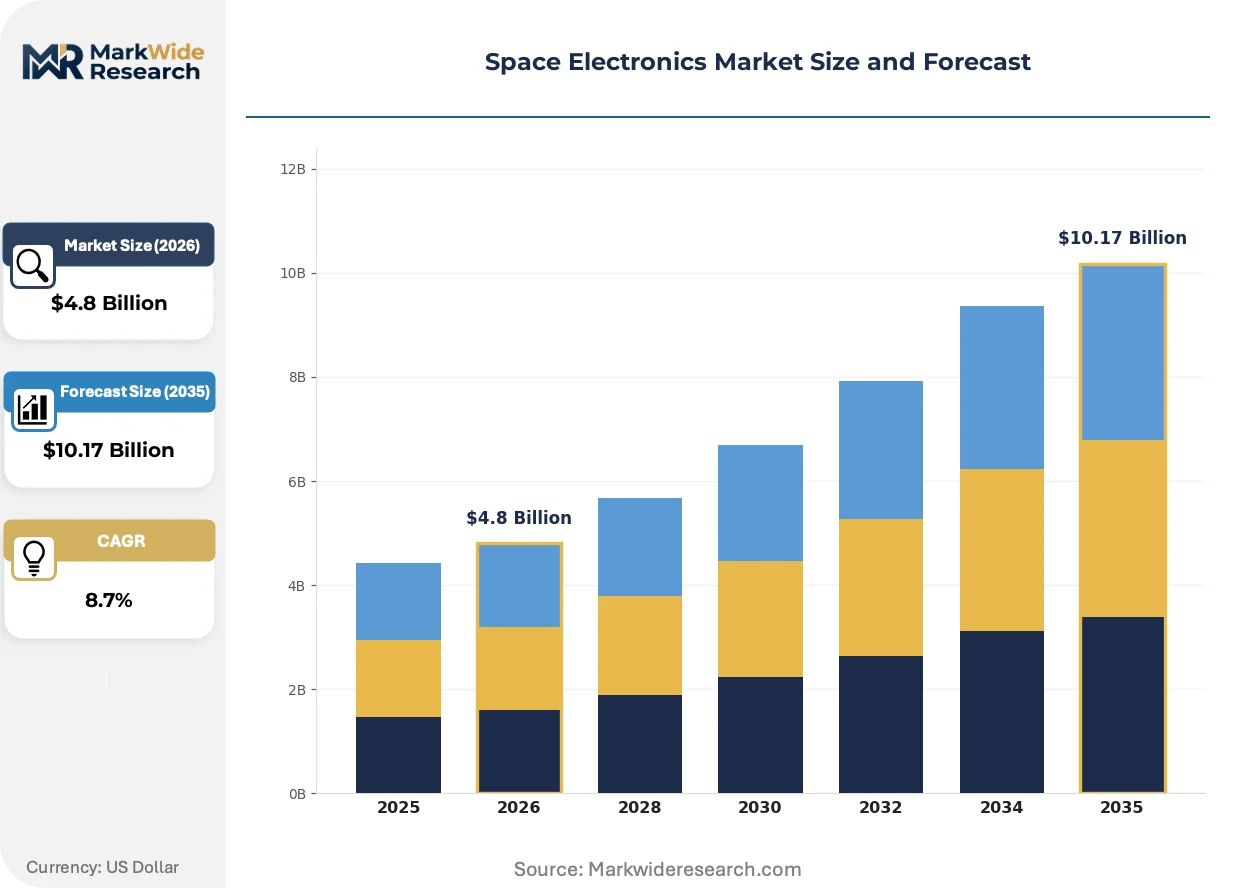
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Systems, Data Handling Units, RF Electronics, Payload Electronics End User: Aerospace Agencies, Commercial Satellites, Defense Contractors, Research Institutions Technology: Integrated Circuits, MEMS, Silicon Photonics, Radiation-Hardened Components Application: Satellite Communication, Space Exploration, Earth Observation, Scientific Research |
| Companies Covered | Rocket Lab, ArkEdge Space, RTX Corporation, Redwire, Seraphim Space, Northrop Grumman, IonQ, L3Harris Technologies, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Electronics Market Emerging Trajectories
Component architectures are fragmenting between heritage-qualified platforms and commercial-off-the-shelf adaptation strategies, with vendor selection criteria polarizing around mission-critical tolerance versus cost-optimized redundancy approaches.
Silicon carbide power electronics is migrating from terrestrial electric vehicle inverters toward satellite power conditioning units. LEO constellation prime contractors are qualifying SiC MOSFETs for bus voltage regulation at accelerated schedules. The technology is migrating from automotive volume production lines into space-qualified packaging through modified die-attach and hermetic sealing processes.
REACH substance restrictions are forcing reformulation of conformal coatings and solder alloys used in European-manufactured flight hardware. ESA suppliers must document full material composition down to 0.1% threshold for candidate list substances. RF component manufacturers serving both European institutional and commercial markets are dual-qualifying alternative metallization schemes to maintain cross-border shipment eligibility.
Prime contractors are unbundling long-term sustainment obligations from initial platform delivery contracts. Defense agencies and commercial operators now separately procure lifecycle electronics support, creating aftermarket service specialists. This pattern concentrates in United States government programs where Space Force and NASA are piloting performance-based logistics arrangements for operational satellite constellations.
Space Electronics Market Segmentation
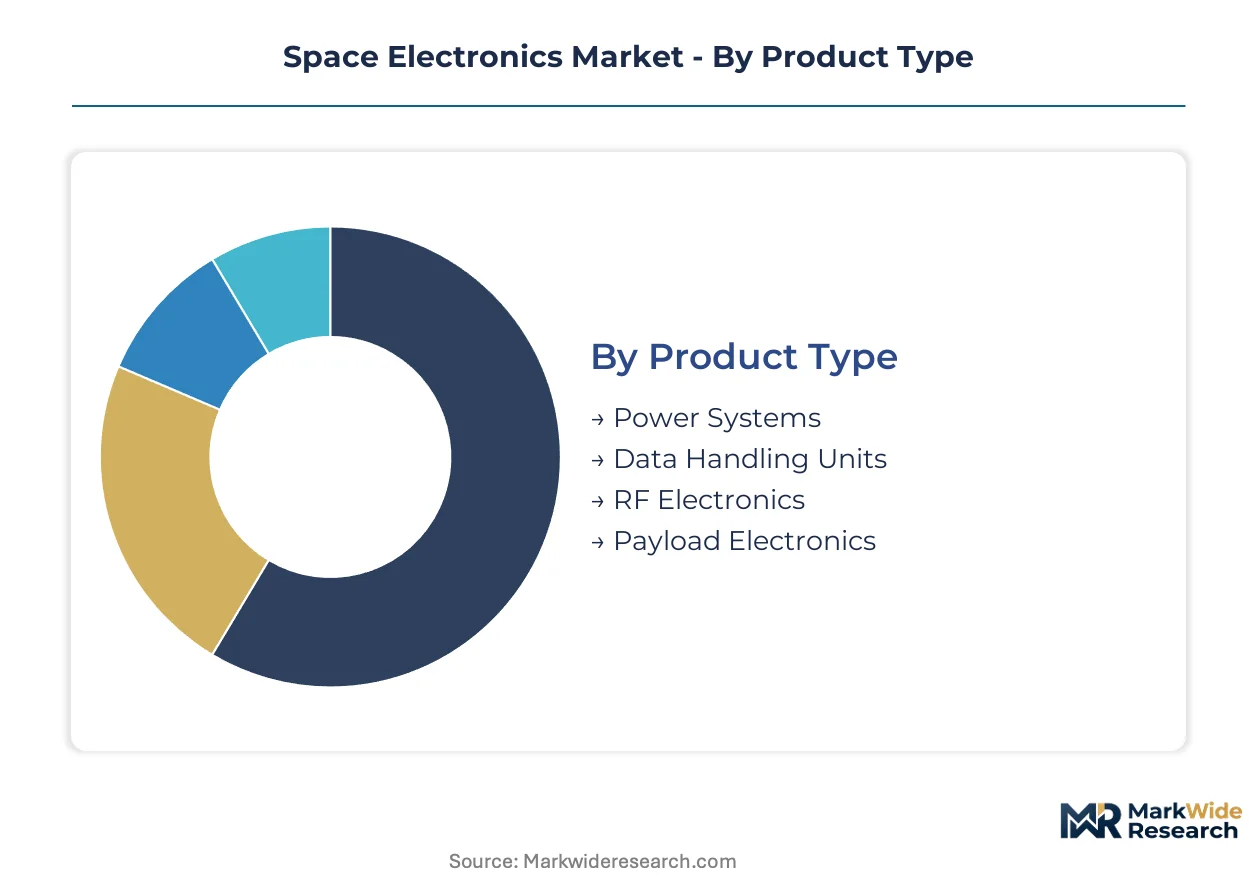
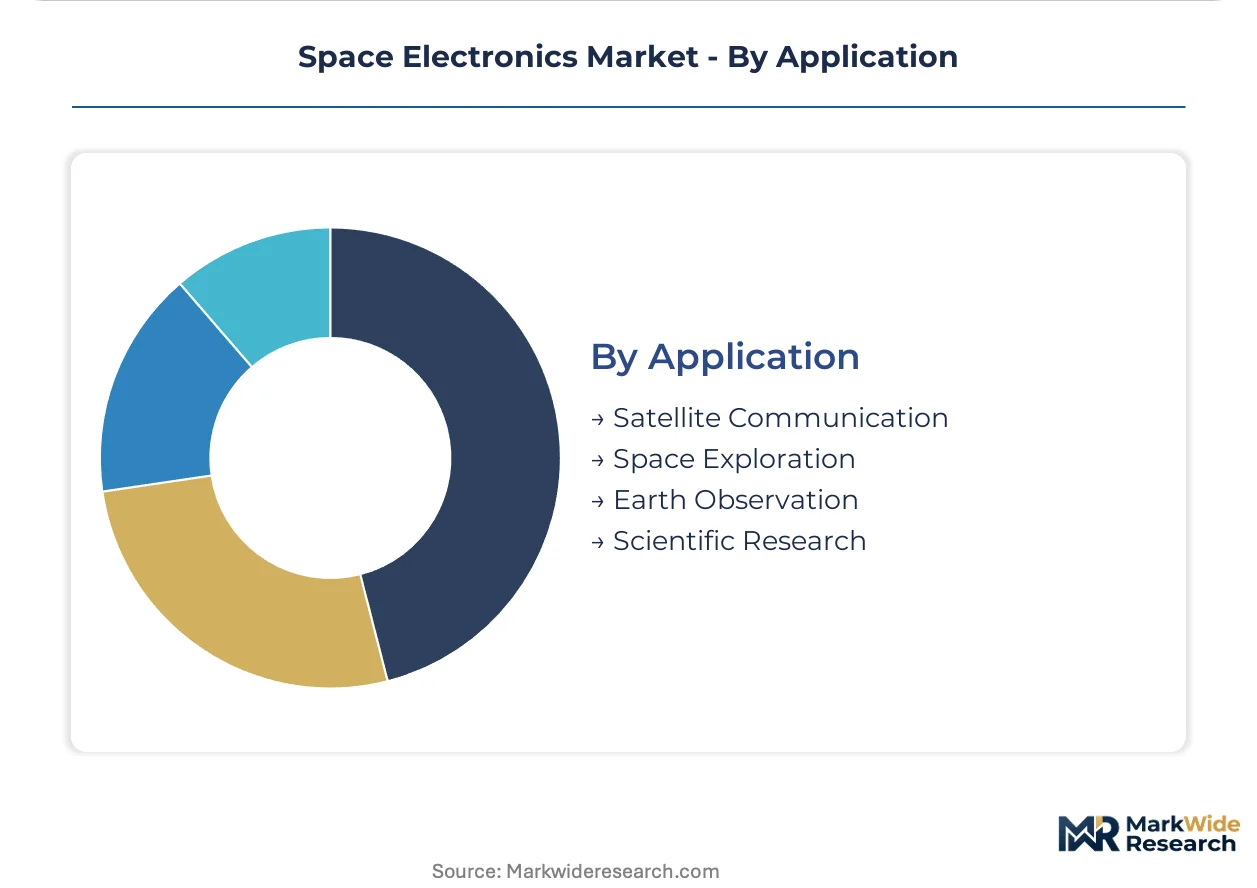
Segmentation in space electronics reveals divergent margin profiles and service intensity requirements across mission types. Constellation operators demand volume-scaled components with compressed qualification timelines, while institutional programs sustain premium pricing for heritage-assured reliability. Understanding these structural splits enables suppliers to align foundry investments and field engineering resources with profit pool concentration.
Product Type:
After-sales-service intensity varies sharply across product categories, with power systems and RF electronics commanding dedicated field engineering teams for orbital anomaly response.
- RF Electronics:Phased array antennas and frequency converters incorporate gallium nitride and silicon germanium semiconductors qualified for multi-decade operational life. Demand clusters with LEO broadband constellation primes in the United States seeking high-volume procurement of steerable beamformers. Limited qualified supplier bases sustain premium pricing tiers.
- Power Systems:Bus voltage regulators, battery charge controllers, and power distribution units manage thermal cycling across eclipse transitions. Silicon carbide MOSFET adoption is accelerating in commercial satellite platforms as suppliers adapt automotive die for space-qualified packaging.
- Data Handling Units:Onboard computers and solid-state recorders process telemetry and payload data through radiation-tolerant architectures.
- Payload Electronics:Mission-specific instrumentation and sensor interfaces vary by orbital application.
By volume, RF Electronics leads. By growth pace, Power Systems is ahead.
End User:
Customer type determines contract structure, with defense agencies favoring cost-plus sustainment arrangements and commercial operators pursuing fixed-price batch procurement.
- Commercial Satellites:Constellation operators procure radiation-hardened components in production volumes that strain legacy foundry capacity. SpaceX, Amazon's Project Kuiper, and OneWeb drive demand for commercial-grade qualification tiers with accelerated acceptance testing.
- Defense Contractors:Classified payload integration and nuclear-hardened platform requirements sustain long-term sole-source relationships. Space Force rapid acquisition pathways are compressing traditional decade-long development cycles toward responsive space timelines.
- Aerospace Agencies:NASA and ESA institutional programs prioritize heritage qualification and traceability documentation.
- Research Institutions:University-led CubeSat and smallsat missions represent entry-level demand with limited qualification budgets.
Commercial Satellites dominate unit volumes. Defense Contractors retain highest average contract values.
Technology:
Process maturity and qualification burden create tiered competitive moats, with radiation-hardened foundry access gating market participation.
- Radiation-Hardened Components:Dedicated fabrication lines at BAE Systems, Honeywell, and Cobham employ specialized layout techniques and epitaxial layers to mitigate single-event effects. Foundry capacity constraints at these US and European facilities create procurement bottlenecks for critical component categories.
- Integrated Circuits:Commercial-off-the-shelf adaptation strategies employ error-correcting codes and triple modular redundancy to compensate for reduced radiation tolerance. FPGA and ASIC designers balance performance against qualification timeline compression.
- MEMS:Microelectromechanical systems enable miniaturized inertial measurement and RF switching functions.
- Silicon Photonics:Optical interconnects for high-bandwidth payload data processing remain emerging with limited flight heritage.
Radiation-Hardened Components anchor revenue concentration. Integrated Circuits are expanding most quickly.
Application:
Mission duration and orbital environment dictate component specification severity, with deep space and lunar applications demanding extended temperature range qualification.
- Satellite Communication:Consumer broadband and enterprise data relay constellations drive volume demand for RF front-ends and digital signal processors. FCC spectrum auctions and ITU coordination filings determine addressable market size for Ka-band and V-band terminal electronics.
- Space Exploration:Artemis lunar infrastructure and Mars sample return missions require electronics qualified for extreme thermal cycling beyond LEO experience bases. NASA's sustained lunar presence mandates new radiation environment characterization.
- Earth Observation:Synthetic aperture radar and multispectral imaging payloads require high-speed data handling and precision timing distribution.
- Scientific Research:Astrophysics and heliophysics missions impose specialized instrument interface requirements with limited production scale.
Satellite Communication leads by deployment count. Space Exploration shows steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States operators deploy radiation-hardened electronics at commercial scale for constellation density, while European and Asian programs emphasize institutional heritage qualification and indigenous foundry development respectively.
United States
Space Force rapid acquisition pathways and private launch cadence from SpaceX and Rocket Lab compress component delivery schedules. FCC spectrum auctions for Ka-band and V-band terminals shape RF electronics demand curves. Los Angeles and Denver metropolitan clusters concentrate prime contractor engineering centers and radiation-hardened component distributors.
Germany
ESA institutional programs through the European Space Operations Centre sustain demand for ECSS-qualified heritage components. REACH substance restrictions force reformulation of conformal coatings and solder alloys in flight hardware. Bavaria's aerospace corridor around Munich hosts satellite prime contractors and specialized radiation effects testing facilities.
Japan
JAXA lunar exploration missions and commercial LEO constellation participation drive specification escalation for extreme thermal cycling electronics. METI funding for domestic semiconductor resilience supports radiation-hardened foundry qualification initiatives. Tokyo-Osaka industrial corridor concentrates space-grade component packaging and test house capabilities.
India
ISRO's commercial arm and emerging private launch providers create captive demand for locally qualified electronics suppliers. BIS certification requirements and DGFT export procedures govern component import substitution programs. Bengaluru and Hyderabad clusters integrate satellite manufacturing with indigenous semiconductor packaging development.
United Kingdom
OneWeb constellation manufacturing and UK Space Agency national programs sustain demand for batch-procured radiation-tolerant components. Satellite licensing frameworks under the UK Space Agency shape operator procurement timelines. Harwell Space Cluster and Glasgow smallsat manufacturing corridor concentrate payload electronics integration capabilities.
Space Electronics Market Vendor Landscape
Capability concentration sits with heritage defense contractors possessing qualified foundry access; scale advantage sits with commercial constellation primes driving volume procurement. The market structures around three tiers: radiation-hardened component specialists with captive fabrication, systems integrators managing multi-source supply chains, and emerging commercial players adapting automotive semiconductor processes. Competitive moves center on strategic partnerships for foundry capacity reservation and backward integration into component packaging capabilities.
Among defense-heritage fabricators, RTX Corporation and Northrop Grumman exemplify the long-term platform support archetype, while L3Harris Technologies occupies a position bridging mission-critical RF payloads with government end-user relationships. Rocket Lab represents the launch-to-electronics vertical integration model originating from New Zealand operations. These three anchors illustrate the polarization between heritage qualification depth and commercial scale velocity reshaping vendor selection criteria.
| Leading Market Players |
|---|
| Rocket Lab |
| ArkEdge Space |
| RTX Corporation |
| Redwire |
| Seraphim Space |
| Northrop Grumman |
| IonQ |
| L3Harris Technologies |
| Moog Inc. |
| Others |
Supply Flow & Price Mechanics
The Los Angeles-to-Denver freight corridor channels radiation-hardened component shipments from defense prime engineering centers to qualification facilities, with logistics costs amplifying price differentiation between heritage-assured and commercial-grade tiers while supply concentration at qualified foundries constrains downstream negotiation leverage for constellation operators.
Pricing Analysis
Long-term offtake agreements anchor pricing for radiation-hardened components, with Space Force and NASA sustainment contracts locking in decade-spanning unit economics that insulate heritage suppliers from spot-market volatility. Three-tier pricing structure across heritage-qualified, commercial-adapted, and COTS-redundancy levels separates mission-critical payloads from constellation batch procurement. Cost compression in commercial-grade tiers intensifies as LEO operators aggregate demand for accelerated qualification timelines. Research institutions and university CubeSat programs exhibit highest price sensitivity, while defense contractors accept premium positioning for nuclear-hardened assurance.
Supply Chain Analysis
ITAR and EAR licensing frameworks restrict technology flows from US and European qualified foundries to international satellite operators, fragmenting supplier addressable markets and extending procurement timelines. Geographic supply concentration centers on the United States, Germany, and France, where BAE Systems, Honeywell, and Cobham operate dedicated radiation-hardened fabrication lines. Raw material dependencies include specialized epitaxial silicon substrates, hermetic packaging alloys, and gallium nitride wafers. Single-source vulnerability pervades critical component categories where foundry capacity remains captive to defense heritage programs. Distribution runs through prime contractor integration facilities rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LEO broadband constellation deployments are compressing qualification timelines and displacing heritage-assured procurement models, creating asymmetric opportunity windows for suppliers capable of bridging commercial semiconductor scale with space-grade reliability.
For Market Incumbents: Harden foundry capacity reservation agreements against emerging commercial players adapting automotive semiconductor processes for space-qualified packaging. Lock in long-term platform support contracts with Space Force rapid acquisition pathways before qualification timeline compression erodes sole-source positioning. Prioritize backward integration into silicon carbide die-attach capabilities as automotive volume production lines migrate toward satellite power conditioning applications. For New Entrants and Emerging Players: Pursue on-orbit servicing electronics subsystems where rendezvous and proximity operations capabilities face limited incumbent competition and premium pricing potential. Target ISRO commercial arm procurement and emerging Indian private launch provider supply chains as the most penetrable geography for locally qualified component positioning. Anchor go-to-market strategy through ESA relaxed heritage requirements for certain payload categories, opening qualification pathways previously blocked to commercial semiconductor suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors radiation-hardened packaging specialists with automotive process node access and accelerated qualification methodologies over pure-play heritage fabricators tethered to legacy process generations. Long-term viability rests on foundry capacity reservation visibility and dual-use export control navigation capabilities. The signal to watch is FCC spectrum auction velocity for Ka-band and V-band terminals, which determines addressable market expansion for RF front-end component demand.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Secures qualified fabrication access at BAE Systems and Honeywell against constellation demand surges. |
| Silicon Carbide Packaging Qualification | Adapts automotive die-attach processes for satellite bus voltage regulation at accelerated schedules. |
| On-Orbit Servicing Subsystem Development | Captures rendezvous electronics demand with limited incumbent competition and premium pricing. |
| REACH Compliance Reformulation | Maintains European cross-border shipment eligibility through alternative metallization schemes. |
| Performance-Based Logistics Arrangement | Pilots lifecycle electronics support unbundling with Space Force operational constellation programs. |
Methodological Framework
Operator-level perspectives from constellation procurement directors, radiation effects engineers, foundry operations managers, and Space Force acquisition officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through NASA technical standards documentation, ESA ECSS qualification protocols, FCC spectrum allocation proceedings, and ITU coordination filings. Bottom-up component demand modeling triangulated against top-down satellite deployment projections.
Scenario-bracketing around foundry capacity constraints and dual-use export control evolution framed the analytical approach across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology tier, and application mission profile alongside orbital environment severity. CAGRs derived from volume trajectory analysis of LEO constellation deployment schedules and defense procurement acceleration patterns. Industry-specific inputs incorporated radiation tolerance benchmark evolution and commercial semiconductor process node advancement rates.
Sensitivities concentrate around ITAR licensing timeline shifts and qualified foundry capacity expansion decisions. Forecasts reflect documented assumptions regarding constellation deployment cadence and heritage requirement relaxation scope. Material shifts in ESA or NASA qualification protocol stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market