
 US Software Consulting Market | 2026-2036
US Software Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
US Software Consulting Market Intelligence
Subscription-based project financing and asset-light operating leases are reshaping how mid-tier firms compete in software consulting engagements. Cognizant leverages its captive delivery centers to sustain margin pressure on fixed-price contracts. Accenture anchors its position through deep vertical specialization in financial services technology transformation. Deloitte Consulting differentiates via integrated risk advisory and regulatory compliance modules bundled with implementation services.
US software consulting encompasses advisory, design, development, and integration services for enterprise application ecosystems, typically delivered through modular service architectures using agile methodologies and DevOps pipelines to reduce deployment cycle times. Custom software development and cloud services command the largest revenue pools, while IT strategy consulting captures premium pricing from board-level digital transformation mandates. Small and medium enterprises represent the fastest-growing client type as packaged SaaS platforms lower the barrier to professional advisory engagement.
The FDA's software-as-a-medical-device framework, HIPAA security rule enforcement by HHS, and state-level data privacy statutes including the California Consumer Privacy Act shape product standards and liability exposure for healthcare and finance sector engagements. Federal procurement regulations under FAR and DFARS clauses further constrain vendor selection and pricing flexibility for public sector contracts. Stakeholders must monitor evolving AI governance standards from NIST and emerging state algorithmic accountability laws to anticipate compliance cost structures and qualification barriers.
Market Dynamics
Enterprise software procurement is fragmenting across cloud-native vendors and specialized consultancies, compressing project timelines and forcing traditional integrators to restructure delivery models around modular, API-first architectures.
Growth Catalysts
- HIPAA Security Rule Enforcement:Healthcare providers must modernize electronic health record systems, generating sustained advisory demand for compliance architecture and risk assessment services.
- DevOps Pipeline Adoption:Financial services institutions deploy continuous integration tools to compress release cycles, requiring consulting support for toolchain integration and automation.
- Silicon Valley Talent Concentration:California's technology corridor attracts specialized practitioners in cloud architecture and AI governance, anchoring high-value project delivery capabilities.
Market Restraints
- Specialized Talent Scarcity:Shortages of certified cloud architects and AI ethics specialists constrain project scaling and inflate compensation costs.
- Regulatory Fragmentation:Conflicting state data privacy statutes create compliance complexity, particularly where California Consumer Privacy Act provisions diverge from federal frameworks.
- Fixed-Price Margin Compression:Client procurement teams demand outcome-based contracts that transfer implementation risk to vendors.
Strategic Opportunities
- NIST AI Governance Standards:Emerging federal algorithmic accountability guidelines create qualification barriers that favor established compliance advisory practices.
- Mid-Market SaaS Integration:Small and medium enterprises represent underpenetrated demand as packaged platforms lower professional service engagement thresholds.
- Cloud-Edge Convergence:Hybrid infrastructure deployments combining centralized cloud with distributed edge computing require new integration methodologies.
Industry Challenges
- Multi-Cloud Certification Timelines:Vendor-specific credentials from AWS, Microsoft Azure, and Google Cloud Platform create credential management overhead for workforce planning.
- Technical Debt Remediation:Enterprise clients demand simultaneous modernization of COBOL and mainframe systems alongside cloud-native development, complicating resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Software Consulting Market |
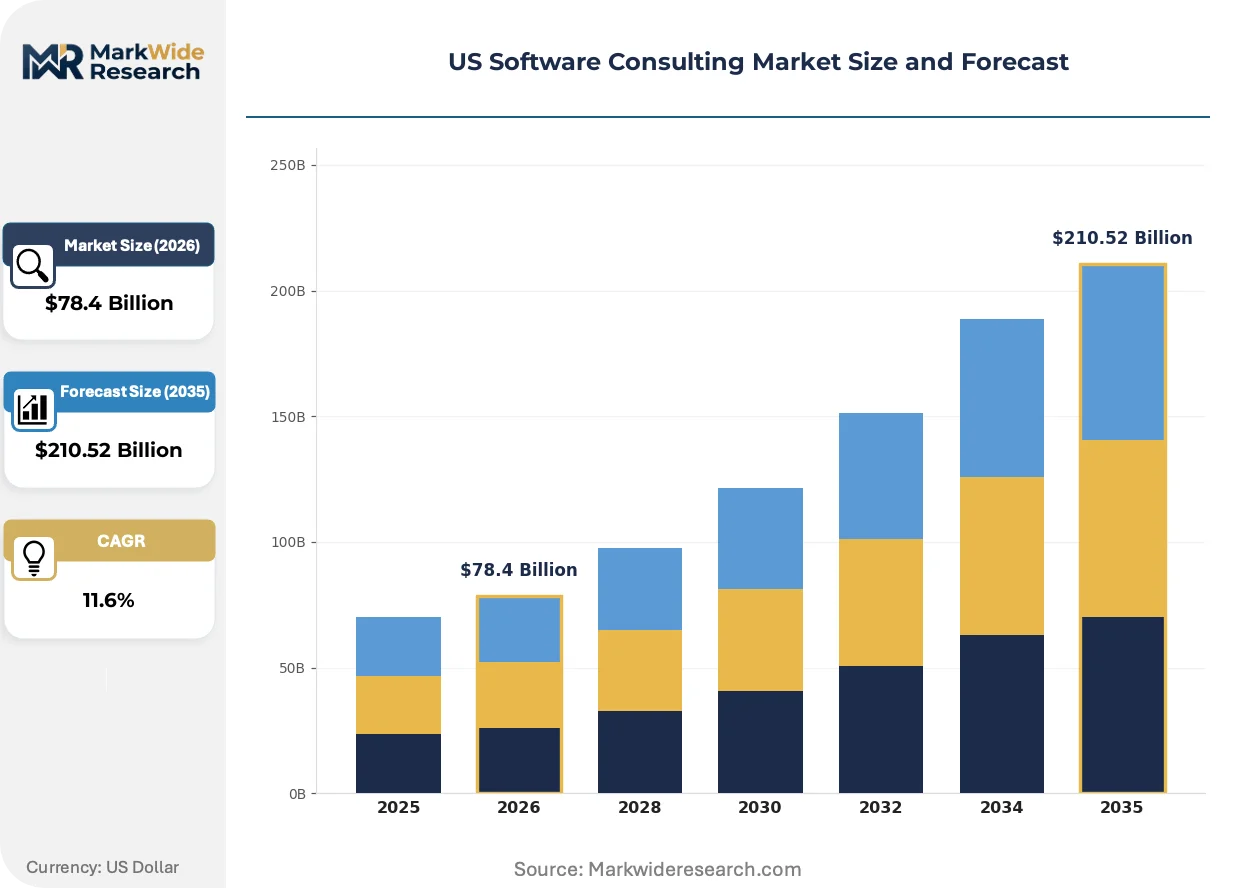
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $210.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Custom Software Development, IT Strategy Consulting, Application Maintenance, Cloud Services Client Type: Small Enterprises, Medium Enterprises, Large Corporations, Non-Profit Organizations Sector: Healthcare, Finance, Retail, Education Engagement Model: Time and Materials, Fixed Price, Dedicated Team, Managed Services |
| Companies Covered | Cognizant, ScienceSoft, Accenture, Space-O Technologies, Intellectsoft, Deloitte Consulting, Tata Consultancy Services (TCS), Codewave, IBM Consulting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Software Consulting Market Strategic Shifts & Innovations
Advisory delivery models are restructuring around composable service architectures and automated code generation, compressing traditional project phases while elevating strategic architecture work.
Generative AI coding assistants are migrating from experimental pilots to production deployment across financial services and healthcare software development teams. Mid-tier consultancies embed these tools to accelerate unit testing and documentation generation. The technology is migrating from productivity augmentation to core delivery infrastructure, forcing pricing recalibration for implementation services.
FDA software-as-a-medical-device guidance establishes predicate requirements for digital therapeutics, mandating quality management systems and clinical validation protocols. Healthcare technology vendors must restructure development workflows to accommodate premarket submission pathways. The regulation most affects diagnostic algorithm developers, who are recruiting regulatory affairs specialists and restructuring product teams.
Enterprise buyers are unbundling implementation from ongoing managed services, contracting separate vendors for deployment and operational support. This pattern fragments revenue concentration among large integrators and creates openings for specialized DevOps and site reliability engineering boutiques. The shift is most visible in California's healthcare provider market, where CIOs separately procure Epic implementation and AWS infrastructure management.
US Software Consulting Market Segmentation
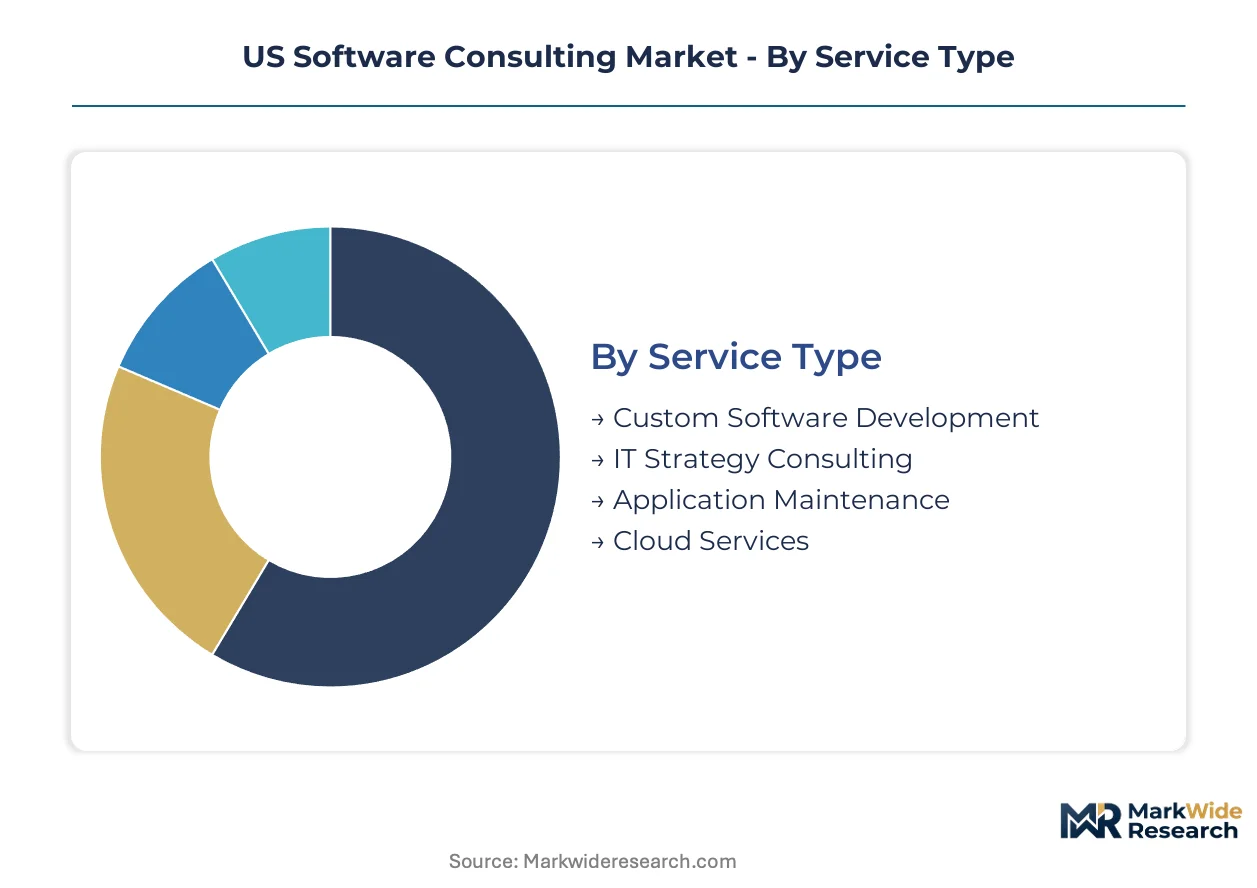
Software consulting engagements fragment across service maturity levels and client sophistication tiers. Understanding these fault lines reveals where pricing power concentrates and which delivery models face margin compression.
Service Type:
Mature service lines anchor revenue stability while emerging capabilities capture premium expansion.
- Custom Software Development:Bespoke application engineering spans mobile, web, and enterprise platforms with tailored architecture patterns. Healthcare providers in California's Bay Area drive concentrated demand for FDA-compliant quality management systems in digital therapeutics development.
- Cloud Services:Migration architecture, multi-cloud orchestration, and FinOps governance constitute the technical scope. Financial institutions deploying AWS and Azure infrastructure generate sustained advisory volume for compliance-aligned security frameworks.
- IT Strategy Consulting:Board-level digital transformation roadmapping and technology investment prioritization.
- Application Maintenance:Legacy system remediation, technical debt reduction, and continuous enhancement services.
Custom Software Development retains volume leadership; Cloud Services holds the steepest expansion curve.
Client Type:
Enterprise scale dictates procurement sophistication and contract structure preferences.
- Large Corporations:Complex multi-year engagements with dedicated account structures and outcome-based pricing. HIPAA-covered entities and federally regulated financial institutions dominate this tier with compliance-driven RFP volumes.
- Medium Enterprises:Packaged SaaS implementations with modular professional services attachments. California's mid-market healthcare providers represent accelerating demand as Epic and Cerner deployments expand beyond academic medical centers.
- Small Enterprises:Project-based engagements with standardized deliverables and accelerated timelines.
- Non-Profit Organizations:Grant-constrained budgets with donor reporting requirements and volunteer coordination platforms.
Large Corporations command the deepest contract values; Medium Enterprises are expanding most quickly as SaaS platforms democratize access to professional advisory.
Sector:
Regulatory intensity varies sharply across vertical exposure profiles.
- Healthcare:Electronic health record modernization, clinical workflow optimization, and FDA software-as-a-medical-device compliance. HHS enforcement of HIPAA security rule updates sustains advisory demand for risk assessment and breach response architecture.
- Finance:Core banking transformation, payment infrastructure modernization, and regulatory reporting automation. DevOps pipeline deployment for continuous compliance monitoring drives tooling integration consulting.
- Retail:Omnichannel platform integration, inventory optimization algorithms, and customer data platform implementation.
- Education:Learning management system migration, student information system integration, and accessibility compliance.
Healthcare captures the densest regulatory compliance spend; Finance delivers the most predictable recurring revenue streams.
Engagement Model:
Commercial risk allocation separates vendor positioning strategies.
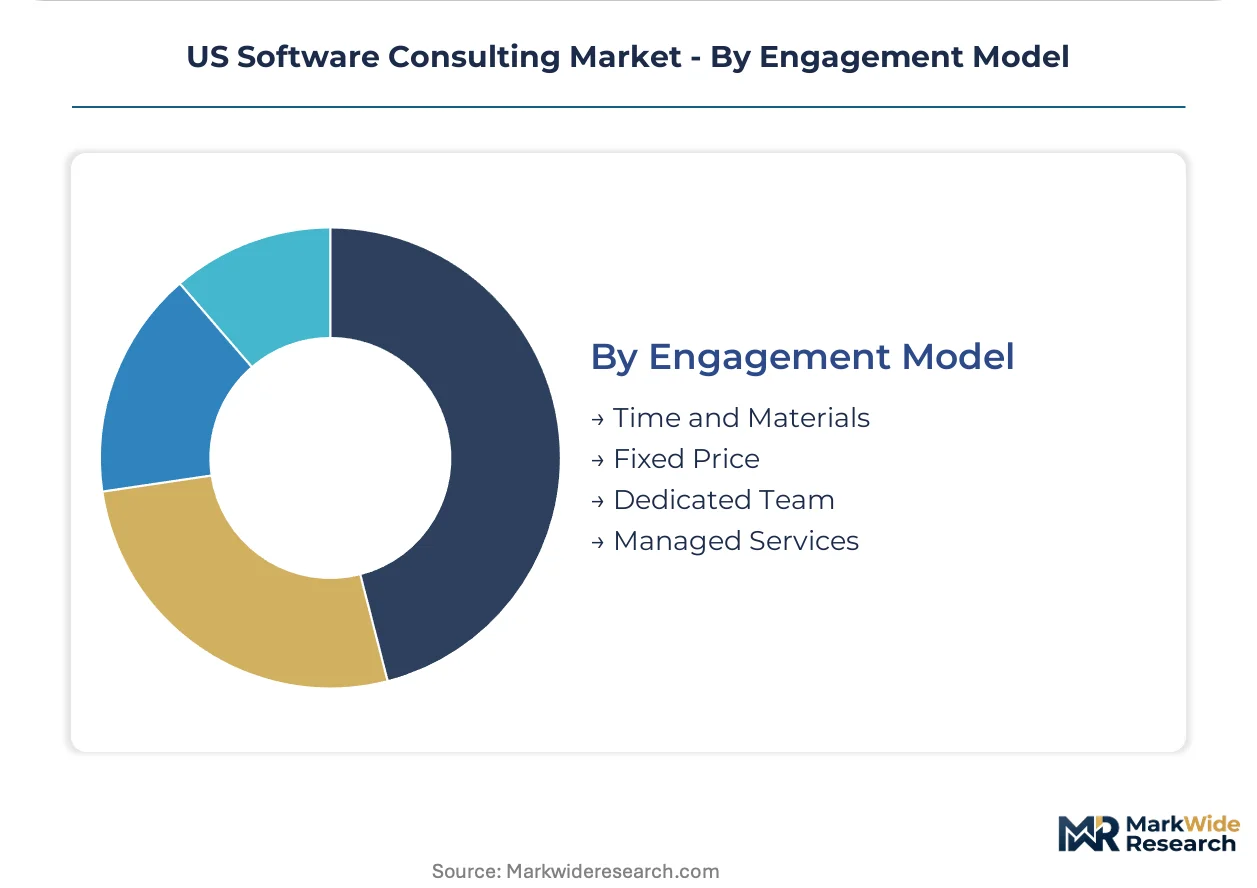
- Time and Materials:Hourly or daily rate structures with scope flexibility and change order protocols. Preferred by clients with evolving requirements and vendors seeking margin protection on uncertain deliverables.
- Fixed Price:Outcome-defined contracts with defined acceptance criteria and penalty clauses. Procurement teams at California health systems increasingly mandate this structure, compressing integrator margins.
- Dedicated Team:Staff augmentation with embedded personnel and client-directed prioritization.
- Managed Services:Operational handoff with SLA-backed performance guarantees and continuous improvement obligations.
Time and Materials dominates advisory-heavy engagements; Fixed Price is gaining share fastest as procurement functions mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement regulations under FAR and DFARS clauses channel substantial software consulting spend toward domestic delivery centers. State-level data privacy statutes create compliance complexity that varies sharply across jurisdictions.
California
Healthcare providers in the Bay Area drive concentrated demand for FDA-compliant quality management systems in digital therapeutics development. The California Consumer Privacy Act imposes data handling requirements that diverge from federal HIPAA frameworks. San Francisco and Silicon Valley anchor high-value project delivery capabilities for cloud architecture and AI governance specialists.
Texas
Energy sector enterprises deploy DevOps pipelines for operational technology integration, requiring consulting support for industrial cybersecurity frameworks. The Texas Data Privacy and Security Act establishes consumer rights that affect cross-border data flows. Dallas-Fort Worth and Austin technology corridors host expanding delivery centers for financial services technology transformation.
New York Metro
Financial institutions mandate continuous compliance monitoring through automated tooling, generating advisory demand for regulatory reporting architecture. New York State's Stop Hacks and Improve Electronic Data Security Act imposes breach notification requirements on covered entities. Manhattan and Jersey City concentrate board-level digital transformation mandates for IT strategy consulting.
Greater Boston
Academic medical centers modernize electronic health record systems, sustaining demand for HIPAA security rule compliance architecture. Massachusetts data protection regulations enforce encryption standards for personal information processing. Cambridge and the Route 128 corridor attract specialized practitioners in healthcare AI validation and clinical workflow optimization.
Pacific Northwest
Cloud-native enterprises unbundle implementation from managed services, creating openings for specialized DevOps boutiques. Washington State's My Health My Data Act establishes health data privacy requirements beyond federal minimums. Seattle and Bellevue host captive delivery centers sustaining margin pressure on fixed-price contracts through scale economies.
US Software Consulting Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered service architectures. Large integrators anchor revenue concentration through multi-year enterprise engagements, while mid-tier consultancies capture modular professional services attachments. Three archetypes dominate: vertically integrated advisory practices, cloud-native implementation specialists, and regulatory compliance boutiques. Competitive moves center on strategic partnerships for technology access and portfolio diversification into adjacent managed services.
Within the integrated advisory tier, Accenture and Deloitte Consulting exemplify deep vertical specialization strategies. Cognizant occupies a position representing captive delivery center models that compress cost structures. These three entities anchor distinct competitive vectors: Accenture through financial services technology transformation, Deloitte via bundled risk advisory and compliance modules, and Cognizant through fixed-price contract execution at scale.
| Leading Market Players |
|---|
| Cognizant |
| ScienceSoft |
| Accenture |
| Space-O Technologies |
| Intellectsoft |
| Deloitte Consulting |
| Tata Consultancy Services (TCS) |
| Codewave |
| IBM Consulting |
| Others |
Cost & Logistics Intelligence
The I-95 freight corridor's surging logistics costs amplify margin pressure for California-based delivery centers while compressing price spreads between premium advisory tiers and standardized implementation services across the US software consulting market.
Pricing Analysis
Certification level creates the primary spread between premium and standard engagement rates, with NIST AI governance credentials and multi-cloud architecture certifications commanding substantial premiums over baseline delivery. Project-based fixed-price contracts dominate healthcare and federal procurement, though subscription-based SaaS-tiered models gain share among mid-market clients. Pricing pressure stems from client procurement teams mandating outcome-based contracts that transfer implementation risk to vendors. Small enterprises exhibit the highest price sensitivity, while HIPAA-covered health systems and federally regulated financial institutions prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Captive delivery centers in India, the Philippines, and Poland hold the majority of offshore capacity for US-headquartered consultancies, with domestic delivery concentrated in California, Texas, and New York Metro corridors. Talent pipelines draw from university computer science programs, coding bootcamps, and vendor-specific certification programs including AWS, Microsoft Azure, and Google Cloud Platform. Supply chain risk centers on single-source vulnerability for specialized AI ethics practitioners and certified cloud architects. Distribution runs through direct enterprise sales organizations, strategic alliance channels with hyperscalers, and specialized healthcare IT brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI coding assistants threaten to commoditize implementation services, forcing incumbents to defend substitution through compliance specialization and strategic architecture elevation.
For Market Incumbents: Insulate margin position by deepening captive delivery center scale in cost-advantaged geographies while accelerating FDA regulatory affairs capabilities to capture digital therapeutics advisory demand. Vertical integration into managed services creates recurring revenue buffers against project-based pricing erosion. For New Entrants and Emerging Players: Build out specialized DevOps and site reliability engineering boutiques targeting California healthcare providers unbundling Epic implementation from AWS infrastructure management. Mid-market SaaS integration for HIPAA-covered entities represents the most penetrable white space, with channel partnerships through Cerner and Epic marketplaces as the primary go-to-market angle. For Investors and Strategic Acquirers: Regulatory compliance boutiques with established FDA quality management system practices and NIST AI governance credentials present the most defensible acquisition profile across the forecast horizon. Long-term viability hinges on advisory revenue mix exceeding implementation dependency. Monitor HHS enforcement patterns for HIPAA security rule violations as the critical inflection signal for compliance advisory demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner marketplace partnerships unlock healthcare provider procurement channels. |
| Acquisition of Specialist Firm | Regulatory affairs boutiques with FDA SaMD experience capture digital therapeutics expansion. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure provide co-sell access to enterprise cloud migration budgets. |
| Geographic Expansion | Dallas-Fort Worth delivery centers serve Texas energy sector DevOps demand. |
| Product Launch | Automated compliance monitoring tools address HHS HIPAA enforcement requirements. |
Research Approach
A spread of perspectives from CTOs at HIPAA-covered health systems, IT procurement officers at federally regulated financial institutions, platform engineers at hyperscaler partners, and integration specialists at Epic implementation boutiques converged on the working assumptions driving this analysis. Secondary validation drew from SEC 10-K filings, HHS breach notification databases, FDA software-as-a-medical-device guidance documents, and hyperscaler capex disclosures. Bottom-up project pipeline analysis triangulated against top-down addressable spend estimates across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with segmentation across deployment model, organization size, vertical exposure, integration complexity, and regional adoption pattern. CAGRs were derived from regression analysis of historical engagement growth rates applied to projected compliance-driven advisory expansion. Cloud migration pipeline data and FDA premarket submission volumes served as industry-specific forecast inputs throughout the modeling period.
The forecast holds incumbent behavior within observed patterns; aggressive moves by generative AI-native implementation platforms would shift outcomes beyond current projections. Model assumptions reflect stable HHS enforcement intensity and continued state-level data privacy fragmentation. Quarterly review of FDA SaMD submission volumes and HIPAA breach notification trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Reporter Systems Market
Software & Services
Global UIUX Software Market
Software & Services
Yacht Management Software Market
Software & Services
Auto Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Animation Design Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Enterprise Resource Planning Market
Software & Services
India Software Services Export Market
Software & Services
Global Business Card Software Market
Software & Services
Salesforce Services Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Global Desktop As a Service Market
Software & Services
Parks and Playground Inspection Software Market