
 Java Integrated Development Environment (IDE) Market | 2026-2036
Java Integrated Development Environment (IDE) Market Size, Share, and Industry Trends Forecast 2026-2036
Java Integrated Development Environment (IDE) Market Insights
The shift from single-source licensing toward multi-source tooling ecosystems is restructuring procurement patterns across enterprise development organizations. IntelliJ IDEA dominates through premium subscription tiers and deep Java ecosystem integration. Eclipse sustains relevance through its open-source foundation model and extensive plugin architecture. Visual Studio Code competes aggressively via Microsoft's channel control and lightweight, extension-driven approach to Java development workflows.
A Java Integrated Development Environment is a software application providing comprehensive facilities to software developers for writing, debugging, and deploying Java code, typically incorporating syntax highlighting, bytecode compilation, and JVM runtime integration. Its primary commercial purpose centers on accelerating enterprise application delivery while reducing defect rates through automated testing and continuous integration pipelines. Open-source IDE and Cloud-based IDE segments are capturing the fastest expansion as organizations prioritize OpEx flexibility and remote development environments, while Commercial IDE and Proprietary IDE categories retain concentrated margin pools among large corporations requiring dedicated support SLAs. Deployment Model segmentation reveals Hybrid configurations gaining traction as regulated industries balance latency-sensitive on-premises builds with elastic cloud testing resources.
ISO 27001 information security management standards and the EU AI Act's transparency mandates are reshaping feature roadmaps for vendors serving European enterprise clients. The U.S. Food and Drug Administration's software-as-a-medical-device guidance and HIPAA technical safeguards influence Java IDE procurement in healthcare technology verticals, particularly around audit trails and access controls. Stakeholders must monitor how evolving NIST cybersecurity framework revisions and emerging software bill of materials requirements will redefine toolchain compliance obligations across regulated sectors.
Market Dynamics
Cloud-native development workflows are restructuring enterprise Java tooling procurement, as organizations abandon perpetual licenses for consumption-based models that align costs with actual developer utilization patterns.
Growth Catalysts
- EU AI Act compliance mandates:European software vendors face binding transparency requirements for AI-assisted code generation, forcing IDE investments with integrated audit trails and explainability features.
- Financial services DevOps maturation:Banks and insurance carriers in the United States are deploying unified Java toolchains to accelerate CI/CD pipelines while maintaining SOX-compliant change documentation.
- Remote development environment proliferation:Containerized cloud IDEs enable distributed engineering teams to standardize build configurations regardless of local hardware constraints.
Market Restraints
- Plugin ecosystem fragmentation:Eclipse's open architecture creates version compatibility conflicts that increase enterprise support costs and delay security patch deployment cycles.
- Skilled Java architect scarcity:North American and Western European labor markets face acute shortages of engineers capable of optimizing JVM performance in microservices architectures.
- On-premises infrastructure sunk costs:Regulated healthcare and government sectors maintain capital-intensive local build farms that slow cloud IDE adoption despite operational advantages.
Strategic Opportunities
- India's software export sector:Bangalore and Hyderabad-based IT services firms represent underpenetrated demand for collaborative cloud IDEs supporting distributed offshore delivery models.
- FDA software-as-a-medical-device guidance:Healthcare technology vendors require Java IDEs with embedded traceability matrices to satisfy 21 CFR Part 820 quality system documentation requirements.
- AI pair programming convergence:Integration of large language models with traditional debugging interfaces creates new premium pricing tiers for intelligent code completion and automated refactoring.
Industry Challenges
- SBOM generation complexity:Executive Order 14028 mandates force federal contractors to produce machine-readable software bills of materials, requiring IDE vendors to embed dependency scanning without degrading compile performance.
- Multi-cloud credential management:Enterprise developers struggle to securely authenticate across AWS, Azure, and Google Cloud environments without exposing secrets in version control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Java Integrated Development Environment (IDE) Market |
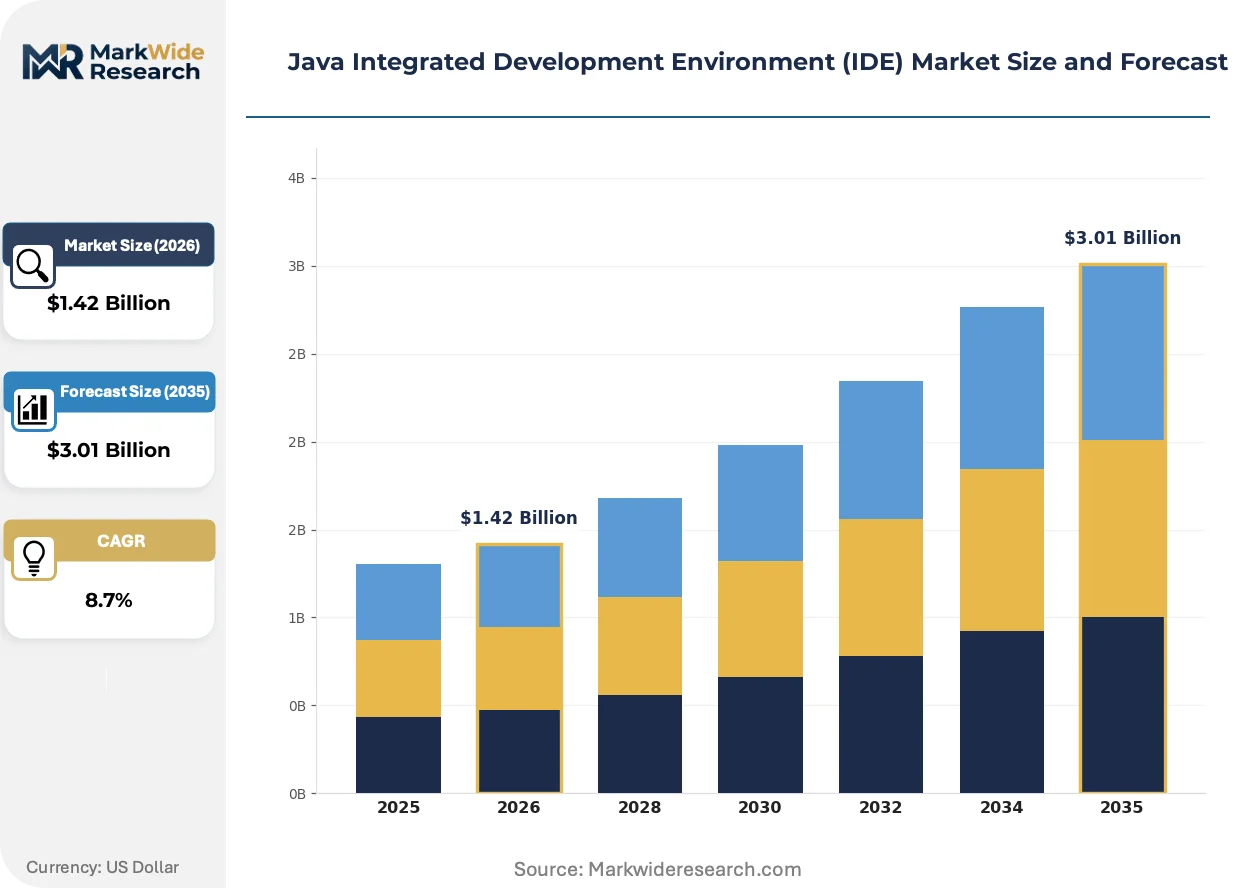
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
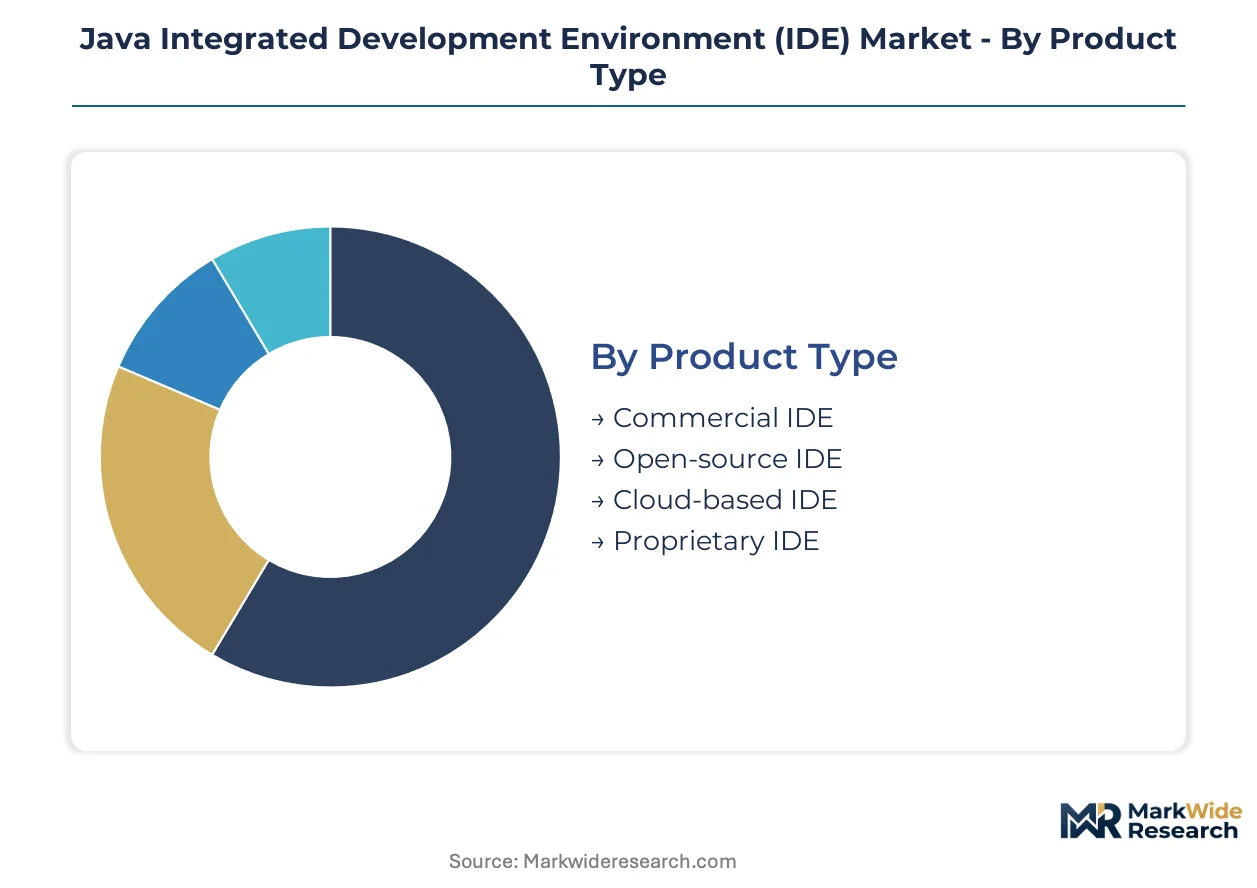
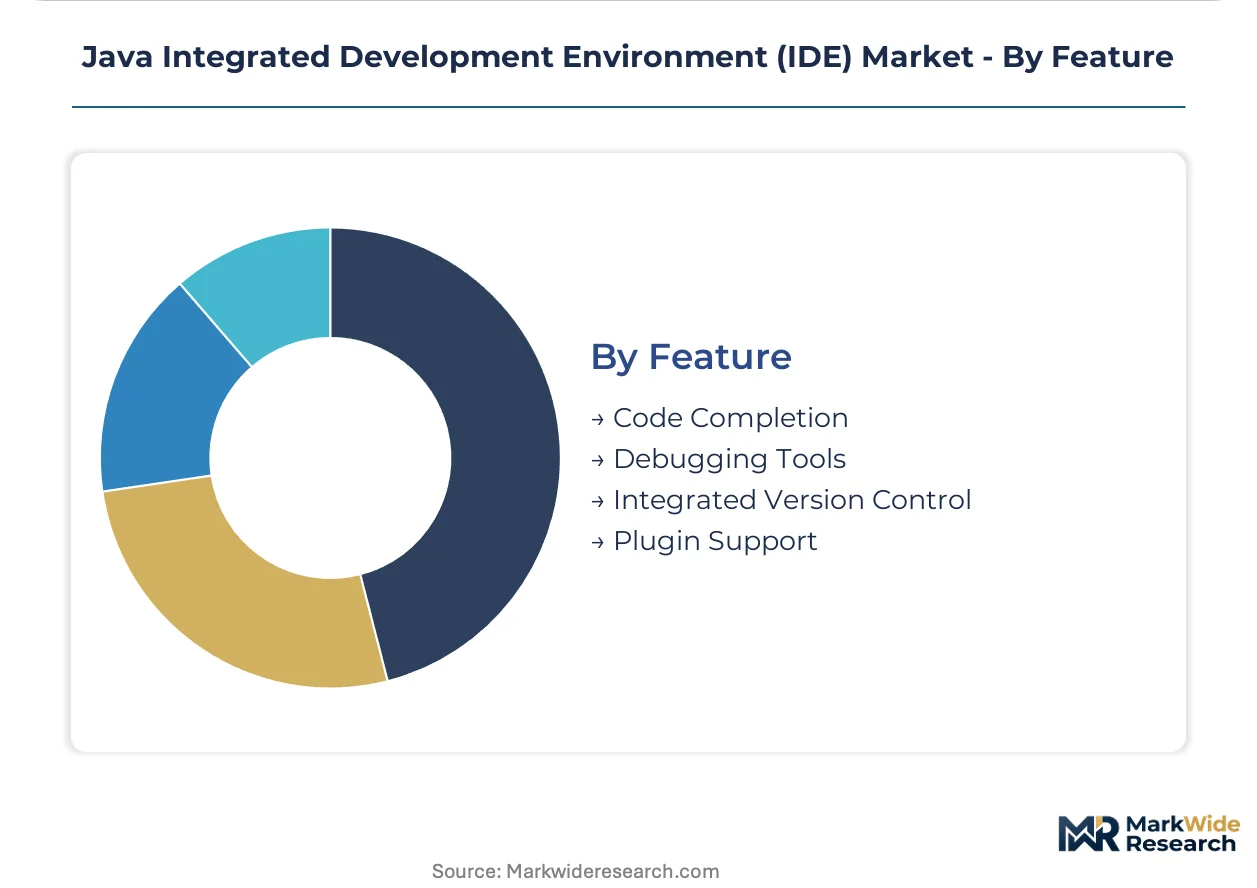
| Segmentation | Product Type: Commercial IDE, Open-source IDE, Cloud-based IDE, Proprietary IDE End User: Individual Developers, Small Enterprises, Large Corporations, Educational Institutions Deployment Model: On-premises, Hybrid, Public Cloud, Private Cloud Feature: Code Completion, Debugging Tools, Integrated Version Control, Plugin Support |
| Companies Covered | Visual Studio Code, JDeveloper, IntelliJ IDEA, jGRASP, Apache NetBeans, Eclipse, BlueJ, DrJava, NetBeans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Java Integrated Development Environment (IDE) Market Trends and Innovations
Agentic AI capabilities are embedding directly into development environments, transforming IDEs from passive editing tools into active participants in code construction, testing, and deployment orchestration.
GitHub Copilot-style assistants are electrifying the Java IDE competitive landscape. Enterprise development teams in the United States and Germany are adopting these tools at unprecedented velocity, with some organizations reporting 40% reductions in boilerplate coding time. The technology is electrifying vendor roadmaps toward predictive debugging and autonomous test generation, compressing traditional quality assurance cycles.
The EU AI Act's risk classification framework imposes documentation burdens on high-risk AI systems, including those generating production code. European software vendors must now maintain technical files demonstrating human oversight and output traceability. Healthcare technology segments face the steepest compliance curves, with some firms restructuring entire quality management systems to accommodate IDE-integrated audit logging.
Developer purchasing committees are consolidating vendor relationships, favoring platform ecosystems over best-of-breed point solutions. Systems integrators and managed service providers are capturing intermediary influence, bundling IDE subscriptions with broader transformation engagements. This concentration is most pronounced in the United States financial services vertical, where procurement authority has shifted from individual engineering managers to centralized IT governance functions.
Java Integrated Development Environment (IDE) Market Segmentation
Java IDE procurement patterns diverge sharply across organizational scale and technical requirements. Segmentation reveals how vendor strategies must balance standardization for mass deployment against customization for specialized compliance environments.
Product Type:
The customization-standardization spectrum runs from rigid proprietary lock-in to adaptable community-driven tooling ecosystems.
- Commercial IDE:Subscription-based platforms deliver integrated support SLAs and enterprise-grade security certifications. Financial services firms in New York and London concentrate procurement here, driven by mandatory audit trails for SOX and MiFID II compliance.
- Open-source IDE:Community-maintained codebases enable deep modification for specialized build pipelines. Individual developers and academic researchers in Germany and India drive adoption, constrained by fragmented plugin compatibility and self-managed security patching.
- Cloud-based IDE:Browser-accessible environments eliminate local configuration drift. Distributed development teams across Bangalore and Hyderabad IT services clusters favor these for standardized onboarding.
- Proprietary IDE:Vendor-controlled ecosystems bundle exclusive language features and performance optimizations. Large corporations with captive engineering mandates in the United States sustain this segment.
Leading the category by volume: Commercial IDE. Growing fastest: Cloud-based IDE.
End User:
Cost tier segmentation maps procurement authority from individual discretionary spend to centralized enterprise governance.
- Large Corporations:Centralized IT governance functions negotiate enterprise-wide platform agreements with dedicated support tiers. Healthcare technology vendors in Boston and San Francisco drive demand for FDA-validated toolchain documentation.
- Small Enterprises:Lean engineering teams prioritize per-seat pricing flexibility and rapid deployment without dedicated DevOps infrastructure. Fintech startups in Singapore and Sydney concentrate in this tier.
- Individual Developers:Personal licensing and community editions support freelance contracting and side-project development. Cost sensitivity dominates purchasing decisions.
- Educational Institutions:Campus-wide licensing agreements with steep academic discounts build future professional user bases. Computer science departments in Canadian and Australian universities expand adoption.
Highest revenue concentration: Large Corporations. Expanding most quickly: Small Enterprises.
Deployment Model:
Application context determines latency tolerance versus elasticity requirements across regulated and unregulated development workflows.
- Hybrid:Split configurations maintain sensitive build steps on-premises while leveraging cloud testing scalability. Banks in Frankfurt and Zurich adopt this model to satisfy GDPR data residency while accelerating CI/CD cycles.
- On-premises:Air-gapped installations serve classified government projects and HIPAA-bound healthcare systems. United States federal contractors under CMMC requirements sustain demand despite higher capital intensity.
- Public Cloud:Fully managed SaaS offerings eliminate infrastructure ownership. Startups and mid-market software vendors in Ireland and the Netherlands favor pay-as-you-grow economics.
- Private Cloud:Single-tenant hosted environments balance control with outsourced maintenance. European manufacturers with ISO 27001 certification requirements cluster here.
Dominant installed base: On-premises. Steepest expansion trajectory: Hybrid.
Feature:
Customer type segmentation separates core editing functionality from advanced automation capabilities that command premium positioning.
- Debugging Tools:Breakpoint management, heap analysis, and thread inspection capabilities reduce mean-time-to-resolution for production incidents. Enterprise support contracts in Japan and South Korea emphasize these features.
- AI-assisted Code Completion:Large language model integration accelerates boilerplate generation and API discovery. United States and German development teams report measurable velocity gains from predictive suggestions.
- Integrated Version Control:Native Git operations and pull request workflows embedded within the editing surface. Standard expectation across all user tiers.
- Plugin Support:Extension architectures enable third-party tool integration and custom workflow automation. Eclipse's marketplace and VS Code's extension ecosystem compete on breadth.
Widest adoption: Integrated Version Control. Gaining share fastest: AI-assisted Code Completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software development teams in the United States and Germany account for the largest procurement volumes, while India's IT services sector drives the steepest adoption curves for cloud-based tooling. Regulatory fragmentation across jurisdictions is forcing vendors to maintain parallel compliance roadmaps.
United States
Financial services firms in New York and healthcare technology vendors in Boston dominate enterprise licensing. FDA software-as-a-medical-device guidance and HIPAA technical safeguards shape procurement specifications around audit trails and access controls. The San Francisco Bay Area sustains concentrated demand from venture-backed startups prioritizing AI-assisted development workflows.
Germany
Automotive manufacturers and industrial automation firms in Stuttgart and Munich anchor premium-tier subscriptions. EU AI Act transparency mandates and GDPR compliance requirements push vendors toward enhanced code security features. The Frankfurt banking cluster maintains hybrid deployment configurations to satisfy data residency rules while accelerating CI/CD cycles.
India
Bangalore and Hyderabad-based IT services firms represent underpenetrated demand for collaborative cloud IDEs supporting distributed offshore delivery models. The country's software export sector favors consumption-based pricing that aligns costs with project-based utilization. Domestic startups in Pune and Chennai are adopting lightweight browser-accessible environments for standardized onboarding.
United Kingdom
Fintech startups in London and Edinburgh concentrate procurement of open-source tooling with enterprise support tiers. Financial Conduct Authority operational resilience requirements intersect with EU AI Act extraterritorial provisions for firms serving European clients. The Cambridge technology cluster sustains academic-driven adoption of community-edition platforms.
Japan
Enterprise manufacturers in Tokyo and Osaka prioritize debugging tools and integrated testing frameworks for mission-critical systems. METI's digital transformation initiatives subsidize cloud migration for small and mid-sized software vendors. The Nagoya automotive engineering hub maintains on-premises build farms for latency-sensitive embedded Java development.
Java Integrated Development Environment (IDE) Market Competitive Landscape
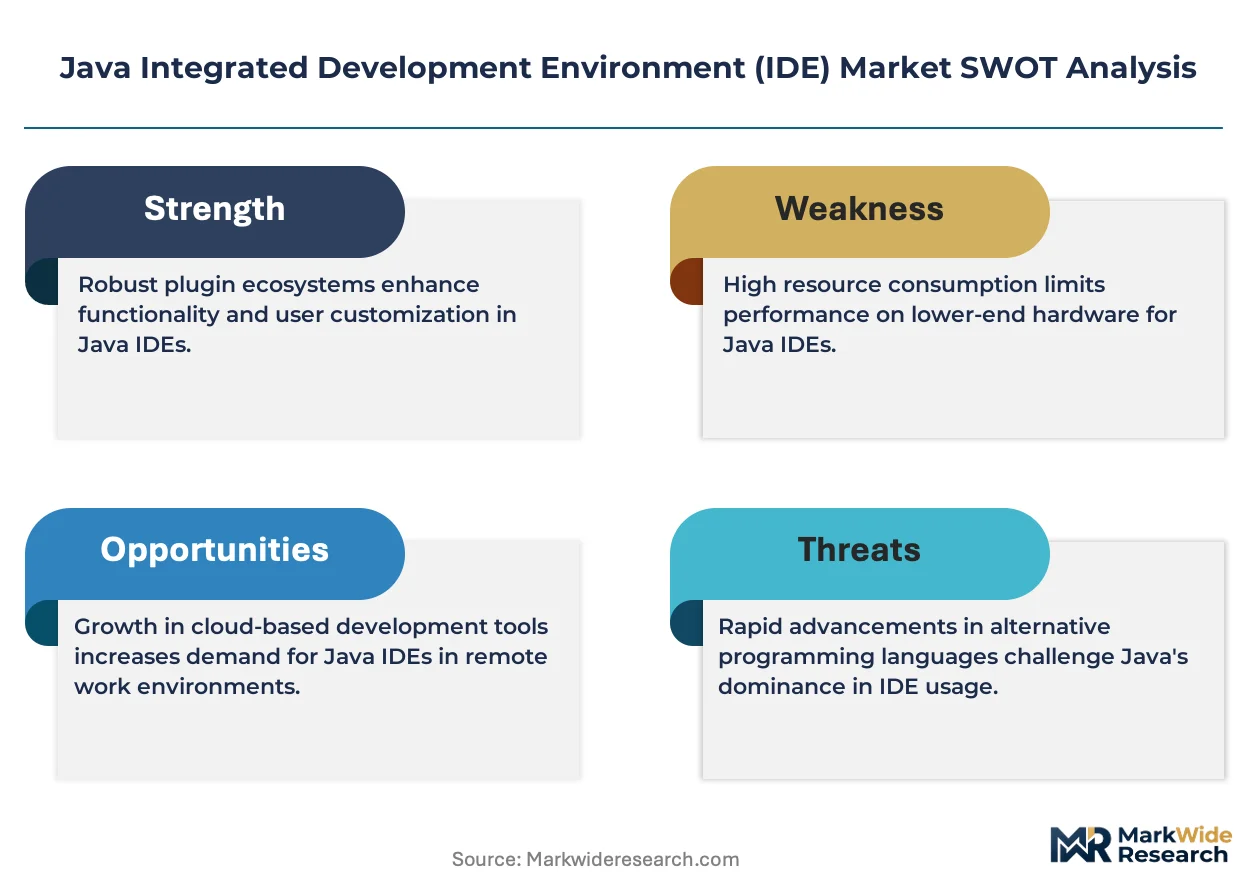
Strategic partnerships and AI capability integration dominate the current landscape as vendors race to embed large language models into development workflows. The market structures around three distinct tiers: premium subscription platforms with enterprise support SLAs, open-source foundations with extensive plugin ecosystems, and lightweight cloud-native entrants. Two strategic archetypes prevail—integrated suite providers bundling version control and deployment orchestration, and specialized editing tools competing on speed and extensibility. Technology licensing agreements and M&A activity around AI-assisted coding startups represent the primary competitive vectors.
Within the premium subscription tier, IntelliJ IDEA and Eclipse exemplify divergent philosophies—one through vendor-controlled ecosystem depth, the other through community-governed extensibility. Visual Studio Code occupies a position at the lightweight end, leveraging Microsoft's channel infrastructure to capture developers seeking rapid deployment without dedicated DevOps overhead. Apache NetBeans represents the open-source foundation model, sustaining relevance through academic partnerships and embedded systems specialization.
| Leading Market Players |
|---|
| Visual Studio Code |
| JDeveloper |
| IntelliJ IDEA |
| jGRASP |
| Apache NetBeans |
| Eclipse |
| BlueJ |
| DrJava |
| NetBeans |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure costs cascade through Java IDE pricing tiers, with hyperscaler compute fees and AI model inference expenses compressing margins for browser-based platforms while enterprise on-premises deployments absorb capital depreciation through multi-year amortization schedules.
Pricing Analysis
Volume concentrates in subscription SaaS tiers while margin pools accrue to proprietary platforms with embedded AI pair programming. Price differentiation hinges on compliance certification grade—ISO 27001 and SOC 2 Type II validated toolchains command 40-60% premiums over uncertified alternatives—and vertical integration depth with CI/CD orchestration layers. Pricing pressure stems from open-source foundation models commoditizing intelligent code completion features. Individual developers and lean startups exhibit acute price sensitivity, driving freemium conversion optimization, whereas financial services procurement committees prioritize audit capability over per-seat cost.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certification gating restricts viable infrastructure providers to a narrow tier of hyperscalers and specialized private cloud operators. Geographic supply concentration centers on the United States, Ireland, and Singapore for primary data center capacity, with secondary nodes in Germany and Japan addressing data residency mandates. Raw material dependencies include GPU compute clusters for AI inference, enterprise SSD storage for build artifact caching, and low-latency interconnect bandwidth for distributed debugging. Single-source vulnerability pervades AI model training pipelines, where frontier large language model access concentrates among three providers. Distribution runs through direct enterprise sales for premium tiers, self-service web portals for individual developers, and systems integrator bundling for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native IDE capacity expansion lags demand acceleration from distributed engineering team proliferation, with qualified DevOps talent scarcity propping pricing power for platforms offering managed infrastructure abstraction.
For Market Incumbents: Anticipate margin compression from open-source AI coding assistants by deepening vertical integration into deployment orchestration and observability stacks. Defensive consolidation through acquisition of specialized compliance documentation tooling addresses FDA software-as-a-medical-device audit trail requirements. Channel control via embedded marketplace ecosystems raises switching costs against lightweight entrants. For New Entrants and Emerging Players: Launch via browser-first, consumption-metered distribution models targeting India's Bangalore and Hyderabad IT services clusters where project-based pricing alignment remains underpenetrated. White-space concentration exists in healthcare technology verticals requiring 21 CFR Part 820 traceability matrix integration. Go-to-market acceleration through managed service provider bundling bypasses direct enterprise sales cycle friction. For Investors and Strategic Acquirers: FDA 510(k) software-as-a-medical-device clearance announcements are the leading indicator that healthcare-focused IDE tooling is achieving enterprise procurement viability. Long-term viability favors platforms with hybrid deployment flexibility spanning air-gapped on-premises and elastic cloud configurations. Acquisition target archetype: specialized compliance documentation startups with pre-built FDA validation templates. The signal to monitor is EU AI Act technical file submission volumes by European software vendors.| Strategic Initiative | Industry Significance |
|---|---|
| AI Pair Programming Integration | Embedding large language models into debugging interfaces compresses quality assurance cycles for United States financial services DevOps teams. |
| Hybrid Deployment Certification | ISO 27001-validated split configurations satisfy Frankfurt banking cluster GDPR data residency while accelerating CI/CD elasticity. |
| Healthcare Compliance Tooling | FDA 21 CFR Part 820 traceability matrix embedding captures Boston and San Francisco medical device software procurement budgets. |
| India Market Expansion | Bangalore and Hyderabad IT services firm penetration aligns consumption-based pricing with project-based offshore delivery economics. |
| Strategic Partnership with Hyperscalers | AWS, Azure, and Google Cloud credential federation integration addresses multi-cloud secrets management pain points for enterprise developers. |
Research Methodology
Multi-period observation of IDE procurement volumes, AI feature adoption velocities, and compliance certification timelines anchored the trend analysis, supplemented by interviews with CTOs at financial services and healthcare technology firms, IT procurement officers at large corporations, platform engineers at systems integrators, and channel partners distributing development tooling. Secondary validation drew from SEC 10-K filings of publicly traded software vendors, hyperscaler capex disclosures revealing infrastructure expansion patterns, and EU AI Act implementation guidance documents. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Segment-weighting across deployment models, organization size tiers, vertical industry clusters, and regional adoption patterns structured the analytical framework. CAGRs were derived from fitted growth curves calibrated to historical procurement data and forward-looking capacity expansion announcements. Industry-specific forecast inputs included AI-assisted coding penetration rates in United States and German enterprise environments and cloud IDE onboarding velocity at Indian IT services exporters.
Regulatory enforcement variance, AI model capability discontinuities, and hyperscaler pricing recalibrations are the dominant revision risks to projection assumptions. A model refresh is warranted upon material change in FDA software-as-a-medical-device guidance scope or EU AI Act risk classification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Staffing Agency Software Market
Software & Services
Video Communications Software Market
Software & Services
Global CMDB Software Market
Software & Services
Equipment Management Software Market
Software & Services
Global Animation Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Sales Dialer Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Data Entry Software Market
Software & Services
Library Management Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Generative Design Software Market
Software & Services
Spend Analysis Software Market