
 Global Business Card Software Market | 2026-2036
Global Business Card Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Card Software Market Foresight
Buyer fragmentation across freelancers and micro-enterprises is realigning how vendors allocate engineering and sales resources. Sansan leverages its enterprise CRM integration depth to anchor recurring revenue from Japanese corporations. HiHello competes through mobile-native design tools that simplify contact exchange at virtual networking events. Covve differentiates via AI-powered contact enrichment that sustains premium pricing against free-tier rivals.
Business card software encompasses digital platforms that create, distribute, and manage electronic contact credentials through NFC transmission, QR code generation, and real-time synchronization with CRM systems. These tools eliminate physical printing while enabling analytics on sharing frequency, follow-up conversion, and geographic reach of professional interactions. Cloud-based deployment leads volume as subscription economics reduce upfront barriers for small businesses, though hybrid architectures capture margin pools from security-conscious financial services clients. Design tools and integration features represent the fastest-growing solution segments as API connectivity with Salesforce and HubSpot becomes a baseline procurement criterion rather than a premium upsell.
The EU AI Act and GDPR impose strictures on automated contact scraping and profiling that shape product architecture decisions for European market entry. Japan's METI promotes paperless administrative standards that accelerate enterprise replacement of physical meishi exchange rituals. Stakeholders must monitor how ISO 27001 certification requirements evolve into table-stakes procurement filters across regulated industries.
Market Dynamics
Cloud migration and API-first architectures are compressing deployment cycles while redefining how vendors capture recurring revenue from fragmented buyer bases.
Growth Catalysts
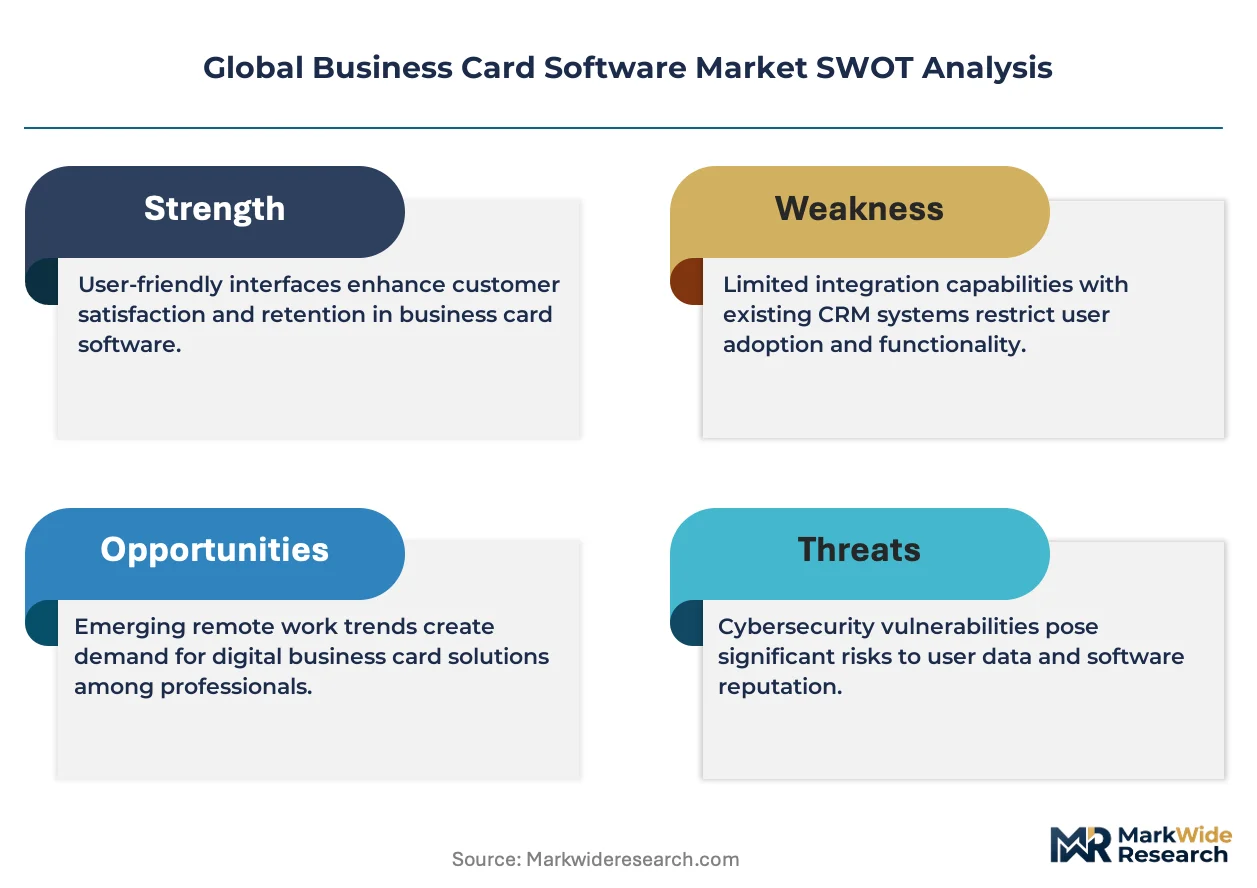
- GDPR and EU AI Act:Compliance mandates across Europe accelerate enterprise procurement of ISO 27001-certified platforms that automate consent management and audit trails for contact data processing.
- Japan METI paperless standards:Administrative digitization directives eliminate traditional meishi exchange rituals in corporate procurement, forcing replacement of physical cards with NFC-enabled digital credentials.
- API connectivity:Native Salesforce and HubSpot integrations transform from premium upsells to baseline procurement criteria, expanding addressable market among CRM-dependent sales organizations.
Market Restraints
- Subscription fatigue:Micro-enterprises and freelancers resist accumulating SaaS overhead, capping pricing power for vendors targeting sub-ten-employee segments.
- Platform dependency risk:Apple and Google control NFC chip access and QR scanning defaults, creating gatekeeper vulnerability for independent software providers.
- Physical card residual utility:Cultural attachment to tactile exchange persists in relationship-heavy industries like luxury real estate and executive recruiting, slowing full digitization.
Strategic Opportunities
- Germany enterprise mid-market:Mittelstand manufacturers with export sales teams remain underpenetrated by mobile-native solutions, presenting whitespace for hybrid cloud offerings with on-premise data residency options.
- Event-tech convergence:Integration with virtual conference platforms and webinar tools creates new distribution channels as hybrid networking becomes permanent fixture in professional services.
- CSRD reporting alignment:Sustainability disclosure requirements position paper-elimination metrics as procurement differentiators for ESG-conscious European corporations.
Industry Challenges
- Legacy CRM integration complexity:Custom on-premise Salesforce instances and obsolete contact databases demand expensive professional services, eroding software margins and extending sales cycles.
- Cross-border data residency:Conflicting requirements between GDPR, Japan's APPI, and US CLOUD Act force costly multi-region infrastructure replication for vendors serving multinational clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Card Software Market |
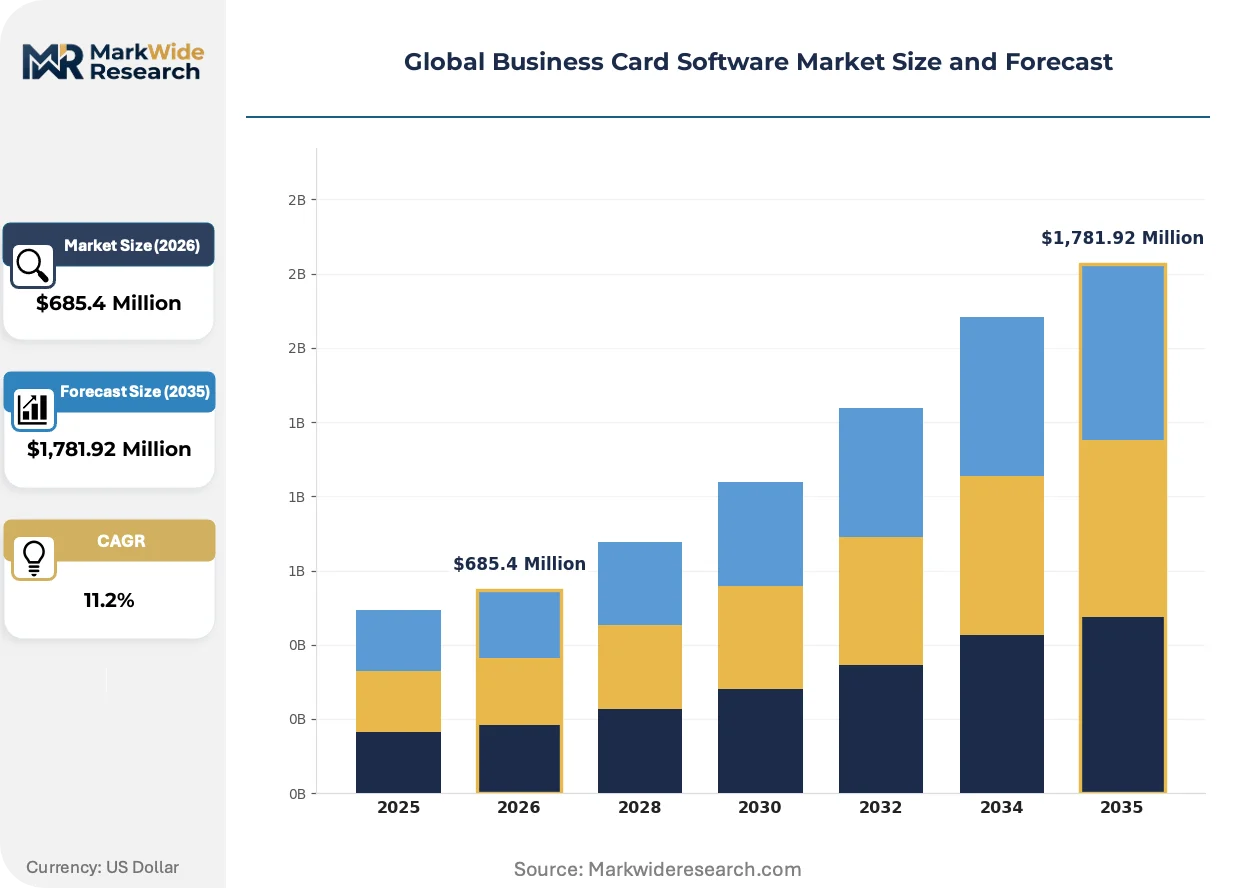
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,781.92 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based Solution: Design Tools, Contact Management, Integration Features, Analytics, Customization Options Application: Networking Events, Sales Enablement, Digital Marketing, Client Management, Brand Promotion End User: Freelancers, Small Businesses, Corporations, Marketing Agencies, Educational Institutions |
| Companies Covered | Sansan, ABBYY, CamCard, HiHello, HubSpot, CircleBack, Covve, Knowee, Haystack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Card Software Market Shifts & Advancements
Product roadmaps prioritize embedded intelligence and frictionless exchange mechanisms as competitive differentiation shifts from design templates to workflow automation depth.
NFC transmission technology enables tap-to-share contact exchange without app installation on recipient devices. Enterprise sales teams and field service technicians adopt this capability fastest, particularly in the United States and Germany where device penetration supports universal compatibility. The technology is converging with biometric authentication protocols to create verified identity layers that reduce spoofing risks in high-trust professional contexts.
Japan's METI digitization mandates explicitly target administrative ritual elimination, including traditional business card exchange protocols. Japanese corporations respond by bundling digital credential platforms with existing keiretsu software procurement relationships. Financial services and pharmaceutical sectors face the steepest compliance deadlines, accelerating replacement cycles ahead of smaller manufacturing affiliates.
Buyer preference gravitates toward usage-based billing models that align costs with actual networking activity rather than seat-based subscriptions. Freelancers and project-based consultants in creative industries drive this shift, forcing vendors to unbundle analytics and CRM sync features into modular tiers. Germany and the Netherlands exhibit the strongest adoption of consumption-aligned pricing, reflecting mature SaaS procurement sophistication among independent professionals.
Global Business Card Software Market Segmentation
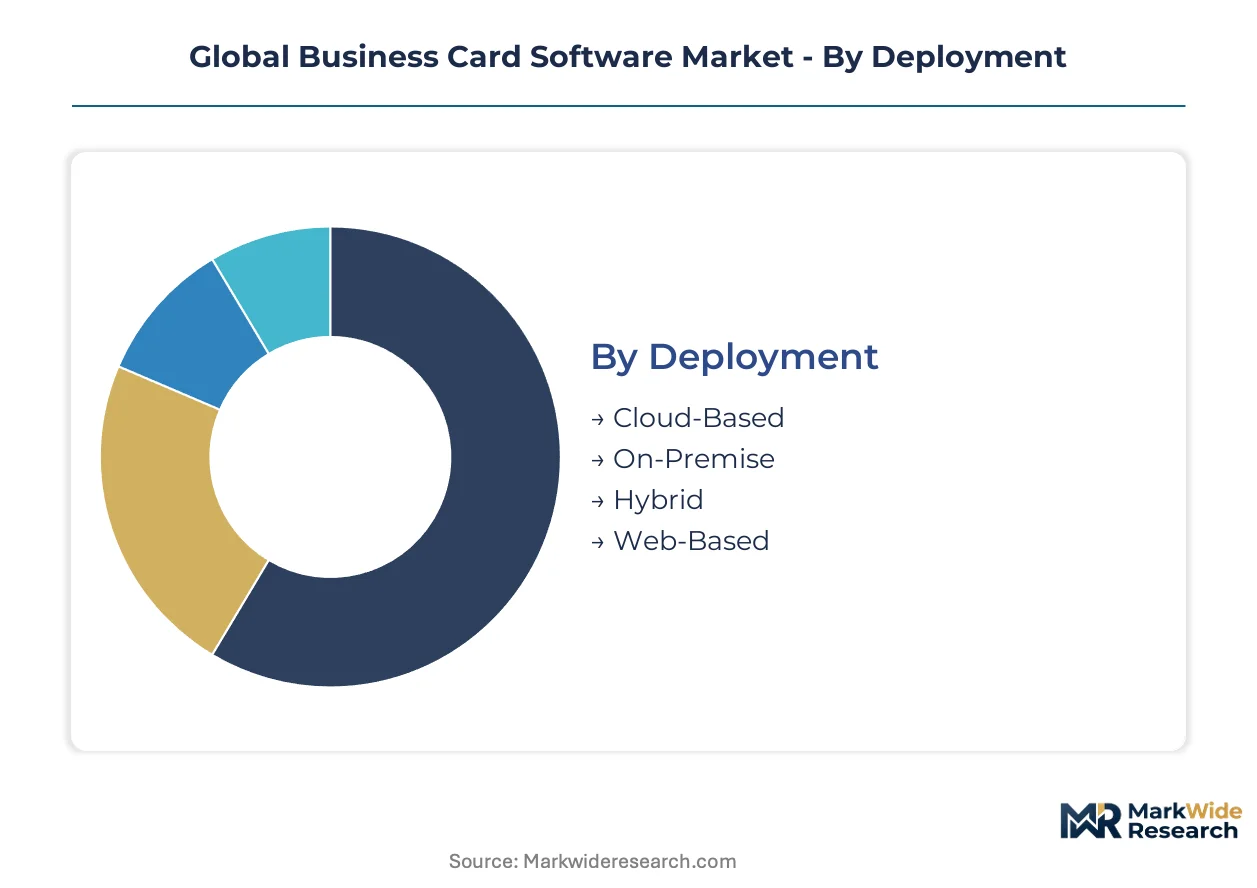
Segmentation in business card software reveals how buyer priorities diverge between cost-conscious independents and integration-heavy enterprises. Deployment architecture and solution depth determine vendor resource allocation across radically different customer lifetime value profiles.
Deployment:
Cost tier and data sovereignty requirements shape procurement decisions across buyer segments.
- Cloud-Based:Multi-tenant SaaS architectures eliminate infrastructure overhead for freelancers and micro-enterprises. Demand concentrates among United States and German independents where subscription economics trump capital expenditure constraints.
- On-Premise:Single-tenant installations with local data residency serve Japanese financial institutions and German Mittelstand manufacturers facing APPI and GDPR compliance mandates. Procurement cycles extend due to security review protocols.
- Hybrid:Split architectures route sensitive contact data through on-premise nodes while leveraging cloud analytics layers. Japanese pharmaceutical distributors and German automotive suppliers adopt this model for cross-border operational continuity.
- Web-Based:Browser-accessible platforms without native app dependencies reduce friction for occasional users. Marketing agencies in the Netherlands and United Kingdom deploy these for temporary project teams.
Cloud-Based leads on scale; Hybrid leads on momentum.
Solution:
Feature depth correlates directly with customer retention and expansion revenue potential.
- Design Tools:Template libraries and brand asset management enable rapid credential creation. Creative freelancers in France and Italy prioritize visual differentiation capabilities over backend integration depth.
- Contact Management:Centralized databases with deduplication and enrichment sustain premium pricing. Enterprise sales teams in the United States and Japan treat this as non-negotiable infrastructure.
- Integration Features:Native API connectivity with Salesforce, HubSpot, and Microsoft Dynamics transforms procurement from discretionary to mandatory. German B2B software vendors and United States SaaS companies drive expansion here.
- Analytics:Sharing frequency, geographic reach, and follow-up conversion metrics justify platform investment. Marketing agencies in the United Kingdom and Australia leverage these for client reporting.
- Customization Options:White-label configurations and bespoke workflow automation serve large consultancies. Japanese keiretsu-affiliated service providers demand extensive tailoring to existing enterprise systems.
Integration Features leads on scale; Analytics leads on momentum.
Application:
Use case specificity determines feature prioritization and pricing elasticity.
- Networking Events:Frictionless exchange mechanisms including NFC tap and QR scan dominate requirements. Trade show organizers in Germany and the United States bundle these capabilities into event technology stacks.
- Sales Enablement:CRM synchronization and pipeline attribution tracking justify departmental procurement. Field sales teams in Japan and the United States treat digital credentials as quota-carrying infrastructure.
- Digital Marketing:UTM parameter embedding and campaign-specific landing pages enable attribution. Performance marketers in the United Kingdom and Netherlands track ROI through credential distribution analytics.
- Client Management:Relationship history and interaction logging support account-based strategies. Professional services firms in Germany and Australia prioritize longitudinal contact intelligence.
- Brand Promotion:Consistent visual identity enforcement across distributed teams protects equity. Consumer brands in France and the United States mandate template lockdown for external-facing employees.
Sales Enablement leads on scale; Digital Marketing leads on momentum.
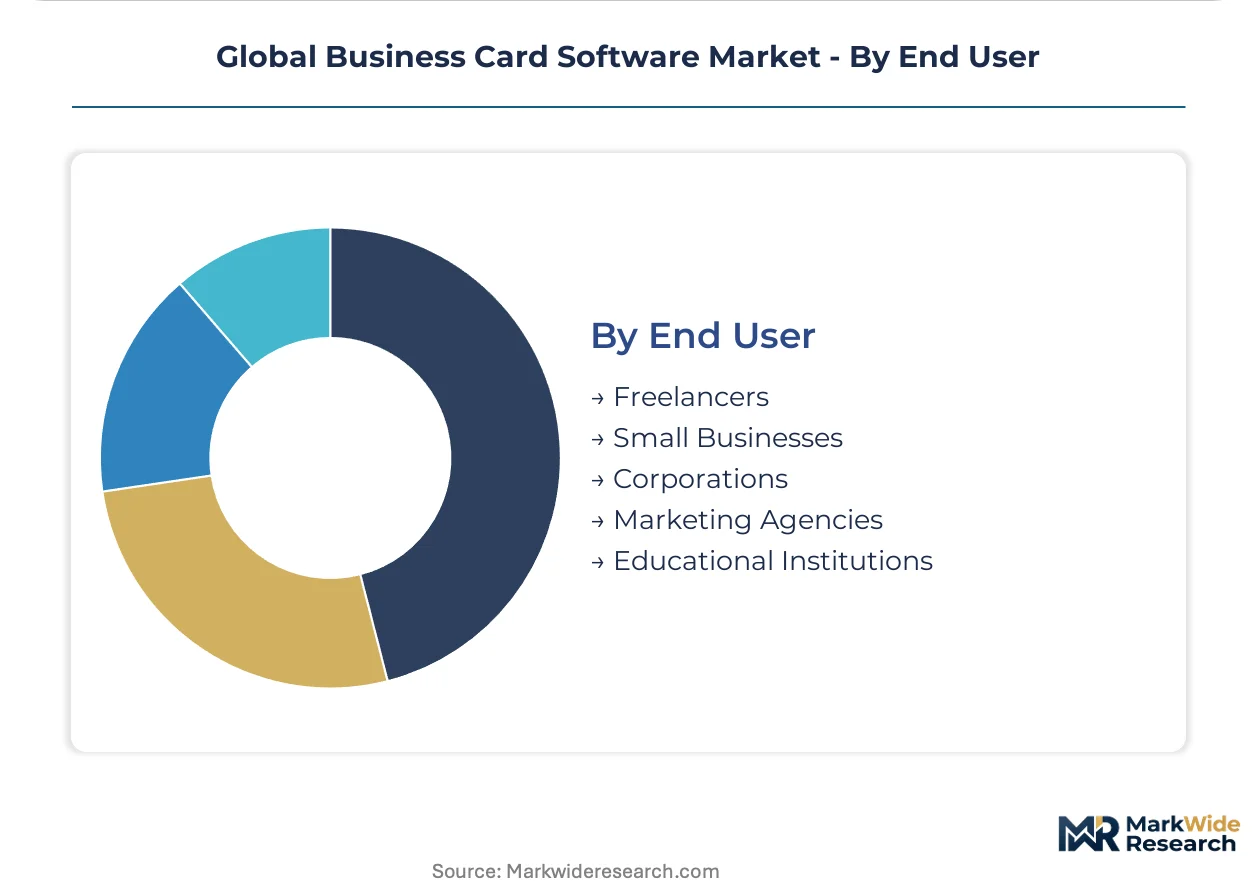
End User:
Organizational size and procurement sophistication create distinct vendor engagement models.
- Freelancers:Individual practitioners prioritize mobile-native interfaces and free-tier availability. Independent consultants in Germany and the United States drive consumption-based billing adoption.
- Small Businesses:Ten-to-fifty-employee companies seek team collaboration features without enterprise complexity. Dutch and United Kingdom agencies balance cost control with brand consistency requirements.
- Corporations:Security certification, SSO integration, and dedicated support contracts define procurement. Japanese manufacturers and United States technology firms mandate ISO 27001 compliance.
- Marketing Agencies:Multi-client management and white-label distribution require platform flexibility. Creative services firms in France and Australia manage separate credential environments per brand portfolio.
- Educational Institutions:Alumni relations and career services departments deploy credentials for networking facilitation. Universities in the United States and United Kingdom issue verified digital credentials to graduating cohorts.
Corporations leads on scale; Freelancers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise SaaS penetration outpaces German Mittelstand adoption, while Japan's regulatory mandates accelerate replacement cycles faster than voluntary migration patterns observed elsewhere.
United States
Salesforce-dependent organizations and remote-work normalized enterprises drive cloud-first procurement. HIPAA and state-level privacy laws shape data handling architectures for healthcare-adjacent deployments. Silicon Valley SaaS vendors and New York financial services clusters anchor demand concentration for API-integrated credential platforms.
Germany
Export-oriented Mittelstand manufacturers seek hybrid cloud deployments with on-premise data residency. GDPR and the EU AI Act impose consent management and audit trail requirements on contact processing workflows. Stuttgart automotive suppliers and Frankfurt financial services firms lead enterprise replacement of physical networking rituals.
Japan
Keiretsu-affiliated corporations replace traditional meishi exchange through bundled software procurement relationships. METI paperless administrative standards mandate digital credential adoption with sector-specific compliance deadlines. Tokyo financial services and Osaka pharmaceutical distributors face the steepest regulatory acceleration timelines.
United Kingdom
Marketing agencies and professional services firms prioritize analytics-enabled credential distribution for client reporting. GDPR compliance requirements intersect with post-Brexit data transfer protocols, complicating cross-border infrastructure decisions. London creative services clusters and Manchester digital agencies drive consumption-based billing adoption.
Australia
Professional services and educational institutions deploy verified digital credentials for alumni networking and career services. The country's privacy regulator enforces notification requirements on automated contact enrichment practices. Sydney consulting firms and Melbourne universities anchor demand for white-label platform configurations.
Global Business Card Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and integration depth vectors. Market structure exhibits moderate consolidation around enterprise CRM-integrated platforms, with fragmentation persisting in mobile-native and design-centric segments. Three archetypes dominate: enterprise integration specialists, mobile-first exchange platforms, and AI-powered contact enrichment providers. Strategic moves concentrate on API ecosystem partnerships and consumption-based pricing model unbundling.
Within the enterprise integration tier, Sansan anchors Japanese keiretsu procurement channels through CRM connectivity depth. HiHello occupies a position exemplifying mobile-native design prioritization for virtual networking contexts. Covve represents the AI-enrichment archetype, sustaining premium positioning against free-tier alternatives through automated contact intelligence capabilities.
| Leading Market Players |
|---|
| Sansan |
| ABBYY |
| CamCard |
| HiHello |
| HubSpot |
| CircleBack |
| Covve |
| Knowee |
| Haystack |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs cascade through subscription tiers as data residency requirements in Germany and Japan force vendors to replicate regional server capacity, pushing hybrid deployment pricing above pure SaaS alternatives while API integration complexity sustains premium tiers for enterprise buyers.
Pricing Analysis
Capacity additions in the United States and Germany are reshaping price floors for cloud-native platforms as hyperscaler competition reduces hosting overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by CRM integration depth and ISO 27001 certification status. Pricing pressure stems from freemium alternatives capturing freelancer segments. Micro-enterprises exhibit highest price sensitivity; Japanese keiretsu-affiliated corporations show lowest.
Supply Chain Analysis
Regional distribution centers in Ireland, Singapore, and Virginia anchor hub-and-spoke patterns for cloud service delivery. The software supply chain draws from semiconductor fabrication in Taiwan, data center construction in China, and specialized API development in India. Single-source vulnerability concentrates in NFC chip supply from Apple and Google controlled ecosystems. Distribution runs through direct digital channels with partner-assisted enterprise implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Japan's METI paperless mandates and Europe's GDPR enforcement create procurement acceleration that outpaces voluntary adoption curves elsewhere.
For Market Incumbents: Anchor recurring revenue through deep Salesforce and HubSpot integration moats that resist displacement by free-tier entrants. Invest in ISO 27001 certification maintenance as procurement table stakes harden across regulated industries. Expand professional services capacity to address legacy CRM integration complexity that erodes software margins.
For New Entrants and Emerging Players: API marketplace distribution channels offer lowest-friction customer acquisition against entrenched enterprise sales motions. Target German Mittelstand manufacturers with export sales teams as the most penetrable whitespace segment. Pursue consumption-based billing models to capture freelancer and project-based consultant demand.
For Investors and Strategic Acquirers: Consolidation pressure builds where API integration depth and keiretsu procurement relationships create winner-take-most dynamics. Long-term viability favors platforms with embedded workflow automation rather than design-template differentiation. Watch for ISO 27001 certification becoming mandatory procurement filter as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and HubSpot connectivity transforms from premium upsell to baseline procurement criterion. |
| Geographic Expansion | German Mittelstand manufacturers with export sales teams remain underpenetrated by mobile-native solutions. |
| Strategic Partnership | Event technology platform alliances create distribution channels as hybrid networking becomes permanent fixture. |
| Product Launch | NFC-enabled tap-to-share capabilities without recipient app installation accelerate field sales team adoption. |
| Acquisition of Specialist Firm | AI-powered contact enrichment capabilities sustain premium positioning against commoditized free-tier alternatives. |
Research Methodology
Direct dialogue with CTOs, IT procurement officers, platform engineers, and integration specialists grounds qualitative assessment in operational reality. Secondary validation draws from SEC filings, hyperscaler capex disclosures, App Annie mobile analytics, and CRM vendor partnership announcements. Bottom-up and top-down triangulation cross-checks segment-level assumptions against aggregate market sizing.
Bottom-up modeling builds from deployment architecture, organization size, vertical industry, and integration complexity dimensions across the analysis window. Top-down verification anchors against aggregate SaaS spend patterns and digital transformation budget allocations. CAGRs derive from replacement cycle acceleration in regulated industries and API adoption curves in CRM-dependent sales organizations.
Regulatory deadline delays, platform gatekeeper policy shifts, and subscription fatigue acceleration are the dominant revision risks that could compress or extend forecast trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Global IVR Software Market
Software & Services
Web Development Market
Software & Services
Global Construction Management Software Market
Software & Services
Course Authoring Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Lead Management Software Market
Software & Services
Home Design Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Global Automation Software Market
Software & Services
Global Cinema Software Market
Software & Services
Global Printing Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Global Animation Software Market
Software & Services
Global Database Software Market