
 Reporter Systems Market | 2026-2036
Reporter Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Reporter Systems Market Analytics
Platform licensing revenue is narrowing relative to perpetual software sales as subscription models displace upfront purchases across the reporter systems landscape. Thermo Fisher Scientific leverages its life sciences instrumentation installed base to cross-sell embedded reporting modules. Promega Corporation anchors its position through specialized assay-to-report workflows that reduce manual data transcription. Takara Bio competes in the Asia-Pacific research corridor with localized cloud deployment options.
Reporter systems comprise software and instrumentation platforms that capture, process, and visualize experimental or operational data through automated collation, statistical validation, and standardized output formatting for regulatory or internal decision-making. These systems integrate optical detection hardware, database architectures, and template-driven report generators to transform raw measurements into auditable documentation suitable for FDA, EMA, or institutional review submissions. Dashboard reporting and interactive reporting represent the fastest-expanding product categories as real-time visualization replaces static batch outputs. Cloud-based deployment models are displacing on-premises installations among enterprises seeking elastic compute for large-scale genomic and clinical datasets. API-based integration levels are gaining share against standalone configurations as laboratory information management systems demand seamless data pipelining.
FDA 21 CFR Part 11 and EMA GxP data integrity guidelines shape product development roadmaps by mandating electronic signatures, audit trails, and validation documentation. ISO 27001 and HIPAA frameworks govern cloud-hosted deployments handling patient-derived research data, creating compliance barriers for uncertified vendors. Stakeholders must weigh the trade-off between embedded integration depth and vendor lock-in exposure as research consortia demand interoperable, multi-platform data exchange.
Market Dynamics
Cloud-native API architectures are compressing deployment timelines for reporter systems from months to weeks, forcing incumbent vendors to restructure licensing frameworks or lose enterprise accounts to agile competitors.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature mandates for pharmaceutical quality documentation are accelerating replacement cycles for legacy paper-based reporting infrastructure.
- Optical detection hardware miniaturization:Benchtop footprint reductions are expanding addressable demand into academic core facilities with space-constrained laboratory environments.
- Germany's research funding intensity:Sustained federal investment in molecular biology consortia is sustaining procurement velocity for integrated assay-to-report platforms.
Market Restraints
- ISO 27001 certification costs:Cloud-hosted deployments handling patient-derived genomic data face six-figure compliance investments that exclude mid-tier vendors from hospital procurement pools.
- Optical sensor supply concentration:Specialized photomultiplier tube manufacturing concentrates in Japanese industrial clusters, exposing lead time volatility for detection module assembly.
- Template standardization gaps:EMA GxP formatting requirements diverge from FDA submission templates, forcing dual validation workflows that inflate implementation labor.
Strategic Opportunities
- India's CDSCO pathway acceleration:Streamlined clinical trial reporting mandates are creating first-mover advantage for cloud-deployed systems with localized data residency options.
- Real-time bioprocess monitoring:Continuous manufacturing adoption in cell therapy production is opening dedicated product lines for streaming reporter analytics.
- API-first integration:Laboratory information management system vendors are prioritizing embedded reporting modules over standalone purchases, rewarding deep partnership architectures.
Industry Challenges
- Computational biology skill scarcity:Statistical validation scripting for automated report generation outpaces available bioinformatics talent pools in contract research organizations.
- Legacy on-premises migration friction:Pharmaceutical quality assurance departments resist cloud transitions due to established paper audit trail workflows, elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reporter Systems Market |
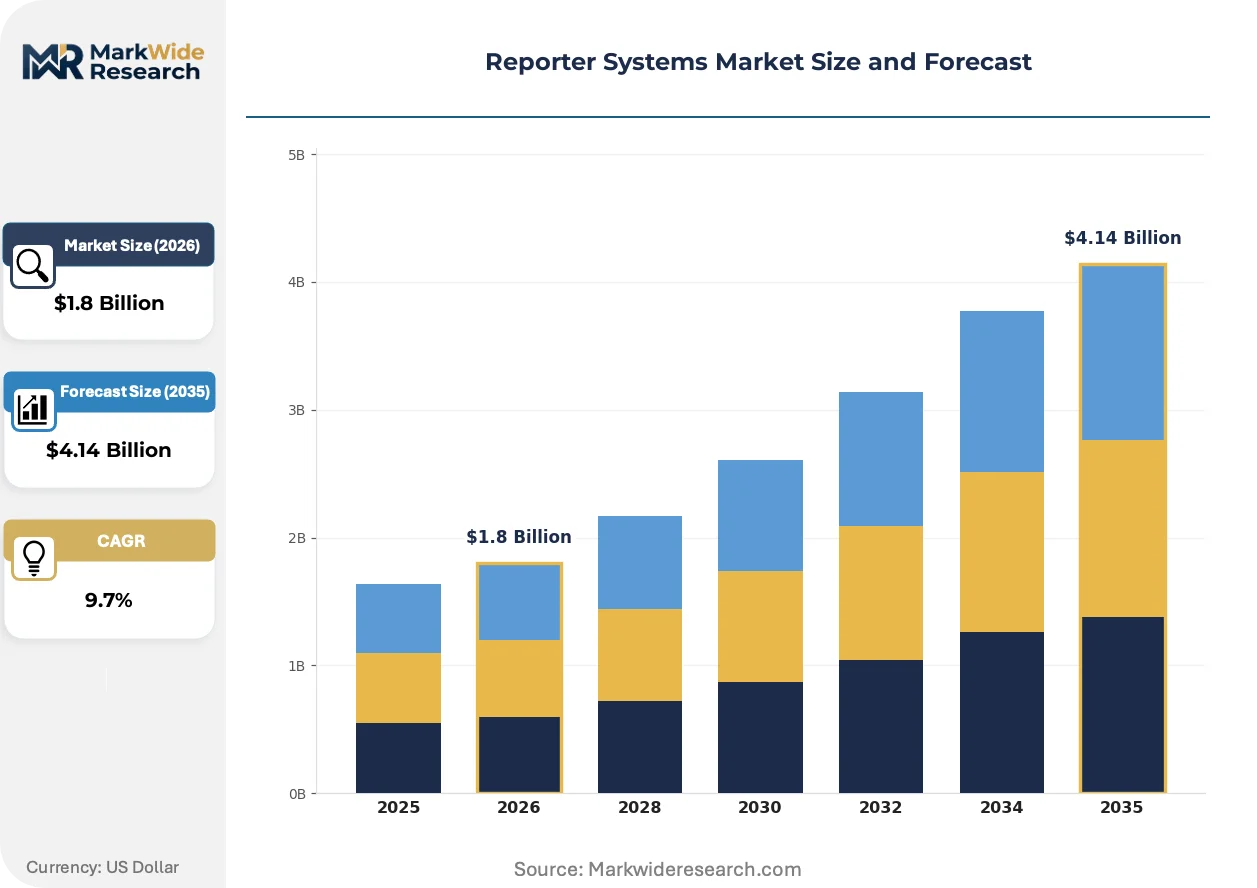
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Reporting, Manual Reporting, Dashboard Reporting, Interactive Reporting End User: Enterprises, Government Agencies, Non-Profits, Academic Institutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Tenant Integration Level: API-Based, Plugin, Standalone, Embedded |
| Companies Covered | Thermo Fisher Scientific, Promega Corporation, Takara Bio, Bio-Rad Laboratories, VectorBuilder, Addgene, Eventus Systems, FIS, Nasdaq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reporter Systems Market Evolving Landscape
Reporter system architectures are pivoting from batch-oriented static outputs toward continuous data streams, with three converging developments redefining competitive positioning across vendor portfolios.
Serverless computing architectures are collapsing total cost of ownership for genomic-scale data processing. Biotechnology enterprises with elastic compute requirements are migrating high-throughput screening workloads to consumption-priced cloud functions. This infrastructure shift is collapsing the price floor that previously protected perpetual-license incumbents.
EMA's Clinical Trial Information System (CTIS) mandate is harmonizing electronic submission formats across European member states. Pharmaceutical sponsors must consolidate previously fragmented national reporting workflows into unified portal submissions. Small-to-mid cap drug developers in Germany and France are prioritizing vendors with pre-validated CTIS connector modules.
Research consortia are unbundling after-sales validation support from core platform licenses. Academic medical centers with internal compliance teams now demand modular pricing that separates software access from professional services. This purchasing pattern is most pronounced in United States National Institutes of Health-funded institutions with established quality assurance functions.
Reporter Systems Market Segmentation
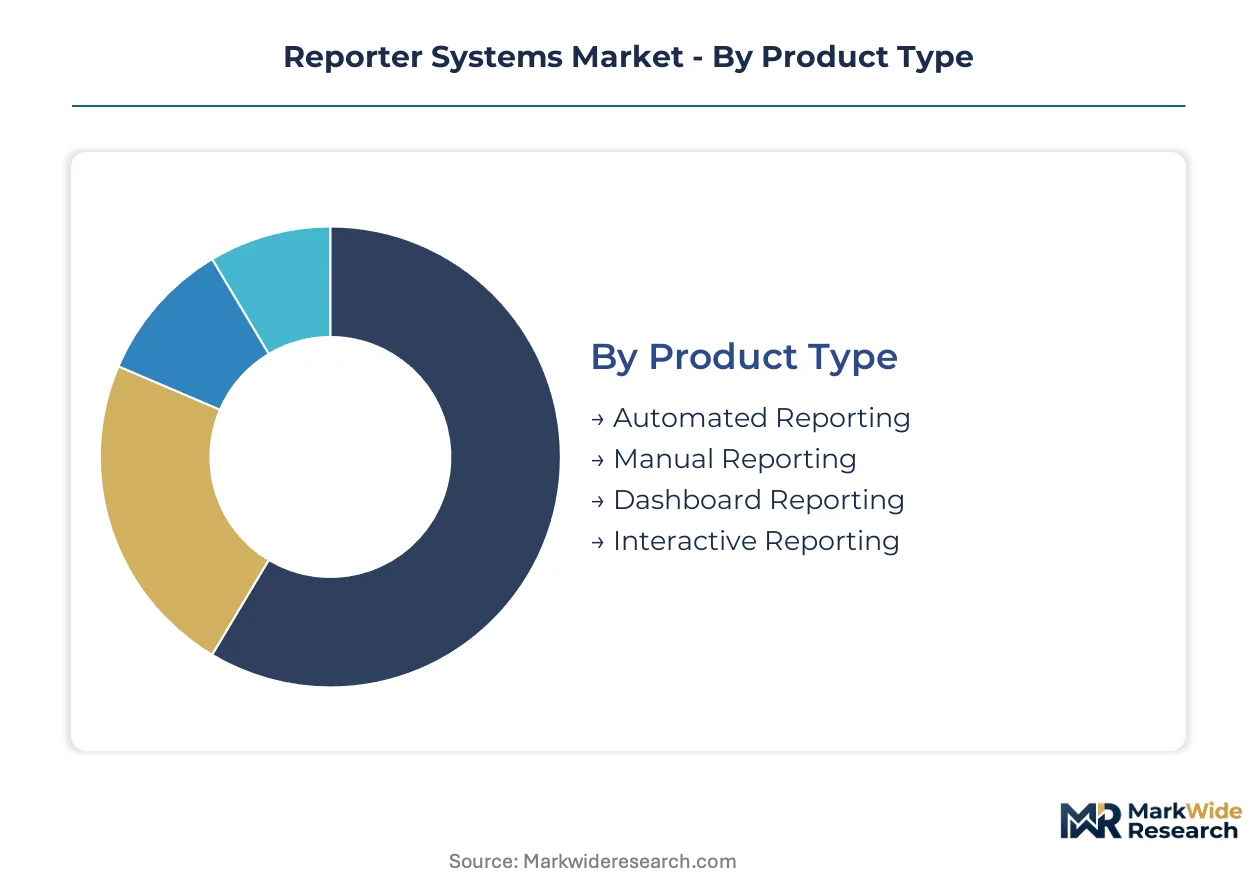
Reporter systems serve divergent workflow requirements across pharmaceutical quality assurance, academic research cores, and government compliance offices. Segmentation reveals how deployment architecture and integration depth separate mature enterprise installations from emerging cloud-native configurations.
Product Type:
Mature batch-oriented formats coexist with emerging real-time visualization platforms as regulatory acceptance timelines diverge.
- Automated Reporting:Rule-driven engines execute FDA 21 CFR Part 11 compliant electronic signatures and audit trails without manual intervention. Pharmaceutical quality departments in the United States and Germany prioritize these systems for IND and NDA submission packages where validation documentation is mandatory.
- Dashboard Reporting:Real-time visualization layers aggregate multi-instrument data streams into configurable widgets for bioprocess monitoring. Cell therapy manufacturers in Japan are adopting these interfaces for continuous manufacturing workflows where batch release decisions require immediate access to trending parameters.
- Manual Reporting:Template-guided data entry systems with structured formatting for institutional review boards.
- Interactive Reporting:Drill-down capable interfaces enabling ad-hoc statistical exploration of genomic datasets.
Automated Reporting handles the majority of throughput; Dashboard Reporting is the fastest mover on share.
End User:
Cost tier separation distinguishes capital-intensive enterprise deployments from grant-funded academic installations with constrained professional services budgets.
- Enterprises:Multi-site pharmaceutical sponsors require validated, audit-ready platforms with 24/7 support SLAs and disaster recovery guarantees. These buyers concentrate procurement authority in quality assurance departments with established vendor qualification procedures.
- Academic Institutions:Core facilities and principal investigator laboratories prioritize modular pricing and open API access for custom workflow integration. NIH-funded centers in the United States increasingly unbundle validation support from software licenses.
- Government Agencies:National health institutes and regulatory bodies with mandated transparency requirements.
- Non-Profits:Disease foundation research consortia with collaborative data sharing mandates.
Enterprises dominate absolute spending; Academic Institutions are expanding most quickly as cloud pricing collapses entry barriers.
Deployment Model:
Volume concentration in legacy on-premises estates is giving way to elastic compute demand from genomic-scale screening operations.
- Cloud-Based:Serverless architectures enable consumption-priced processing of terabyte-scale sequencing outputs without capital infrastructure commitment. ISO 27001 certification requirements restrict viable vendors to those with six-figure compliance investments.
- Hybrid:Sensitive patient-derived data remains on-premises while compute-intensive analytics burst to cloud infrastructure. German molecular biology consortia favor this architecture for GDPR-compliant genomic research.
- On-Premises:Perpetual-license installations with dedicated hardware for validated GxP environments.
- Multi-Tenant:Shared infrastructure with logical isolation for contract research organizations serving multiple sponsors.
Cloud-Based deployments are gaining share fastest; On-Premises retains the largest installed base.
Integration Level:
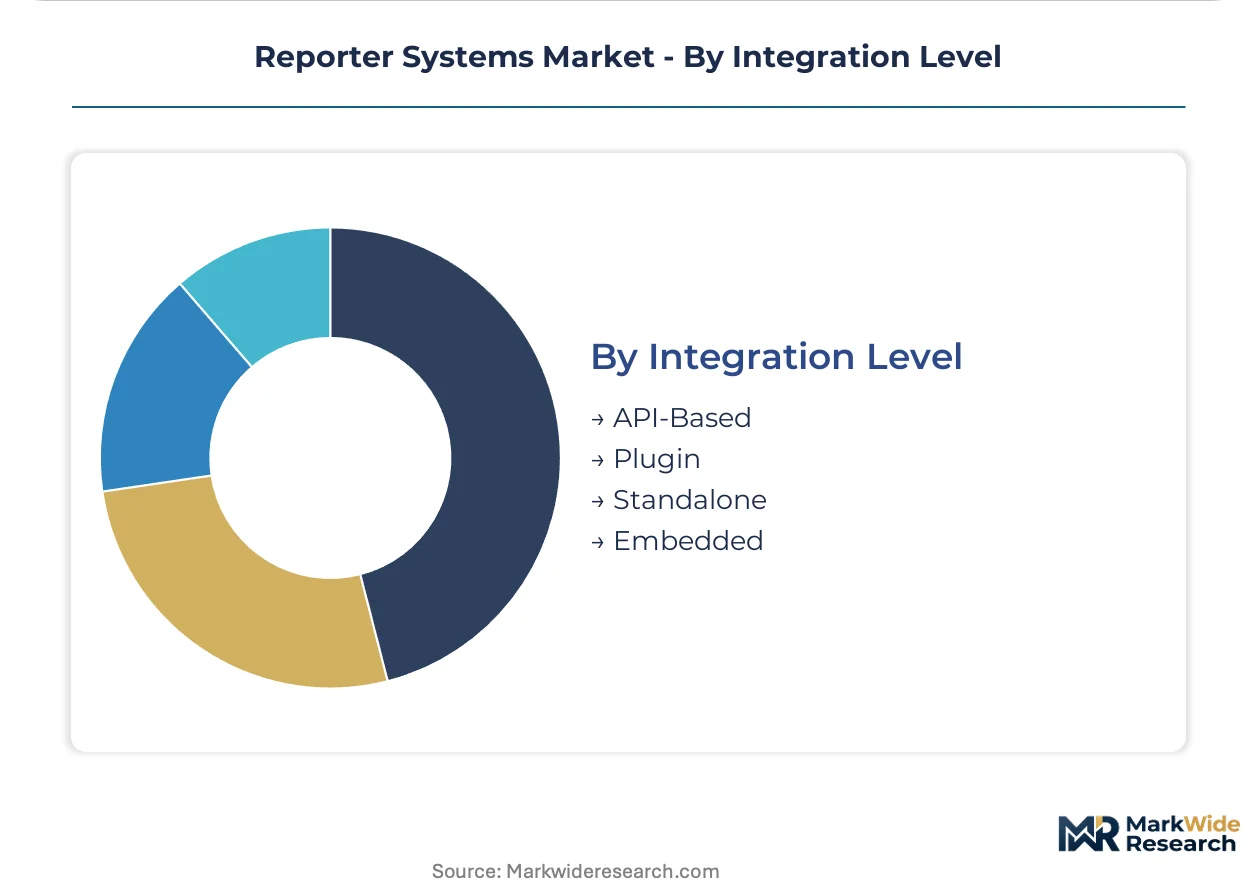
Supply concentration among laboratory information management system vendors is forcing reporter system suppliers into partnership architectures.
- API-Based:REST and GraphQL interfaces enable seamless data pipelining between instruments, LIMS, and regulatory submission portals. EMA CTIS harmonization is accelerating demand for pre-validated connector modules.
- Embedded:Reporting functionality compiled directly into instrument control software or LIMS platforms. Thermo Fisher Scientific leverages this approach across its life sciences instrumentation portfolio.
- Plugin:Extension modules for existing software ecosystems with limited customization scope.
- Standalone:Disconnected platforms requiring manual data import and export procedures.
API-Based integration is climbing the fastest; Embedded modules capture the deepest workflow penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized photomultiplier tube manufacturing clusters in Japan create lead time volatility that ripples through detection module assembly worldwide. Cloud migration patterns diverge sharply between jurisdictions with stringent data residency mandates and those with elastic compute subsidies.
United States
FDA 21 CFR Part 11 electronic signature mandates drive replacement cycles for legacy paper-based reporting infrastructure across pharmaceutical quality departments. NIH-funded academic medical centers in Boston and San Francisco increasingly unbundle validation support from software licenses. The National Institutes of Health headquarters in Bethesda anchors procurement velocity for integrated assay-to-report platforms.
Germany
Sustained federal investment in molecular biology consortia sustains procurement velocity for integrated platforms among research-intensive institutions. EMA GxP data integrity guidelines and GDPR compliance requirements shape hybrid deployment architectures for genomic research. The Heidelberg and Munich biotech clusters favor on-premises sensitive data storage with cloud bursting for compute-intensive analytics.
Japan
Cell therapy manufacturers in Kanto and Kansai regions adopt dashboard reporting interfaces for continuous manufacturing workflows requiring immediate batch release decisions. PMDA regulatory frameworks and METI industrial policy accelerate optical detection hardware miniaturization for space-constrained academic core facilities. Tokyo-Yokohama corridor concentrates demand for benchtop footprint reductions.
India
CDSCO pathway acceleration for streamlined clinical trial reporting creates first-mover advantage for cloud-deployed systems with localized data residency options. Bangalore and Hyderabad biotech parks drive demand for API-first architectures that compress deployment timelines from months to weeks. Contract research organizations in these clusters prioritize multi-tenant shared infrastructure with logical isolation.
United Kingdom
Research consortia in Cambridge and Oxford unbundle after-sales validation support from core platform licenses, demanding modular pricing that separates software access from professional services. MHRA alignment with EMA CTIS harmonization pressures vendors to consolidate fragmented national reporting workflows. London-based pharmaceutical sponsors prioritize pre-validated connector modules for unified portal submissions.
Reporter Systems Market Competitive Landscape
Life sciences instrumentation conglomerates and specialized assay workflow developers split the market into distinct competitive spheres. Consolidation pressure intensifies as cloud-native entrants compress deployment timelines and collapse price floors that previously protected perpetual-license incumbents. Three archetypes dominate: diversified conglomerates leveraging installed base cross-sell, specialists anchoring position through assay-to-report integration, and regional cloud deployment optimizers. Incumbent restructuring of licensing frameworks and agile partnership architectures with laboratory information management system vendors represent the dominant competitive moves.
Within the instrumentation conglomerate tier, Thermo Fisher Scientific exemplifies cross-sell leverage across life sciences portfolios. Among specialized workflow developers, Promega Corporation occupies a position defined by assay-to-report integration depth. Takara Bio represents the regional cloud optimization archetype with Asia-Pacific deployment focus. These three anchors illustrate how vendor strategies diverge across integration depth, geographic concentration, and licensing model innovation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Promega Corporation |
| Takara Bio |
| Bio-Rad Laboratories |
| VectorBuilder |
| Addgene |
| Eventus Systems |
| FIS |
| Nasdaq |
| Others |
Value Network & Pricing Analysis
Hamamatsu City anchors specialized photomultiplier tube manufacturing for optical detection modules, concentrating capacity that downstream reporter system vendors cannot easily replicate. This geographic clustering of precision photonics manufacturing translates into asymmetric pricing power for detection hardware suppliers, while cloud-native software competitors collapse subscription price floors through serverless infrastructure economics.
Pricing Analysis
After-sales validation support contracts generate lifetime value multiples exceeding initial platform licenses as research consortia unbundle professional services from software access. Three-tier pricing structure across enterprise-grade validated platforms, mid-tier academic licenses, and entry-level cloud subscriptions captures divergent buyer budgets. Pricing pressure stems from serverless computing collapsing infrastructure cost floors for genomic-scale processing. Academic institutions with NIH funding exhibit highest price sensitivity; pharmaceutical quality departments with FDA submission mandates show lowest sensitivity due to compliance risk aversion.
Supply Chain Analysis
Upstream feedstock for optical detection hardware concentrates in Japanese industrial clusters producing photomultiplier tubes and precision optical sensors. Specialized semiconductor fabrication for signal processing chips draws from Taiwan and South Korea. Single-source vulnerability pervades photomultiplier tube supply, with Hamamatsu Photonics holding dominant manufacturing share. Distribution runs through life sciences instrumentation distributors with embedded service capabilities, plus direct enterprise sales for validated GxP deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioinformatics talent scarcity for statistical validation scripting constrains automated report generation deployment across contract research organizations. This capability gap separates vendors with in-house computational biology teams from those dependent on external talent markets.
For Market Incumbents:Pre-empt cloud-native entrants by restructuring perpetual-license frameworks into consumption-priced serverless offerings before agile competitors capture enterprise accounts. Deepen API partnership architectures with laboratory information management system vendors to secure embedded integration slots. ISO 27001 certification investment represents the critical defensive lever for hospital procurement pool access.
For New Entrants and Emerging Players:Establish a beachhead in India's CDSCO-accelerated clinical trial reporting segment where localized data residency requirements disadvantage global incumbents. Target academic core facilities in United States NIH-funded institutions with modular pricing that separates validation support from software licenses. Lead with API-first deployment architectures that compress implementation timelines from months to weeks.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified life sciences conglomerates with under-optimized reporter system modules buried within broader instrumentation portfolios. Long-term viability hinges on cloud-native architecture migration completion and regulatory validation documentation depth. Watch EMA CTIS harmonization implementation velocity as inflection indicator for pre-validated connector module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Architecture | REST and GraphQL interfaces enable seamless EMA CTIS portal integration for pharmaceutical sponsors. |
| ISO 27001 Certification Investment | Six-figure compliance expenditure unlocks hospital procurement pools handling patient-derived genomic data. |
| Serverless Infrastructure Migration | Consumption-priced cloud functions collapse total cost of ownership for terabyte-scale sequencing workloads. |
| Assay-to-Report Workflow Integration | Specialized embedded modules reduce manual data transcription errors in high-throughput screening operations. |
| Localized Data Residency Deployment | India-specific cloud instances satisfy CDSCO mandates for clinical trial reporting data sovereignty requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with laboratory information management system vendors, pharmaceutical quality assurance directors, academic core facility managers, and regulatory affairs specialists; plus secondary validation against FDA 21 CFR Part 11 guidance documents, EMA CTIS technical specifications, ISO 27001 certification registries, and NIH funding disbursement records. Bottom-up instrumentation shipment tracking and top-down enterprise IT spending estimates were triangulated against cloud infrastructure provider revenue disclosures.
Forecast inputs across the analysis window incorporated deployment model migration curves, regulatory mandate implementation timelines, and genomic data volume growth trajectories. Segmentation dimensions spanned product type, end user archetype, deployment architecture, and integration complexity level. CAGRs were derived from elasticity-adjusted adoption curves cross-referenced against historical replacement cycle data for validated GxP systems.
Stress conditions across cloud infrastructure pricing volatility, photomultiplier tube supply disruption scenarios, and bioinformatics salary inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization velocity and research funding continuity. Cross-checking against vendor-reported backlog figures and academic procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
E-Clinical Solution Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Global Digital Signage Software Market
Software & Services
Spend Analysis Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Lab Automation Software Market
Software & Services
Email Marketing Software Market
Software & Services
Oracle Services Market
Software & Services
Test Automation Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Saas-Based SCM Market
Software & Services
Inventory Management Software Market
Software & Services
Website Translation Software Market
Software & Services
Bankruptcy Software Market